
 Radiation-Induced Fibrosis Treatment Market | 2026-2036
Radiation-Induced Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation-Induced Fibrosis Treatment Market Analytics
Aftermarket service revenue for long-term patient monitoring is tilting toward integrated care platforms that track fibrosis progression post-radiation. Merck KGaA leverages its oncology diagnostics infrastructure to sustain recurring engagement with treatment centers. Bristol-Myers Squibb anchors its position through immunology R&D pipelines that address fibrotic complications. Galecto, Inc. specializes in galectin-3 inhibitor development, competing on mechanism-of-action differentiation against broader anti-fibrotic approaches.
Radiation-induced fibrosis treatment encompasses pharmacological, mechanical, and biological interventions that counteract collagen deposition and tissue stiffening following ionizing radiation exposure, typically involving TGF-beta pathway modulation, pentoxifylline regimens, or hyperbaric oxygen protocols with pressure specifications of 2.0 to 2.5 atmospheres absolute. The primary purpose is restoring functional tissue elasticity and preventing irreversible organ dysfunction in cancer survivors. Medications dominate current revenue as oral and intravenous delivery models capture hospital formulary placement, while devices remain a smaller margin pool constrained by reimbursement variability. Therapies applied through rehabilitation centers represent the fastest-growing channel as post-radiation survivorship protocols expand beyond acute oncology settings.
FDA oversees clinical trial endpoints for fibrosis-modifying drugs through its Division of Oncology Products, while EMA's Committee for Medicinal Products for Human Use evaluates conditional marketing authorizations for orphan fibrosis indications. Both frameworks elevate evidence standards for histological improvement, directly shaping which developers secure market access. The EU AI Act introduces algorithmic scrutiny for diagnostic tools that quantify fibrosis severity from imaging data. Stakeholders must monitor how payer evidence requirements evolve for combination regimens that pair anti-fibrotic medications with radiation sensitizers.
Market Dynamics
Survivorship program expansion across major hospital systems is restructuring procurement priorities, elevating long-term fibrosis management from adjuvant care to core oncology service lines. This shift compresses vendor selection cycles and rewards platforms that integrate diagnostic monitoring with therapeutic delivery.
Growth Catalysts
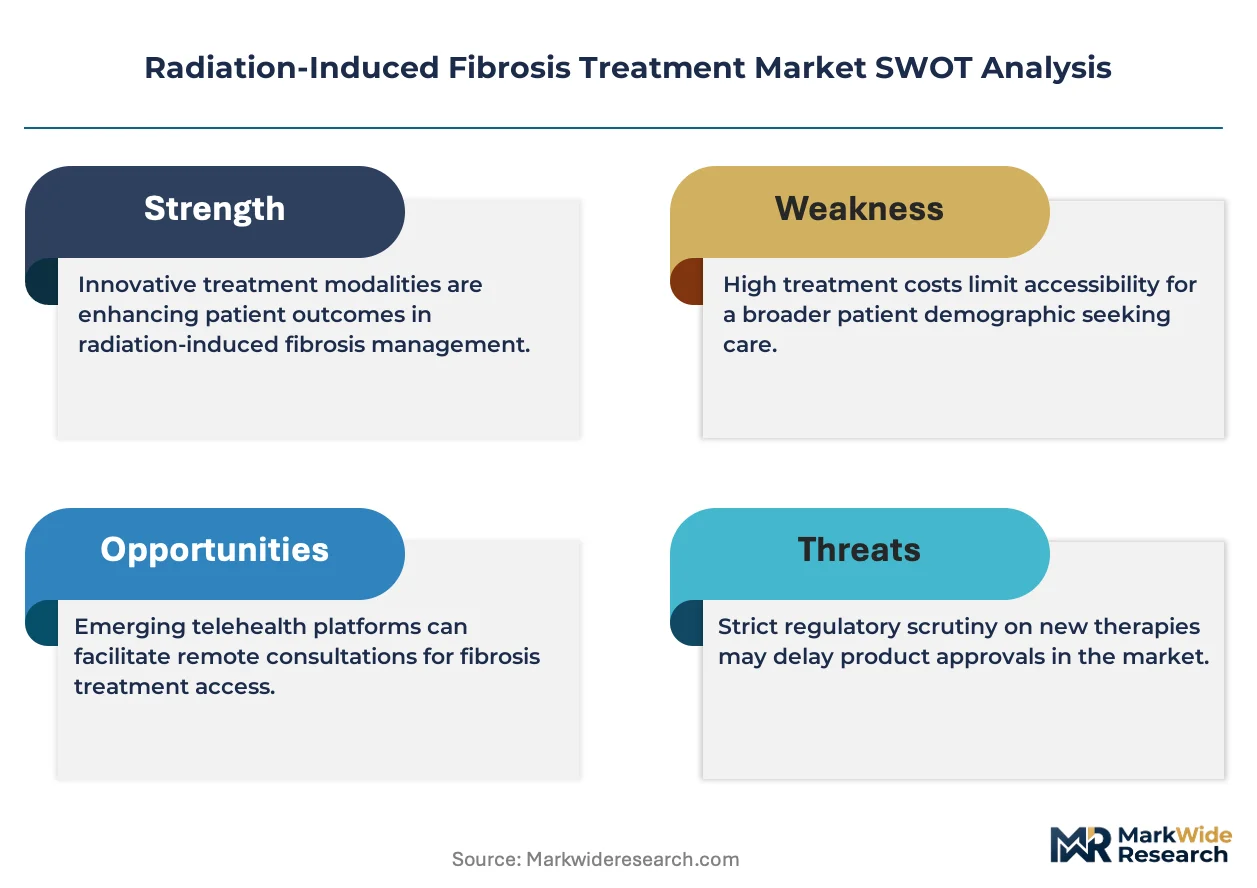
- FDA Division of Oncology Products guidance:Streamlined endpoints for fibrosis-modifying drugs accelerate trial completion timelines. Developers gain clearer pathways to conditional approval.
- Hyperbaric oxygen protocols:Rehabilitation centers in the United States, Germany, and Japan are embedding 2.0-2.5 ATA pressure specifications into standard post-radiation care bundles.
- TGF-beta pathway modulation:Mechanism-specific drug candidates attract dedicated funding from oncology-focused biopharma investment arms.
Market Restraints
- Reimbursement variability for device-based interventions:Hyperbaric oxygen chambers face inconsistent CMS coverage determinations across US hospital networks, limiting capital deployment.
- Histological evidence requirements:EMA Committee for Medicinal Products for Human Use demands biopsy-confirmed improvement endpoints that extend Phase III durations.
- Oral pentoxifylline substitution:Generic availability of established anti-fibrotic regimens caps pricing power for novel entrants in hospital formularies.
Strategic Opportunities
- Algorithmic diagnostic tools:The EU AI Act creates first-mover advantage for imaging quantification platforms that secure conformity assessment before 2026 enforcement deadlines.
- Rehabilitation channel expansion:Outpatient physical therapy networks in Japan represent underpenetrated points of care for mechanical intervention delivery.
- Galectin-3 inhibitor convergence:Combination regimens pairing mechanism-differentiated biologics with radiation sensitizers open new trial design categories.
Industry Challenges
- Fibrosis quantification standardization:Lack of harmonized imaging biomarkers between FDA and EMA creates dual-track development burdens for diagnostic-therapeutic bundles.
- Specialized radiobiology talent:Scarce clinical investigators with combined radiation oncology and fibrosis pathology expertise constrain site activation for pivotal trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation-Induced Fibrosis Treatment Market |
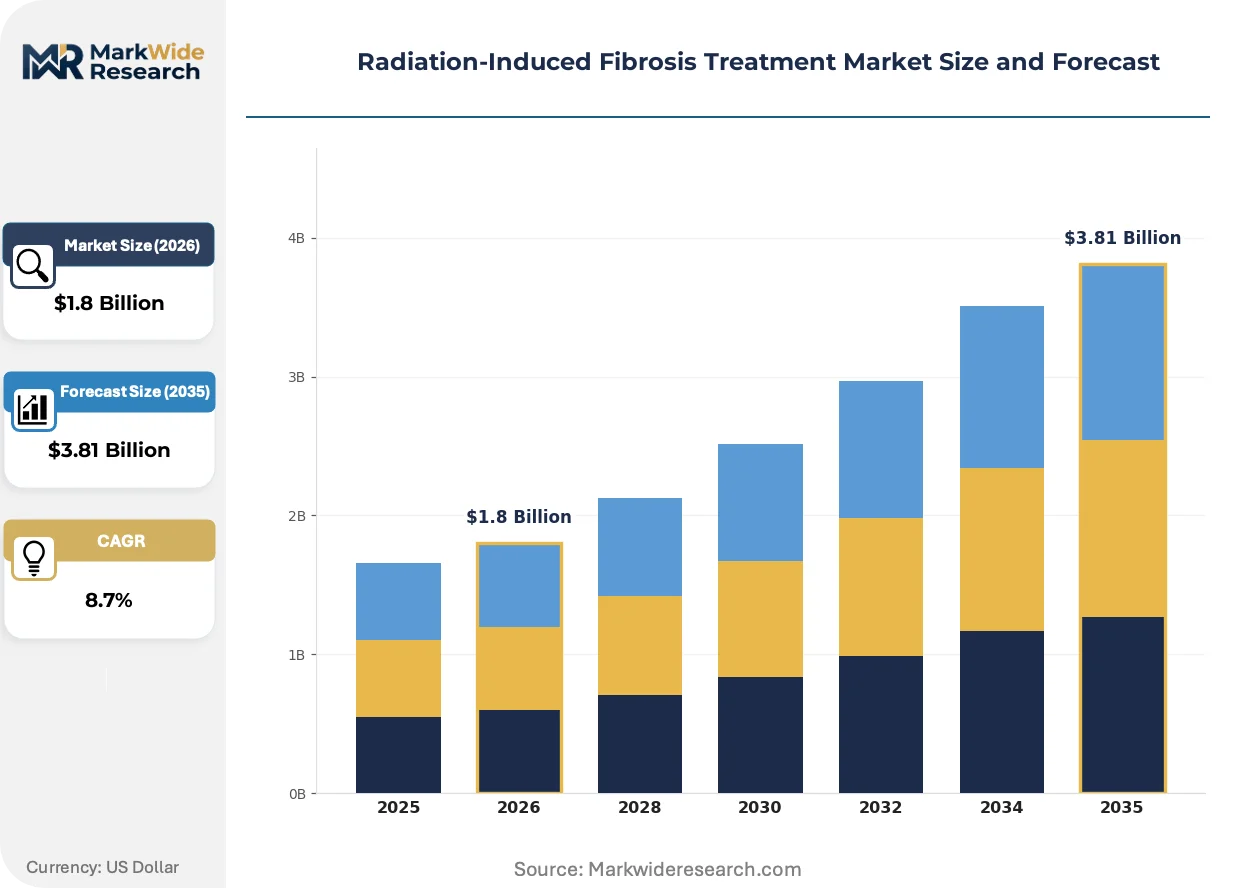
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
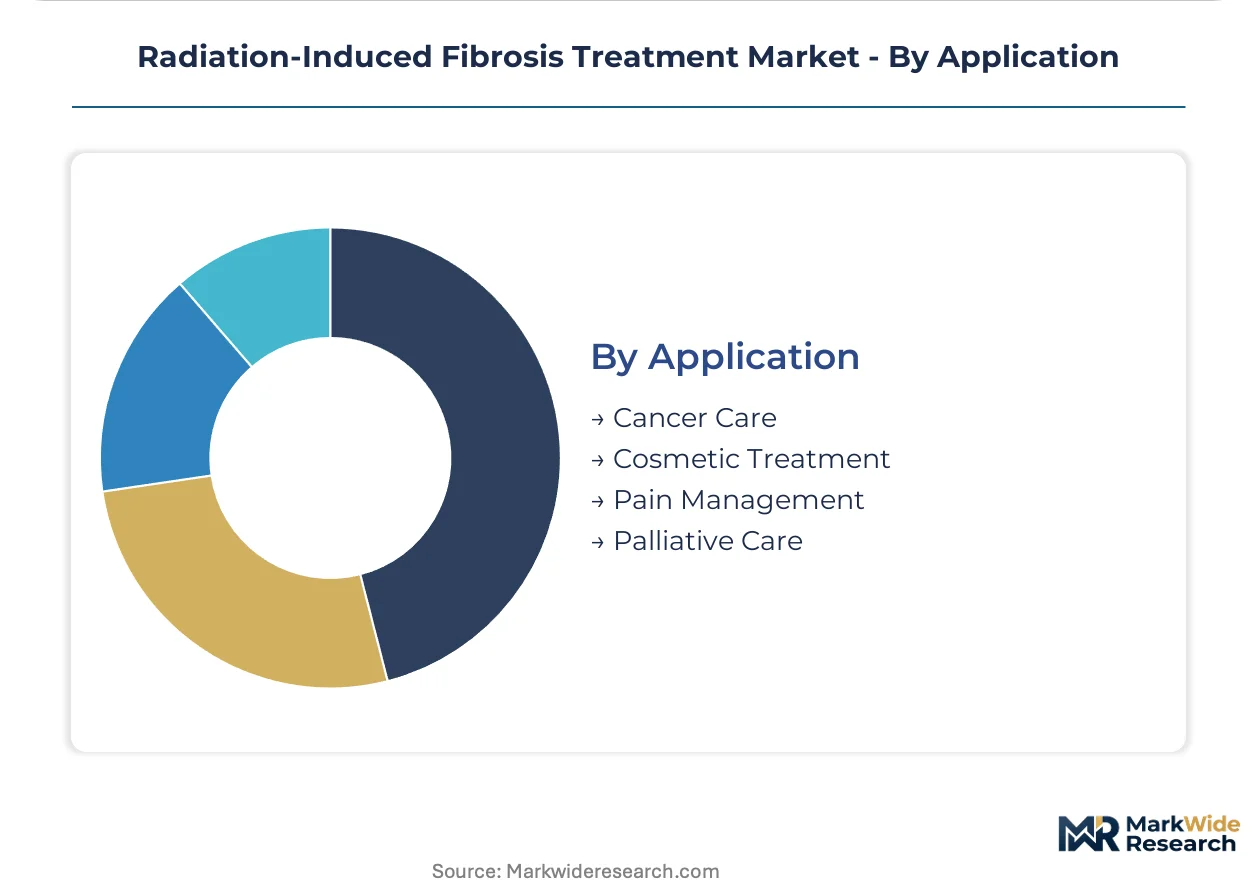
| Segmentation | Product Type: Medications, Devices, Therapies, Supplements Delivery Model: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Cancer Care, Cosmetic Treatment, Pain Management, Palliative Care |
| Companies Covered | Merck KGaA, Sanofi S.A., Bristol-Myers Squibb, Galecto, Inc., Trevi Therapeutics, Inc., Boehringer Ingelheim International GmbH, AbbVie Inc., Gilead Sciences, Inc., Redx Pharma Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation-Induced Fibrosis Treatment Market Evolving Landscape
Mechanism-driven drug development is fragmenting the competitive landscape as developers abandon broad anti-fibrotic claims in favor of pathway-specific positioning. This specialization demands new clinical evidence architectures and reshapes how treatment centers evaluate therapeutic options.
Galectin-3 inhibitor technology is hybridizing diagnostic and therapeutic functions through companion biomarker strategies that identify responsive patient subsets. Academic medical centers in the United States are piloting these integrated platforms for breast cancer radiation survivors. The approach compresses traditional silos between pathology and pharmacy decision-making.
EMA's conditional marketing authorization framework for orphan fibrosis indications is elevating histological endpoints above surrogate markers in European trial protocols. Sponsors must now power studies for biopsy-confirmed collagen reduction rather than imaging-based stiffness measures. German reference pricing authorities are incorporating these stricter evidence standards into hospital reimbursement calculations.
Aftermarket service unbundling is separating long-term monitoring contracts from initial therapy procurement in United States cancer centers. Third-party survivorship platforms are displacing bundled vendor relationships that historically tied device sales to multi-year maintenance agreements. This pattern concentrates in academic hospital systems with dedicated late-effects clinics.
Radiation-Induced Fibrosis Treatment Market Segmentation
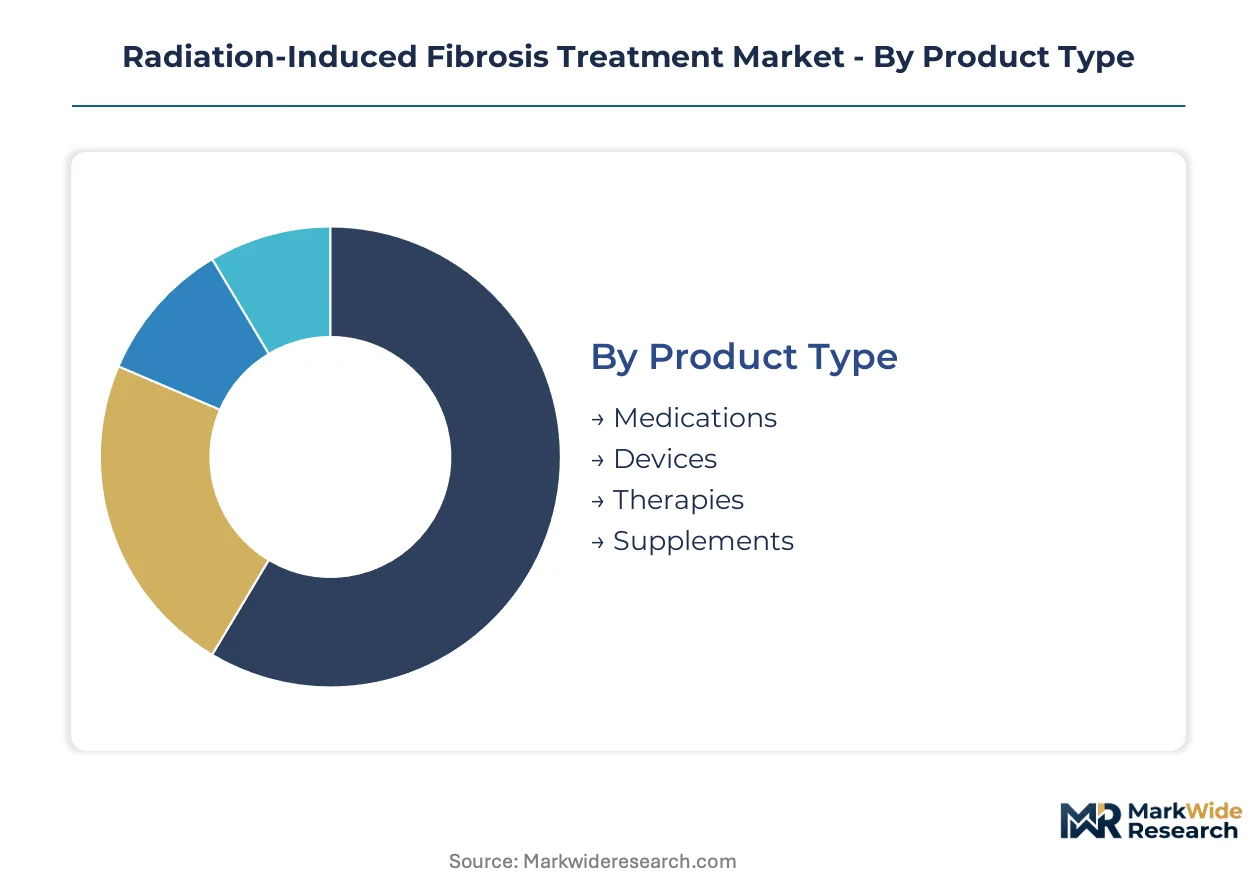
Segmentation in radiation-induced fibrosis treatment reveals distinct procurement patterns across clinical settings. Hospital formularies prioritize pharmacological solutions while rehabilitation networks drive mechanical intervention demand. Understanding these divides shapes vendor positioning and channel strategy.
Product Type:
The use-case spectrum spans acute intervention through chronic management, with each modality carrying different reimbursement profiles and clinical evidence requirements.
- Medications:Oral and intravenous formulations targeting TGF-beta pathway modulation and collagen deposition. Hospital oncology departments in the United States and Germany dominate procurement, driven by FDA Division of Oncology Products guidance streamlining trial endpoints for fibrosis-modifying drugs.
- Devices:Hyperbaric oxygen chambers operating at 2.0-2.5 atmospheres absolute for tissue oxygenation protocols. Rehabilitation centers in Japan and Germany embed these into post-radiation care bundles, though CMS coverage variability constrains US capital deployment.
- Therapies:Physical rehabilitation protocols combining manual tissue mobilization with pressure-based interventions. Outpatient networks in major US hospital systems are expanding dedicated late-effects clinics.
- Supplements:Nutritional adjuncts supporting collagen metabolism and tissue repair. Home care channels in Japan show rising patient-directed procurement outside formal reimbursement pathways.
The dominant share belongs to Medications, while Devices is closing the gap fastest as rehabilitation protocols standardize across major markets.
Delivery Model:
Cost tier differentiation separates premium intravenous hospital administration from economical oral self-management, with reimbursement tiers reinforcing clinical decision pathways.
- Oral:Pentoxifylline and emerging galectin-3 inhibitors in tablet formulation. Generic availability caps pricing power, though mechanism-differentiated candidates command formulary placement in academic medical centers.
- Injectable:Subcutaneous biologics requiring cold-chain logistics. German reference pricing authorities incorporate EMA histological endpoint requirements into hospital reimbursement calculations.
- Topical:Localized application for superficial fibrosis following breast or head-neck radiation. Cosmetic treatment applications in Japan drive demand outside traditional oncology reimbursement.
- Intravenous:Hospital-administered agents with intensive monitoring protocols. United States cancer centers concentrate procurement through integrated pharmacy and diagnostic platforms.
Oral formulations capture volume leadership, yet Intravenous delivery is expanding most quickly as combination regimens with radiation sensitizers enter clinical pipelines.
End User:
Customer type fragmentation reflects the transition from acute oncology care to long-term survivorship management, with procurement authority shifting across institutional boundaries.
- Hospitals:Academic medical centers with dedicated radiation oncology and late-effects clinics. Survivorship program expansion across major US hospital systems is restructuring vendor selection cycles toward integrated diagnostic-therapeutic bundles.
- Clinics:Community oncology practices managing stable patients post-radiation. EMA conditional marketing authorization frameworks shape which mechanism-specific agents secure European clinic formulary access.
- Home Care:Patient-directed management of chronic fibrosis symptoms. Japan's aging population drives demand for remote monitoring integration with oral therapy adherence.
- Rehabilitation Centers:Physical therapy networks specializing in post-radiation functional restoration. German and Japanese outpatient rehabilitation protocols are embedding hyperbaric oxygen specifications into standard care bundles.
Hospitals retain the dominant procurement position, though Rehabilitation Centers are gaining share fastest as survivorship care migrates beyond acute oncology settings.
Application:
Application scope determines regulatory pathway complexity, with oncology-linked indications accessing streamlined approval frameworks unavailable to cosmetic or pain-focused claims.
- Cancer Care:Fibrosis prevention and reversal in radiation-treated malignancies. FDA Division of Oncology Products oversees endpoints, while EMA Committee for Medicinal Products for Human Use demands biopsy-confirmed improvement standards.
- Cosmetic Treatment:Aesthetic restoration following radiation-induced tissue changes. Japan's cosmetic clinic networks operate outside oncology reimbursement, creating direct-pay market dynamics.
- Pain Management:Symptomatic relief from fibrotic tissue stiffness and nerve compression. United States pain clinics face CMS coverage variability for device-based interventions.
- Palliative Care:Comfort-focused approaches for advanced fibrosis with organ dysfunction. Hospice networks in Germany integrate mechanical interventions into end-of-life care protocols.
Cancer Care commands the dominant application share, while Cosmetic Treatment is climbing the fastest as patient-directed aesthetic restoration demand expands in Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan demonstrate the lowest price elasticity as aging demographics drive patient-directed procurement outside formal reimbursement, while German reference pricing authorities impose the tightest cost controls on hospital formulary placement.
United States
Academic medical centers in Boston and Houston anchor demand for integrated diagnostic-therapeutic bundles as survivorship programs expand. FDA Division of Oncology Products streamlines trial endpoints for fibrosis-modifying drugs, accelerating developer access to conditional approval pathways. The MD Anderson and Memorial Sloan Kettering networks pilot galectin-3 inhibitor companion biomarker strategies for breast cancer radiation survivors.
Germany
Reference pricing authorities incorporate EMA histological endpoint requirements into hospital reimbursement calculations, compressing margins for novel entrants. The Committee for Medicinal Products for Human Use demands biopsy-confirmed collagen reduction standards that extend Phase III durations. Munich and Heidelberg radiation oncology clusters embed hyperbaric oxygen protocols at 2.0-2.5 ATA specifications into post-radiation care bundles.
Japan
Aging population dynamics drive home care channel expansion for oral therapy adherence and remote monitoring integration. PMDA oversight of combination regimens shapes trial design for agents paired with radiation sensitizers. Tokyo and Osaka rehabilitation networks represent underpenetrated points of care for mechanical intervention delivery outside acute oncology settings.
United Kingdom
NHS England cancer strategy documents elevate late-effects clinics to core service line status, restructuring procurement toward long-term monitoring contracts. MHRA alignment with EMA conditional marketing authorization frameworks shapes which mechanism-specific agents secure formulary access. The Manchester and London academic hospital systems unbundle aftermarket services from initial therapy procurement.
Switzerland
Swissmedic evaluation of orphan fibrosis indications attracts developers seeking premium pricing corridors outside EU reference pricing. Basel and Zurich pharmaceutical clusters concentrate radiobiology talent for pivotal trial site activation. Private clinic networks in Geneva operate direct-pay cosmetic restoration markets for radiation-induced tissue changes.
Radiation-Induced Fibrosis Treatment Market Competitive Landscape
Capability concentration sits with mid-cap biopharma developers possessing combined radiation oncology and fibrosis pathology expertise; scale advantage sits with diversified pharmaceutical conglomerates leveraging existing oncology infrastructure for recurring hospital engagement. The competitive structure fragments across mechanism-specific positioning rather than consolidated therapeutic categories. Three archetypes dominate: diversified pharmaceutical incumbents with immunology R&D pipelines, galectin-3 inhibitor specialists competing on pathway differentiation, and integrated care platform vendors bundling diagnostic monitoring with therapeutic delivery. Dominant competitive moves include strategic partnerships between device manufacturers and rehabilitation networks, plus portfolio diversification into companion biomarker strategies.
Within the diversified pharmaceutical tier, Merck KGaA and Bristol-Myers Squibb occupy anchor positions. Merck KGaA exemplifies the oncology diagnostics infrastructure archetype, while Bristol-Myers Squibb represents immunology R&D pipeline diversification into fibrotic complications. Galecto, Inc. sits within the mechanism-differentiated specialist tier, occupying a position defined by galectin-3 inhibitor development against broader anti-fibrotic approaches. These three companies collectively illustrate the competitive tension between scale-driven platform leverage and targeted pathway specialization.
| Leading Market Players |
|---|
| Merck KGaA |
| Sanofi S.A. |
| Bristol-Myers Squibb |
| Galecto, Inc. |
| Trevi Therapeutics, Inc. |
| Boehringer Ingelheim International GmbH |
| AbbVie Inc. |
| Gilead Sciences, Inc. |
| Redx Pharma Plc |
| Others |
Value Network & Pricing Analysis
Overcapacity in hyperbaric oxygen chamber manufacturing across German and Japanese rehabilitation networks is compressing capital equipment margins while elevating aftermarket service pricing power for integrated monitoring platforms. This utilization asymmetry rewards vendors that unbundle hardware from long-term patient tracking contracts.
Pricing Analysis
Aftermarket service revenue tiers covering multi-year patient monitoring contracts drive lifetime value capture for platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center bundles from community clinic procurement and home care direct-pay channels. Cost compression in oral pentoxifylline generics is intensifying because of hospital formulary substitution patterns. Home care channels in Japan demonstrate the lowest price sensitivity due to aging-driven patient-directed procurement outside reimbursement frameworks.
Supply Chain Analysis
Export-control scrutiny of galectin-3 inhibitor biologics and companion diagnostic algorithms under the EU AI Act is constraining cross-border technology flows. Active pharmaceutical ingredient sourcing draws from India, China, and Switzerland for TGF-beta modulators and collagen-targeting compounds. Cold-chain logistics for injectable biologics rest on single-source vulnerability for specialized radiopharmaceutical carriers. Distribution runs through hospital pharmacy and integrated care platforms in the United States, Germany, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA Division of Oncology Products guidance and EMA histological endpoint requirements create switching costs that lock treatment centers into validated platform vendors.
For Market Incumbents: Harden formulary placement through companion biomarker integration that ties diagnostic monitoring to therapeutic procurement. Expand capacity for galectin-3 inhibitor manufacturing in Switzerland to exploit Swissmedic orphan indication premium pricing corridors. Vertical integration into rehabilitation network partnerships defends against third-party survivorship platform displacement.
For New Entrants and Emerging Players: Pursue underpenetrated outpatient rehabilitation networks in Japan's Osaka and Tokyo clusters where mechanical intervention protocols remain outside acute oncology procurement. Target cosmetic treatment applications for superficial fibrosis following breast radiation, where direct-pay dynamics bypass reimbursement variability. Anchor go-to-market strategy through algorithmic diagnostic tools that secure EU AI Act conformity assessment ahead of enforcement deadlines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across oral formulation manufacturing as generic substitution commoditizes pentoxifylline supply. Long-term viability across the analysis window favors platform vendors with combined diagnostic-therapeutic bundling capability. Acquisition targets should demonstrate radiobiology talent concentration and pivotal trial site activation relationships. Watch for FDA guidance revisions on fibrosis-modifying drug endpoints as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Division of Oncology Products guidance accelerates conditional approval timelines for mechanism-specific candidates. |
| Companion Biomarker Development | Galectin-3 inhibitor platforms integrate diagnostic identification of responsive patient subsets in academic medical centers. |
| Rehabilitation Network Partnership | German and Japanese outpatient protocols embed hyperbaric oxygen specifications into standard post-radiation care bundles. |
| EU AI Act Conformity Assessment | Algorithmic diagnostic tools for fibrosis quantification secure first-mover advantage before enforcement deadlines. |
| Pipeline Diversification | Combination regimens pairing anti-fibrotic agents with radiation sensitizers open new trial design categories. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Primary fieldwork with radiation oncology department heads and rehabilitation center procurement managers combined with secondary validation from CMS coverage determinations and German reference pricing authority publications. Bottom-up patient volume modeling and top-down market sizing triangulation anchored quantitative outputs.
Assumptions held fixed include current FDA Division of Oncology Products guidance frameworks and EMA histological endpoint standards, while pricing elasticity parameters varied across reimbursement environments. Segmentation dimensions modeled encompass product type, delivery model, end user, and application scope throughout the forecast period. CAGRs derived from procedure volume trajectories in survivorship programs and therapy adoption curves in rehabilitation networks. Forecast inputs incorporated PMDA oversight patterns for combination regimens and NHS England late-effects clinic expansion rates.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement austerity measures or radiobiology talent availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and histological evidence standard harmonization. Material shifts in FDA guidance on fibrosis-modifying drug endpoints or EU AI Act enforcement timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Enzyme Replacement Therapy Market