
 Idiopathic Thrombocytopenic Purpura Market | 2026-2036
Idiopathic Thrombocytopenic Purpura Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Thrombocytopenic Purpura Market Outlook
Maintenance and monitoring service bundles tied to chronic therapy administration is pivoting how pharmaceutical firms capture long-term value from ITP treatments. Amgen Inc. leverages its thrombopoietin receptor agonist portfolio to anchor recurring patient touchpoints through specialty pharmacy networks. Grifols, S.A. sustains vertical control over plasma collection and fractionation, securing immunoglobulin supply continuity for hospital infusion centers. Novartis AG competes through differentiated access programs that bridge payer coverage gaps for biologic ITP therapies.
Idiopathic thrombocytopenic purpura is an autoimmune hematologic disorder characterized by antibody-mediated platelet destruction, typically presenting with peripheral blood platelet counts below 100,000 per microliter and mucocutaneous bleeding symptoms. The condition demands sustained therapeutic intervention to elevate platelet levels and prevent hemorrhagic complications, with treatment selection hinging on disease chronicity and patient bleeding risk stratification. Corticosteroids occupy the frontline position in acute management protocols, while thrombopoietin receptor agonists represent the fastest-expanding segment as clinicians shift toward platelet-stimulating mechanisms with favorable long-term safety profiles. Hospital end users concentrate the highest margin pool due to bundled reimbursement for intravenous immunoglobulin administration and inpatient monitoring capacity.
FDA, EMA, and WHO standards govern plasma-derived product purity, viral inactivation validation, and lot-to-lot consistency for immunoglobulin therapies, directly shaping manufacturing investment thresholds and market access timelines for new entrants. The EU MDR and FDA's updated biologics guidance are tightening post-market surveillance requirements for thrombopoietin receptor agonists, compelling sponsors to maintain robust pharmacovigilance infrastructure. Stakeholders must weigh regulatory compliance costs against the pricing power of therapies demonstrating superior bleeding event reduction in head-to-head real-world evidence generation.
Market Dynamics
Hospital-based infusion services are consolidating purchasing power for immunoglobulin and thrombopoietin receptor agonist therapies, shifting vendor relationships toward long-term service contracts rather than transactional product sales.
Growth Catalysts
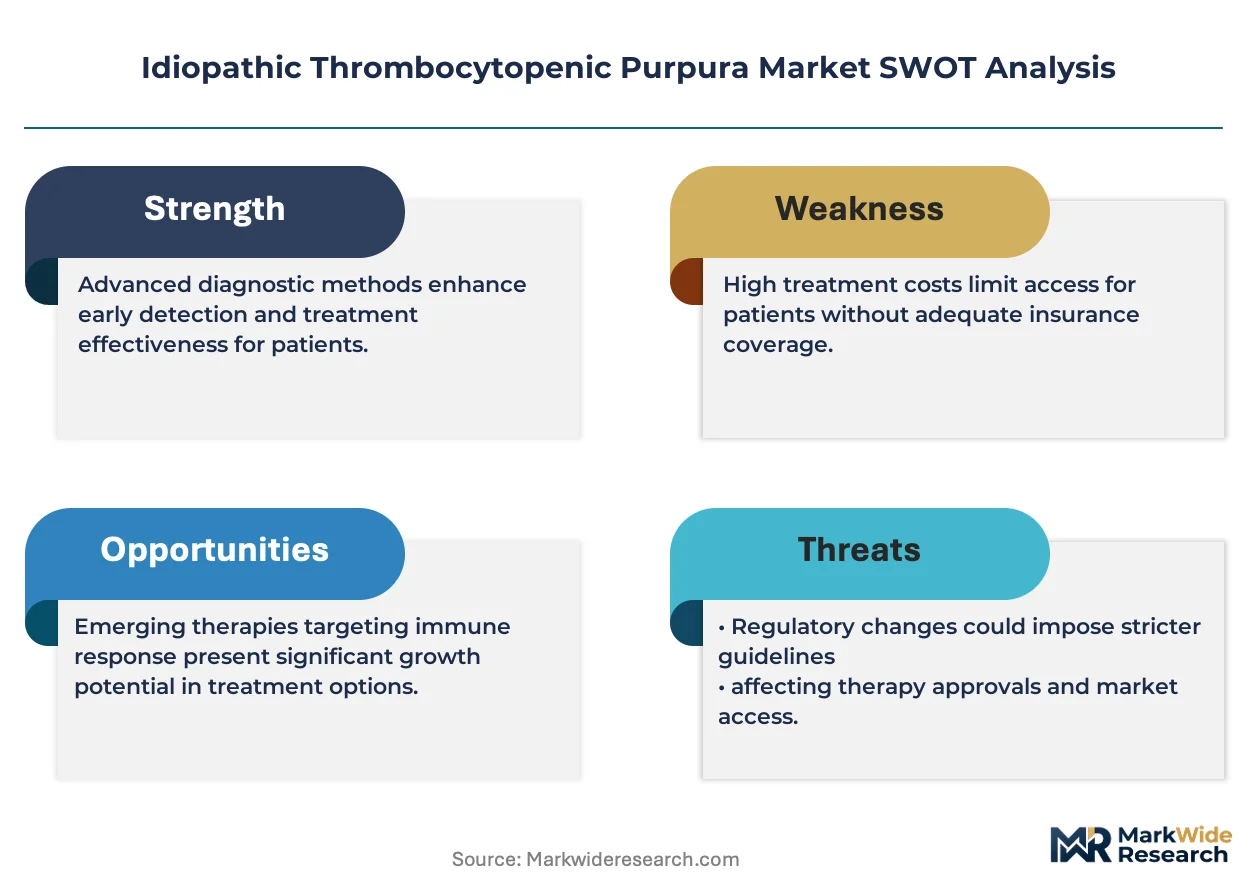
- FDA biologics guidance:Tightened purity benchmarks for intravenous immunoglobulin products are accelerating manufacturing upgrades that reduce lot-to-lot variability and improve patient safety profiles.
- Thrombopoietin receptor agonist mechanisms:Platelet-stimulating therapies with favorable long-term safety data are displacing corticosteroid dependence in chronic ITP management protocols across hematology practices.
- Japan reimbursement pathways:Established chronic disease coverage frameworks for biologic ITP therapies are concentrating demand and validating premium pricing for innovative treatments.
Market Restraints
- Plasma supply concentration:Dependence on US-based collection networks for immunoglobulin raw material creates geographic vulnerability and fractionation capacity bottlenecks.
- EMA post-market surveillance:EU MDR requirements for thrombopoietin receptor agonists extend pharmacovigilance timelines and inflate regulatory maintenance costs for sponsors.
- Substitution pressure from splenectomy:Surgical intervention remains a cost-competitive alternative for refractory patients in markets with limited biologic reimbursement.
Strategic Opportunities
- Germany specialty pharmacy networks:Untapped channel partnerships for home-based subcutaneous immunoglobulin administration could bypass hospital capacity constraints.
- WHO viral inactivation standards:Harmonized international benchmarks for plasma-derived products enable streamlined multi-territory registration and faster market entry.
- Real-world evidence generation:Head-to-head bleeding event reduction data from patient registries supports differentiated pricing negotiations with US payers.
Industry Challenges
- Pharmacovigilance infrastructure:Sponsors must maintain specialized safety monitoring teams capable of detecting rare thrombotic events in chronic TPO-RA exposure populations.
- Legacy corticosteroid protocols:Physician familiarity with frontline steroid tapering regimens creates inertia against switching to platelet-stimulating mechanisms despite superior long-term outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Thrombocytopenic Purpura Market |
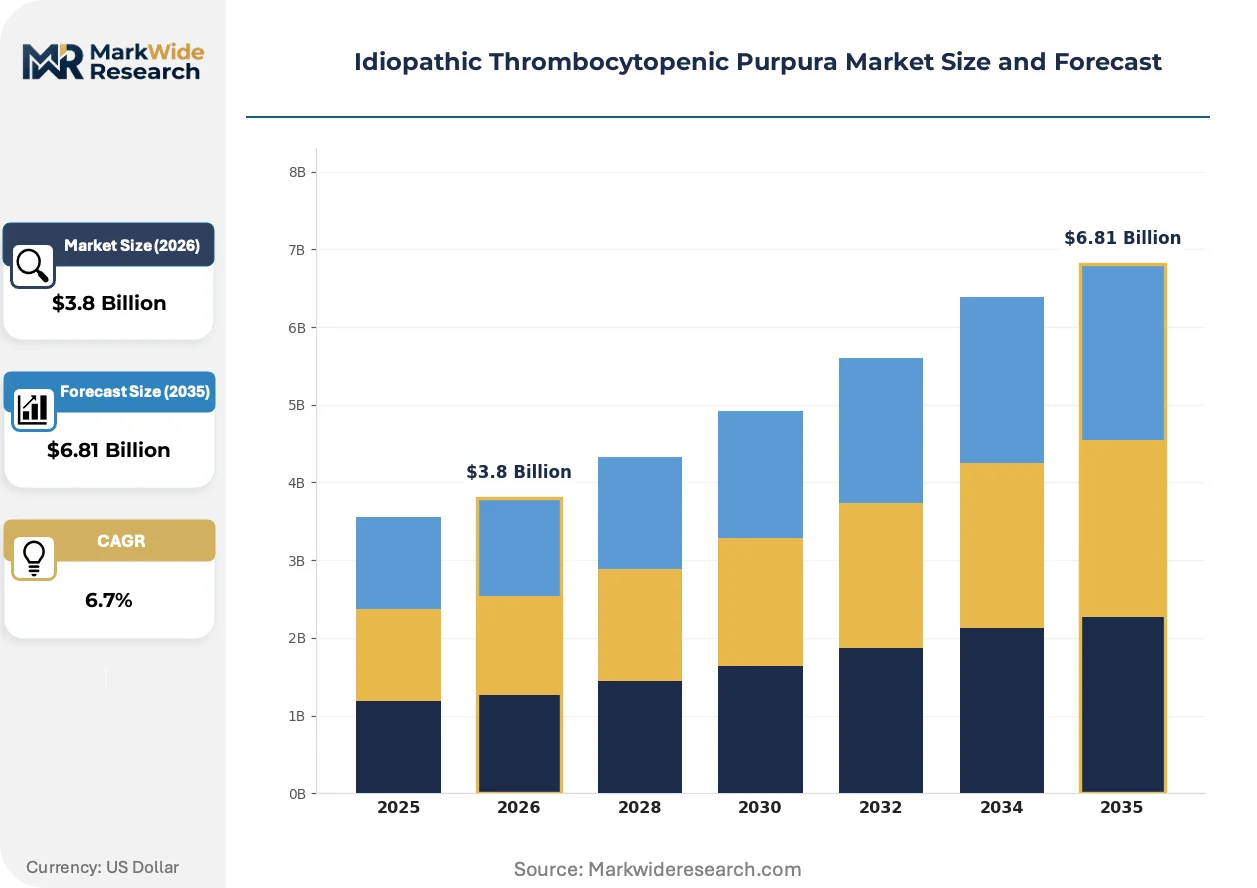
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunoglobulins, Thrombopoietin Receptor Agonists, Others End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare, Specialty Clinics Delivery Mode: Injectables, Oral Medications, Intravenous Solutions, Infusions Diagnosis Method: Bone Marrow Biopsy, Blood Tests, Imaging Techniques, Clinical Evaluation |
| Companies Covered | Amgen Inc., F. Hoffmann-La Roche Ltd, Grifols, S.A., GSK plc., Novartis AG, CSL Behring, Octapharma AG, Bristol-Myers Squibb, Sobi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Thrombocytopenic Purpura Market Strategic Shifts
Biologic manufacturing consistency and patient monitoring technologies are reshaping how ITP therapies demonstrate value beyond platelet count elevation.
Subcutaneous immunoglobulin delivery systems are converging with home nursing support platforms to reduce hospital dependency for chronic ITP patients. Specialty pharmacy networks in Germany and Japan are piloting integrated administration programs that bundle product delivery with trained injection assistance. This convergence is compressing the traditional hospital-centric reimbursement model and shifting margin capture toward outpatient service providers.
EU MDR implementation is mandating enhanced post-market clinical follow-up for thrombopoietin receptor agonists with novel mechanisms of action. Manufacturers must now submit periodic safety update reports with real-world usage data from European patient registries. TPO-RA sponsors with existing EU market authorization are responding by expanding pharmacovigilance teams and funding independent registry studies to preempt regulatory scrutiny.
After-sales service unbundling is fragmenting the traditional bundled reimbursement model for hospital-based IVIG administration. US payers are separating product costs from infusion facility fees, forcing providers to justify monitoring charges independently. This shift is most visible in Medicare Advantage plans, where prior authorization requirements now distinguish between medically necessary observation and routine administration supervision.
Idiopathic Thrombocytopenic Purpura Market Segmentation
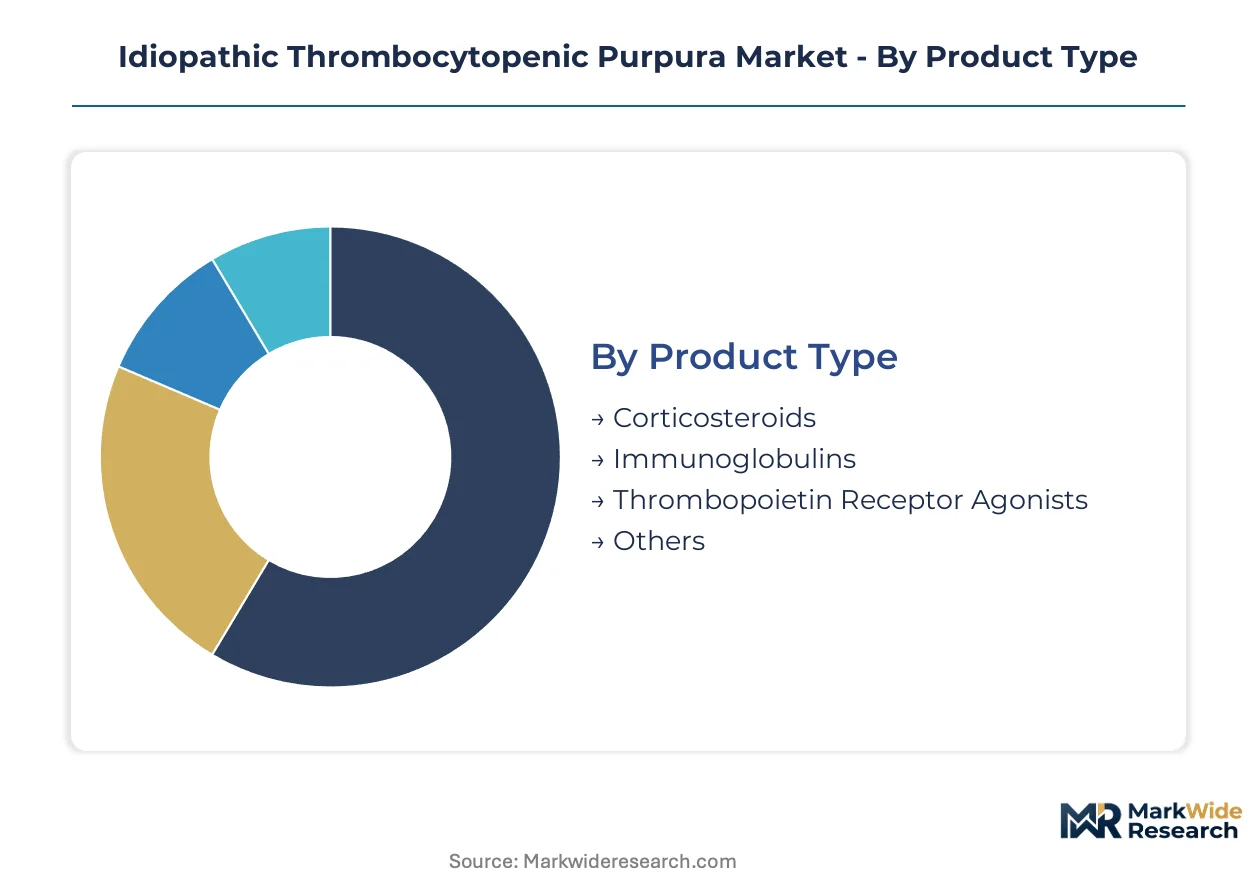
ITP therapeutic selection hinges on disease chronicity, bleeding risk stratification, and reimbursement pathways that favor specific administration settings. Segmentation reveals how platelet-stimulating mechanisms are displacing corticosteroid dependence while hospital infusion services consolidate purchasing power for biologic therapies.
Product Type:
Platelet-stimulating mechanisms and immunomodulatory agents define the therapeutic hierarchy, with manufacturing complexity and long-term safety profiles driving prescriber migration between drug classes.
- Thrombopoietin Receptor Agonists:Synthetic peptides and small molecules stimulate megakaryocyte proliferation through c-Mpl receptor activation. Demand concentrates in hematology practices across the United States and Japan where chronic disease management reimbursement supports premium pricing for platelet-stabilizing regimens with reduced corticosteroid exposure.
- Immunoglobulins:Polyclonal antibody preparations derived from pooled human plasma provide rapid platelet count recovery through Fc receptor blockade and immunomodulatory effects. Hospital infusion centers in Germany and the United States anchor demand due to bundled reimbursement for intravenous administration and inpatient monitoring capacity.
- Corticosteroids:First-line immunosuppressants with established tapering protocols dominate acute ITP management despite long-term toxicity limitations.
- Others:Splenectomy alternatives and investigational monoclonal antibodies fill refractory case niches where standard therapies fail.
Mature deployment sits with Corticosteroids. Newer deployment is concentrated in Thrombopoietin Receptor Agonists.
End User:
Reimbursement bundling and care setting economics determine where margin pools accumulate across the treatment continuum.
- Hospitals:Acute care facilities capture the highest-value procedures through bundled payments for IVIG administration, bone marrow biopsy, and inpatient bleeding event management. FDA and EMA manufacturing consistency requirements for plasma-derived products reinforce hospital preference for established fractionator supply relationships.
- Home Healthcare:Subcutaneous immunoglobulin delivery and oral TPO-RA regimens enable outpatient chronic management with nursing support. Germany's specialty pharmacy networks pilot integrated administration programs that shift margin capture from inpatient facilities to trained home injection services.
- Ambulatory Surgical Centers:Same-day splenectomy and diagnostic procedures concentrate in markets with streamlined prior authorization for surgical alternatives to biologic therapy.
- Specialty Clinics:Hematology-focused practices manage stable chronic patients through telemedicine monitoring and prescription renewal protocols.
Revenue concentration remains with Hospitals. Patient volume expansion is accelerating fastest in Home Healthcare.
Delivery Mode:
Route of administration shapes pharmacokinetic profiles, patient compliance, and the economic structure of therapy provision.
- Intravenous Solutions:Rapid platelet count elevation through immediate bioavailability supports acute bleeding event management. United States hospital systems favor IVIG infusion protocols with established viral inactivation validation and lot-to-lot consistency documentation required by FDA biologics guidance.
- Injectables:Subcutaneous TPO-RA formulations enable patient self-administration with reduced healthcare facility dependency. Japan's chronic disease coverage frameworks validate home-based delivery for romiplostim and eltrombopag analogues.
- Oral Medications:Daily eltrombopag tablets suit maintenance therapy but require hepatic monitoring and dietary timing restrictions.
- Infusions:Extended-duration immunoglobulin preparations support outpatient scheduling flexibility with nursing supervision.
Acute intervention relies on Intravenous Solutions. Maintenance therapy is migrating toward Injectables.
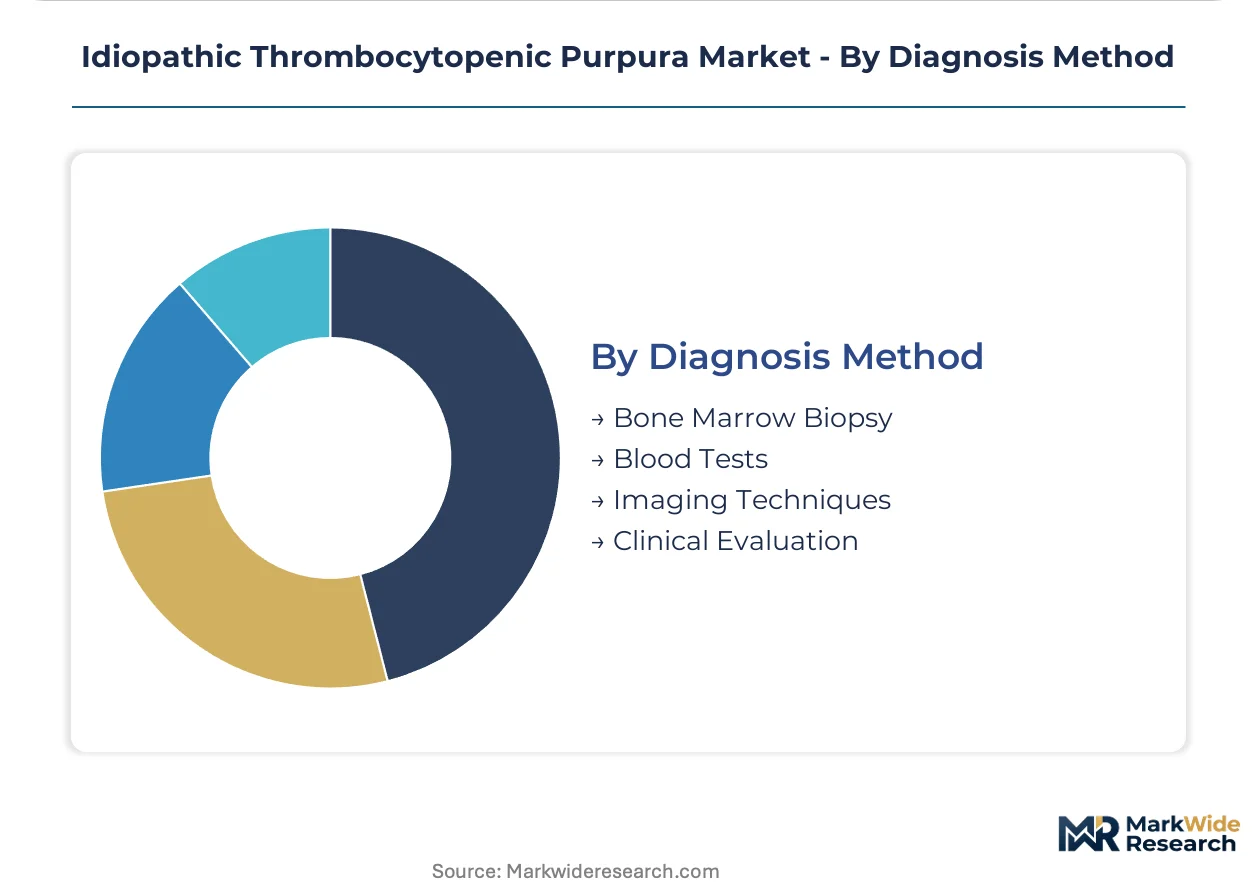
Diagnosis Method:
Confirmatory testing intensity correlates with disease severity assessment and treatment eligibility determination.
- Blood Tests:Complete blood count with peripheral smear review provides initial platelet quantification and morphology assessment. Diagnostic laboratories across the United States, Germany, and Japan standardize automated analyzer protocols for reproducible count thresholds below 100,000 per microliter.
- Clinical Evaluation:Mucocutaneous bleeding symptom assessment and medication history review guide initial corticosteroid initiation without invasive procedures. Primary care networks in markets with limited hematology specialist access rely on standardized bleeding score instruments.
- Bone Marrow Biopsy:Aspirate and trephine examination rules out aplastic anemia and leukemia in atypical presentations or treatment-refractory cases.
- Imaging Techniques:Ultrasound and cross-sectional imaging exclude splenic sequestration or occult hemorrhage in severe thrombocytopenia.
Definitive confirmation rests with Bone Marrow Biopsy. Frontline screening is concentrating in Blood Tests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation capacity concentrates in the United States while consumption spreads across developed markets with established reimbursement frameworks. Hospital infusion networks in Germany and Japan absorb significant immunoglobulin volumes through bundled chronic disease management pathways.
United States
FDA biologics guidance mandates tightened purity benchmarks for intravenous immunoglobulin products, accelerating manufacturing upgrades among plasma fractionators. Hospital-based infusion services in Texas and North Carolina anchor demand through bundled Medicare reimbursement for chronic ITP administration. Specialty pharmacy networks in California pilot home-based subcutaneous delivery programs that bypass traditional inpatient capacity constraints.
Germany
EMA post-market surveillance requirements under EU MDR extend pharmacovigilance timelines for thrombopoietin receptor agonists, inflating regulatory maintenance costs for sponsors. The country's statutory health insurance funds validate premium pricing for biologic ITP therapies through established chronic disease management protocols. Bavaria's hematology centers concentrate real-world evidence generation capabilities that support differentiated pricing negotiations with regional sickness funds.
Japan
PMDA manufacturing consistency standards govern lot-to-lot variability documentation for plasma-derived products entering the market. The Ministry of Health, Labour and Welfare's chronic disease coverage frameworks concentrate demand for romiplostim and eltrombopag analogues in Tokyo and Osaka metropolitan hospitals. Home healthcare providers in Kansai region pilot integrated administration programs that shift margin capture from inpatient facilities to trained injection services.
Switzerland
Swissmedic viral inactivation validation requirements align with WHO international benchmarks, enabling streamlined multi-territory registration for immunoglobulin therapies. The country's compulsory health insurance system reimburses biologic ITP treatments through standardized tariff structures. Basel's pharmaceutical manufacturing cluster hosts fractionation facilities that supply hospital networks across German-speaking Europe.
United Kingdom
NHS England's specialised commissioning framework restricts biologic ITP therapy access to designated tertiary hematology centers. NICE technology appraisals determine cost-effectiveness thresholds for thrombopoietin receptor agonists against corticosteroid tapering protocols. London's academic medical centers generate head-to-head bleeding event reduction data that informs national treatment guidelines.
Idiopathic Thrombocytopenic Purpura Market Competitive Environment
Capital-heavy plasma fractionators compete with asset-light biologic developers across distinct value chain segments. The market structure consolidates around vertically integrated plasma collectors and specialty pharmaceutical firms with thrombopoietin receptor agonist portfolios. Three archetypes dominate: integrated plasma suppliers controlling raw material through fractionation, biologic developers licensing platelet-stimulating mechanisms, and diversified hematology players bundling diagnostic and therapeutic offerings. Capacity expansion in US plasma collection networks and strategic partnerships between specialty pharmacies and home nursing platforms represent the dominant competitive moves reshaping vendor relationships.
Among integrated plasma suppliers, Grifols, S.A. and CSL Behring exemplify the archetype of backward-controlled fractionators securing immunoglobulin supply continuity for hospital infusion centers. Within the biologic development tier, Amgen Inc. and Novartis AG occupy positions anchored by thrombopoietin receptor agonist portfolios that generate recurring patient touchpoints through specialty pharmacy networks. These named entities represent distinct strategic postures rather than exhaustive market coverage, with each archetype competing on different vectors of manufacturing scale, regulatory compliance infrastructure, and chronic disease management service bundling.
| Leading Market Players |
|---|
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| Grifols, S.A. |
| GSK plc. |
| Novartis AG |
| CSL Behring |
| Octapharma AG |
| Bristol-Myers Squibb |
| Sobi |
| Others |
Value Chain & Pricing Dynamics
Backward integration into plasma collection networks anchors both supply security and pricing power for immunoglobulin fractionators, while TPO-RA developers compete through service bundling rather than raw material control. Hospital purchasing committees leverage bundled reimbursement to extract volume discounts from established suppliers, compressing margins for transactional vendors lacking chronic disease management infrastructure.
Pricing Analysis
Margin tightening in hospital-based IVIG administration reflects unbundling of product costs from infusion facility fees under Medicare Advantage prior authorization reforms. Three-tier pricing structure across premium fractionators, standard plasma suppliers, and economy-grade regional players tracks FDA viral inactivation validation tiers and lot-to-lot consistency documentation. Cost-down pressure on subcutaneous immunoglobulin accelerates because specialty pharmacy networks in Germany and California pilot home-based delivery programs that bypass traditional inpatient markups. Price-sensitive buyers cluster in ambulatory surgical centers evaluating splenectomy alternatives, while least-sensitive demand concentrates in tertiary hematology centers managing refractory chronic ITP with premium TPO-RA regimens.
Supply Chain Analysis
Single-source vulnerability sits with US-based plasma collection networks that feed fractionation capacity concentrated in Texas, North Carolina, and Basel metropolitan clusters. Raw material dependencies center on paid donor plasma volumes, viral inactivation validation reagents, and c-Mpl receptor synthesis substrates for peptide agonist manufacturing. Supply chain risk traces to geographic concentration of fractionation assets exposed to FDA biologics guidance compliance costs and lot-release bottlenecks. Distribution runs through hospital-based infusion centers in the United States and Germany, with emerging direct-to-patient channels via Japan's home healthcare providers and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where plasma fractionators deepen backward control over donor collection while biologic developers extend forward into patient monitoring services. Winners will anchor pricing power through captive raw material supply or chronic disease management infrastructure.
For Market Incumbents: Extend pharmacovigilance infrastructure investments to preempt EU MDR post-market surveillance scrutiny for TPO-RA portfolios, and expand plasma collection center networks in the United States to secure immunoglobulin raw material continuity against geographic supply shocks. Defensive consolidation should target specialty pharmacy partnerships that bundle product delivery with trained injection assistance, neutralizing emerging home healthcare competitors.
For New Entrants and Emerging Players: Capture white-space in Germany's home-based subcutaneous immunoglobulin administration channel, where statutory health insurance reimbursement validation creates entry pathways for integrated service providers. Target Japan's chronic disease coverage frameworks for oral TPO-RA regimens, leveraging PMDA manufacturing consistency standards as a regulatory moat against unvalidated competitors. Go-to-market positioning should emphasize real-world bleeding event reduction data to differentiate against legacy corticosteroid protocols.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmaceutical firms with thrombopoietin receptor agonist portfolios and established pharmacovigilance infrastructure, or integrated plasma suppliers with captive collection networks. Long-term viability favors assets demonstrating sustained pricing power through regulatory compliance barriers and chronic therapy bundling capabilities. The signal to watch is unbundling acceleration in US Medicare Advantage reimbursement structures, which would compress margins for hospital-centric business models and reward outpatient service integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Backward integration into US donor centers secures immunoglobulin raw material continuity against geographic supply concentration risks. |
| Pharmacovigilance Infrastructure Buildout | EU MDR compliance capabilities differentiate TPO-RA sponsors facing extended post-market surveillance timelines and registry study mandates. |
| Specialty Pharmacy Partnership | Integrated administration programs in Germany and Japan shift margin capture from hospital infusion centers to home-based service providers. |
| Real-World Evidence Generation | Head-to-head bleeding event reduction data from patient registries supports premium pricing negotiations with US payers and regional sickness funds. |
| Subcutaneous Delivery Platform Development | Self-administration formulations reduce healthcare facility dependency and align with Japan's chronic disease coverage frameworks for home-based therapy. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hematology practice directors, hospital procurement managers, plasma fractionation executives, and payer access specialists. FDA biologics guidance documents, EMA post-market surveillance submissions, and PMDA manufacturing consistency standards provided regulatory validation. Bottom-up patient population estimates triangulated against top-down therapy expenditure data from statutory health insurance funds and Medicare claims patterns.
Data-stream reconciliation across product type, end user, delivery mode, and diagnosis method segmentation generated volume and value outputs across the projection horizon. CAGRs derived from therapy line migration assumptions, corticosteroid-to-TPO-RA switching rates, and reimbursement pathway expansion in target markets. Forecast inputs incorporated plasma collection volume trends, fractionation capacity utilization, and chronic disease management protocol adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, plasma supply geographic shocks, and unbundling acceleration in US reimbursement structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Single Blood Drop Analysis Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Hemostatic Spray Market
Hematology
Global Hematology Diagnostics Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Rare Hematology Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Febrile Neutropenia Market
Hematology
Sickle Cell Treatment Market
Hematology
Global Immunohematology Market
Hematology
Global Hemoglobin Meter Market
Hematology
Graft vs Host Disease Market
Hematology
Allogeneic Stem Cell Therapy Market