
 Commercial Wood Fired Pizza Oven Market | 2026-2036
Commercial Wood Fired Pizza Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Wood Fired Pizza Oven Market Insights
NSF International commercial food equipment certification is bifurcating the competitive landscape between qualified and unqualified suppliers. Forno Bravo leverages its California manufacturing base to anchor North American distribution. Marra Forni specializes in Italian-imported refractory materials that sustain premium positioning. Wood Stone Corporation dominates the hybrid gas-wood segment through technology leadership in infrared burner integration.
A commercial wood fired pizza oven is a thermally insulated cooking chamber constructed from refractory brick, castable concrete, or engineered steel, designed to reach operational temperatures between 700°F and 900°F for rapid Neapolitan-style baking. The product category serves restaurants, pizzerias, and mobile catering operations requiring authentic flame-cooked output and visible hearth aesthetics. Brick ovens command the highest margin pools due to material costs and artisanal installation requirements, while mobile ovens represent the fastest-expanding category as food truck operators seek differentiated menu offerings. Fuel type segmentation reveals wood-pellet hybrids gaining traction where municipal wood-burning restrictions limit traditional hardwood combustion.
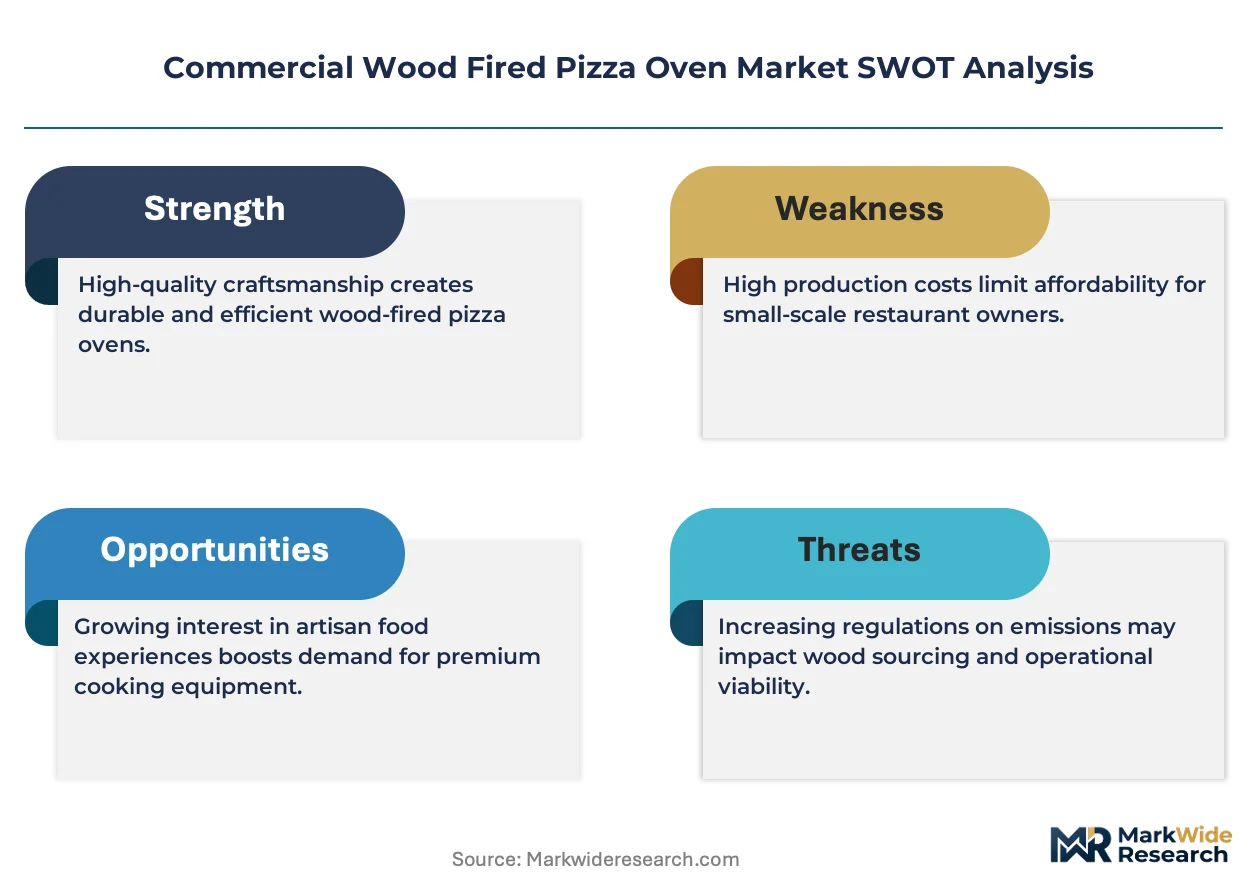
The United States Food and Drug Administration and NSF International jointly govern surface-contact safety standards, while the Environmental Protection Agency regulates particulate emissions from commercial wood combustion equipment. European manufacturers face REACH compliance for refractory material composition and CE marking for gas-fired hybrid models. Stakeholders must monitor evolving municipal burn bans and emission thresholds that threaten wood-exclusive installations in dense urban zones.
Market Dynamics
NSF International certification requirements are bifurcating supplier qualification tiers, concentrating procurement authority among certified manufacturers while marginalizing uncertified imports in the United States foodservice equipment channel.
Growth Catalysts
- Fast-casual restaurant chain expansion:Independent pizzerias and multi-unit operators are prioritizing visible hearth installations to differentiate dining experiences and command premium menu pricing.
- Wood-pellet hybrid combustion systems:Municipal wood-burning restrictions in dense urban zones are accelerating adoption of compliant fuel-flexible configurations that satisfy EPA emission thresholds.
- REACH compliance harmonization:European refractory material standards are streamlining cross-border certification for Italian and Spanish manufacturers exporting to unified regulatory markets.
Market Restraints
- Artisanal installation labor scarcity:Refractory brick oven construction requires specialized masons whose training pipelines have contracted, extending deployment timelines.
- Refractory material cost volatility:High-alumina firebrick and castable concrete supply concentrates in Mediterranean production clusters exposed to energy input fluctuations.
- Gas-fired hybrid substitution pressure:Infrared burner integration from Wood Stone Corporation and competitors threatens pure-wood positioning where emission restrictions tighten.
Strategic Opportunities
- Mobile catering channel penetration:Food truck operators in Texas, California, and Florida represent underdeveloped demand for compact trailer-mounted oven configurations.
- CE marking pathway expansion:Gas-fired hybrid models accessing unified European markets through streamlined conformity assessment reduce national-level compliance duplication.
- Infrared-wood convergence:Dual-fuel technology combining traditional flame aesthetics with precision temperature control opens institutional cafeteria and hotel kitchen segments.
Industry Challenges
- NSF certification timeline compression:Commercial food equipment approval cycles average fourteen months, delaying product launches and freezing R&D roadmaps.
- Refractory supply chain reconfiguration:Italian-imported material dependencies force inventory pre-positioning that strains working capital for North American distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Wood Fired Pizza Oven Market |
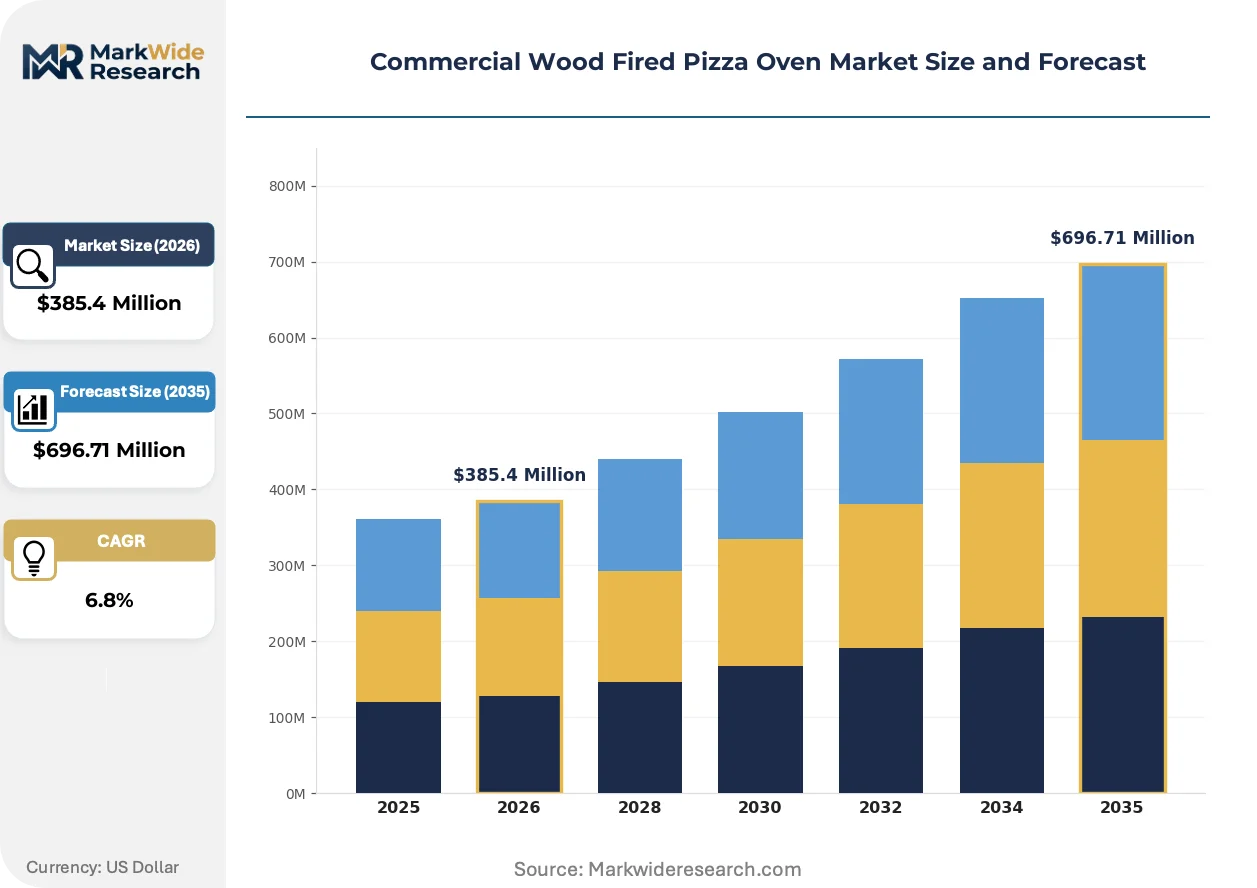
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brick Oven, Mobile Oven, Modular Oven, Traditional Oven End User: Restaurants, Food Trucks, Catering Services, Pizzerias Fuel Type: Wood, Pellets, Charcoal, Gas Size: Small, Medium, Large, Extra Large |
| Companies Covered | Beech Ovens, Californo, Chicago Brick Oven, EarthStone Wood Fire Ovens, Fontana Forni USA, Forno Bravo, Wood Stone Corporation, Marra Forni, Morello Forni Italia Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Wood Fired Pizza Oven Market Trends and Innovations
Active thermal management and combustion control technologies are redefining operational specifications across installation types, compressing the performance gap between traditional masonry and engineered steel alternatives.
Engineered steel oven enclosures with integrated insulation systems are displacing site-built refractory construction in time-sensitive deployment scenarios. Fast-casual chains with standardized kitchen footprints are specifying modular prefabricated units that ship in three weeks versus three months. This displacement is compressing the addressable market for artisanal brick masons while expanding manufacturer direct-to-operator sales channels.
EPA particulate emission standards for commercial wood combustion equipment are tightening enforcement in metropolitan air quality districts. Manufacturers must now submit certified test data for each oven model, adding fifteen thousand dollars in compliance costs per configuration. Mobile operators in California and New York are responding by pre-filtering procurement toward pellet-ready hybrid systems.
Specification authority is migrating from executive chefs to procurement directors with standardized equipment matrices. Chain operators are unbundling after-sales service from initial purchase, contracting third-party maintenance networks instead of manufacturer technicians. This shift concentrates volume with distributors offering multi-brand service coverage, particularly visible in the Southeast and Southwest United States markets.
Commercial Wood Fired Pizza Oven Market Segmentation
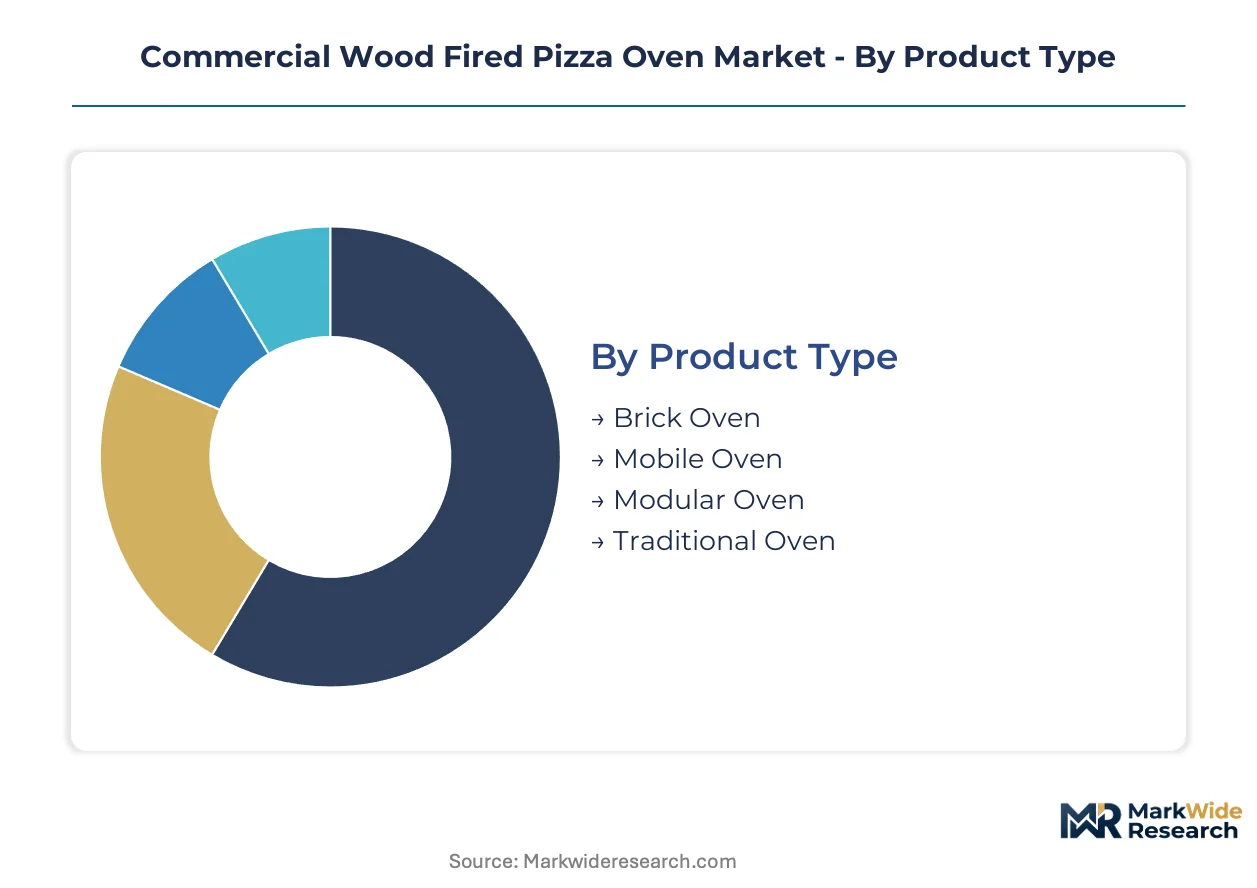
Segmentation in commercial wood fired pizza ovens reveals how regulatory compliance, mobility requirements, and fuel restrictions reshape procurement patterns across foodservice channels. Each dimension carries distinct certification burdens and installation constraints that determine addressable market scope.
Product Type:
NSF International certification requirements bifurcate this category between permanently installed masonry systems and transportable engineered alternatives, with compliance timelines and material specifications diverging sharply.
- Brick Oven:Constructed from high-alumina refractory firebrick and castable concrete, these site-built installations require specialized masons and artisanal construction timelines. Independent pizzerias in Italy and heritage restaurant operators across the United States concentrate demand here, driven by visible hearth aesthetics and thermal mass retention for Neapolitan-style baking.
- Mobile Oven:Trailer-mounted steel enclosures with integrated insulation systems serve food truck operators and temporary catering setups. Texas, California, and Florida operators are expanding installations fastest as municipal permitting streamlines for mobile foodservice equipment.
- Modular Oven:Prefabricated refractory components ship flat-pack for on-site assembly, compressing deployment timelines versus traditional brick construction.
- Traditional Oven:Dome-shaped masonry designs imported from Mediterranean production clusters anchor premium positioning in artisanal pizzeria segments.
Brick ovens handle the majority of throughput in established dining markets; mobile ovens are expanding most quickly as food truck licensing accelerates across Sun Belt states.
End User:
Procurement authority varies dramatically across this dimension, with executive chefs driving specification in independent restaurants while procurement directors standardize equipment matrices for multi-unit chains.
- Restaurants:Full-service operators prioritize visible hearth installations to differentiate dining experiences and command premium menu pricing. Fast-casual chains in the United States specify modular prefabricated units that ship in three weeks versus three months for site-built alternatives.
- Pizzerias:Independent operators and multi-unit franchisees require NSF-certified equipment for insurance and health department compliance, concentrating volume with certified manufacturers.
- Food Trucks:Compact footprint requirements and weight restrictions favor engineered steel enclosures over refractory masonry.
- Catering Services:Rental and event operators demand rapid thermal recovery and transportability for off-premise service.
Restaurants command the largest installed base; food trucks are gaining share fastest as mobile foodservice licensing expands.
Fuel Type:
EPA particulate emission standards and municipal burn bans are restructuring competitive positioning across combustion configurations, with hybrid systems capturing share in restricted air quality districts.
- Wood:Traditional hardwood combustion delivers authentic flame aesthetics and flavor profiles prized by artisanal operators. Dense urban zones in California and New York are tightening restrictions, threatening pure-wood positioning where emission thresholds constrict.
- Pellets:Compressed biomass fuel systems satisfy EPA emission standards while preserving visible flame characteristics. Municipal wood-burning restrictions are accelerating adoption of pellet-ready hybrid configurations among mobile operators in regulated air quality districts.
- Gas:Infrared burner integration enables precise temperature control and rapid preheat cycles, opening institutional cafeteria and hotel kitchen segments.
- Charcoal:Lump charcoal combustion serves specialty barbecue-pizza fusion concepts seeking distinct smoke profiles.
Wood retains the dominant installed position; pellet configurations are climbing the fastest as compliance pressure mounts.
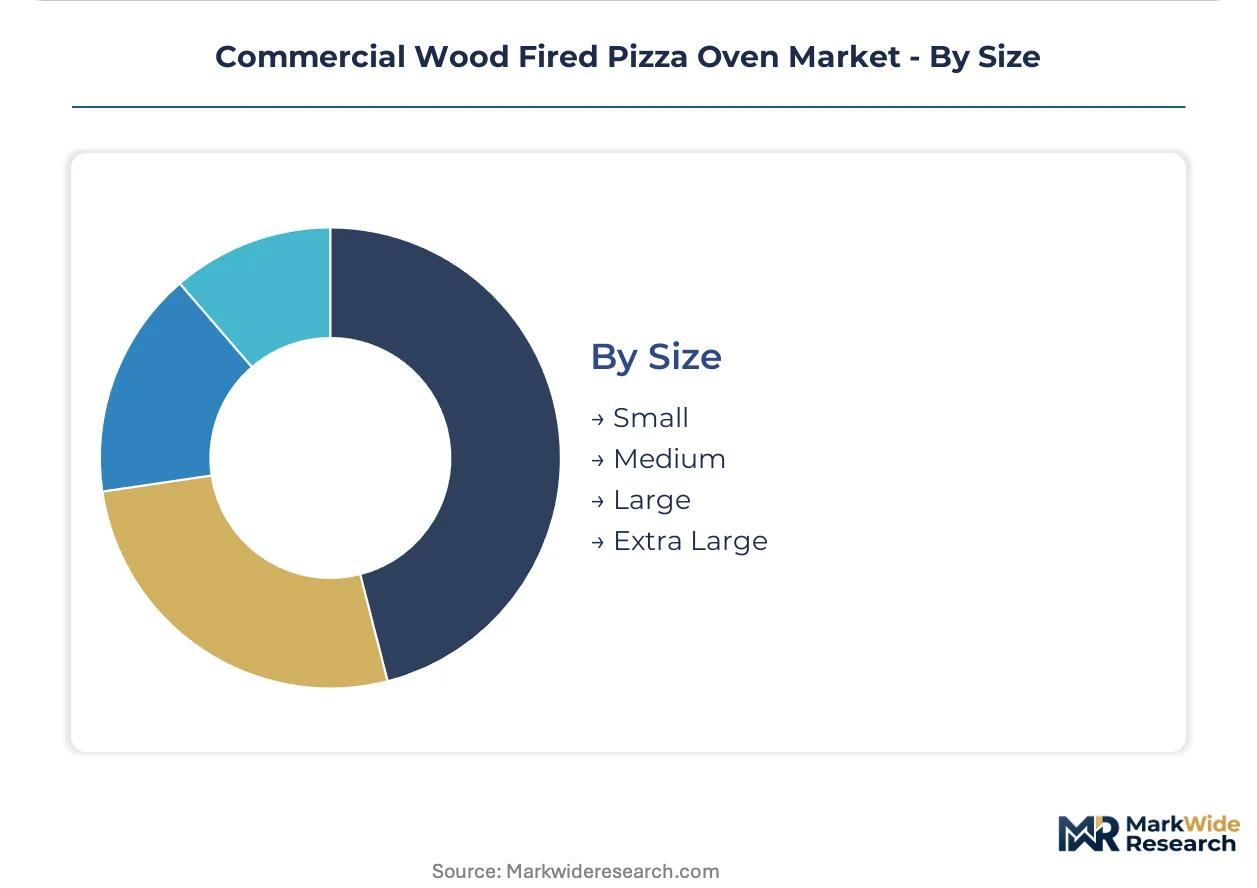
Size:
Kitchen footprint constraints and throughput requirements determine specification, with fast-casual chains standardizing dimensions across standardized buildouts.
- Large:High-volume installations accommodate multiple pizza simultaneous baking for busy dinner service periods. Chain operators in the United States specify these for flagship locations with visible open-kitchen designs.
- Medium:Versatile throughput range serves independent pizzerias with variable demand patterns and limited line cook staffing.
- Small:Compact enclosures fit food truck galley layouts and ghost kitchen operations with severe space constraints.
- Extra Large:Custom installations serve high-throughput commissary kitchens and stadium concession operations.
Medium units handle the majority of new installations; large formats are expanding fastest as chain rollouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission thresholds and NSF certification mandates are concentrating procurement authority among qualified suppliers in regulated markets, while REACH compliance streamlines Italian and Spanish manufacturer access across European borders.
United States
Fast-casual restaurant chains in Texas, California, and Florida are accelerating visible hearth installations to command premium menu pricing. The Environmental Protection Agency enforces particulate emission standards that add fifteen thousand dollars in compliance costs per oven configuration. Los Angeles and New York metropolitan air quality districts are tightening burn bans, pushing mobile operators toward pellet-ready hybrid systems.
Italy
Artisanal pizzerias in Naples and Rome sustain demand for dome-shaped masonry designs imported from Mediterranean production clusters. REACH compliance for refractory material composition enables streamlined CE marking access across unified European markets. The Emilia-Romagna industrial corridor anchors high-alumina firebrick manufacturing, though energy input fluctuations strain working capital for export-oriented fabricators.
Germany
Full-service restaurant operators in Bavaria and North Rhine-Westphalia prioritize thermal mass retention for Neapolitan-style baking authenticity. ECHA oversees REACH enforcement for refractory material imports from Italian suppliers. Berlin's fast-casual dining expansion favors modular prefabricated units that compress deployment timelines versus site-built alternatives.
Spain
Catalonia and Madrid hospitality clusters are adopting engineered steel enclosures for time-sensitive kitchen renovations. CE marking for gas-fired hybrid models reduces national-level compliance duplication across Iberian Peninsula markets. Barcelona's food truck licensing acceleration favors compact trailer-mounted configurations with integrated insulation systems.
Canada
Independent pizzerias in Ontario and British Columbia concentrate demand for NSF-certified equipment to satisfy health department and insurance requirements. Health Canada and PMRA govern surface-contact safety standards for commercial foodservice equipment. Vancouver's municipal permitting streamlines for mobile foodservice equipment are expanding food truck operator installations.
Commercial Wood Fired Pizza Oven Market Competitive Landscape
Player mix skews toward Italian-imported refractory specialists and North American engineered steel fabricators, creating a tiered structure where certification status determines channel access. Two strategic archetypes dominate: Mediterranean artisanal brick oven exporters leveraging material authenticity premiums, and California-based manufacturers exploiting domestic production for NSF compliance speed. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into pellet-hybrid configurations.
Among Italian-imported specialists, Marra Forni and Morello Forni Italia Srl occupy positions anchored by refractory material sourcing from Mediterranean production clusters. Forno Bravo represents the North American domestic manufacturing archetype, leveraging its California base to compress NSF certification timelines and anchor distribution across the United States foodservice equipment channel.
| Leading Market Players |
|---|
| Beech Ovens |
| Californo |
| Chicago Brick Oven |
| EarthStone Wood Fire Ovens |
| Fontana Forni USA |
| Forno Bravo |
| Wood Stone Corporation |
| Marra Forni |
| Morello Forni Italia Srl |
| Others |
Pricing and Supply Chain Analysis
Production scale at Mediterranean refractory clusters anchors both supply concentration and price floors, as Italian and Spanish fabricators leverage high-alumina firebrick sourcing advantages while North American engineered-steel competitors compete on NSF certification velocity rather than material cost.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified suppliers, with NSF International approval adding compliance premiums that separate certified manufacturers from marginal imports. Three-tier pricing structure across artisanal brick, modular prefabricated, and mobile steel enclosures reflects installation complexity and thermal mass differentiation. Cost compression in entry-level engineered segments is intensifying because fast-casual chains unbundle after-sales service and standardize equipment matrices. Independent pizzerias exhibit lowest price sensitivity due to authenticity premiums, while food truck operators face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of Italian-imported refractory materials prevails over just-in-time preferences, as Mediterranean supply disruptions from energy input volatility force North American distributors to pre-position inventory. High-alumina firebrick and castable concrete concentrate in Italy and Spain, while engineered steel enclosures source from domestic U.S. fabrication. Single-source vulnerability runs through Emilia-Romagna refractory clusters exposed to natural gas price swings. Distribution runs through multi-brand foodservice equipment distributors offering bundled maintenance coverage, particularly across Southeast and Southwest U.S. markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against infrared gas-wood hybrid systems that threaten pure-wood positioning where EPA emission restrictions tighten.
For Market Incumbents: Fortify certification moats by compressing NSF approval cycles below fourteen-month industry averages, while anchoring distribution partnerships with multi-brand service networks in Texas and Florida. Gas-fired hybrid substitution from Wood Stone Corporation and competitors demands defensive R&D investment in pellet-ready configurations. For New Entrants and Emerging Players: California NSF fast-track certification offers the most penetrable entry pathway, exploiting domestic manufacturing proximity to regulatory authorities. Mobile catering channels in food truck licensing acceleration zones present white-space demand for compact trailer-mounted configurations with integrated insulation systems. Target direct-to-operator sales bypassing established distributor tiers. For Investors and Strategic Acquirers: Mediterranean-imported refractory specialists with REACH compliance infrastructure and established CE marking pathways represent the priority acquisition archetype. Long-term viability hinges on fuel-flexibility portfolio positioning as municipal burn bans expand. Watch EPA particulate enforcement intensity in Los Angeles and New York metropolitan districts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pellet-Hybrid Configuration Launch | EPA emission compliance in California and New York air quality districts secures channel access. |
| NSF Certification Fast-Track Investment | Fourteen-month approval cycle compression anchors procurement authority in U.S. foodservice. |
| Mobile Catering Channel Expansion | Texas and Florida food truck licensing acceleration opens underdeveloped demand segments. |
| REACH Compliance Infrastructure Buildout | Italian and Spanish manufacturers leverage unified European market access through CE marking. |
| After-Sales Service Network Unbundling | Third-party maintenance contracting aligns with fast-casual chain procurement director preferences. |
Research Methodology
Operator-level perspectives from pizzeria owners, fast-casual chain procurement directors, food truck operators, and commercial kitchen equipment distributors anchored the qualitative base. Primary interviews combined with secondary validation from EPA emission standard filings, NSF International certification databases, and foodservice equipment customs records. Bottom-up unit economics from installation cost structures and top-down market sizing from refractory material trade flows enabled triangulation across independent verification paths.
Sensitivity analysis tested demand elasticity to municipal burn ban expansion scenarios and refractory material cost volatility assumptions across the projection horizon. Segmentation modeling incorporated product type, fuel configuration, end-user channel, and geographic regulatory cluster dimensions. CAGRs derived from installed base growth rates, replacement cycle compression, and penetration assumptions in mobile catering channels. Forecast inputs included artisanal mason labor availability constraints and pellet combustion technology adoption curves.
Decision-makers should treat outputs as directional under stable EPA enforcement intensity and no federal preemption of municipal wood-burning restrictions; material deviation would warrant model refresh. Revision becomes warranted when infrared hybrid substitution rates cross thresholds that restructure competitive tiering.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Dispensing Systems and Equipment Market