
 Fish Processing Equipment Market | 2026-2036
Fish Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Processing Equipment Market Analysis
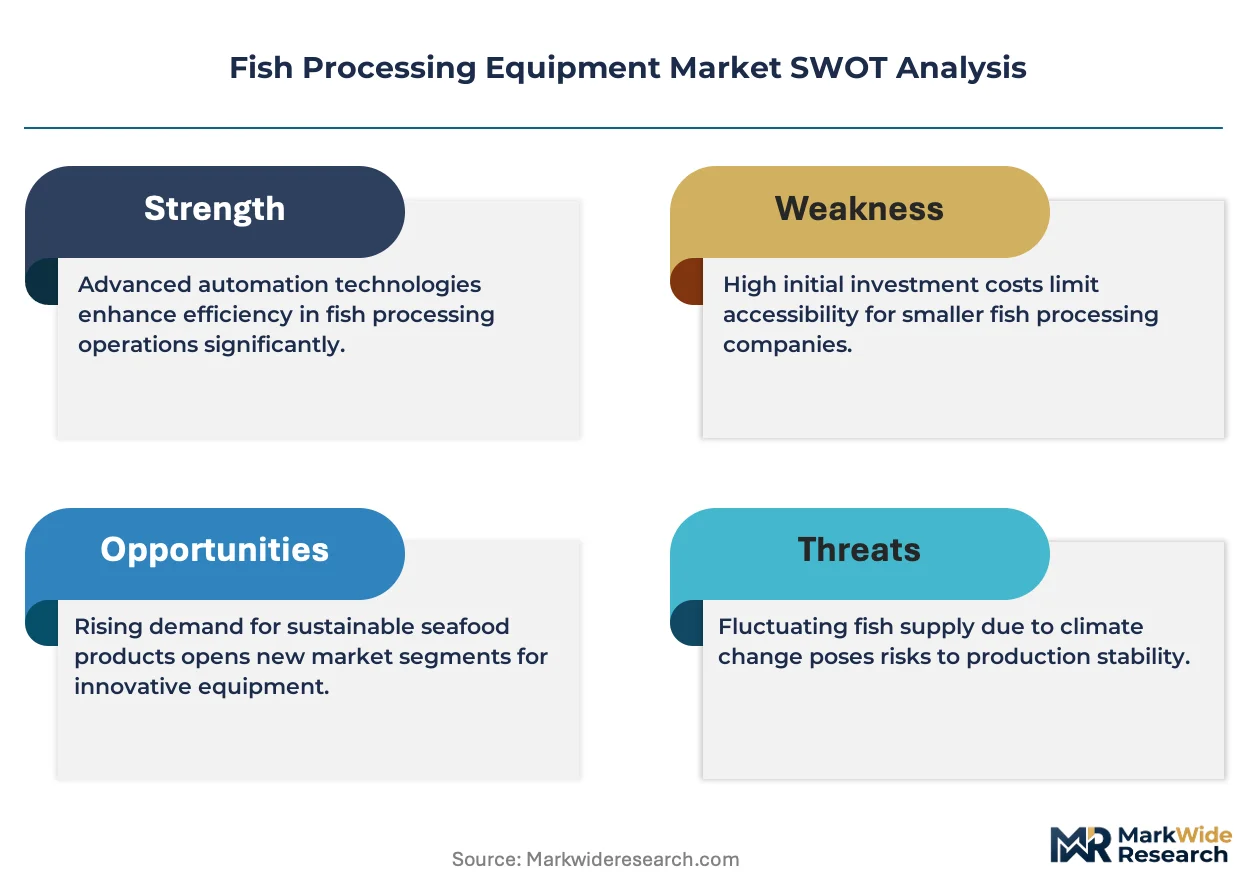
Automation in fish processing is rewriting the competitive economics of filleting and portioning operations. Marel leverages its robotics portfolio to sustain premium positioning in high-throughput salmon processing. Baader Global SE anchors its market presence through deep specialization in precision cutting systems for whitefish species.
Fish processing equipment encompasses machinery designed to transform raw catch into consumer-ready products through heading, gutting, filleting, skinning, freezing, and packaging operations, typically operating at temperatures between minus 25°C and 10°C to preserve protein integrity and inhibit bacterial proliferation. Filleting machines dominate capital allocation due to labor substitution economics in high-wage processing economies. Automated systems represent the fastest-expanding technology dimension as pneumatic and hydraulic platforms face displacement by vision-guided robotic workcells that reduce yield loss and improve portion consistency. Processing plants absorb the majority of installed equipment value, while food service channels are emerging as a distinct demand node driven by centralized kitchen prep requirements.
The European Food Safety Authority mandates Hazard Analysis and Critical Control Points compliance across seafood processing equipment, elevating stainless-steel construction standards and sanitization protocol integration. The FDA's Seafood HACCP regulation in the United States creates parallel design requirements for exporters serving American retail and restaurant chains. Stakeholders must monitor how evolving carbon accounting rules from the EU Green Deal reshape freezer energy specifications and refrigerant selection across the equipment supply base.
Market Dynamics
Automated filleting systems are compressing labor-dependent processing economics while EU traceability mandates force capital redeployment toward digital sorting infrastructure. Blast freezing capacity expansion in Norway's seafood corridor signals equipment preference shifts across Nordic processing clusters.
Growth Catalysts
- EU Common Fisheries Policy reform:Tightened traceability requirements are accelerating processor investment in blockchain-enabled sorting and digital tracking systems across European seafood facilities.
- Retail supermarket chains:Frozen seafood demand from centralized retail procurement is driving capital expenditure on automated filleting and freezing lines in high-wage processing economies.
- Vision-guided robotics:Pneumatic and hydraulic platforms face displacement by robotic workcells that reduce yield loss and improve portion consistency in salmon and whitefish operations.
Market Restraints
- Stainless-steel input volatility:Equipment construction costs fluctuate with nickel and chromium price swings, compressing margin buffers for mid-scale processing equipment manufacturers.
- Refrigerant supply concentration:EU F-Gas Regulation phase-down schedules constrain hydrofluorocarbon availability, forcing processor adaptation to alternative cooling chemistries with uncertain service infrastructure.
- Technical limitation in species flexibility:Automated filleting systems require mechanical reconfiguration between flatfish and roundfish geometries, limiting throughput versatility in mixed-species processing plants.
Strategic Opportunities
- India's aquaculture processing expansion:Underpenetrated automated filleting capacity in Andhra Pradesh and Gujarat coastal zones creates equipment deployment potential as FSSAI cold-chain standards tighten.
- EU Green Deal carbon accounting:Evolving freezer energy specifications and refrigerant selection rules will advantage equipment suppliers with low-GWP cooling system portfolios.
- Food service channel centralization:Centralized kitchen prep requirements in contract catering and hotel chains are emerging as a distinct demand node for pre-portioned frozen seafood equipment.
Industry Challenges
- Robotics integration complexity:Vision-system calibration and legacy conveyor synchronization demand specialized automation engineers scarce in traditional fishing regions.
- Seafood HACCP certification timelines:FDA compliance documentation for exporters serving American retail chains extends equipment commissioning cycles by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Processing Equipment Market |
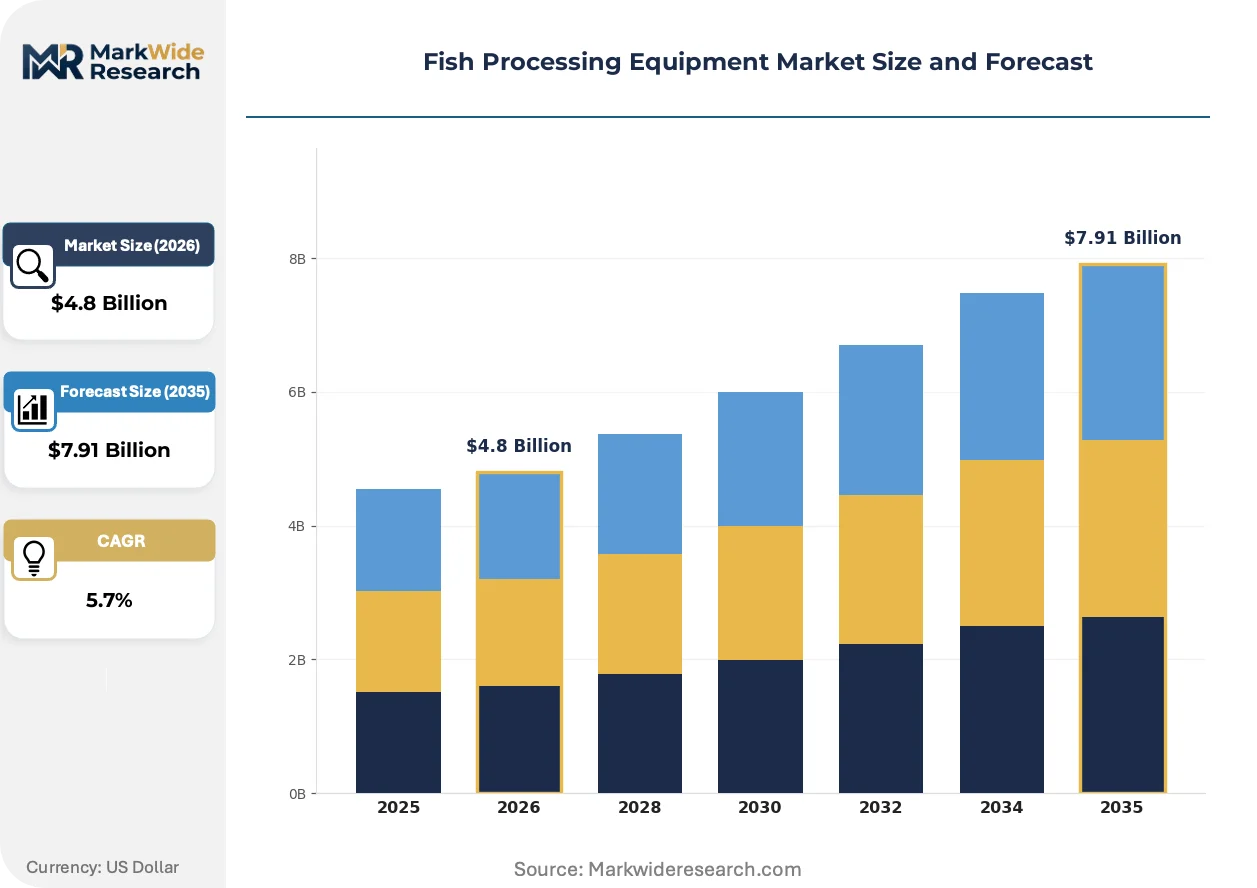
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filleting Machines, Skinning Machines, Vacuum Packers, Freezing Equipment Technology: Mechanical, Hydraulic, Pneumatic, Automated Systems Application: Processing Plants, Fish Farms, Seafood Distributors, Food Service End User: Commercial Fisheries, Retail Market, Restaurant Chains, Wholesalers |
| Companies Covered | Marel, Baader Global SE, Carsoe Seafood ApS, GEA Group AG, JBT Corporation, CTB Inc., Pisces Fish Machinery Inc., Bühler, Optimar AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Processing Equipment Market Emerging Trajectories
Processing equipment is migrating toward closed-loop energy systems and AI-driven yield optimization as regulatory pressure and labor scarcity converge. Equipment architecture is rewiring around data capture and predictive maintenance capabilities.
Hyperspectral imaging technology is migrating from laboratory quality control to inline sorting stations. Norwegian salmon processors are deploying these systems at commercial scale to detect blood spots and melanin defects before filleting. The technology is migrating from premium salmon operations toward whitefish species as sensor costs compress and algorithm training datasets expand.
EFSA's Hazard Analysis and Critical Control Points mandate is elevating stainless-steel construction standards and sanitization protocol integration across European processing equipment. Equipment manufacturers must now embed clean-in-place systems and surface roughness documentation into standard offerings. Whitefish processors in the North Sea region are absorbing the highest compliance costs while accelerating equipment replacement cycles.
After-sales service unbundling is fragmenting traditional equipment procurement models. Processing plants in Iceland and the Faroe Islands are purchasing filleting machinery without captive maintenance contracts, instead sourcing third-party technical support through specialized marine automation contractors. This pattern is most visible in remote processing locations where manufacturer service networks face travel cost and response time constraints.
Fish Processing Equipment Market Segmentation
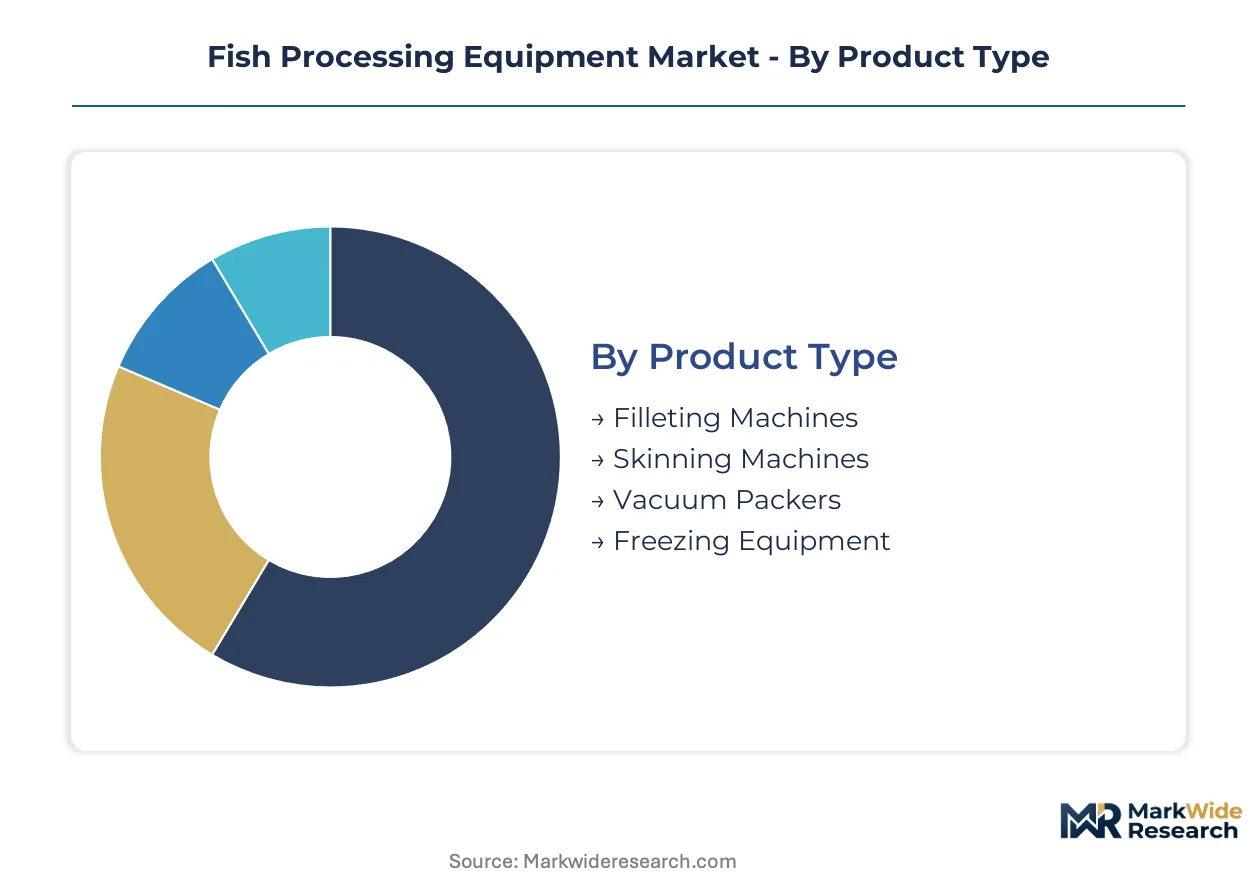
Equipment segmentation in fish processing reveals how capital allocation splits between labor substitution technologies and regulatory compliance infrastructure. Processor procurement patterns vary sharply by species handled, throughput requirements, and export destination mandates.
Product Type:
Cost tier differentiation across equipment categories tracks labor intensity and yield sensitivity in target species.
- Filleting Machines:Vision-guided robotic workcells with adaptive blade geometry handle salmon and whitefish at speeds exceeding 40 fish per minute. Norwegian processing corridors absorb the highest installed density as wage compression accelerates automation payback periods.
- Freezing Equipment:Blast freezing and plate freezing systems operate at minus 35°C to minus 40°C core temperatures, with ammonia and CO2 cascade systems displacing hydrofluorocarbon refrigerants under EU F-Gas Regulation phase-down schedules. Arctic processing clusters in Iceland and the Faroe Islands prioritize energy recovery modules to offset diesel-generated power costs.
- Skinning Machines:Drum and band configurations remove epidermal layers with minimal flesh loss for whitefish and flatfish species.
- Vacuum Packers:Thermoforming and chamber systems extend shelf life for retail-ready portions through oxygen exclusion.
Filleting machines hold installed capacity. Automated systems are rotating up the share rankings.
Technology:
Application maturity spans from proven mechanical platforms to emerging AI-driven workcells with uneven service infrastructure.
- Automated Systems:Robotic filleting workcells integrate 3D vision, force-feedback cutting, and predictive maintenance algorithms. Marel and Baader Global SE dominate deployment in high-wage Nordic economies where yield consistency justifies capital intensity.
- Mechanical:Fixed-geometry cutting and conveying systems persist in emerging processing economies with lower labor costs and simpler species mixes.
- Hydraulic:Pressure-driven actuation systems face displacement by electric servomotors in new installations.
- Pneumatic:Compressed-air platforms retain niche roles in corrosive environments where electrical ingress protection costs escalate.
Mechanical platforms hold installed capacity. Automated systems are climbing the fastest.
Application:
Customer type determines equipment specification, with export-certified plants demanding traceability-integrated architectures absent from domestic-market facilities.
- Processing Plants:High-throughput facilities in Norway, Scotland, and Alaska combine heading-gutting-filleting lines with blockchain-enabled sorting for EU and US retail compliance. EFSA and FDA HACCP mandates elevate stainless-steel grades and clean-in-place integration.
- Food Service:Centralized kitchen prep requirements in contract catering and hotel chains drive demand for pre-portioned, individually quick-frozen seafood with consistent weight specifications.
- Seafood Distributors:Repackaging and value-addition operations require flexible equipment handling mixed species batches.
- Fish Farms:Land-based aquaculture facilities integrate bleeding, chilling, and primary processing for freshness preservation.
Processing plants hold installed capacity. Food service is rotating up the share rankings.
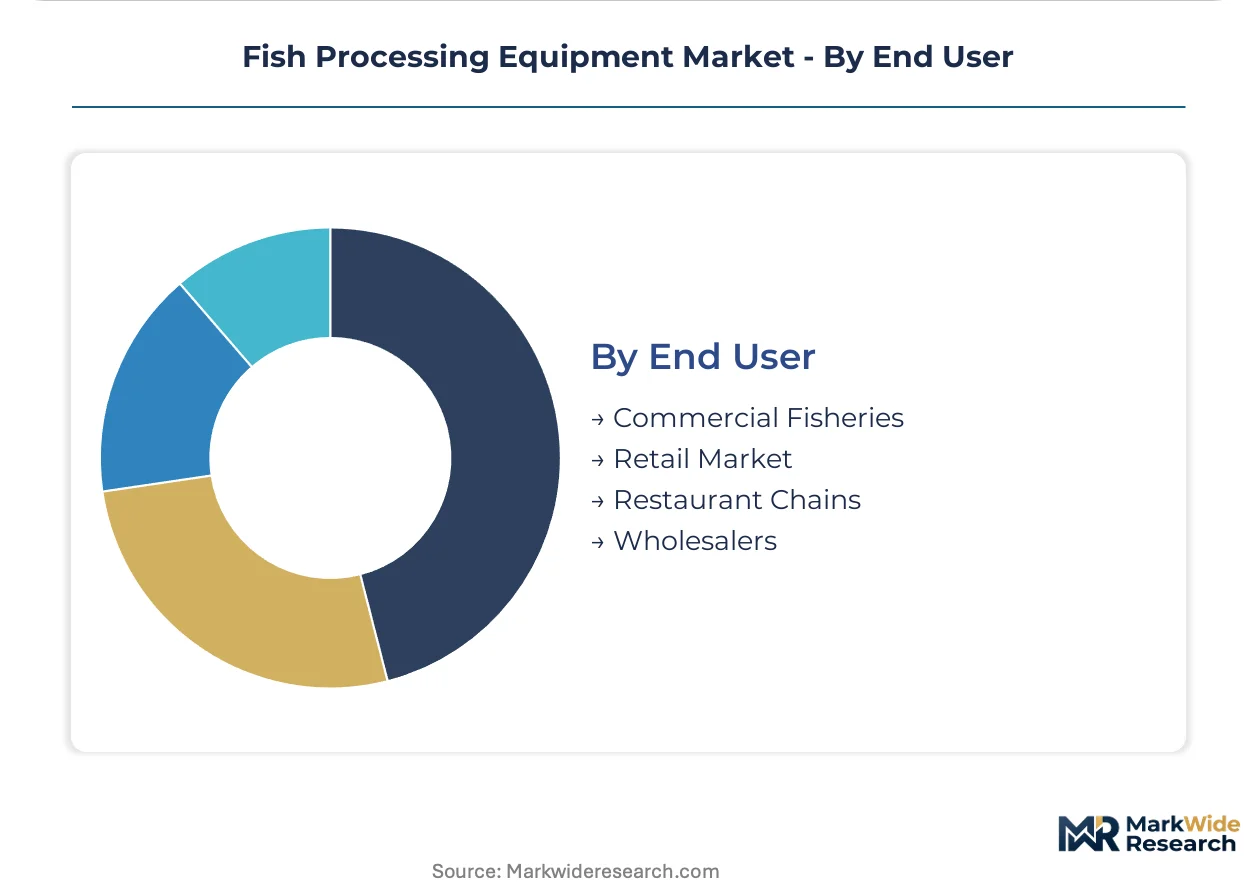
End User:
Volume concentration and margin structure vary sharply between commodity wholesalers and branded retail channels with traceability premiums.
- Commercial Fisheries:Vessel-based and shore-side operations in Alaska, Norway, and Chile prioritize compact, corrosion-resistant equipment with minimal crew training requirements.
- Retail Market:Supermarket chains specify equipment outputting tray-ready, labeled portions with shelf-life dating and origin documentation for consumer transparency mandates.
- Restaurant Chains:Centralized procurement from quick-service and casual dining groups drives demand for standardized portion weights and batter-breading compatibility.
- Wholesalers:Commodity traders prioritize throughput over yield optimization, favoring robust mechanical systems with lower capital recovery risk.
Commercial fisheries hold installed capacity. Retail market is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances across major seafood processing economies are reshaping equipment deployment patterns. Nations with processing trade surpluses absorb disproportionate capital investment in automation, while import-dependent markets prioritize cost-efficient mechanical platforms.
Norway
Salmon export volumes drive continuous upgrading of filleting and vacuum-packing lines along the western coast. The Norwegian Food Safety Authority enforces strict cold-chain documentation under EEA alignment with EFSA standards. Bergen and Ålesund anchor the seafood processing corridor where blast freezing capacity expansion signals equipment preference shifts across Nordic clusters.
United States
Alaska's pollock and cod harvests sustain shore-side processing investment despite labor cost pressures in remote locations. FDA Seafood HACCP regulation creates design requirements for equipment serving American retail and restaurant chains. Dutch Harbor and Kodiak concentrate vessel-based and land-based processing facilities where corrosion-resistant specifications dominate procurement.
India
Shrimp export growth to EU and US markets is accelerating cold-chain infrastructure investment in coastal processing zones. FSSAI cold-chain standards are tightening traceability and temperature documentation requirements for aquaculture products. Andhra Pradesh and Gujarat coastal zones present deployment potential for automated filleting capacity as compliance costs rise.
Iceland
Whitefish quota management supports steady equipment replacement cycles despite volatile catch volumes. EEA regulatory alignment mandates EFSA-compliant stainless-steel construction and clean-in-place integration. Reykjanesbær and Akureyri host processing clusters where after-sales service unbundling is fragmenting traditional equipment procurement models.
Chile
Atlantic salmon farming expansion is driving land-based processing investment from farm to primary processing. National fisheries service regulations align with EU export requirements for traceability and sanitary certification. Puerto Montt and Chiloé Island concentrate aquaculture processing facilities where bleeding, chilling, and primary processing equipment demand is rising.
Fish Processing Equipment Market Vendor Landscape
On the supply side, the industry is consolidating around specialized automation platforms and diversified food technology conglomerates. Equipment manufacturers cluster into three strategic archetypes: precision-cutting specialists, integrated robotics providers, and broad-line food technology suppliers. Competitive moves center on geographic expansion into underpenetrated aquaculture regions and technology licensing partnerships with regional fabricators.
Among Nordic specialists, Marel and Baader Global SE exemplify the integrated robotics archetype with established presence in high-wage salmon and whitefish economies. GEA Group AG and JBT Corporation represent diversified food technology conglomerates with cross-category equipment portfolios. Bühler anchors the precision-processing tier with grain and food equipment expertise extending into seafood applications. These named entities occupy positions across the automation spectrum without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Marel |
| Baader Global SE |
| Carsoe Seafood ApS |
| GEA Group AG |
| JBT Corporation |
| CTB Inc. |
| Pisces Fish Machinery Inc. |
| Bühler |
| Optimar AS |
| Others |
Supply Flow & Price Mechanics
Overcapacity in blast freezing systems across Norway's seafood corridor is compressing capital equipment margins while forcing Nordic suppliers toward extended service contracts and financing arrangements to maintain pricing power.
Pricing Analysis
Current-generation robotic filleting workcells command substantial premiums over prior-generation pneumatic platforms and emerging next-gen AI-driven adaptive systems. Pricing stratifies across premium, standard, and economy tiers based on vision-system sophistication and stainless-steel grade certification under EFSA standards. Cost compression in mechanical equipment tiers is intensifying because of Indian and Chinese fabricator entry. Wholesalers and commodity processors exhibit highest price sensitivity, while retail-certified plants prioritize yield optimization over upfront capital cost.
Supply Chain Analysis
Contract manufacturing concentration for precision cutting assemblies rests with specialized marine automation foundries in Denmark, Germany, and the Netherlands. Equipment production draws from stainless-steel mills in Finland and Sweden, servo-motor suppliers in Japan, and refrigerant component manufacturers in Germany. Single-source vulnerability in high-grade nickel alloys creates exposure to commodity price swings. Distribution runs through direct sales teams for large processing plants and regional distributors serving smaller aquaculture facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in fish processing equipment is approaching an inflection as blockchain-enabled traceability systems create interoperability requirements between sorting, filleting, and freezing subsystems.
For Market Incumbents: Harden service network density in Norway and Alaska to defend against third-party technical support fragmentation. Deepen backward integration into vision-system calibration and predictive maintenance software to capture recurring revenue streams threatened by unbundling trends in Iceland and the Faroe Islands.
For New Entrants and Emerging Players: Build out automated filleting capacity deployment in India's Andhra Pradesh and Gujarat coastal zones where FSSAI cold-chain standard enforcement is accelerating compliance-driven equipment replacement. Target shrimp processors with modular, species-flexible workcells that minimize mechanical reconfiguration downtime between flatfish and roundfish geometries.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated robotics providers with captive aftermarket service networks and software subscription attach. Long-term viability over the next decade favors precision-cutting specialists with demonstrated EU Green Deal refrigerant transition capability. Watch for inflection signals in ammonia and CO2 cascade system adoption rates across Nordic processing clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled Traceability Integration | EU Common Fisheries Policy reform mandates digital sorting equipment with origin documentation capabilities for retail compliance. |
| Refrigerant Transition Partnership | EU F-Gas Regulation phase-down schedules favor equipment suppliers with low-GWP cooling system portfolios and service infrastructure. |
| Vision-Guided Robotics Acquisition | Yield optimization algorithms and 3D imaging capabilities differentiate premium positioning in high-wage salmon processing economies. |
| Aftermarket Service Network Expansion | Remote processing locations in Iceland and Alaska face manufacturer service network constraints, creating third-party technical support opportunities. |
| Species-Flexible Workcell Development | Mixed-species processing plants require mechanical reconfiguration capabilities that current automated filleting systems lack. |
Methodological Framework
A standing panel of seafood processing plant managers, equipment procurement directors, marine automation engineers, and aftermarket service technicians provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade data, EFSA regulatory filings, SEC equipment manufacturer disclosures, and Norwegian Food Safety Authority cold-chain documentation. Bottom-up equipment shipment tracking and top-down processing capacity modeling were triangulated to establish market sizing.
Scenario-bracketing around EU Green Deal implementation pace, F-Gas Regulation enforcement intensity, and aquaculture processing automation adoption curves bounded the projection range. Segmentation modeling covered equipment type, automation technology tier, application channel, and end-user archetype across the analysis window. CAGRs were derived from installed base replacement cycles, greenfield capacity announcements, and regulatory compliance-driven upgrade timelines specific to seafood HACCP mandates.
Stress conditions across nickel price volatility, refrigerant supply disruption, and labor cost compression in Nordic economies were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume continued EEA regulatory alignment and FDA Seafood HACCP enforcement stability. Quarterly review of EU F-Gas Regulation phase-down schedules and Indian FSSAI cold-chain standard adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market