
 Fish Cutting Machine Market | 2026-2036
Fish Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Cutting Machine Market Foresight
A capital-intensity divergence between automated filleting specialists and manual-cutter assemblers is reorganizing competitive tiers in fish processing equipment. Marel leverages integrated software-hardware platforms to anchor premium positioning in Nordic salmon operations. Baader sustains multi-decade relationships with European whitefish processors through proprietary blade-path engineering. AGK Kronawitter competes on compact footprint designs for mid-scale foodservice providers lacking plant-floor expansion capacity.
A fish cutting machine is an electromechanical or hydraulic device engineered to section, fillet, skin, or portion raw fish with blade tolerances typically measured in millimeters, employing stainless-steel contact surfaces to satisfy HACCP sanitation protocols. Its primary commercial purpose is to replace manual labor in high-throughput seafood processing while yield consistency and worker safety margins. Automatic filleting machines dominate value capture in large-scale fish processing plants, where throughput rates justify capital deployment against labor arbitrage. Electric-drive technology leads installed bases across frozen fish production lines, though pneumatic systems retain share in wet-processing environments where moisture exposure degrades electronic components. Seafood packaging applications represent the fastest-growing demand segment, driven by pre-portioned retail formats requiring uniform cut weights.
CE marking under the EU Machinery Directive and EFSA food-contact material regulations constrain market access for non-compliant Asian manufacturers exporting into European seafood processing chains. The US FDA's Hazard Analysis and Critical Control Points framework and OSHA machine-guarding standards shape equipment specification sheets for North American buyers prioritizing liability reduction. China's SAMR national food safety standards and GB machinery certification requirements create parallel compliance tracks for domestic versus export-oriented equipment builders. Stakeholders must monitor divergence between regional electrical safety codes and blade-guarding specifications when configuring global product platforms.
Market Dynamics
Automated filleting systems are compressing labor arbitrage advantages that once justified manual processing in mid-scale seafood operations, forcing equipment vendors to rebundle software analytics and blade-path optimization as core value propositions.
Growth Catalysts
- EFSA Hygiene Directives:CE marking requirements for food-contact machinery are accelerating replacement cycles in European processing plants, particularly in Norway's coastal aquaculture clusters where compliance audits have intensified.
- Pre-portioned retail formats:Supermarket chains and meal-kit services are specifying cut-weight uniformity that only automated portioning systems can deliver at throughput scale.
- Electric-drive technology:Frozen fish production lines are migrating from pneumatic to electric drive systems to reduce moisture-related component degradation and maintenance downtime.
Market Restraints
- Stainless steel input volatility:Grade 316L stainless steel price swings constrain margin predictability for equipment fabricators dependent on HACCP-compliant contact surfaces.
- Blade-path engineering concentration:Proprietary cutting algorithms remain concentrated among Nordic specialists, limiting second-source procurement options for processors seeking competitive quotes.
- Wet-processing environment limitations:Pneumatic systems retain defensive share where electronic component sealing cannot achieve IP69K ratings required for high-pressure washdown protocols.
Strategic Opportunities
- Mid-scale foodservice penetration:Compact footprint designs are opening procurement access to commercial kitchens lacking plant-floor expansion capacity in urban European markets.
- Software-hardware convergence:Integrated yield-optimization platforms combining machine vision with blade-path adjustment are creating premium pricing tiers distinct from commodity filleting equipment.
- China's SAMR certification pathway:Dual-track compliance strategies for domestic GB standards versus export-oriented CE marking are enabling modular platform architectures that reduce SKU proliferation.
Industry Challenges
- Mechatronics technician scarcity:Seafood processing regions face recruitment gaps for technicians capable of calibrating servo-driven blade actuators and troubleshooting PLC-integrated control systems.
- Legacy system integration friction:Brownfield installations require custom mechanical interfacing with existing conveying and ice-handling infrastructure, extending commissioning timelines.
- CE marking documentation burden:EU Machinery Directive technical file preparation consumes 6-12 months for novel blade-guarding configurations, delaying market entry for innovative safety designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Cutting Machine Market |
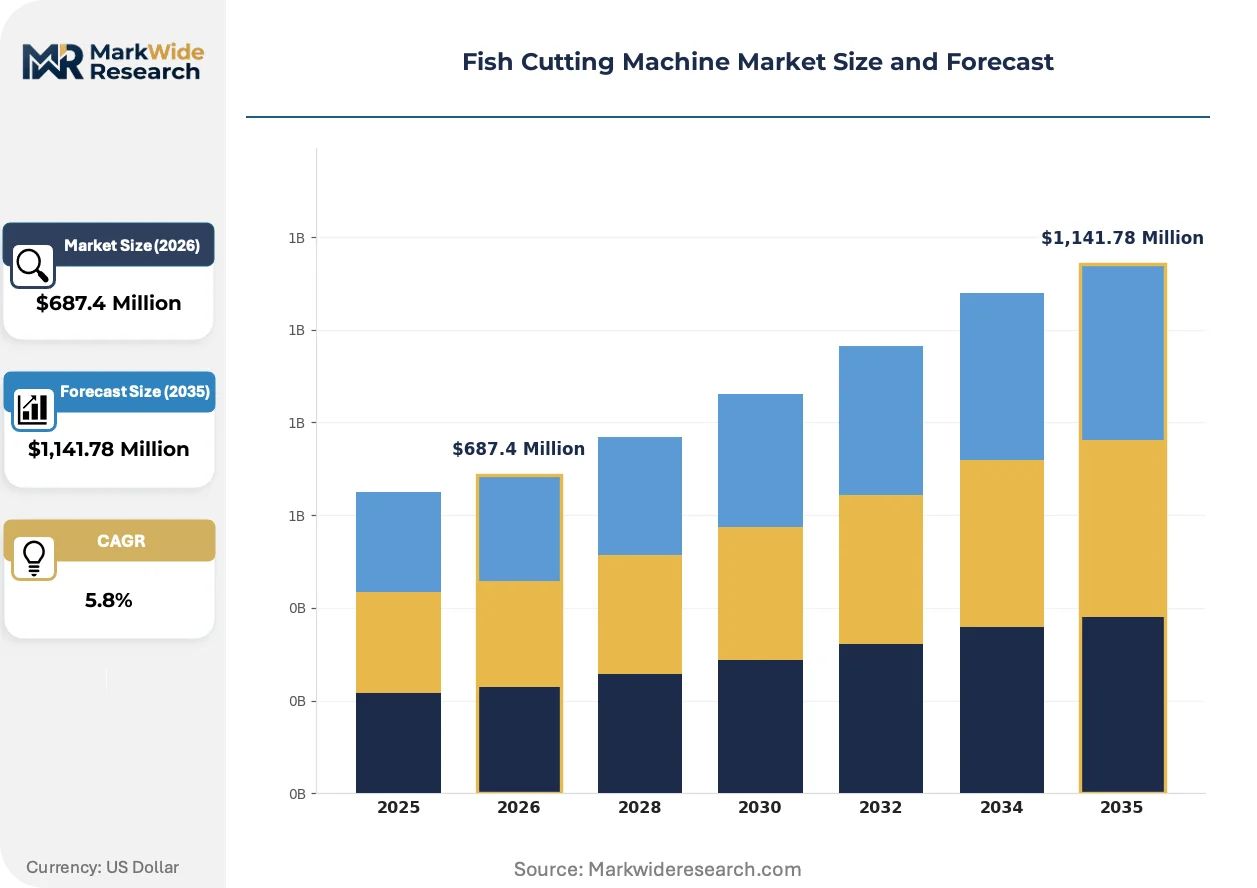
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,141.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Fish Cutter, Semi-Automatic Cutter, Manual Cutter, Filleting Machine, Skinning Machine Technology: Hydraulic, Pneumatic, Electric, Blade, Laser Application: Fish Processing Plants, Seafood Packaging, Frozen Fish Production, Fish Traders, Foodservice Providers End User: Seafood Processors, Aquaculture Facilities, Commercial Kitchens, Cold Storage Operators |
| Companies Covered | Marel, Baader, AGK Kronawitter, GEA Group, JBT Corporation, Bühler, Carnitec, Kroma AS, YUKE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Cutting Machine Market Shifts & Advancements
Machine vision-guided blade adjustment is compressing yield variance tolerances that previously required manual operator intervention, while regulatory pressure on traceability is embedding data-capture capabilities as standard rather than optional equipment features.
Vision-guided portioning systems are displacing operator-dependent cutting consistency in high-throughput salmon processing lines. Nordic whitefish processors are deploying these systems at replacement cycle acceleration to meet retail chain specifications for gram-weight precision. The technology is displacing premium pricing power from mechanical engineering toward software analytics and yield-optimization algorithms.
EFSA food-contact material regulations are tightening migration testing protocols for polymer components in blade housings and conveyor belts. Equipment vendors must now submit expanded technical documentation demonstrating compliance with updated specific migration limits before CE marking authorization. European seafood processors are responding by consolidating procurement around vendors with established regulatory affairs capabilities, marginalizing smaller fabricators lacking dedicated compliance teams.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles into separate subscription tiers. Large-scale processors are negotiating predictive maintenance contracts distinct from capital equipment purchases, while mid-scale buyers opt for per-incident technical support. This shift is most pronounced in Germany and the Netherlands, where processor finance departments favor operational expenditure treatment over capital depreciation schedules.
Fish Cutting Machine Market Segmentation
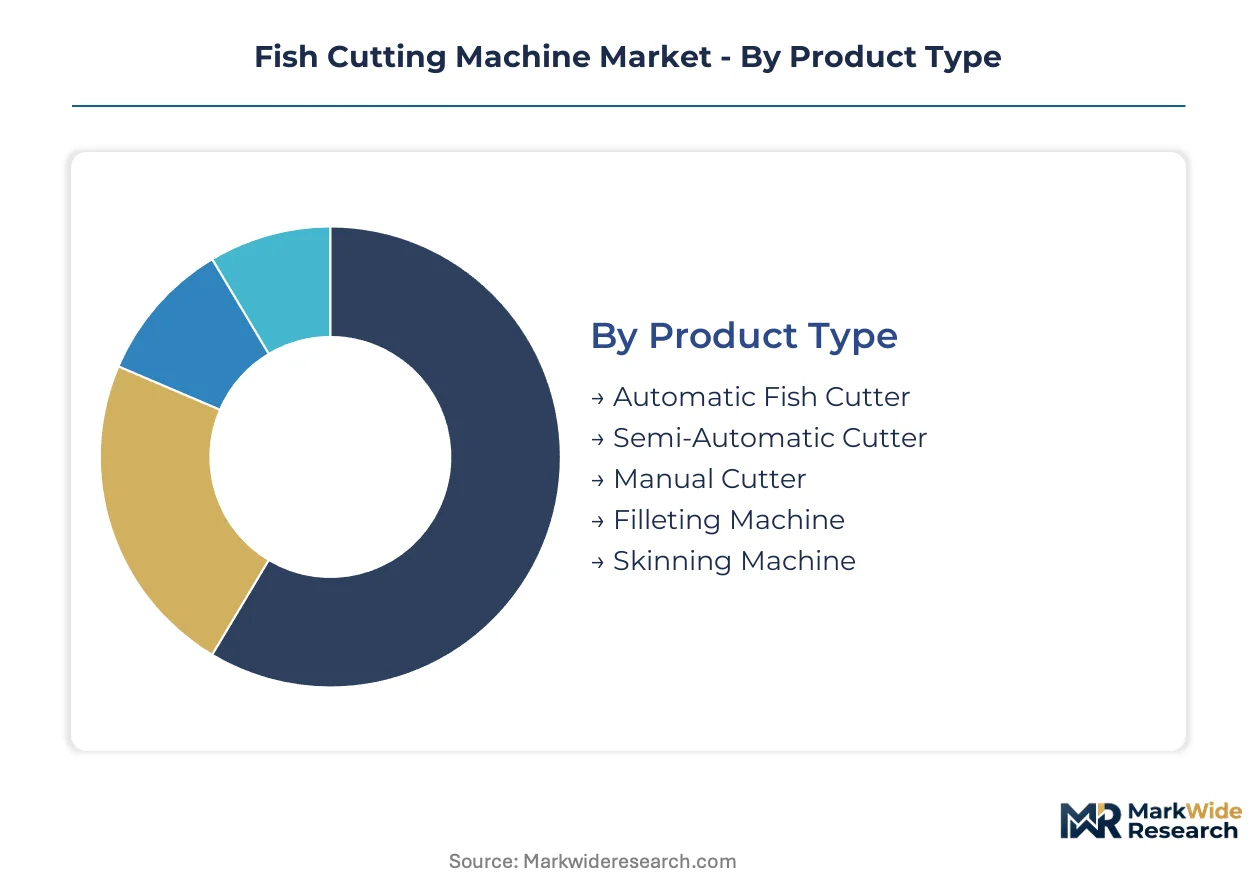
Equipment specification diverges sharply across processing scales, with capital intensity and compliance requirements fragmenting procurement patterns. Segmentation reveals where automation premiums command pricing power versus commodity hardware competition.
Product Type:
Margins concentrate in integrated filleting systems where blade-path software creates switching costs, while manual cutters compete on price in labor-abundant markets.
- Automatic Fish Cutter:Servo-driven blade actuation with programmable portion weights dominates high-throughput salmon processing in Norway's coastal clusters. EFSA hygiene directive compliance costs favor vendors with established CE marking technical files.
- Filleting Machine:Multi-axis cutting heads with vision-guided yield optimization anchor premium positioning in Nordic whitefish operations. Retail chain contracts for gram-weight precision are accelerating replacement cycles beyond standard depreciation schedules.
- Semi-Automatic Cutter:Hybrid designs blending operator oversight with mechanized blade feed serve mid-scale processors in Germany's Baltic seafood corridor.
- Manual Cutter:Stainless-steel frame assemblies with interchangeable blade sets retain share in artisanal processing and emerging market entry segments.
- Skinning Machine:Drum-style or band-skinning configurations with tension-calibrated rollers address species-specific hide thickness variations in North Sea flatfish operations.
The dominant share belongs to automatic fish cutters, while filleting machines are closing the gap fastest.
Technology:
Drive system selection hinges on moisture exposure severity and maintenance technician availability across processing environments.
- Electric:Brushless servo motors with IP69K-rated enclosures are displacing pneumatic alternatives in frozen fish production lines where component longevity outweighs initial cost premiums. Norway's processing plants lead this migration.
- Pneumatic:Compressed-air actuation retains defensive positioning in wet-processing environments where high-pressure washdown protocols degrade electronic sealing integrity. Baltic region whitefish operations maintain installed bases here.
- Hydraulic:High-torque fluid power systems serve heavy-duty heading and gutting applications in industrial-scale Atlantic cod processing.
- Blade:Mechanical cutting edges with adjustable blade-path geometry remain the baseline technology across all drive configurations.
- Laser:Experimental CO2 and fiber laser cutting trials are progressing in research consortiums evaluating yield preservation in delicate flesh species.
Electric systems hold the installed base majority, though pneumatic technology defends share in washdown-intensive settings.
Application:
End-use specifications diverge between weight-precision retail formats and throughput-maximizing commodity processing.
- Seafood Packaging:Pre-portioned retail formats with vacuum-sealed tray packs require gram-scale uniformity that machine vision-guided systems deliver. German supermarket chains are specifying this equipment tier in supplier audits.
- Fish Processing Plants:Integrated lines with ice-handling and conveying infrastructure demand custom mechanical interfacing, extending commissioning timelines for brownfield installations.
- Frozen Fish Production:Blast-freeze compatibility and cryogenic-temperature material ratings constrain component selection in Baltic region export-oriented facilities.
- Fish Traders:Mobile or semi-permanent installations with rapid reconfiguration capability serve auction-hall and harbor-side processing in Netherlands' Scheveningen cluster.
- Foodservice Providers:Compact footprint designs with reduced noise emissions penetrate urban commercial kitchens lacking plant-floor expansion capacity in Copenhagen and Hamburg.
Seafood packaging commands the steepest expansion trajectory, while fish processing plants retain volume concentration.
End User:
Procurement authority sits with technical operations teams in large processors versus finance departments in mid-scale facilities.
- Seafood Processors:Integrated operations with species-dedicated lines prioritize yield-optimization software and predictive maintenance subscriptions. Norway's SalMar and Lerøy-tier operations set specification standards.
- Commercial Kitchens:Urban foodservice providers in Stockholm and Oslo markets select compact electric units with operational expenditure treatment favoring leasing over capital depreciation.
- Aquaculture Facilities:Onshore processing co-located with farming operations in Scotland's Shetland Islands require equipment matched to specific harvest-size distributions.
- Cold Storage Operators:Third-party logistics providers with multi-species handling needs specify rapid blade-path reconfiguration and sanitation protocols between product changeovers.
Seafood processors dominate procurement value, while commercial kitchens are expanding most quickly as urban foodservice automation penetrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian processors deploy electric-drive filleting systems for salmon portioning, while Baltic whitefish operations retain pneumatic infrastructure due to washdown intensity. This consumption-mix differential separates high-automation Nordic clusters from cost-sensitive Eastern European manual-cutter markets.
Norway
Coastal aquaculture clusters in Bergen and Ålesund drive automated filleting procurement for Atlantic salmon operations. EFSA hygiene directives and CE marking requirements accelerate replacement cycles as compliance audits intensify. SalMar and Lerøy-tier processors anchor specification standards for yield-optimization software.
Germany
Baltic seafood corridor processors in Lübeck and Rostock specify hybrid semi-automatic cutters balancing throughput with labor retention. EU Machinery Directive technical file preparation constrains vendor selection to established regulatory affairs teams. Supermarket chains in Hamburg enforce gram-weight precision standards in supplier audits.
China
Export-oriented equipment builders in Shandong and Zhejiang provinces navigate dual-track compliance for domestic GB standards versus CE marking. SAMR national food safety standards and machinery certification requirements create modular platform demand. Yangtze River Delta processing hubs concentrate procurement for frozen fish production lines.
United States
Alaska pollock processors and Pacific Northwest salmon facilities specify equipment under FDA Hazard Analysis and Critical Control Points frameworks. OSHA machine-guarding standards shape specification sheets prioritizing liability reduction. Seattle-area technical operations teams dominate procurement authority for integrated filleting systems.
Netherlands
Scheveningen harbor-side fish traders demand mobile installations with rapid reconfiguration capability. Randstad urban foodservice providers in Amsterdam and Rotterdam select compact electric units with operational expenditure treatment favoring leasing. Third-party logistics providers specify rapid blade-path reconfiguration between multi-species changeovers.
Fish Cutting Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium positioning anchored in software-hardware convergence versus commodity hardware competition. The structure concentrates blade-path engineering expertise among Nordic-origin fabricators while Asian manufacturers compete on compact footprint designs for mid-scale foodservice penetration. Three archetypes dominate: integrated platform vendors with predictive maintenance subscriptions, mechanical engineering specialists with multi-decade processor relationships, and compact-system fabricators targeting urban kitchen constraints. Competitive moves center on M&A for regulatory affairs capabilities and capacity expansion in CE-marking technical file preparation.
Within the integrated platform tier, Marel and Baader exemplify contrasting geographic anchoring strategies, with the former representing software-analytics premium positioning and the latter embodying proprietary blade-path engineering concentration. AGK Kronawitter occupies a position among compact-footprint specialists serving mid-scale European foodservice providers lacking plant-floor expansion capacity. These three fabricators collectively illustrate how competitive positioning separates yield-optimization algorithm vendors from mechanical-hardware commodity suppliers.
| Leading Market Players |
|---|
| Marel |
| Baader |
| AGK Kronawitter |
| GEA Group |
| JBT Corporation |
| Bühler |
| Carnitec |
| Kroma AS |
| YUKE |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Norwegian salmon processors and equipment vendors lock in blade-path engineering access while stabilizing input cost visibility against stainless steel price swings. These contracts bundle predictive maintenance subscriptions with capital deployment, converting volatile service margins into recurring revenue streams.
Pricing Analysis
Long-term offtake structures dominate procurement in Norway's coastal clusters, with SalMar-tier processors negotiating multi-year blade-path engineering access bundled with yield-optimization software licenses. Price differentiation rests on CE marking certification grade and after-sales service tier, with premium vendors commanding spreads based on regulatory affairs capabilities. Cost compression in mid-scale foodservice equipment is intensifying because Asian manufacturers compete on compact footprint designs without integrated analytics. Commercial kitchens in urban European markets exhibit highest price sensitivity, while integrated seafood processors prioritize yield consistency over unit economics.
Supply Chain Analysis
Inbound logistics costs from Asian component hubs through Rotterdam port congestion constrain margin predictability for European equipment fabricators dependent on servo motor and machine vision sensor deliveries. Supply concentration centers on Germany for precision blade engineering, China for stainless steel fabrication, and Norway for software-hardware integration platforms. Raw material dependencies include Grade 316L stainless steel, brushless servo motors, and polymer conveyor belt compounds. Single-source vulnerability in proprietary blade-path algorithms creates procurement risk. Distribution runs through direct vendor relationships with large processors and equipment distributors serving mid-scale foodservice.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine vision-guided yield optimization is compressing manual operator roles while EFSA hygiene directives accelerate replacement cycles, creating a high-growth disruption window for automated filleting systems.
For Market Incumbents: Compound software-hardware convergence advantages by deepening predictive maintenance subscription attach rates and expanding CE marking technical file preparation capacity. Defend against Asian compact-system entrants by anchoring premium positioning in Norway's salmon processing clusters where blade-path engineering concentration creates switching costs. Prioritize backward integration into servo motor calibration capabilities to reduce component lead time exposure. For New Entrants and Emerging Players: Differentiate on modular platform architectures that enable dual-track compliance for China's SAMR GB standards and European CE marking without SKU proliferation. Target Germany's Baltic seafood corridor mid-scale processors with hybrid semi-automatic designs balancing throughput with labor retention. Pursue direct sales relationships with urban commercial kitchens in Copenhagen and Hamburg seeking operational expenditure treatment. For Investors and Strategic Acquirers: Regulatory affairs boutiques with established EFSA food-contact material documentation capabilities represent priority acquisition targets as compliance audit intensity accelerates. Long-term viability hinges on software analytics ownership rather than mechanical hardware fabrication. Watch for machine vision algorithm standardization as the inflection signal indicating commoditization pressure on blade-path engineering premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Converts capital equipment sales into recurring revenue with Norwegian salmon processors. |
| CE Marking Technical File Expansion | Accelerates market entry authorization for novel blade-guarding safety configurations. |
| Machine Vision Algorithm Acquisition | Secures yield-optimization software capabilities distinct from commodity hardware. |
| Compact Footprint Product Line Extension | Penetrates urban commercial kitchen segments lacking plant-floor expansion capacity. |
| Dual-Track Compliance Modular Platform | Reduces SKU proliferation for export-oriented equipment builders serving China and Europe. |
Research Methodology
The analysis maps automatic filleting systems, semi-automatic cutters, and skinning machine sub-sectors, each validated through plant engineers, seafood processor procurement leads, and aftermarket service heads. Primary interviews with maintenance directors at Norway's SalMar-tier operations and commercial kitchen operators in Hamburg and Copenhagen combined with secondary validation from EFSA hygiene directive documentation, EU Machinery Directive technical files, and SEC filings of listed equipment vendors. Bottom-up equipment shipment tracking and top-down aquaculture output modeling provided triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology type, application segment, and end-user procurement authority dimensions throughout the forecast period. CAGRs were derived from equipment replacement cycle acceleration patterns and aquaculture capacity expansion trajectories. Forecast inputs incorporated EFSA compliance audit intensity projections and electric-drive technology migration rates from pneumatic systems.
The analysis sits within stated boundaries; outcomes outside sustained EFSA hygiene directive enforcement or Grade 316L stainless steel price stability would require recalibration. Forecasts reflect assumptions regarding mechatronics technician availability and legacy system integration friction timelines. Specific risk factors including CE marking documentation delays and wet-processing environment IP69K sealing failures could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Food Ingredients Sterilization Market