
 Cook Processor Market | 2026-2036
Cook Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Cook Processor Market Insights
Chinese contract manufacturers is pivoting toward automated assembly lines for induction heating modules, reshaping cost structures for Western brands. Vorwerk leverages direct-to-consumer channel control to sustain premium positioning in European households. De'Longhi Group anchors its competitiveness through specialized R&D on smart cooking algorithms. Robert Bosch GmbH competes by extending its appliance ecosystem integration across European retail networks.
A cook processor combines thermal cooking, mechanical food processing, and programmable control logic within a single countertop appliance, typically integrating heating elements rated between 800 and 1500 watts with stainless steel or ceramic cooking bowls and multi-blade assemblies for chopping, kneading, or emulsifying. Its primary commercial purpose is to consolidate preparation and cooking stages, reducing labor time and equipment footprint in both domestic and professional kitchens. Multipurpose cookers dominate value contribution as households trade multiple single-function devices for consolidated platforms, while smart cooking technology represents the fastest-expanding margin pool as connectivity and recipe automation command price premiums. Induction heating occupies a mature but stable position in premium tiers where energy precision differentiates professional-grade units from standard convection models.
The EU Ecodesign Directive and CE marking requirements shape product development cycles by mandating minimum energy efficiency thresholds and electrical safety certifications for appliances sold across member states. The US FDA and FCC respectively govern food-contact material safety and wireless connectivity protocols in smart-enabled units, creating dual compliance tracks for manufacturers serving both markets. Stakeholders must monitor evolving interoperability standards between smart cooking platforms and third-party recipe services, as ecosystem lock-in risks becoming a decisive purchase factor.
Market Dynamics
Restaurants across Germany, France, and Italy are consolidating kitchen equipment footprints to combat labor shortages and real estate costs, creating structural pull toward multifunctional thermal appliances that displace standalone mixers, steamers, and sous-vide baths.
Growth Catalysts
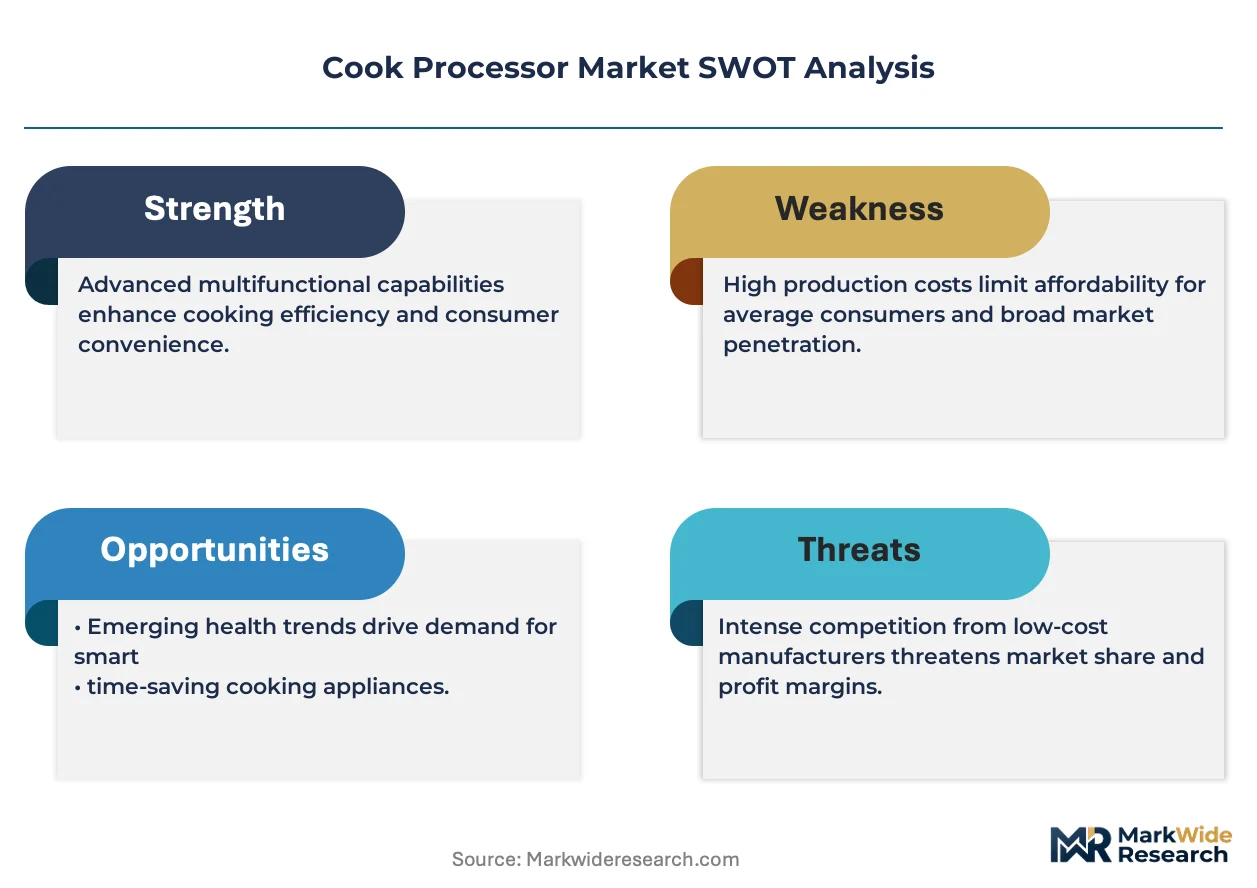
- EU Ecodesign Directive:Tightening energy efficiency thresholds for household appliances are forcing manufacturers to redesign heating modules, creating upgrade cycles across German and French retail channels.
- Induction module automation:Chinese contract manufacturers are deploying robotic assembly for precision-wound copper coils, compressing production costs for Western OEMs sourcing premium heating subsystems.
- Commercial kitchen labor economics:Full-service restaurants in Milan, Barcelona, and Amsterdam are replacing three to four single-purpose stations with consolidated cook processors to reduce headcount and training overhead.
Market Restraints
- Ceramic bowl supply concentration:German and Austrian specialty ceramics suppliers control thin-walled alumina-silicate production for premium-tier cooking vessels, creating input bottlenecks during demand spikes.
- Smart connectivity certification friction:FCC Part 15 and CE RED testing timelines for Wi-Fi and Bluetooth-enabled units extend European and North American launch windows by four to six months.
- Countertop real estate competition:Air fryers and combi-microwave ovens occupy similar price-positioning and electrical-loading profiles, fragmenting household upgrade budgets.
Strategic Opportunities
- India BIS appliance standards:New mandatory safety and energy labeling requirements for kitchen equipment create first-mover positioning for brands establishing localized assembly and service networks.
- Cloud recipe platform convergence:Integration between cook processor firmware and third-party meal-planning applications opens recurring revenue streams through subscription content partnerships.
- Professional catering channel expansion:Institutional foodservice operators in Saudi Arabia and UAE are replacing traditional commissary equipment with programmable thermal processors to standardize output across outlet networks.
Industry Challenges
- Multi-physics simulation talent scarcity:Thermal-fluid and electromagnetic modeling expertise for optimizing induction field distribution and blade flow patterns concentrates in Munich, Stuttgart, and Zurich engineering clusters.
- Legacy appliance ecosystem lock-in:Proprietary blade interfaces and bowl geometries from established brands complicate third-party accessory development and consumer switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cook Processor Market |
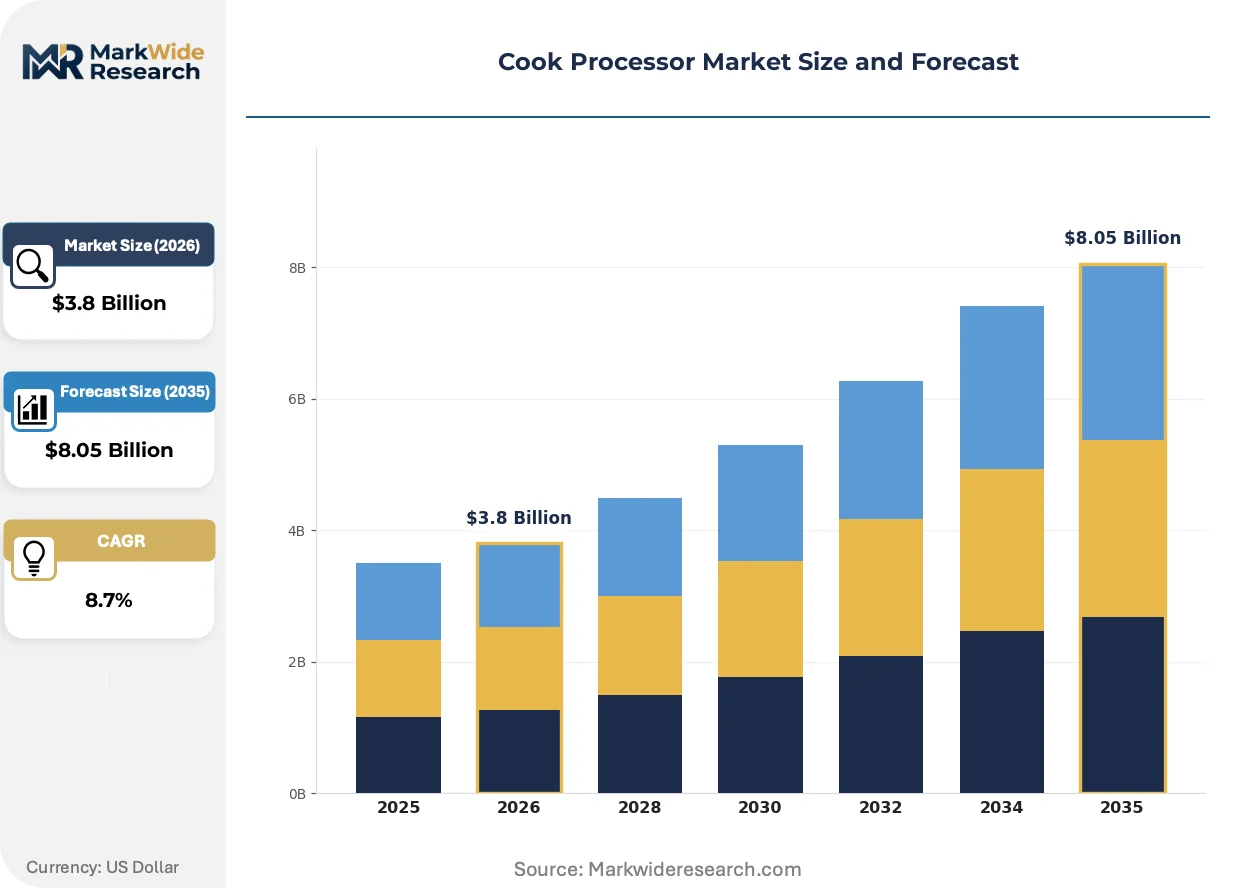
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multipurpose Cookers, Food Processors, Slow Cookers, Blenders End User: Households, Restaurants, Catering Services, Food Delivery Services Technology: Smart Cooking, Induction Heating, Convection Cooking, Pressure Cooking Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Vorwerk, De'Longhi Group, Whirlpool Corporation, Groupe SEB, Breville Group Limited, SharkNinja Operating LLC, Robert Bosch GmbH, Koninklijke Philips N.V., Magimix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cook Processor Market Trends and Innovations
Sensor fusion and adaptive control algorithms are displacing fixed-recipe programming across mid-tier and premium cook processors, enabling real-time adjustment of temperature gradients and blade speeds based on food load detection.
Precision temperature sensing arrays are integrating infrared and thermocouple feedback loops to maintain sub-one-degree Celsius stability during sous-vide and emulsification cycles. Professional kitchens in Copenhagen and Stockholm are adopting these modules for sauce consistency. The technology is integrating recipe reproducibility guarantees into service contracts between equipment lessors and restaurant groups.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in adjacent foodservice cooling equipment, indirectly tightening thermal efficiency expectations for cook processors marketed as complete kitchen solutions. Manufacturers serving German and Austrian markets are accelerating induction-only product line rationalization to preempt efficiency benchmarking disadvantages. CE marking bodies are expanding scope to cover networked appliance cybersecurity, adding compliance layers for smart-enabled units.
Direct-to-consumer subscription models are displacing traditional retail attachment selling for high-consideration kitchen appliances. Vorwerk's Thermomix advisor network in France and Spain demonstrates the model's viability. Independent kitchen specialists in Turin and Lyon are responding with experiential showroom formats and white-glove installation services to defend margin capture.
Cook Processor Market Segmentation
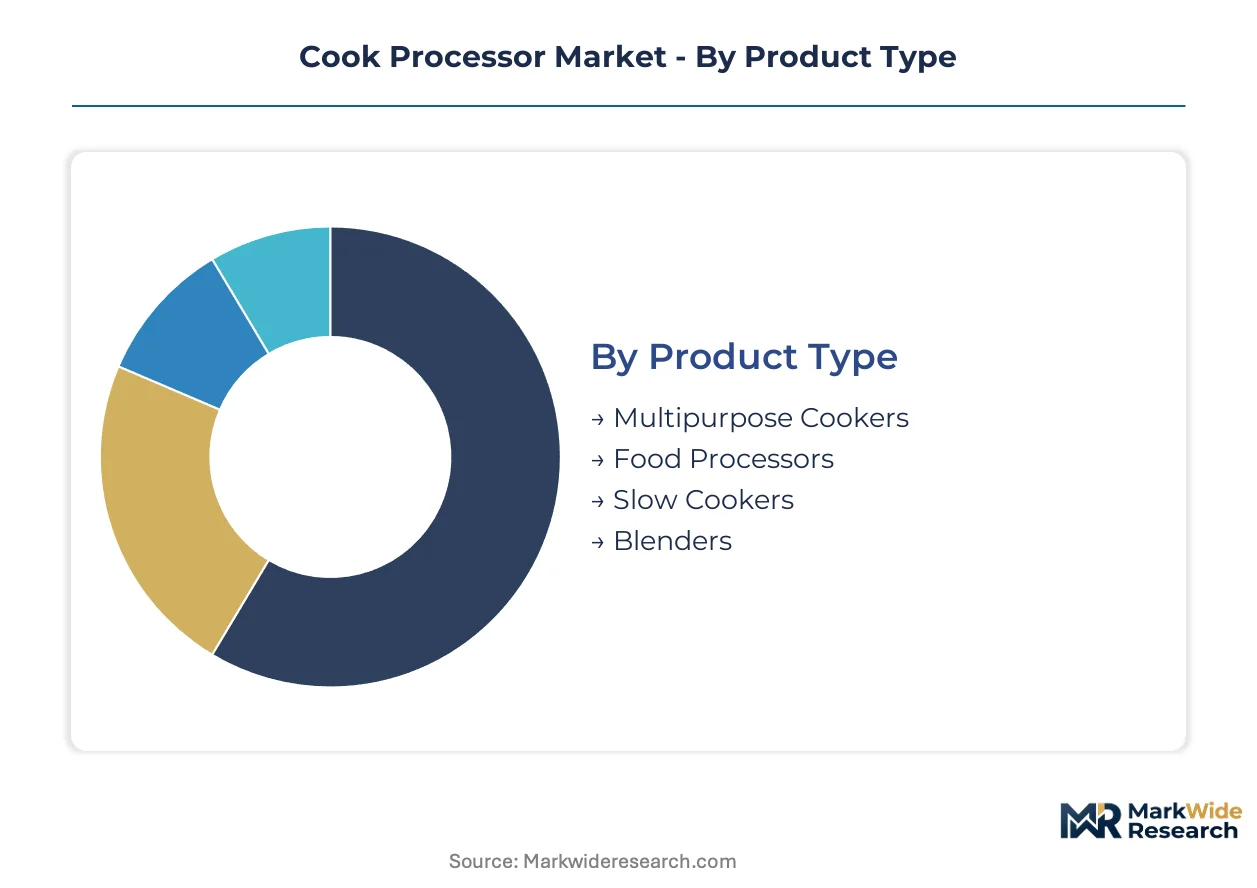
Cook processor manufacturers configure product portfolios around thermal performance tiers, end-use intensity, and connectivity requirements. Segmentation discipline determines pricing architecture and channel investment priorities across fragmented demand pockets.
Product Type:
Buyers in this category differentiate by consolidation appetite versus single-function loyalty, with equipment footprint and labor substitution value driving selection.
- Multipurpose Cookers:These units integrate thermal cooking, mechanical processing, and programmable control within 800-1500 watt platforms. German and French households dominate procurement as kitchen space constraints intensify in urban apartments. The EU Ecodesign Directive accelerates replacement cycles for legacy single-purpose equipment.
- Food Processors:Dedicated chopping, slicing, and emulsifying assemblies without heating elements serve preparation-intensive commercial kitchens. Italian restaurants in Milan and Turin concentrate demand where sauce consistency requirements exceed multipurpose unit precision. Labor cost pressures in Barcelona full-service dining reinforce adoption.
- Slow Cookers:Low-wattage ceramic vessels target price-sensitive household segments with extended thermal cycles.
- Blenders:High-speed blade assemblies for beverage and puree applications occupy adjacent countertop positioning.
Volume sits with Multipurpose Cookers; growth tilts toward Food Processors in commercial channels.
End User:
Application intensity separates buyers here, with cycle frequency, output consistency requirements, and total cost of ownership calculations determining specification levels.
- Households:Domestic purchasers prioritize countertop footprint reduction and recipe automation over throughput. Vorwerk's direct-to-consumer advisor networks in France and Spain demonstrate channel control value for this segment. FCC Part 15 and CE RED certification timelines delay smart-enabled unit launches by four to six months.
- Restaurants:Full-service operators across Germany, France, and Italy consolidate three to four single-purpose stations into programmable thermal processors. Amsterdam and Copenhagen kitchens adopt precision temperature sensing arrays for sauce reproducibility guarantees. Labor shortage economics in Milan and Barcelona accelerate equipment rationalization.
- Catering Services:Institutional foodservice operators in Saudi Arabia and UAE deploy programmable units for output standardization across outlet networks.
- Food Delivery Services:Ghost kitchen operators prioritize throughput consistency and minimal training overhead for high-turnover staff.
Restaurants command the steepest expansion trajectory; households retain volume dominance through replacement cycles.
Technology:
Performance precision and energy efficiency credentials separate buyers, with professional kitchens paying premiums for thermal stability and domestic users valuing connectivity convenience.
- Smart Cooking:Sensor fusion algorithms enable real-time temperature and blade speed adjustment based on food load detection. De'Longhi Group's specialized R&D on cooking algorithms anchors European competitiveness. Cloud recipe platform convergence opens recurring revenue through third-party meal-planning integration.
- Induction Heating:Precision-wound copper coils deliver sub-one-degree Celsius stability for sous-vide and emulsification. Chinese contract manufacturers' automated assembly lines compress production costs for Western OEMs sourcing premium heating subsystems.
- Convection Cooking:Fan-assisted thermal distribution serves mid-tier price positioning where energy efficiency thresholds satisfy EU Ecodesign requirements without induction premiums.
- Pressure Cooking:Sealed-vessel high-pressure cycles reduce cooking duration for time-constrained household segments.
Induction Heating retains volume leadership in premium tiers; Smart Cooking gains share fastest as connectivity commands price premiums.
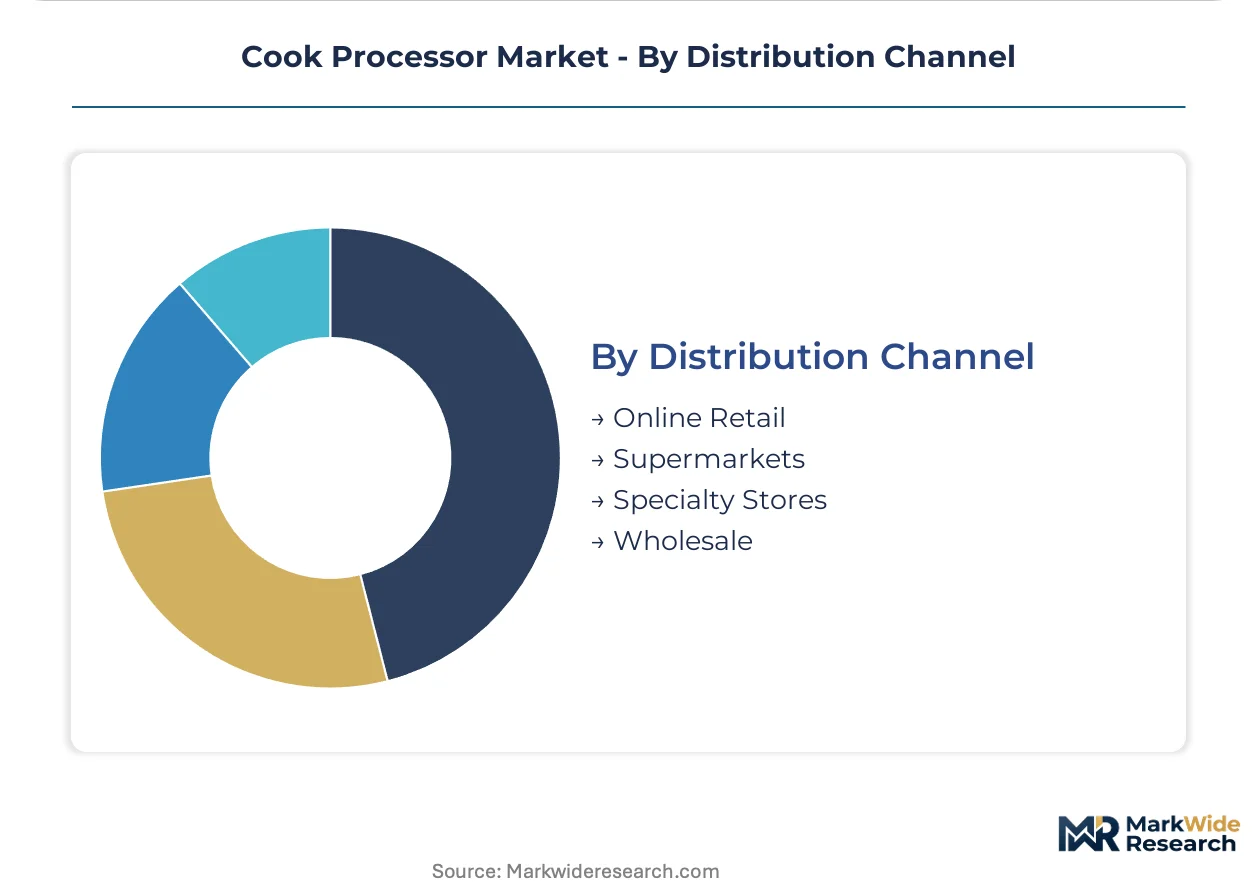
Distribution Channel:
Customer acquisition cost and service attachment requirements differentiate channel economics, with high-consideration purchases shifting toward experiential formats.
- Online Retail:Direct-to-consumer subscription models displace traditional retail attachment for premium appliances. Vorwerk's Thermomix advisor network demonstrates viability in France and Spain. Cybersecurity compliance layers from expanded CE marking scope add complexity for smart-enabled units.
- Supermarkets:Mass-market volume concentrates here for entry-level multipurpose cookers and slow cookers with minimal service requirements.
- Specialty Stores:Independent kitchen specialists in Turin and Lyon deploy experiential showroom formats and white-glove installation to defend margin capture against direct-to-consumer encroachment.
- Wholesale:Commercial catering procurement in Saudi Arabia and UAE routes through institutional foodservice distributors for outlet network standardization.
Online Retail captures the steepest growth curve; Specialty Stores retain premium-tier volume through service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision ceramics suppliers anchor thin-walled alumina-silicate production for premium cooking vessels, creating input dependencies that ripple through Western European and North American assembly networks. This feedstock concentration shapes regional manufacturing strategies and compliance pathways across three continents.
Germany
Urban apartment kitchen space constraints in Berlin and Munich intensify demand for consolidated 800-1500 watt multipurpose platforms. The EU Ecodesign Directive mandates minimum energy efficiency thresholds that accelerate replacement cycles for legacy single-purpose equipment. Stuttgart engineering clusters concentrate thermal-fluid modeling expertise for optimizing induction field distribution.
France
Direct-to-consumer advisor networks in Paris and Lyon demonstrate channel control viability for high-consideration appliance purchases. CE marking requirements for electrical safety certifications shape product development timelines for smart-enabled units. Independent kitchen specialists in Lyon deploy experiential showroom formats to defend margin capture against online retail encroachment.
United States
FCC Part 15 testing timelines for Wi-Fi and Bluetooth-enabled cook processors extend North American launch windows by four to six months. FDA food-contact material safety regulations govern stainless steel and ceramic bowl specifications for domestic and commercial kitchens. California and New York Metro households drive premium-tier demand for sensor fusion and adaptive control algorithms.
China
Contract manufacturers in Guangdong and Zhejiang provinces deploy robotic assembly lines for precision-wound copper induction coils, compressing production costs for Western OEMs sourcing premium heating subsystems. GB standards and MIIT regulations shape domestic product certification requirements. Yangtze River Delta industrial zones concentrate automated assembly capacity for induction heating modules.
India
New BIS mandatory safety and energy labeling requirements for kitchen equipment create first-mover positioning opportunities for brands establishing localized assembly networks. Maharashtra and Karnataka states concentrate emerging middle-class demand for countertop consolidation appliances. DGFT import regulations and PLI scheme incentives reshape competitive entry strategies for multinational OEMs.
Cook Processor Market Competitive Landscape
Global majors compete with regional champions across distribution channel control and thermal technology specialization. The vendor base stratifies into three tiers: integrated appliance conglomerates with ecosystem breadth, specialized thermal equipment firms with R&D depth, and contract-manufacturing-dependent brands with cost-focused positioning. Dominant competitive moves include direct-to-consumer channel bypass of traditional retail and vertical integration into precision ceramics and induction coil supply.
Within the premium-tier vector, Vorwerk and De'Longhi Group exemplify channel control and algorithm specialization strategies respectively. Robert Bosch GmbH anchors ecosystem integration approaches across European retail networks. Among Asian manufacturing partners, Chinese contract manufacturers occupy positions as cost-structure compressors for Western OEMs sourcing induction heating subsystems.
| Leading Market Players |
|---|
| Vorwerk |
| De'Longhi Group |
| Whirlpool Corporation |
| Groupe SEB |
| Breville Group Limited |
| SharkNinja Operating LLC |
| Robert Bosch GmbH |
| Koninklijke Philips N.V. |
| Magimix |
| Others |
Pricing and Supply Chain Analysis
Robotic assembly line deployment by Chinese contract manufacturers for precision-wound copper induction coils simultaneously compresses production economics for Western OEMs and concentrates supply leverage within Guangdong and Zhejiang industrial zones. This automation transition feeds downstream into warranty bundling strategies and tiered equipment positioning across European and North American retail channels.
Pricing Analysis
Warranty and service bundling separates premium-tier cook processors from unbundled economy alternatives, with Vorwerk's advisor network in France and Spain demonstrating full-coverage subscription viability. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade differentiation under EU Ecodesign Directive thresholds and CE marking requirements. Cost compression in mid-tier convection models is intensifying because Chinese contract manufacturers are passing through automation savings to Western OEMs. Ghost kitchen operators and food delivery services exhibit highest price sensitivity, while full-service restaurants in Milan and Copenhagen absorb premiums for precision temperature sensing arrays.
Supply Chain Analysis
Dual-sourcing requirements for thin-walled alumina-silicate ceramic cooking vessels mandate qualification of both German and Austrian specialty ceramics suppliers, creating procurement complexity for premium-tier assembly. Supply concentration rests on China for automated induction coil production, Germany for precision ceramics, and Italy for commercial channel distribution infrastructure. Raw material dependencies span copper coil windings, alumina-silicate ceramic formulations, and stainless steel bowl specifications. Single-source vulnerability concentrates in German ceramics suppliers controlling premium vessel production. Distribution runs through direct-to-consumer subscription platforms, independent kitchen specialists in Turin and Lyon, and institutional foodservice wholesalers in Saudi Arabia and UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over precision ceramics supply and induction coil sourcing determines margin capture against contract-manufacturing-dependent competitors.
For Market Incumbents: Anchor ecosystem defensibility through captive supply of thin-walled alumina-silicate ceramics from German and Austrian suppliers, insulating against input bottlenecks during demand spikes. Deepen algorithm specialization in sensor fusion and adaptive control to maintain premium positioning against smart-enabled entrants from Asian manufacturing networks. Counter air fryer and combi-microwave substitution threats by emphasizing consolidated equipment footprint value in urban apartment kitchens.
For New Entrants and Emerging Players: Enter via cloud recipe platform partnerships that bypass proprietary firmware lock-in from established brands, targeting household segments in India where BIS mandatory labeling creates first-mover positioning. Exploit underpenetrated institutional catering channels in Saudi Arabia and UAE where programmable thermal processors standardize output across outlet networks. Pursue white-glove installation service differentiation against direct-to-consumer encroachment in Lyon and Turin specialty retail.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated appliance conglomerates seeking thermal technology depth and algorithm R&D capabilities. Long-term viability hinges on backward integration into precision ceramics or induction coil supply chains rather than contract-manufacturing-dependent positioning. Acquisition target archetypes include specialized thermal equipment firms with Munich or Stuttgart engineering clusters and direct-to-consumer channel control in France or Spain. Watch multi-physics simulation talent scarcity as inflection indicator for R&D cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Ceramics | Captive supply of alumina-silicate vessels insulates German OEMs from input bottlenecks during demand spikes. |
| Direct-to-Consumer Subscription Launch | Vorwerk's advisor network in France and Spain demonstrates channel control viability against retail encroachment. |
| Smart Cooking Algorithm Acquisition | De'Longhi Group's specialized R&D anchors European competitiveness in sensor fusion and adaptive control. |
| Cloud Recipe Platform Partnership | Integration with third-party meal-planning applications opens recurring revenue streams beyond hardware margins. |
| Commercial Catering Channel Expansion | Institutional operators in Saudi Arabia and UAE deploy programmable units for outlet network standardization. |
Research Methodology
Independent corroboration across primary interviews with appliance R&D directors, commercial kitchen operators in Milan and Barcelona, specialty ceramics procurement managers, and direct-to-consumer channel strategists underwrites the qualitative findings. Secondary validation draws from EU Ecodesign Directive regulatory filings, CE marking body documentation, FCC Part 15 certification records, BIS appliance standard notifications, and customs data on induction heating module trade flows. Bottom-up demand modeling from end-user specification levels triangulates against top-down market sizing from OEM shipment disclosures.
Rate-of-change decomposition across the projection horizon isolates volume drivers by product type, end-user intensity, technology tier, and distribution channel economics. Segmentation dimensions span thermal performance tiers, connectivity requirements, and regional regulatory clusters including EU Ecodesign, FCC Part 15, and BIS mandatory labeling. CAGRs derive from installed base replacement cycles, commercial kitchen labor economics, and smart cooking technology adoption curves. Industry-specific forecast inputs incorporate induction module automation cost trajectories and precision ceramics supply elasticity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU F-Gas Regulation expansion or cybersecurity compliance scope increases from CE marking bodies. Deviation in Chinese contract manufacturer automation adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market