
 Soda Production Machine Market | 2026-2036
Soda Production Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Soda Production Machine Market Analytics
Mechatronics engineering talent is bifurcating the competitive landscape between established industrial OEMs and agile consumer-appliance entrants. SodaStream Inc. leverages its captive CO₂ cylinder exchange network to sustain recurring revenue beyond hardware sales. Aarke competes on design-forward stainless-steel form factors that command premium positioning in European and North American retail channels. iSi GmbH anchors its position through decades of pressure-system expertise inherited from whipped-cream charger technology applied to carbonation.
Soda production machines integrate pressurized CO₂ injection, precision syrup metering, and automated valve sequencing to transform potable water into flavored carbonated beverages at flow rates from 0.5 to 500 liters per minute. Carbonation systems dominate installed base value due to compressor and pressure-vessel capital intensity, while automated control technology captures expanding margin pools as bottling plants retrofit legacy lines for real-time flow adjustment. Restaurants represent the fastest-growing end-user segment as tabletop and under-counter units displace pre-bottled procurement, though bottling plants retain the largest absolute equipment spend.
The US FDA governs contact-surface materials and sanitation protocols for commercial beverage equipment, while the EPA regulates CO₂ venting and refrigerant leakage from production-scale carbonation compressors. CE marking under the EU Machinery Directive mandates pressure-equipment conformity assessment for machines sold across European member states. Stakeholders must monitor evolving carbon-border adjustments and refrigerant-phase-down schedules that could restructure total cost of ownership calculations for production equipment deployed across jurisdictions.
Market Dynamics
EU F-Gas Regulation is forcing manufacturers to redesign refrigeration loops and CO₂ recovery architectures, compressing development cycles and raising compliance costs across European supply chains while opening substitution windows for electromechanical carbonation systems.
Growth Catalysts
- Foodservice carbonation programs:Restaurants and hotel chains deploy under-counter units to eliminate bottled beverage procurement and reduce waste hauling fees.
- REACH-compliant material substitution:Stainless-steel pressure vessels replace legacy aluminum components in premium residential machines, satisfying durability and recyclability mandates.
- German precision engineering clusters:Concentrated supplier networks around Stuttgart and Munich accelerate prototyping cycles for high-pressure valve assemblies.
Market Restraints
- CO₂ supply concentration:Industrial gas distributors control cylinder exchange infrastructure, creating captive dependencies for countertop machine operators.
- Refrigerant phase-down schedules:The EU F-Gas Regulation restricts hydrofluorocarbon use in compressor-based carbonation, forcing costly retooling of existing product lines.
- Pressure-vessel certification timelines:CE marking under the EU Machinery Directive requires 6-12 month conformity assessments, delaying product launches.
Strategic Opportunities
- India foodservice penetration:Quick-service restaurant chains in Mumbai and Bangalore represent underdeveloped demand for commercial carbonation equipment.
- CO₂ recovery system integration:Brewery and ethanol plant waste gas capture creates closed-loop supply for regional bottling operations.
- IoT-enabled predictive maintenance:Sensor-embedded valves and flow meters enable subscription-based service revenue from fleet operators.
Industry Challenges
- Mechatronics talent scarcity:Shortages of control-systems engineers with pneumatic and fluid-dynamics expertise constrain R&D throughput in European manufacturing bases.
- Legacy bottling line integration:Retrofitting automated valve sequencing into 1990s-era production infrastructure requires custom mechanical adapters and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soda Production Machine Market |
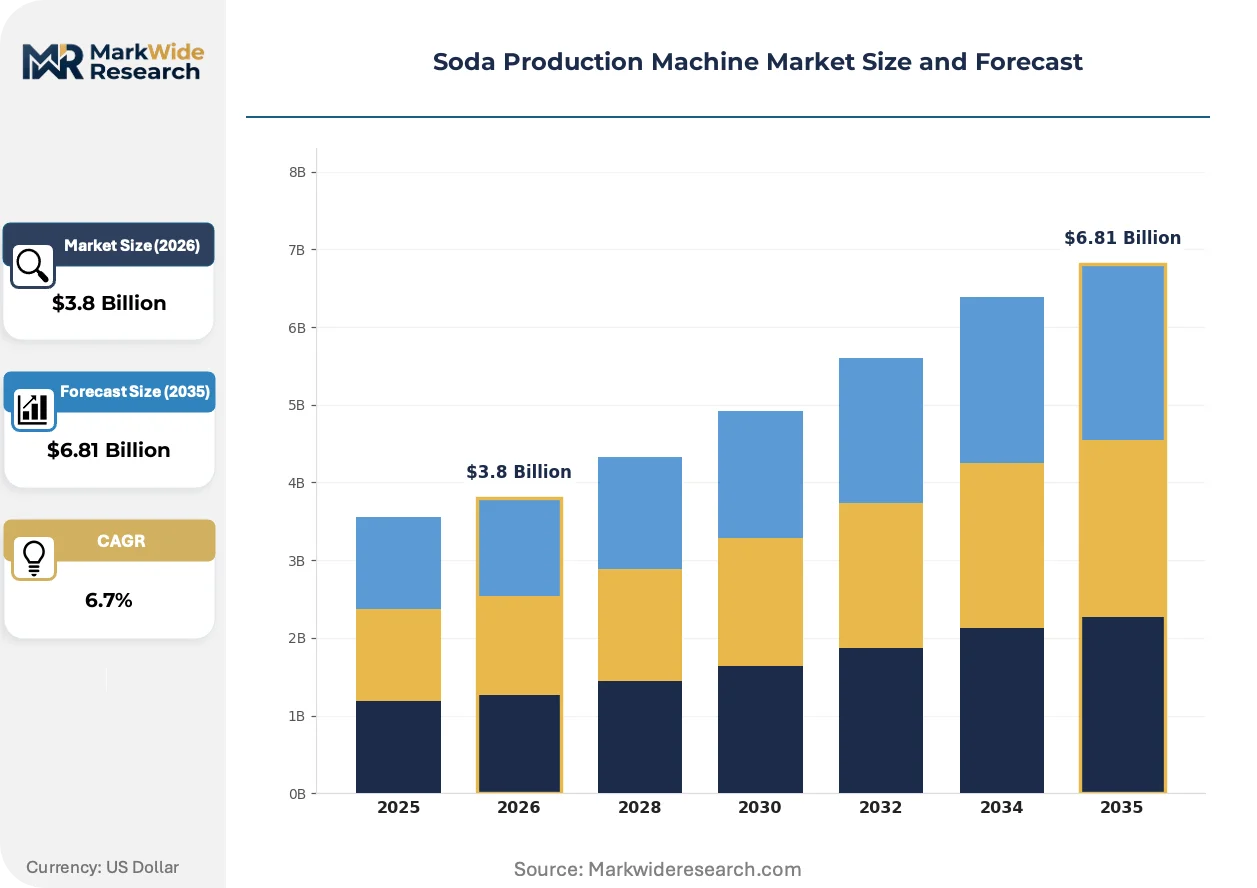
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonation Systems, Syrup Dilution Units, Valve Assemblies, Flavoring Machines Technology: Batch Processing, Continuous Flow, Pressure Injection, Automated Control End User: Restaurants, Bottling Plants, Beverage Distributors, Home Users Application: Soft Drinks, Energy Beverages, Carbonated Water, Mixers |
| Companies Covered | SodaStream Inc., DrinkMate, Aarke, Drinkworks, Sparkel Beverage Systems, Mr. Butler, Nuvantee, Mysoda, iSi GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soda Production Machine Market Evolving Landscape
Electromechanical carbonation hardware is displacing compressor-dependent architectures across residential and light-commercial segments. Three converging developments are compressing equipment footprints, tightening regulatory compliance, and restructuring procurement relationships between manufacturers and end-users.
Membrane-based carbonation technology is miniaturizing CO₂ dissolution systems for countertop appliances. Residential buyers in Germany and the Netherlands adopt these units at accelerating rates. The technology is miniaturizing pressure-chamber volumes from 2-liter industrial scales to 0.5-liter domestic formats without flow-rate degradation.
The EU F-Gas Regulation mandates progressive reduction in fluorinated greenhouse gas emissions from refrigeration equipment. Manufacturers of compressor-based carbonation systems face stranded asset risk in existing product portfolios. Bottling plant operators in France and Italy are prioritizing electromechanical alternatives to preempt compliance penalties.
After-sales service unbundling is separating hardware ownership from consumable supply in commercial accounts. Restaurant chains negotiate cylinder-exchange contracts independently of equipment purchase, compressing manufacturer margin capture. This pattern is most visible in North American foodservice procurement, where third-party gas distributors control recurring revenue streams.
Soda Production Machine Market Segmentation
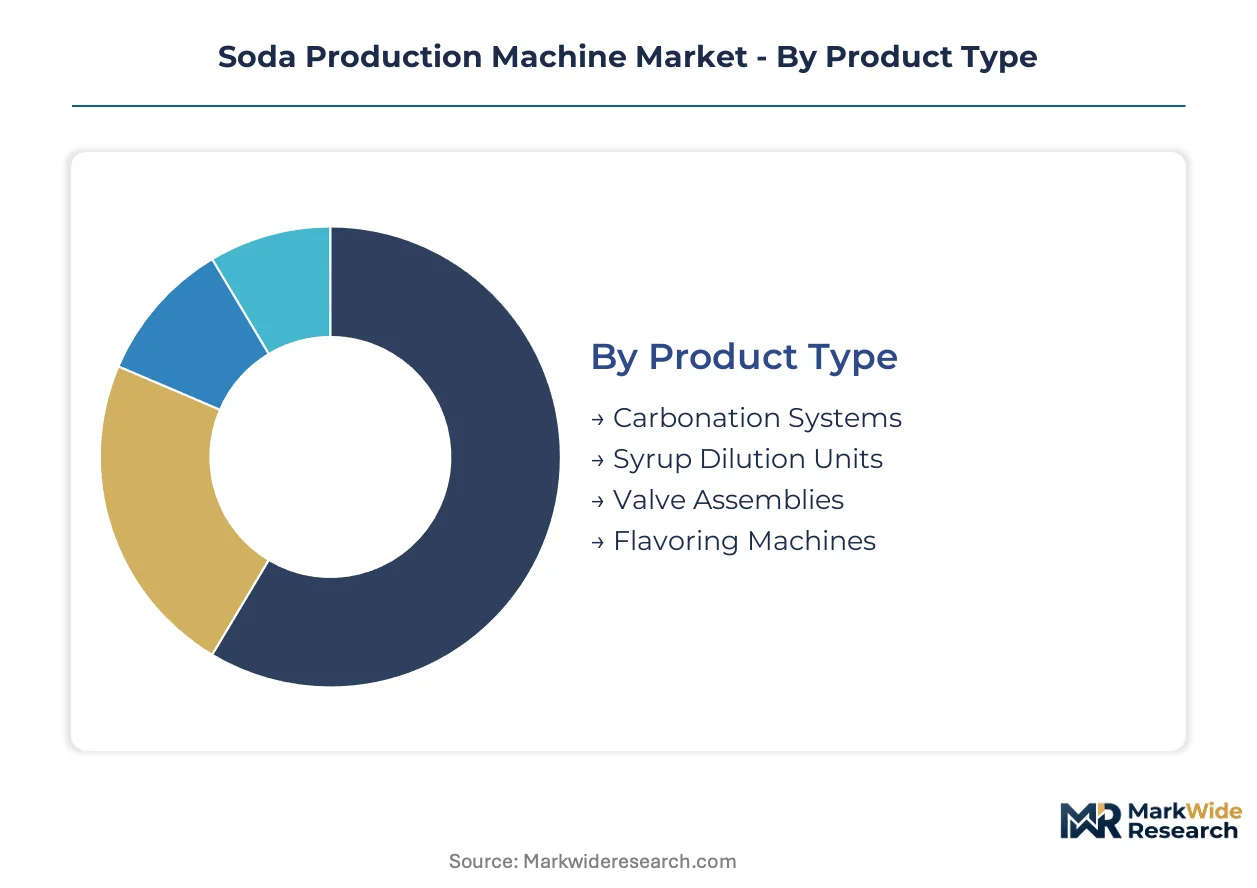
Soda production machine segmentation reveals how regulatory pressure, operational scale, and carbonation intensity reshape procurement priorities across equipment categories. Manufacturers configure product lines around pressure-equipment certification tiers and end-user throughput requirements rather than one-size-fits-all platforms.
Product Type:
EU F-Gas Regulation and CE marking under the EU Machinery Directive create divergent compliance burdens across pressure-equipment categories, with carbonation systems facing the most stringent refrigerant-phase-down and vessel-certification requirements.
- Carbonation Systems:Compressor-driven or electromechanical pressure chambers dissolve CO₂ into water at 2-8 bar operating pressure. Bottling plants in Germany and France prioritize these units for high-volume lines, though refrigerant restrictions are forcing accelerated redesign cycles. CE marking timelines of 6-12 months delay launches for new compressor architectures.
- Syrup Dilution Units:Precision metering pumps blend concentrate with carbonated water at ratios from 1:5 to 1:20. Restaurant chains in North America deploy under-counter formats to eliminate bottled syrup procurement. FDA contact-surface material rules govern stainless-steel and polymer selection for commercial installations.
- Valve Assemblies:High-pressure solenoid and pneumatic valves sequence CO₂ injection, syrup dosing, and container filling. German precision engineering clusters around Stuttgart supply critical components.
- Flavoring Machines:Post-carbonation additive systems inject fruit essences, botanical extracts, or functional ingredients. Home users in the Netherlands and Germany adopt compact residential formats.
Carbonation Systems handle the majority of throughput; Syrup Dilution Units are expanding most quickly in foodservice deployment.
Technology:
Capital intensity and energy efficiency separate batch architectures favored by small-scale operators from continuous-flow systems that dominate bottling plant retrofits.
- Continuous Flow:Uninterrupted water carbonation and flavoring at 50-500 liters per minute. Bottling plants in Italy and Spain retrofit legacy lines with automated control overlays to preempt F-Gas compliance penalties. Real-time flow adjustment captures expanding margin pools as plants modernize.
- Automated Control:Sensor-embedded valve sequencing and predictive maintenance algorithms reduce downtime. Restaurant fleet operators in the United States subscribe to IoT-enabled service contracts for tabletop and under-counter units.
- Batch Processing:Discrete chamber carbonation for small-volume or seasonal production runs. Beverage distributors in India deploy these for regional mixer programs.
- Pressure Injection:Direct CO₂ dissolution without compressor-dependent refrigeration loops. Residential buyers adopt electromechanical formats to sidestep refrigerant regulations.
Continuous Flow commands the largest installed base value; Automated Control is climbing the fastest on subscription revenue attachment.
End User:
Volume scale and procurement autonomy determine whether operators accept captive CO₂ supply relationships or negotiate independent cylinder-exchange contracts.
- Restaurants:Tabletop and under-counter units displace pre-bottled beverage procurement. Chains in the United States and Germany negotiate gas supply separately from hardware purchase, compressing manufacturer recurring revenue. Waste hauling fee reduction drives adoption.
- Bottling Plants:Production-scale lines at 100-500 liters per minute retain the largest absolute equipment spend. Operators in France prioritize electromechanical carbonation to avoid stranded asset risk from F-Gas phase-down schedules.
- Beverage Distributors:Regional filling operations for private-label and craft brands. CO₂ recovery system integration from brewery waste gas creates closed-loop supply in Germany.
- Home Users:Countertop appliances at 0.5-2 liter batch capacity. Design-forward stainless-steel form factors command premium positioning in European retail channels.
Bottling Plants retain the dominant share of capital deployment; Restaurants are gaining share fastest as in-house carbonation programs expand.
Application:
Carbonation intensity and flavor complexity requirements differentiate equipment specifications across beverage categories.
- Soft Drinks:Standardized syrup formulations and consistent CO₂ volumes dominate mass-market production. Bottling plants in Germany and Italy anchor regional supply chains for cola and lemon-lime variants.
- Carbonated Water:Unflavored or lightly essence-infused formats with precision carbonation control. Home users and restaurants in the Netherlands adopt membrane-based miniaturized systems.
- Energy Beverages:Functional ingredient stability requires specialized post-carbonation additive handling. Beverage distributors in India represent underdeveloped demand for commercial equipment.
- Mixers:Tonic, ginger beer, and soda water for cocktail programs. Restaurant chains deploy dedicated under-counter lines to customize carbonation levels.
Soft Drinks absorb the majority of production volume; Carbonated Water is expanding fastest as health-conscious consumers displace sugary alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European compliance architecture, forcing CO₂ recovery redesigns across German, French, and Italian manufacturing bases while compressing development timelines for compressor-dependent carbonation systems.
Germany
Precision engineering clusters around Stuttgart and Munich supply high-pressure valve assemblies to bottling plant operators. CE marking under the EU Machinery Directive mandates 6-12 month pressure-vessel conformity assessments, delaying product launches for new compressor architectures. Beverage equipment exports from Baden-Württemberg anchor regional supply chains serving French and Italian retrofit programs.
France
Bottling plant operators prioritize electromechanical carbonation alternatives to preempt stranded asset risk from refrigerant phase-down schedules. The country's national environmental regulator enforces progressive fluorinated greenhouse gas emission reductions. Lyon-based distributors negotiate independent cylinder-exchange contracts, compressing manufacturer recurring revenue capture.
United States
Restaurant chains deploy under-counter units to eliminate bottled beverage procurement and reduce waste hauling fees. The FDA governs contact-surface materials and sanitation protocols for commercial installations. Chicago and Dallas foodservice markets represent concentrated demand for tabletop carbonation programs.
India
Quick-service restaurant chains in Mumbai and Bangalore represent underdeveloped demand for commercial carbonation equipment. The Food Safety and Standards Authority of India regulates beverage contact materials and processing hygiene. Maharashtra-based beverage distributors deploy batch processing systems for regional mixer programs.
Netherlands
Residential buyers adopt membrane-based miniaturized carbonation systems at accelerating rates. REACH-compliant material substitution mandates drive stainless-steel pressure vessel adoption in premium domestic machines. Amsterdam and Rotterdam retail channels command design-forward positioning for countertop appliances.
Soda Production Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling captive CO₂ cylinder exchange infrastructure and the lower tier competing on design differentiation and pressure-system expertise. The market structure bifurcates between industrial OEMs serving bottling plants and agile consumer-appliance entrants targeting residential and foodservice segments. Two strategic archetypes dominate: integrated gas-supply operators leveraging recurring revenue streams, and engineering specialists monetizing decades of pressure-vessel heritage. Competitive moves center on electromechanical technology licensing and geographic expansion into underpenetrated foodservice markets.
Within the integrated gas-supply tier, SodaStream Inc. and DrinkMate exemplify operators leveraging captive cylinder exchange networks to sustain recurring revenue beyond hardware transactions. Among European engineering specialists, Aarke occupies a position anchored through design-forward stainless-steel form factors, while iSi GmbH represents decades of pressure-system expertise inherited from whipped-cream charger technology applied to carbonation. These three companies illustrate how divergent competitive vectors—gas-supply integration, design premiumization, and technical heritage—structure positioning across residential and commercial segments.
| Leading Market Players |
|---|
| SodaStream Inc. |
| DrinkMate |
| Aarke |
| Drinkworks |
| Sparkel Beverage Systems |
| Mr. Butler |
| Nuvantee |
| Mysoda |
| iSi GmbH |
| Others |
Value Network & Pricing Analysis
Long-term cylinder-exchange contracts lock in CO₂ supply access for restaurant chains while compressing manufacturer visibility into recurring revenue streams. These arrangements tether foodservice operators to industrial gas distributors across Germany and France, stripping equipment vendors of consumable margin capture.
Pricing Analysis
Price spreads between electromechanical and compressor-based carbonation systems widen in France and Italy as F-Gas compliance costs accumulate. Three-tier pricing structure across premium stainless-steel residential units, standard commercial under-counter formats, and economy-grade batch systems reflects CE certification grade and volume scale. Pricing pressure stems from refrigerant-phase-down schedules forcing costly retooling. Small restaurant chains exhibit highest price sensitivity; bottling plants prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Germany and Italy anchor precision manufacturing of high-pressure valve assemblies and stainless-steel pressure vessels. Component sourcing draws from Stuttgart engineering clusters for pneumatic systems, Dutch membrane suppliers for miniaturized carbonation chambers, and Chinese electronics for sensor-embedded control boards. Single-source vulnerability concentrates in CO₂ cylinder exchange infrastructure controlled by industrial gas distributors. Distribution runs through beverage equipment OEMs serving retrofit bottling lines and direct-to-foodservice channels for under-counter units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
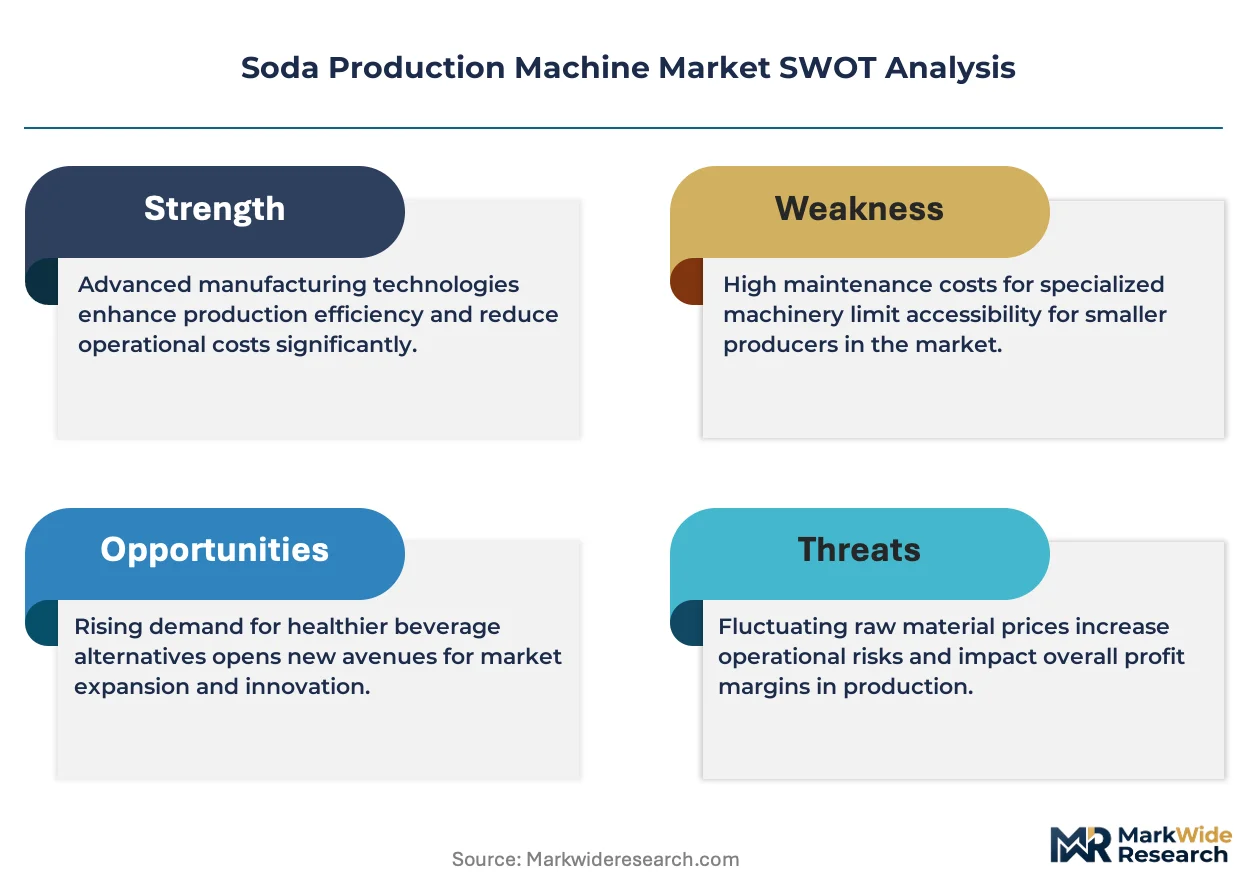
This market rewards defensive moats built on regulatory entrenchment. CE marking timelines and F-Gas compliance create switching costs that protect established positions.
For Market Incumbents: Consolidate control over CO₂ cylinder exchange networks to defend recurring revenue against third-party gas distributors. Acquire precision valve engineering capabilities in Stuttgart clusters to preempt mechatronics talent scarcity. Expand electromechanical product lines before refrigerant-phase-down deadlines strand compressor-dependent assets.
For New Entrants and Emerging Players: Differentiate on membrane-based miniaturization for residential segments where design-forward positioning commands premium pricing. Target quick-service restaurant chains in Mumbai and Bangalore with batch processing systems tailored to FSSAI compliance requirements. Pursue direct partnerships with brewery waste-gas recovery operations to bypass industrial gas distributor gatekeepers.
For Investors and Strategic Acquirers: Engineering specialists with decades of pressure-system heritage represent acquisition targets with defensible technical moats. Long-term viability hinges on electromechanical carbonation patent portfolios and captive gas-supply relationships. Watch for inflection when EU F-Gas phase-down penalties accelerate bottling plant retrofit timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Technology Licensing | Enables compressor-dependent OEMs to preempt stranded asset risk from F-Gas restrictions. |
| CO₂ Recovery System Integration | Creates closed-loop supply from brewery waste gas for regional bottling operations. |
| IoT-Enabled Predictive Maintenance | Generates subscription revenue from sensor-embedded valves deployed across restaurant fleets. |
| REACH-Compliant Material Substitution | Satisfies durability mandates through stainless-steel pressure vessel adoption. |
| Precision Engineering Cluster Expansion | Accelerates prototyping cycles for high-pressure valve assemblies around Stuttgart. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. The research incorporated discussions with plant engineers at German bottling facilities, procurement leads at French restaurant chains, aftermarket service heads at beverage equipment distributors, and regulatory affairs specialists navigating CE marking procedures. Secondary sources included EU F-Gas Regulation compliance databases, FDA contact-surface material guidelines, SEC filings from listed equipment manufacturers, and trade flow data from German engineering export statistics. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Sensitivity analysis tested forecast robustness against refrigerant-phase-down acceleration and CO₂ supply disruption scenarios. The modeling framework segmented volume and value across product type, technology architecture, end-user scale, and application carbonation intensity. CAGRs derived from historical equipment replacement cycles and retrofit penetration rates. Industry-specific inputs included CE marking timeline distributions and foodservice carbonation program adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained F-Gas enforcement or stable industrial gas pricing would require recalibration. Forecasts reflect assumptions about electromechanical technology cost curves and membrane miniaturization yield rates. Recalibration cycles align with material shifts in EU regulatory schedules and foodservice procurement pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Fluidized Bed Dryer Market