
 Food Recycler Market | 2026-2036
Food Recycler Market Size, Share, and Industry Trends Forecast 2026-2036
Food Recycler Market Analysis
On-site biological decomposition technology is tilting food waste management away from centralized municipal collection toward distributed, building-level processing. FoodCycler leverages compact thermal dehydration systems to serve apartment-dwelling households with limited outdoor space. Whirlpool Corporation anchors its position through appliance-grade manufacturing scale and retail channel penetration in North American big-box stores. Oklin International Ltd. specializes in commercial-grade aerobic digesters for high-volume restaurant and hotel kitchens across Asian metropolitan markets.
Food recyclers are electromechanical or biologically active systems that reduce organic waste volume through dehydration, fermentation, or accelerated composting, typically achieving mass reduction of 80-90% within 24 hours for thermal units and 3-7 days for biological systems. Their primary purpose is to eliminate landfill-bound food scraps at the point of generation, cutting haulage costs and methane emissions. The in-vessel product category dominates commercial installations due to sealed odor control and accelerated processing cycles, while the household end-user segment shows the fastest trajectory as unit prices fall below mass-market appliance thresholds. Mechanical technology leads current installed base because of lower capital requirements, though biological systems command margin premiums where effluent quality standards apply.
The US EPA landfill diversion guidelines and California's SB 1383 enforcement timeline shape product certification requirements and commercial buyer procurement criteria. The EU Green Deal's food waste reduction targets and national organic waste separation mandates in France, Italy, and the Netherlands create compliance-driven replacement cycles for outdated composting infrastructure. Stakeholders must monitor how municipal organic waste collection fees versus capital expenditure breakevens shift as energy costs and carbon pricing mechanisms evolve.
Market Dynamics
California's SB 1383 enforcement timeline is compressing commercial buyer decision cycles and tilting procurement toward certified on-site processing units that demonstrate measurable landfill diversion.
Growth Catalysts
- EU Green Deal food waste targets:France, Italy, and the Netherlands now mandate organic waste separation, triggering replacement cycles for outdated municipal composting infrastructure.
- Thermal dehydration advances:Compact electromechanical systems achieve 80-90% mass reduction within 24 hours, unlocking apartment-dwelling households with zero outdoor space.
- Restaurant sector concentration:High-volume kitchen operators across Germany and California face escalating organic waste collection fees, accelerating on-site unit deployment.
Market Restraints
- Capital intensity barrier:Commercial aerobic digesters require upfront expenditure that extends payback periods when municipal collection fees remain artificially suppressed.
- Biological system limitations:Aerobic decomposition cycles of 3-7 days constrain throughput for peak-volume food service operations versus thermal alternatives.
- Fragmented certification requirements:Divergent state-level organic waste processing standards across the US create compliance friction for multi-state equipment vendors.
Strategic Opportunities
- Household subsidy channels:German municipal composting infrastructure supports dual rebate programs for residential unit purchases, expanding addressable market penetration.
- Carbon pricing integration:Evolving methane emission accounting methodologies position landfill diversion equipment for verified carbon credit monetization.
- Retail appliance channel convergence:Big-box store placement adjacent to dishwashers and garbage disposals normalizes food recyclers as standard kitchen infrastructure.
Industry Challenges
- Odor control engineering talent:Sealed in-vessel design expertise remains concentrated among specialized mechanical engineering consultancies, constraining product development velocity.
- Legacy waste haulage contract structures:Long-term municipal service agreements lock commercial buyers into collection-based models despite superior unit economics from on-site processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Recycler Market |
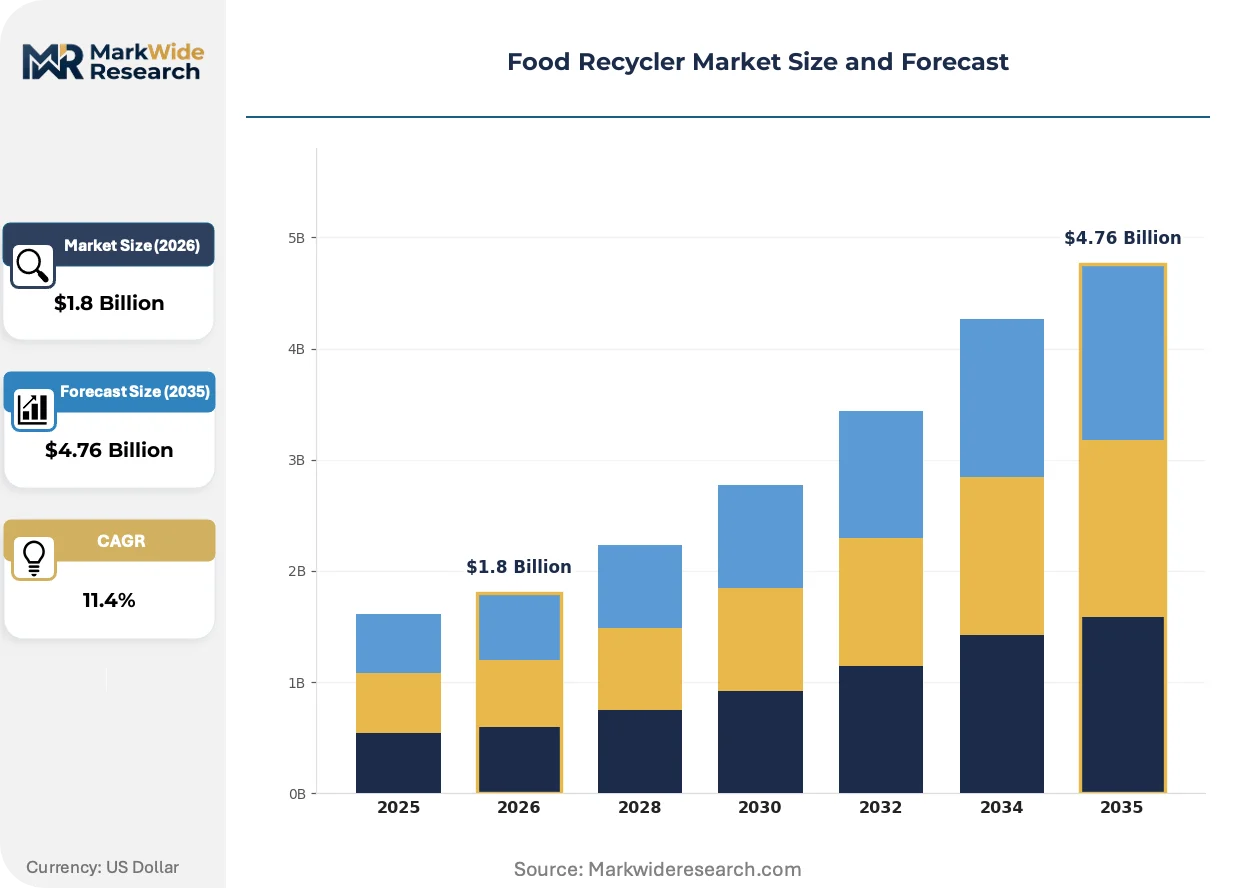
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Vessel, Aerobic, Anaerobic, Composting End User: Restaurants, Grocery Stores, Households, Food Processing Facilities Technology: Mechanical, Biological, Thermal, Chemical Installation: Indoor, Outdoor, Mobile, Fixed |
| Companies Covered | FoodCycler, simplehuman, Oklin International Ltd., Emerson Electric Co., Whirlpool Corporation, Joseph Joseph Ltd., Renovare Environmental, Inc., BioHiTech Global, Ridan Composting Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Recycler Market Emerging Trajectories
Sensor-integrated monitoring systems are digitizing food recycler operations, enabling predictive maintenance and diversion analytics that reshape how buyers justify capital expenditure.
Thermal dehydration technology is digitizing volume reduction workflows through embedded load sensors and automated cycle optimization. Restaurant chains with centralized procurement functions are piloting connected units that transmit real-time processing data to sustainability dashboards. This connectivity layer is digitizing what was previously opaque waste generation patterns into auditable metrics for ESG reporting.
The US EPA landfill diversion guidelines are tightening certification thresholds for commercial food waste processing equipment. Equipment procurement criteria now explicitly reference EPA-approved testing protocols for mass reduction verification and effluent quality. California's enforcement timeline is compressing vendor certification cycles and disqualifying non-compliant units from state-funded rebate programs.
Building-level sustainability officers are consolidating vendor relationships under master service agreements that bundle equipment, maintenance, and diversion reporting. Hotel and hospitality groups with multi-property portfolios are displacing single-unit purchases with fleet-wide deployment contracts. This concentration pattern is most visible in Asian metropolitan markets where property management companies operate cross-border hotel networks.
Food Recycler Market Segmentation
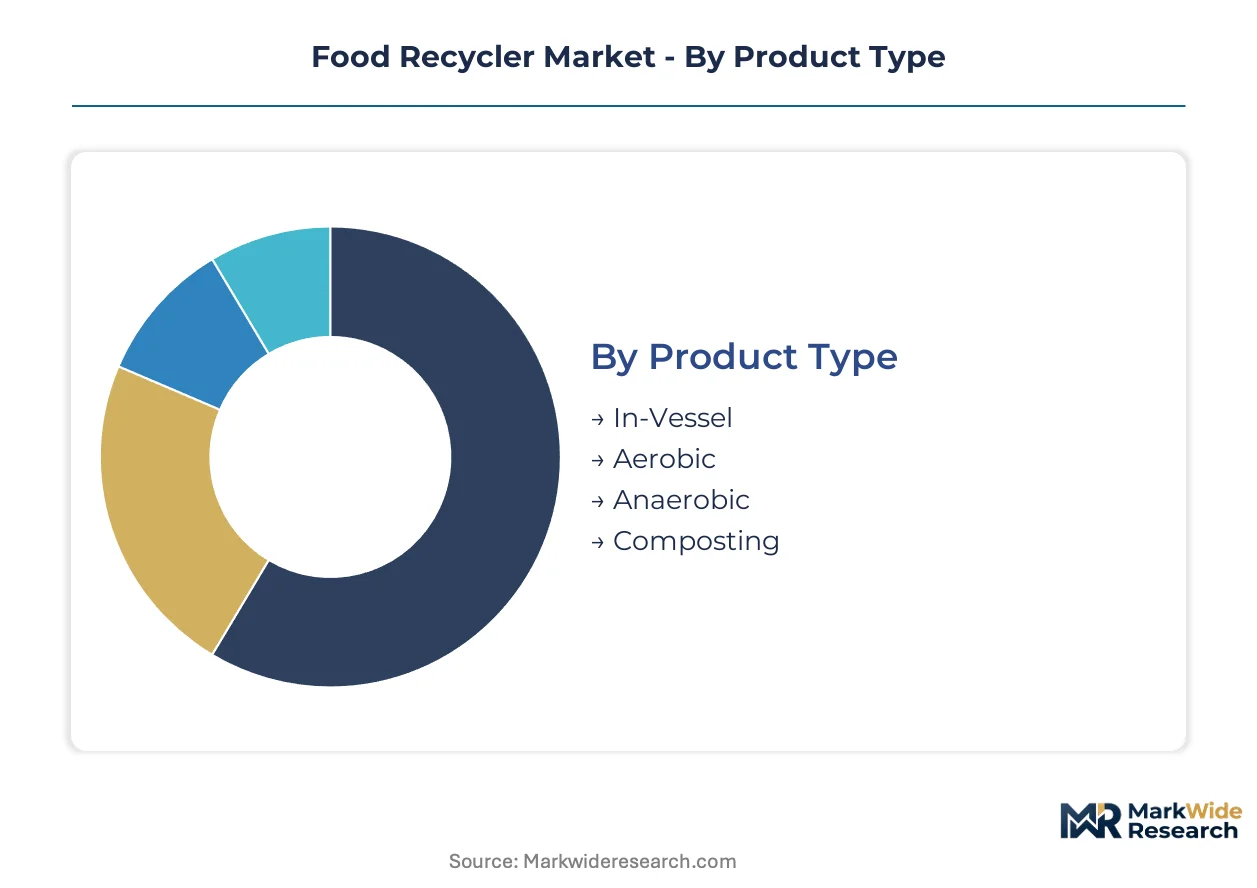
Food recycler segmentation reveals divergent equipment specifications across deployment contexts. Commercial buyers prioritize throughput and odor containment, while residential purchasers trade processing speed for compact footprints and retail accessibility.
Product Type:
After-sales service intensity varies sharply across product categories, with in-vessel systems demanding scheduled seal inspections and aerobic units requiring microbial culture replenishment programs.
- In-Vessel:Sealed containment systems with controlled aeration and automated moisture regulation process organic waste in enclosed drums or tunnels. Restaurant chains across Germany and California specify these units for compliance with municipal odor ordinances and SB 1383 diversion documentation requirements. Scheduled maintenance contracts concentrate service revenue with original equipment manufacturers.
- Aerobic:Open or semi-enclosed systems accelerate decomposition through forced oxygen circulation and periodic agitation. Grocery retailers in France and the Netherlands deploy these for pre-consumer produce trimmings where processing cycle tolerance permits 3-7 day throughput. Biological additive subscriptions create recurring revenue streams that extend vendor relationships beyond initial capital expenditure.
- Anaerobic:Oxygen-excluded digestion chambers producing biogas and digestate outputs suitable for agricultural applications.
- Composting:Passive or low-mechanization pile management systems requiring manual turning and extended curing periods.
By volume, in-vessel leads. By growth pace, aerobic is ahead.
End User:
Cost tier stratification separates commercial purchasers with capital budgets and sustainability mandates from residential buyers sensitive to unit price thresholds and utility consumption.
- Restaurants:High-volume kitchen operators generate 50-200 kg daily food scraps requiring rapid processing to prevent putrefaction and pest attraction. California's SB 1383 enforcement timeline compresses procurement cycles for full-service and quick-service chains facing escalating organic waste collection fees.
- Households:Apartment-dwelling consumers with zero outdoor space drive demand for countertop thermal dehydrators achieving 80-90% mass reduction within 24 hours. German municipal rebate programs subsidize residential unit purchases, expanding addressable market penetration beyond early adopter segments.
- Grocery Stores:Supermarket deli and produce departments with consistent pre-consumer waste streams.
- Food Processing Facilities:Industrial-scale operations with homogeneous organic byproduct streams and on-site energy recovery integration.
Restaurants command the largest installed base. Households exhibit the steepest expansion trajectory.
Technology:
Application requirements dictate technology selection, with mechanical systems dominating where capital constraints prevail and biological systems penetrating where effluent quality standards apply.
- Mechanical:Electromechanical dehydration and grinding systems reduce waste volume through thermal drying and particle size reduction without microbial decomposition. Lower capital requirements and minimal consumable dependencies attract price-sensitive commercial buyers in markets with suppressed municipal collection fees.
- Thermal:Heat-based moisture extraction achieving rapid mass reduction through controlled temperature cycling. Compact footprints unlock apartment-dwelling households across Asian metropolitan markets where outdoor composting space is unavailable.
- Biological:Microbial digestion systems producing stabilized compost outputs suitable for soil amendment applications.
- Chemical:Accelerated breakdown through enzymatic or pH-modification agents.
Mechanical technology holds the dominant share. Thermal systems are climbing the fastest.
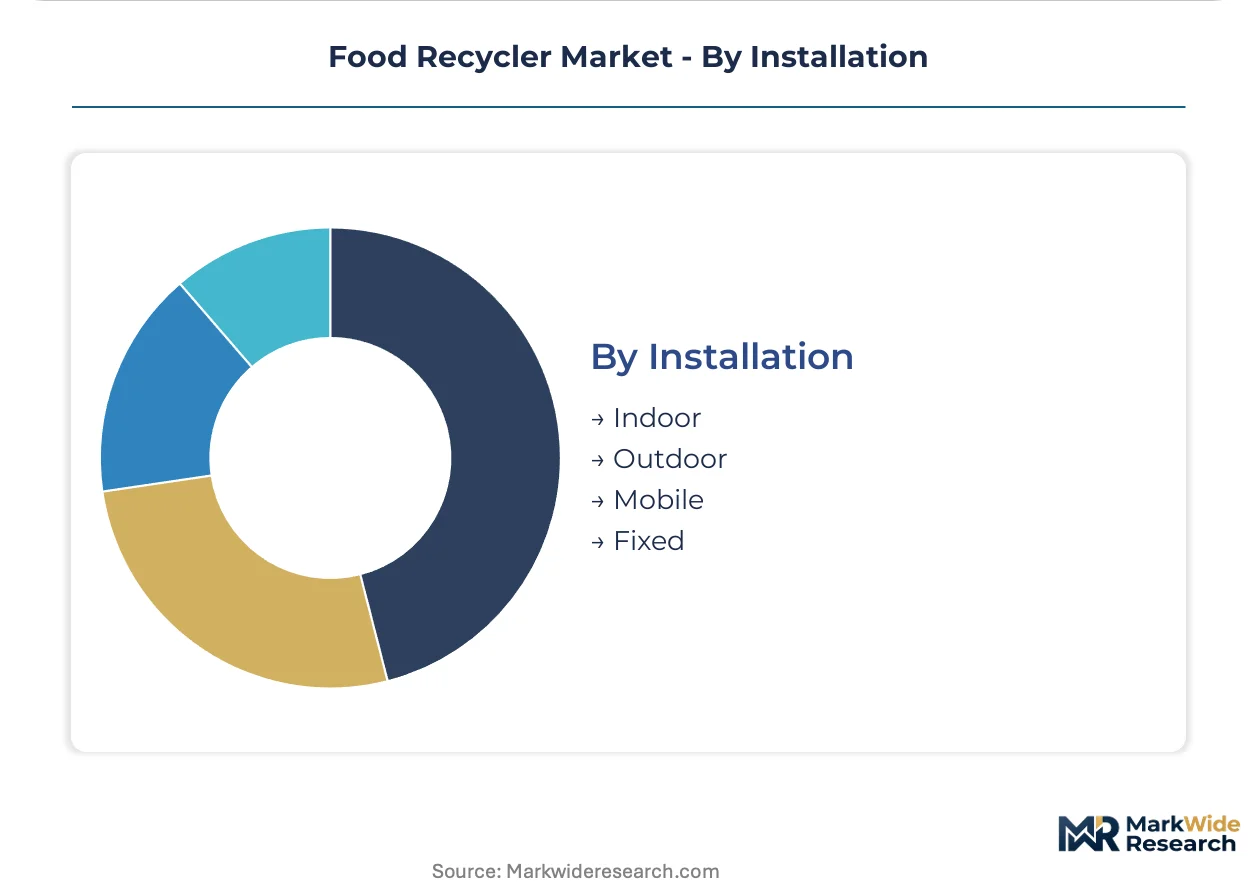
Installation:
Customer type and property configuration determine installation modality, with fixed indoor units representing standard commercial deployment and mobile configurations serving temporary or distributed operational needs.
- Indoor:Climate-controlled installation within kitchen or utility spaces requiring ventilation integration and electrical supply. Hotel and hospitality groups across Asian metropolitan markets standardize on indoor aerobic digesters for back-of-house waste streams where guest-facing odor control is mandatory.
- Fixed:Permanent foundation-mounted systems with hard utility connections and structural enclosures. Municipal composting infrastructure in Germany anchors fixed outdoor installations for centralized community processing facilities.
- Outdoor:Exterior placement with weatherproofing and seasonal operational adjustments.
- Mobile:Trailer-mounted or skid-based units relocatable across construction sites, event venues, or seasonal operations.
Fixed installation dominates commercial procurement. Mobile configurations are gaining share fastest among temporary food service operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Restaurant chains and hotel operators concentrate procurement authority in Germany, the United States, and Japan, while apartment-dwelling households in South Korea and Singapore drive residential unit adoption where outdoor composting space is unavailable.
United States
California's SB 1383 enforcement timeline compresses commercial buyer decision cycles for on-site processing units. The EPA landfill diversion guidelines tighten certification thresholds for mass reduction verification. Los Angeles and San Francisco restaurant clusters accelerate deployment of certified aerobic digesters to demonstrate measurable landfill diversion metrics.
Germany
Municipal composting infrastructure supports dual rebate programs for residential food recycler purchases. The EU Green Deal's food waste reduction targets trigger replacement cycles for outdated community composting facilities. Bavaria and North Rhine-Westphalia anchor fixed outdoor installations for centralized processing while Berlin apartment households adopt compact thermal dehydrators.
Japan
Hotel and hospitality groups with multi-property portfolios consolidate vendor relationships under master service agreements. METI efficiency standards shape equipment procurement criteria for commercial kitchen operators. Tokyo and Osaka metropolitan markets standardize on indoor aerobic digesters for back-of-house waste streams where guest-facing odor control is mandatory.
South Korea
Apartment-dwelling consumers with zero outdoor space drive demand for countertop thermal dehydrators. The country's national environmental regulator enforces organic waste separation mandates in multi-unit residential buildings. Seoul Capital Area retail channels normalize food recyclers as standard kitchen infrastructure adjacent to dishwashers and garbage disposals.
Singapore
Property management companies operating cross-border hotel networks pilot connected units transmitting real-time processing data. The country's national environmental agency mandates food waste segregation for large commercial and industrial premises. Central Business District hotel clusters deploy fleet-wide deployment contracts displacing single-unit purchases.
Food Recycler Market Vendor Landscape
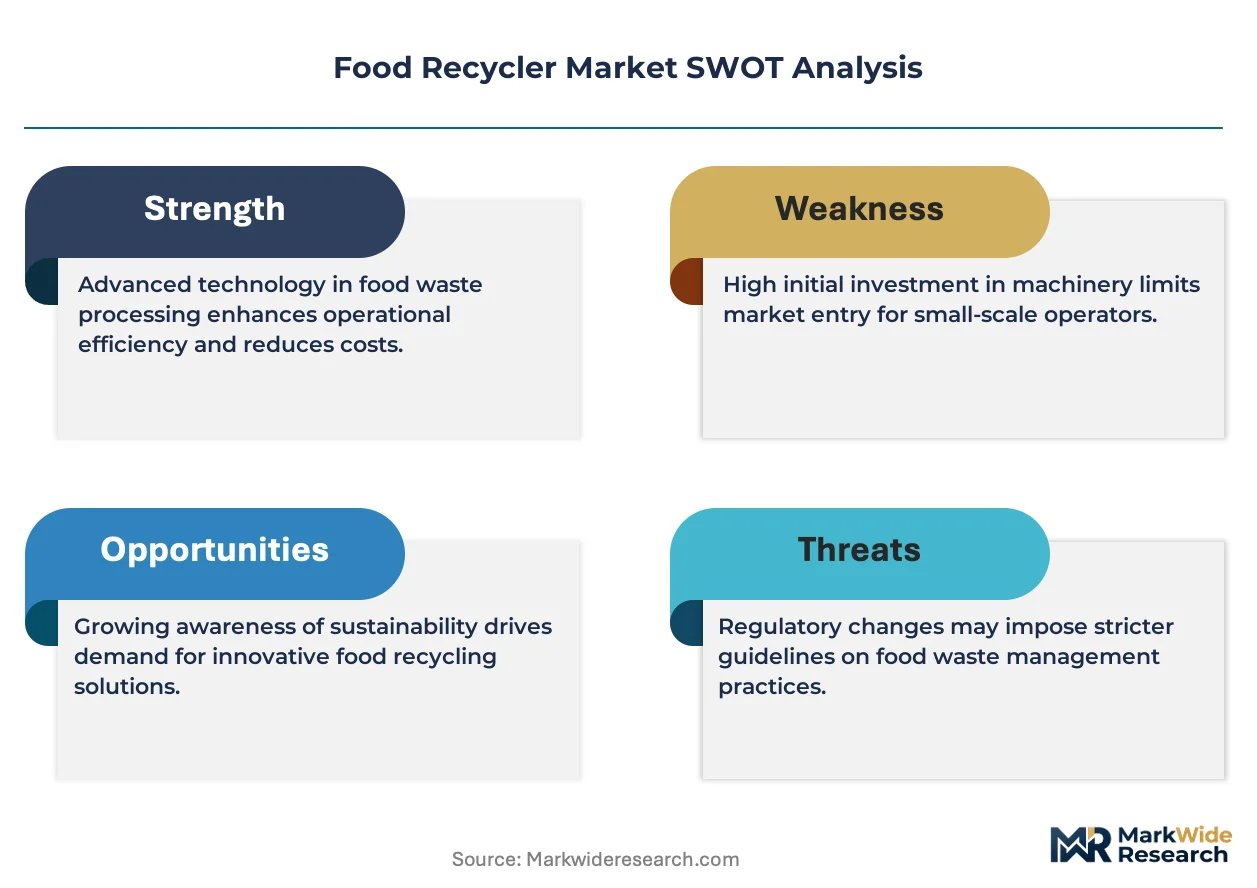
Channel-controlling players compete with product-specialist players across divergent go-to-market strategies. Appliance-grade manufacturers leverage retail penetration in big-box stores while specialized engineering consultancies concentrate sealed in-vessel design expertise. Three archetypes dominate: manufacturing-scale diversified industrials, compact thermal dehydration specialists, and commercial-grade aerobic digester engineers. Strategic moves center on retail appliance channel convergence and fleet-wide deployment contracts for multi-property hospitality portfolios.
Among North American appliance manufacturers, Whirlpool Corporation and Emerson Electric Co. exemplify manufacturing-scale archetypes with retail channel infrastructure. FoodCycler represents the compact thermal dehydration specialist positioned for apartment-dwelling households. Oklin International Ltd. anchors the commercial-grade aerobic digester segment serving high-volume kitchen operators.
| Leading Market Players |
|---|
| FoodCycler |
| simplehuman |
| Oklin International Ltd. |
| Emerson Electric Co. |
| Whirlpool Corporation |
| Joseph Joseph Ltd. |
| Renovare Environmental, Inc. |
| BioHiTech Global |
| Ridan Composting Limited |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese thermal dehydration component manufacturing is compressing supplier margins and tilting procurement power toward appliance-grade OEMs with volume commitments. This utilization dynamic forces specialized engineering consultancies to absorb cost pressure while retail-channel players extract favorable terms through backward integration into sealed vessel fabrication.
Pricing Analysis
Cost-plus contracts indexed to stainless steel and sensor component spot markets dominate commercial aerobic digester procurement. Three-tier pricing structure across premium certified, standard compliance, and economy non-certified levels separates EPA-verified units from state-exempt alternatives. Cost compression in economy tiers is intensifying because municipal rebate programs disqualify non-certified equipment. Quick-service restaurant chains exhibit highest price sensitivity due to thin operating margins, while hotel groups with ESG mandates accept premium positioning.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for electromechanical subassemblies. Manufacturing concentrates in China, South Korea, and Germany for thermal processing units, with Mexico emerging as nearshoring alternative for North American appliance assembly. Critical inputs include precision temperature sensors, corrosion-resistant alloys, and microbial culture media. Distribution runs through big-box retail partnerships for household units and direct OEM relationships for commercial fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's SB 1383 enforcement timeline constitutes a regulatory inflection accelerating commercial procurement velocity beyond historical replacement cycles. This disruption compresses vendor certification windows and rewards pre-positioned compliance infrastructure.
For Market Incumbents: Build certification moats through EPA-approved testing protocol investments ahead of state rebate program disqualification thresholds. Secure exclusive service contracts with multi-property hospitality portfolios to lock out specialized engineering entrants. Channel control through retail appliance placement defends against compact thermal dehydration specialists encroaching on household segments. For New Entrants and Emerging Players: French and Dutch municipal composting infrastructure replacement cycles represent underpenetrated white space where EU Green Deal mandates outpace incumbent service capacity. Grocery retailer pre-consumer waste streams tolerate 3-7 day biological processing cycles unavailable to restaurant operators. Partner with European engineering consultancies for sealed in-vessel design expertise rather than building captive capability. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biological additive subscription programs and scheduled maintenance contracts for in-vessel systems. Long-term viability over a decade horizon favors vendors with dual household-commercial product architectures capable of absorbing segment-specific demand shocks. Monitor carbon credit monetization methodology approvals as inflection signal for landfill diversion equipment valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Retail Appliance Channel Convergence | Big-box placement adjacent to garbage disposals normalizes food recyclers as standard kitchen infrastructure. |
| Fleet-Wide Deployment Contracting | Multi-property hospitality portfolios displace single-unit purchases with bundled equipment-maintenance-reporting agreements. |
| Carbon Credit Methodology Investment | Verified methane diversion accounting positions landfill diversion equipment for emissions trading monetization. |
| Backward Integration into Vessel Fabrication | Appliance-grade manufacturers capture margin from specialized engineering consultancies through in-house sealed drum production. |
| Sensor-Integrated Connectivity Layer | Real-time processing data transmission enables predictive maintenance and auditable ESG reporting for sustainability officers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA certification databases, EU member state organic waste mandate filings, and appliance retail audit data. Primary interviews engaged sustainability officers at multi-property hospitality groups, procurement directors at quick-service restaurant chains, municipal waste management administrators, and sealed vessel engineering consultants. Secondary validation drew from SB 1383 enforcement timelines, METI efficiency standard disclosures, and trade customs records for thermal dehydration component flows. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Forecast inputs span technology penetration curves across mechanical, thermal, and biological systems; installation modality preferences by property type; and regulatory enforcement intensity by jurisdiction. Segmentation dimensions modeled include product category, end-user vertical, technology type, and installation configuration. CAGRs derive from logistic adoption curve fitting against historical appliance replacement cycles and compliance-driven procurement compression. Industry-specific inputs incorporate municipal organic waste collection fee trajectories and carbon pricing mechanism evolution.
Practitioners should monitor state-level organic waste processing standard divergence and carbon credit methodology approval timelines for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Beverage Processing Equipment Market
Food Processing Equipment
Decanter Centrifuge Market