
 Brewing Equipment Market | 2026-2036
Brewing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brewing Equipment Market Outlook
Multi-source procurement among mid-size craft breweries is expanding as brewers seek to reduce dependency on single-vendor bottling lines and fermenter packages. GEA Group leverages its integrated process technology portfolio to anchor turnkey brewhouse contracts across Europe. Paul Mueller Company sustains its position in North American stainless steel tank fabrication through custom welding capabilities and regional service density. Krones AG dominates high-speed packaging integration, while BrauKon specializes in compact, energy-efficient brewhouse designs for urban microbreweries.
Brewing equipment encompasses vessels, heat transfer systems, and control assemblies engineered to convert malted grains into finished beer through controlled mashing, lautering, boiling, fermentation, and conditioning stages. Fermenters typically utilize 304 or 316-grade stainless steel construction with glycol-jacketed walls maintaining temperatures between 8°C and 22°C depending on yeast strain and beer style, ensuring sanitary processing and batch consistency. Automated systems command premium positioning as labor costs rise and batch reproducibility becomes critical for distributed craft brands scaling beyond taproom sales. Electric brewing gains share in urban installations where steam infrastructure proves prohibitively expensive, while industrial-scale facilities retain steam heating for thermal efficiency. Microbreweries represent the fastest-growing end-user category as regulatory easing lowers capital barriers in multiple jurisdictions.
The FDA's Food Safety Modernization Act and EU Machinery Directive impose sanitary design standards on wort handling and fermentation surfaces, compelling equipment redesign and documentation investments. China's SAMR enforces GB standards for imported brewing machinery, creating compliance friction for European exporters seeking access to the country's expanding craft sector. Brewers and equipment vendors must monitor energy efficiency mandates from Germany's Federal Environment Agency and evolving carbon accounting rules under the EU Green Deal as these reshape total cost of ownership calculations and capital allocation priorities.
Market Dynamics
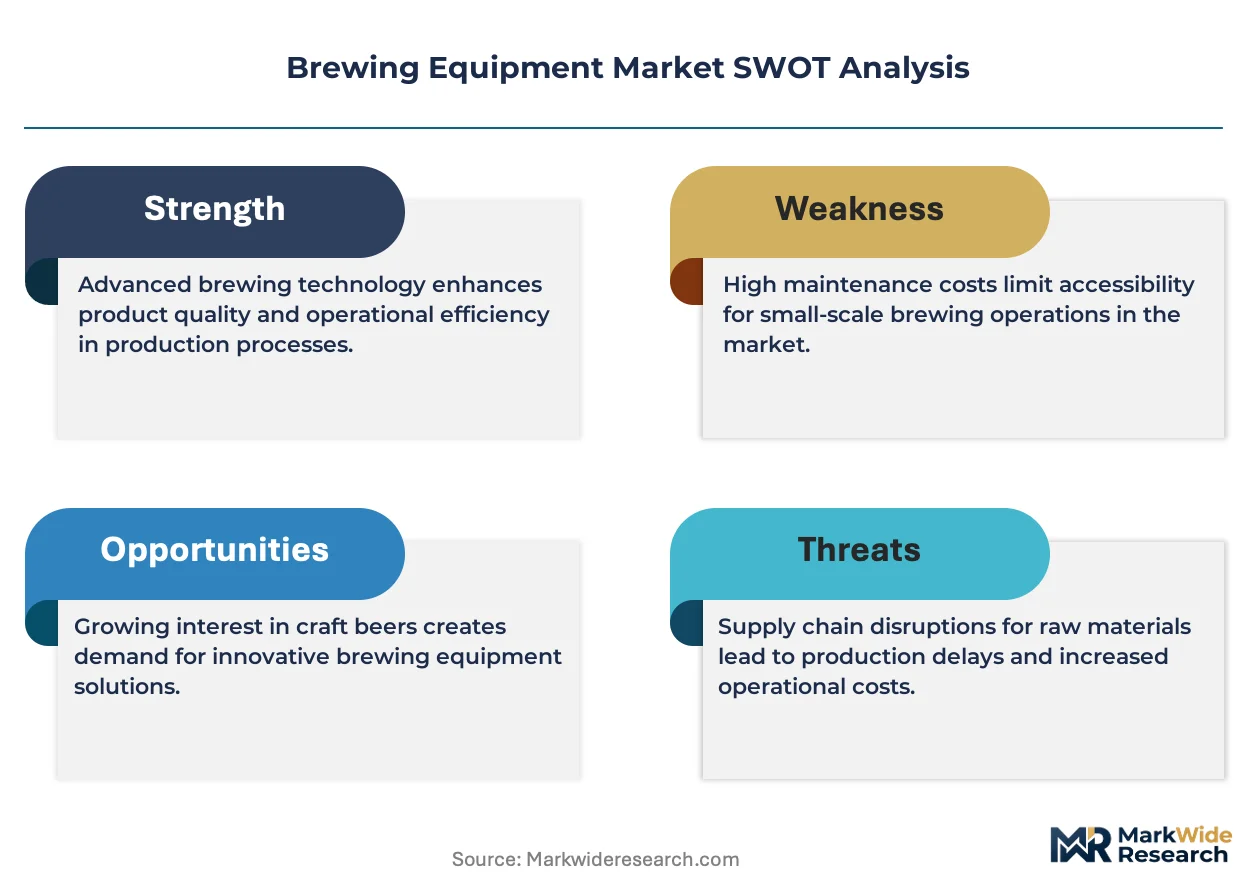
Equipment replacement cycles among craft breweries are compressing as FDA and EU hygiene directives force stainless steel fermentation tank upgrades, while energy efficiency mandates from Germany's Federal Environment Agency reshape capital allocation priorities across the supply base.
Growth Catalysts
- Flavor differentiation imperatives:Craft brewers in Bavaria and Colorado pursue distinctive profiles through precision-controlled fermentation systems. This drives demand for glycol-jacketed vessels with temperature ranges spanning 8°C to 22°C.
- EU Green Deal carbon accounting:The framework's evolving rules are accelerating electric brewing system adoption in urban installations where steam infrastructure costs prove prohibitive.
- Regulatory easing:Capital barrier reductions in multiple jurisdictions are expanding microbrewery licensing, directly stimulating compact brewhouse equipment orders.
Market Restraints
- Stainless steel input volatility:304 and 316-grade steel price swings compress fabrication margins for tank specialists dependent on commodity metal markets.
- China SAMR compliance friction:GB standards enforcement for imported brewing machinery creates documentation bottlenecks for European exporters targeting the country's craft sector expansion.
- Steam infrastructure lock-in:Industrial-scale facilities retain thermal-efficient steam heating, constraining electric system penetration in capacity-constrained segments.
Strategic Opportunities
- Urban microbrewery density:Compact, energy-efficient brewhouse designs serve space-constrained installations in metropolitan Germany and the United States where real estate premiums favor smaller footprints.
- Automated control convergence:Integration of process sensors with batch management software is unifying quality control and traceability for distributed craft brands scaling beyond taproom sales.
- Multi-source procurement models:Mid-size craft breweries are diversifying vendor relationships to reduce single-vendor bottling line dependency.
Industry Challenges
- Sanitary welding certification timelines:FDA Food Safety Modernization Act documentation requirements extend equipment qualification periods for export-oriented suppliers.
- Legacy system integration complexity:Automated brewhouse upgrades must interface with existing fermentation monitoring infrastructure, complicating retrofit deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewing Equipment Market |
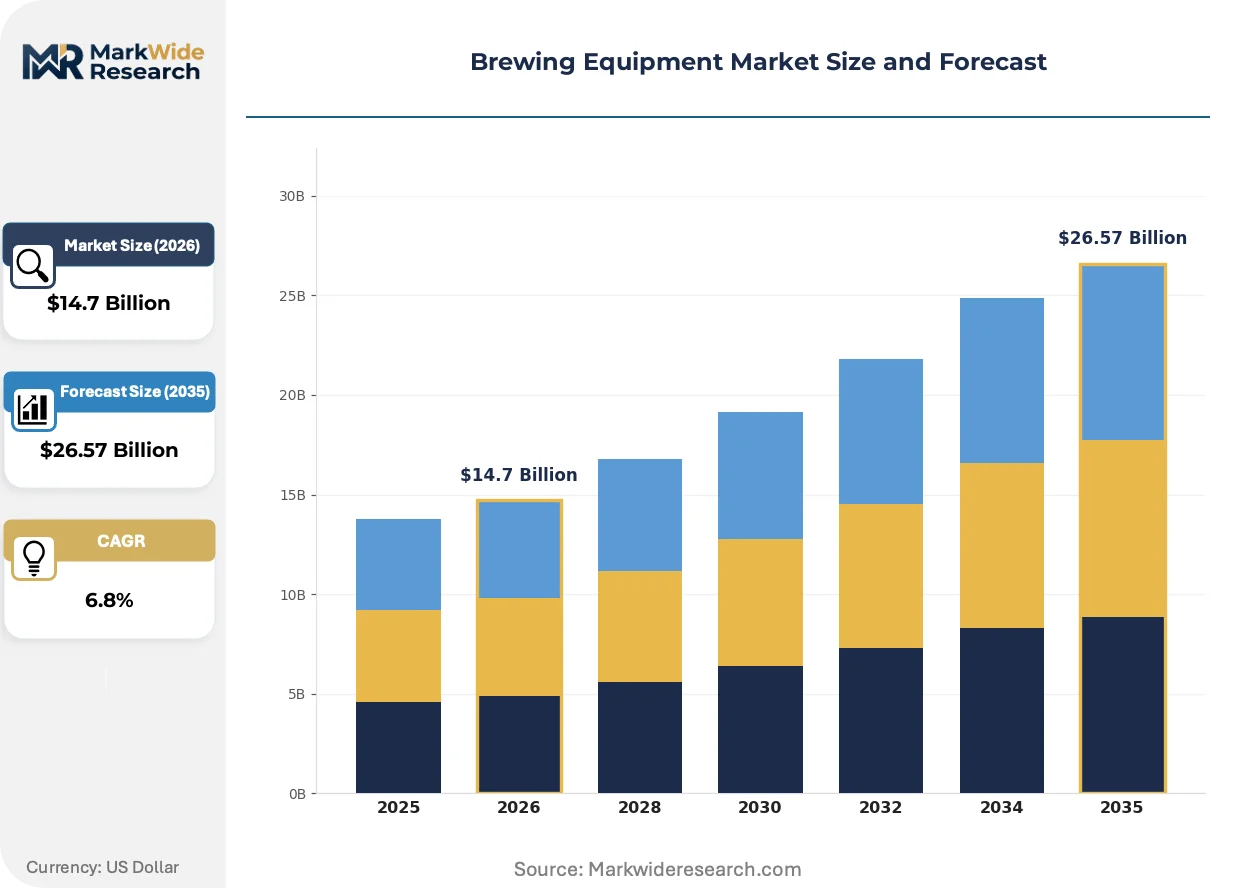
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brew Kettles, Fermenters, Mash Tuns, Heat Exchangers Technology: Electric Brewing, Steam Brewing, Traditional Brewing, Automated Systems End User: Microbreweries, Craft Breweries, Commercial Breweries, Homebrewers Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | Ziemann Holvrieka, Della Toffola, GEA Group, Middleby Corporation, Paul Mueller Company, Krones AG, BrauKon, Meura, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewing Equipment Market Strategic Shifts
Digital process control and energy system electrification are restructuring brewhouse capital deployment patterns, while regulatory documentation burdens intensify compliance engineering investments across the fabrication base.
Integrated brewhouse automation platforms are unifying mashing, lautering, and fermentation control through centralized SCADA architectures. Urban microbreweries in Denver and Munich are adopting these systems fastest, compressing labor requirements and tightening batch reproducibility for brands expanding into distributed retail channels.
REACH chemical safety assessments and F-Gas Regulation phase-down schedules are compelling refrigerant system redesigns in glycol-jacketed fermentation vessels. Equipment vendors serving EU export markets must now document alternative cooling circuit compliance, with Bavarian fabricators investing most heavily in engineering validation capacity.
Service unbundling from equipment supply contracts is fragmenting vendor relationships across the craft segment. Mid-size breweries in Colorado now separately source tank fabrication, control integration, and maintenance services, compressing traditional turnkey supplier margins while expanding specialized service provider opportunities.
Brewing Equipment Market Segmentation
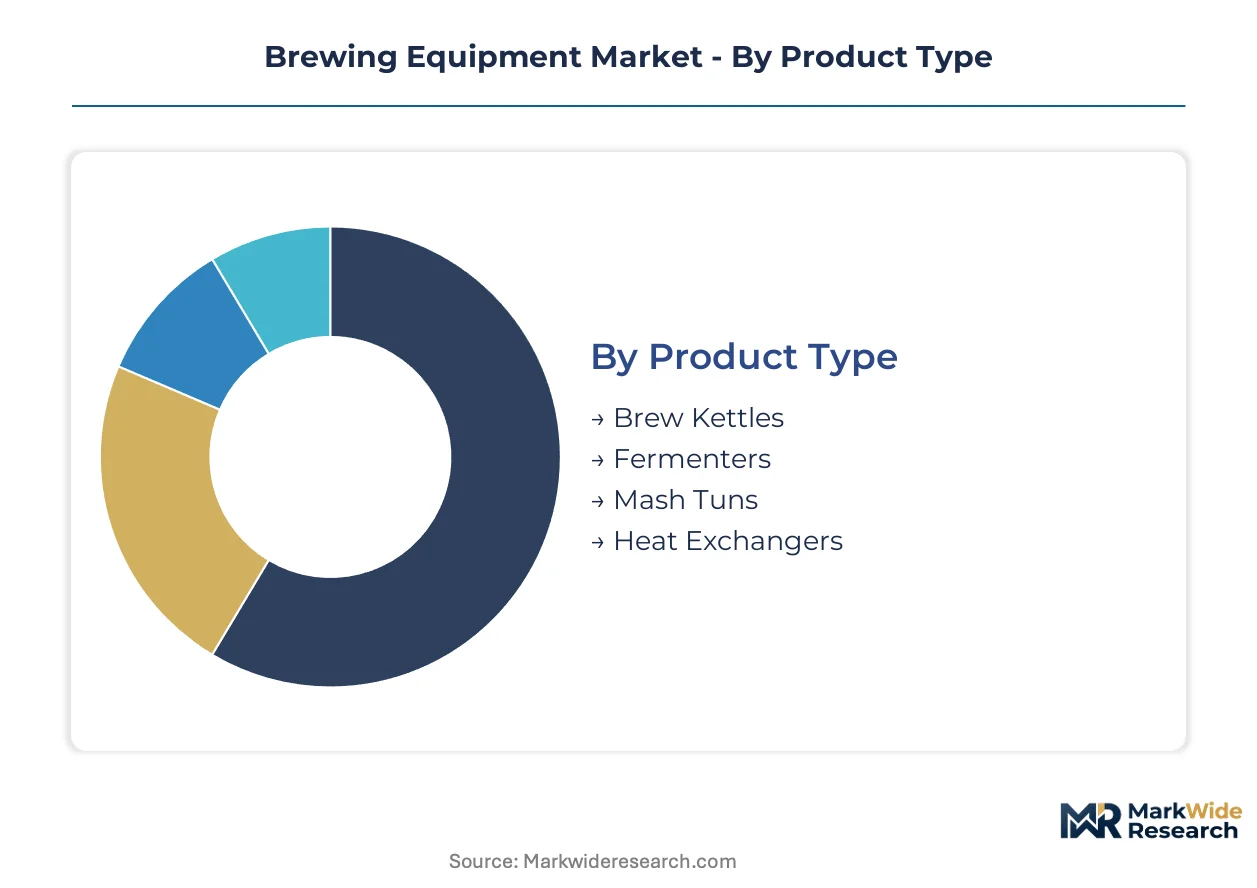
Equipment selection in brewing follows distinct procurement logics across buyer tiers, with microbreweries prioritizing compact footprints and commercial operators emphasizing throughput consistency. Understanding these segment boundaries clarifies where technology investments concentrate and how vendor portfolios must align to capture contract flow.
Product Type:
Purchase decisions pivot on vessel lifecycle durability and thermal control precision, with stainless steel grades and jacketing configurations determining total cost of ownership calculations.
- Fermenters:Glycol-jacketed vessels in 304 or 316-grade stainless steel maintain temperature windows between 8°C and 22°C for yeast strain optimization. Demand concentrates among craft breweries in Bavaria and Colorado replacing legacy tanks to meet FDA and EU hygiene directives for sanitary surface finishes.
- Brew Kettles:Steam-jacketed or direct-fire vessels engineered for wort boiling with precise evaporation control. Commercial breweries in industrial-scale facilities retain these for thermal efficiency, though electric variants gain share in urban installations where steam infrastructure costs prove prohibitive.
- Mash Tuns:Lautering vessels with false bottom configurations separating wort from spent grain. Microbreweries favor compact single-vessel designs that combine mashing and lautering functions.
- Heat Exchangers:Plate or shell-and-tube configurations rapidly cooling wort post-boil to pitching temperatures. Craft brewers pursuing flavor differentiation invest in multi-stage units with precise temperature stepping.
Volume sits with fermenters given replacement cycle compression from regulatory upgrades; growth tilts toward brew kettles as electric heating displaces steam in metropolitan installations.
Technology:
Energy source selection and automation depth determine capital allocation patterns, with labor cost trajectories and carbon accounting rules reshaping technology preferences across facility scales.
- Automated Systems:SCADA-integrated platforms unifying mashing, lautering, and fermentation control through centralized batch management software. Distributed craft brands scaling beyond taproom sales in Denver and Munich adopt these fastest to tighten reproducibility.
- Electric Brewing:Resistance or induction heating elements eliminating steam boiler dependency. Urban microbreweries facing real estate premiums favor these for infrastructure simplicity and EU Green Deal carbon accounting compliance.
- Steam Brewing:Boiler-fed thermal systems retaining efficiency advantages at industrial throughput levels. Capacity-constrained commercial breweries maintain these for energy economics despite electrification pressure.
- Traditional Brewing:Manual or semi-manual operations with limited process control integration. Homebrewers and entry-level microbreweries select these for capital accessibility.
Automated systems command premium positioning; electric configurations are climbing the fastest as regulatory frameworks penalize carbon intensity.
End User:
Scale of operation dictates equipment complexity, with licensing barriers and capital access creating distinct procurement behaviors across the buyer base.
- Microbreweries:Compact brewhouse installations typically below 15 barrel capacity serving taproom-dominant distribution models. Regulatory easing in multiple jurisdictions expands licensing, directly stimulating orders for space-constrained urban designs.
- Craft Breweries:Mid-scale operations pursuing distributed retail presence and flavor portfolio breadth. These buyers drive multi-source procurement trends, separately sourcing tank fabrication, control integration, and bottling lines to reduce vendor dependency.
- Commercial Breweries:High-volume facilities prioritizing throughput consistency and line integration. Krones AG packaging systems and GEA Group turnkey contracts concentrate here.
- Homebrewers:Small-batch enthusiasts utilizing entry-level kettles and fermentation vessels. Price sensitivity dominates with limited service attachment.
Commercial breweries anchor installed base value; microbreweries show the steepest expansion trajectory from capital barrier reduction.
Capacity:
Throughput requirements determine vessel sizing, jacketing complexity, and automation depth, with scale thresholds creating distinct supplier relationships.
- Medium Scale:15-60 barrel systems serving regional distribution craft breweries. Paul Mueller Company custom welding capabilities and regional service density sustain competitive positioning here.
- Small Scale:Sub-15 barrel configurations for taproom-focused microbreweries. BrauKon compact energy-efficient designs target this segment in metropolitan Germany and United States corridors.
- Large Scale:60-200 barrel systems for multi-state distributed brands. Turnkey brewhouse contracts with integrated process technology dominate procurement.
- Industrial Scale:200+ barrel continuous operations with full packaging integration. Steam heating retention and high-speed line automation characterize these installations.
Medium scale concentrates current revenue; small scale is gaining share fastest from urban microbrewery density expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in Germany and the United States where craft brewery density and regulatory stringency create replacement cycle pressure. Bavaria's manufacturing cluster and Colorado's brewing corridor anchor fabrication capacity and end-user demand respectively.
Germany
Bavaria's equipment manufacturing cluster supplies glycol-jacketed fermenters to domestic craft breweries pursuing flavor differentiation. The Federal Environment Agency enforces energy efficiency mandates that accelerate electric brewing system adoption in urban installations. Munich fabricators invest heavily in engineering validation capacity for REACH-compliant refrigerant system redesigns.
United States
Colorado's craft brewing corridor drives demand for compact brewhouse designs as microbreweries expand taproom-dominant distribution models. The FDA's Food Safety Modernization Act imposes sanitary welding documentation requirements that extend equipment qualification periods. Denver breweries adopt SCADA-integrated automation platforms fastest to tighten batch reproducibility for distributed retail expansion.
China
Imported brewing machinery faces compliance friction from SAMR's GB standards enforcement as the country's craft sector expands. The national dual carbon goals reshape capital allocation priorities toward energy-efficient electric configurations. Yangtze River Delta fabricators develop documentation capacity to serve European exporter qualification requirements.
United Kingdom
Urban microbreweries in London and Southeast England favor space-constrained brewhouse installations as real estate premiums compress facility footprints. The EU Machinery Directive's sanitary design standards continue influencing procurement criteria post-Brexit through export-oriented supplier alignment. Midlands-based fabricators specialize in custom welding capabilities for regional craft brewery service density.
Belgium
Traditional brewing heritage centers in Flanders sustain demand for precision-controlled fermentation systems among heritage and craft operators. ECHA's REACH chemical safety assessments compel refrigerant system redesigns in glycol-jacketed vessels. Brussels-area equipment vendors document alternative cooling circuit compliance for EU export market access.
Brewing Equipment Market Competitive Environment
Multi-source procurement dominates the current landscape as mid-size craft breweries diversify vendor relationships to reduce single-supplier dependency. The vendor base structures around turnkey system integrators, specialized tank fabricators, and packaging line specialists. Three archetypes anchor competitive positioning: integrated process technology providers, custom stainless steel welding specialists, and compact urban brewhouse designers. Portfolio diversification and geographic service density expansion constitute the dominant competitive moves.
Among German-based fabricators, Ziemann Holvrieka and BrauKon occupy positions within the integrated brewhouse tier, with the latter exemplifying compact energy-efficient design specialization for metropolitan installations. GEA Group anchors the turnkey process technology archetype across European markets. Paul Mueller Company represents North American custom stainless steel tank fabrication capabilities.
| Leading Market Players |
|---|
| Ziemann Holvrieka |
| Della Toffola |
| GEA Group |
| Middleby Corporation |
| Paul Mueller Company |
| Krones AG |
| BrauKon |
| Meura |
| Alfa Laval |
| Others |
Value Chain & Pricing Dynamics
Multi-source procurement preferences among mid-size craft breweries are forcing equipment vendors to unbundle service contracts from hardware sales, compressing traditional turnkey margins while expanding specialized fabrication opportunities across regional supplier bases.
Pricing Analysis
Volume concentrates with standard fermenter configurations while margins persist in custom welding and automation integration tiers. Price differentiation separates FDA-validated sanitary finishes from standard commercial grades, with certification documentation adding substantial cost premiums. Pricing pressure stems from stainless steel commodity volatility affecting 304 and 316-grade tank fabrication. Microbreweries exhibit highest price sensitivity, while commercial breweries prioritize throughput consistency over unit economics.
Supply Chain Analysis
Sanitary welding certification requirements from FDA and EU hygiene directives are gating supplier qualification, extending equipment validation timelines for export-oriented fabricators. Manufacturing concentrates in Germany, the United States, and China, with Bavaria's cluster anchoring European glycol-jacketed vessel production. Raw material dependencies center on nickel-alloyed stainless steel, specialized welding consumables, and precision temperature control components. Supply chain risk rests on single-source vulnerability for certified welding labor pools. Distribution runs through direct OEM sales for large contracts and regional service networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with integrated automation capabilities and regulatory documentation capacity, as compliance engineering investments force smaller fabricators toward acquisition or exit.
For Market Incumbents: Cement regional service density through targeted certification investments in FDA and EU sanitary welding qualifications. Acquire compact brewhouse specialists in urban microbrewery corridors to capture electrification-driven replacement cycles. Threats from electric heating system startups and carbon accounting mandates favor vendors with backward integration into control software development. For New Entrants and Emerging Players: SCADA-integrated fermentation monitoring systems offer a technology-first wedge into mid-size craft brewery multi-source procurement patterns. Target Colorado and Bavaria microbrewery density for compact electric brewhouse sales. Pursue white-label control integration partnerships with established tank fabricators lacking software capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with custom stainless steel welders possessing regional service networks given regulatory documentation intensity. Long-term viability favors vendors with captive supply of certified welding labor and validated refrigerant system redesigns. Watch for SAMR GB standards enforcement acceleration in China as inflection indicator for exporter qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA and EU sanitary welding documentation capacity separates viable exporters from qualification-limited competitors. |
| Electric System Product Line Expansion | Urban microbrewery electrification driven by Germany's Federal Environment Agency mandates reshapes capital allocation. |
| Service Contract Unbundling | Separate maintenance offerings capture recurring revenue as hardware margins compress from multi-source procurement. |
| Regional Fabrication Footprint Addition | Colorado and Bavaria proximity reduces logistics costs for craft brewery replacement cycle capture. |
| Control Software Acquisition | SCADA integration capabilities tighten batch reproducibility for distributed brands scaling beyond taproom sales. |
Study Parameters
Multi-period observation of equipment replacement cycles, regulatory filing timelines, and stainless steel input costs anchored the trend analysis, supplemented by interviews with brewhouse engineering directors, craft brewery procurement managers, stainless steel fabrication plant managers, and aftermarket service heads. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EU Machinery Directive technical specifications, SAMR GB standards filings, and trade customs data for brewing machinery imports. Bottom-up vendor revenue triangulation against top-down end-user capital expenditure surveys calibrated market sizing.
The input-output matrix framework modeled capacity installations, technology substitution rates, and segment migration patterns across the projection horizon. Segmentation dimensions included vessel type, heating technology, automation depth, end-user scale tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs incorporated carbon accounting rule evolution from the EU Green Deal and SAMR enforcement intensity trajectories.
Several conditions sit outside the modeled scope, including abrupt stainless steel commodity price shocks, unanticipated regulatory harmonization between FDA and EU hygiene directives, and breakthrough fermentation technologies displacing conventional vessel designs. Forecasts reflect documented assumptions regarding replacement cycle compression rates and electrification adoption curves. A model refresh is warranted upon material change in China craft sector licensing velocity or Federal Environment Agency energy efficiency mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Freeze-Drying Market