
 Pie Packaging Market | 2026-2036
Pie Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pie Packaging Market Analytics
Premium-grade barrier specifications is bifurcating the competitive landscape as bakeries and retailers demand longer shelf stability without refrigeration. Amcor plc leverages multilayer coextrusion expertise to serve high-volume frozen pie accounts across North America. Huhtamaki Group anchors European demand through molded fiber tray systems designed for hot-held and chilled applications. WestRock Company competes with integrated paperboard and display packaging combinations that reduce total landed cost for club-store pie programs.
Pie packaging encompasses primary and secondary containment systems engineered to protect baked goods with crimped or fluted edges from mechanical damage, moisture loss, and microbial contamination during distribution, retail display, and home consumption. Technical specifications include grease-resistant coatings rated for butter-fat content exceeding 18%, vapor transmission barriers below 2 g/m²/day, and stack-load capacities of 15-25 kg for secondary shipping cases. Clamshells dominate the quick-service and deli channel due to visual merchandising advantages and reclosability. Biodegradable materials represent the fastest-expanding material category as brand owners respond to corporate sustainability commitments and retailer plastic reduction mandates. Boxes sustain margin pools in the gifting and seasonal segment where lithographic printing and die-cut windows command price premiums.
The FDA governs food-contact substance compliance under 21 CFR for pie packaging sold into the United States, while the EPA regulates per- and polyfluoroalkyl substance phase-outs that directly impact grease-resistant paperboard treatments. The EU Green Deal and PPWR timeline are forcing converters to redesign single-use formats around fiber recovery and recycled content minimums. Stakeholders must monitor how state-level extended producer responsibility laws in California, Oregon, and Colorado reshape cost allocation between packaging suppliers and pie manufacturers.
Market Dynamics
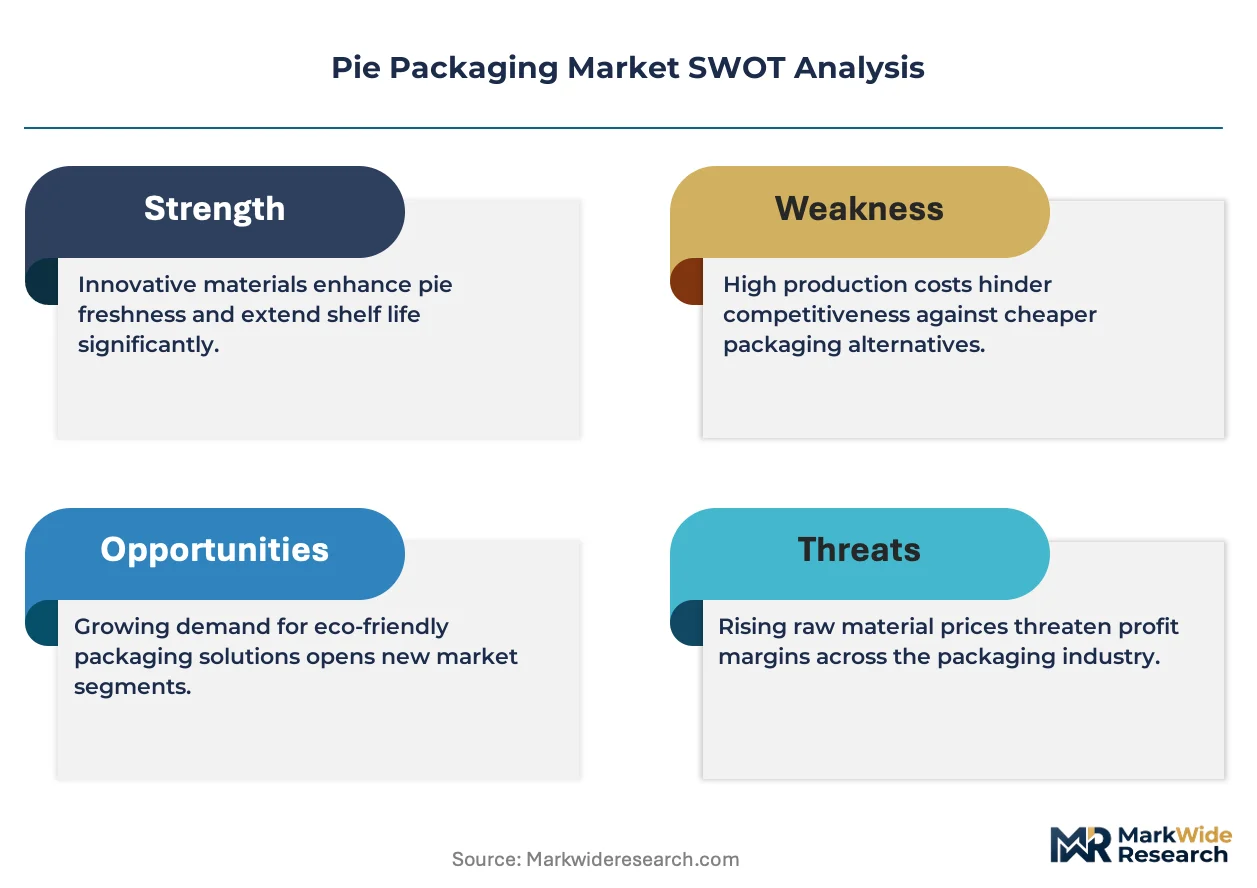
Private-label expansion at Kroger, Albertsons, and Publix is forcing converters to retool lines for shorter-run, higher-SKU packaging formats with faster changeover cycles. This retail consolidation is compressing supplier margins while demanding simultaneous investment in barrier innovation and sustainability credentials.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated fiber-recovery targets are redirecting converter R&D budgets toward molded pulp and paperboard alternatives, creating first-mover advantages for compliant suppliers.
- Direct-to-consumer frozen pie shipping:E-commerce fulfillment requirements for temperature integrity across 48-hour transit windows are pulling demand for insulated box liners and phase-change material integration.
- Quick-service deli channel expansion:Grab-and-go hot-held pie programs at convenience stores are standardizing clamshell specifications with anti-fog coatings and vented domes.
Market Restraints
- Per- and polyfluoroalkyl substance phase-outs:EPA restrictions on PFAS-based grease-resistant treatments are forcing rapid reformulation of butter-fat barrier coatings at elevated technical risk.
- Specialized resin supply concentration:Ethylene vinyl alcohol copolymers for high-barrier multilayer films source from limited Asian petrochemical complexes, exposing converters to input volatility.
- Recyclability-versus-performance trade-off:Fiber-based alternatives to plastic clamshells currently fail to match vapor transmission rates below 2 g/m²/day required for extended shelf stability.
Strategic Opportunities
- Underpenetrated club-store pie gifting segment:Costco and Sam's Club seasonal programs currently use generic corrugated; customized lithographic display cases with die-cut windows command 15-20% price premiums.
- California extended producer responsibility implementation:SB 54 mandates place compliance cost burdens on brand owners, creating consulting and packaging-as-a-service revenue streams for integrated converters.
- Active packaging convergence:Oxygen scavenger films combined with humidity-indicator labels are enabling ambient distribution for preservative-free pie formulations.
Industry Challenges
- Multilayer coextrusion technician scarcity:Operating precision barrier film lines requires 18-24 month training pipelines that outpace available vocational program throughput.
- Food-contact notification timeline compression:FDA 21 CFR submissions for novel grease-resistant chemistries now average 14-18 months, misaligning with retailer sustainability deadline commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pie Packaging Market |
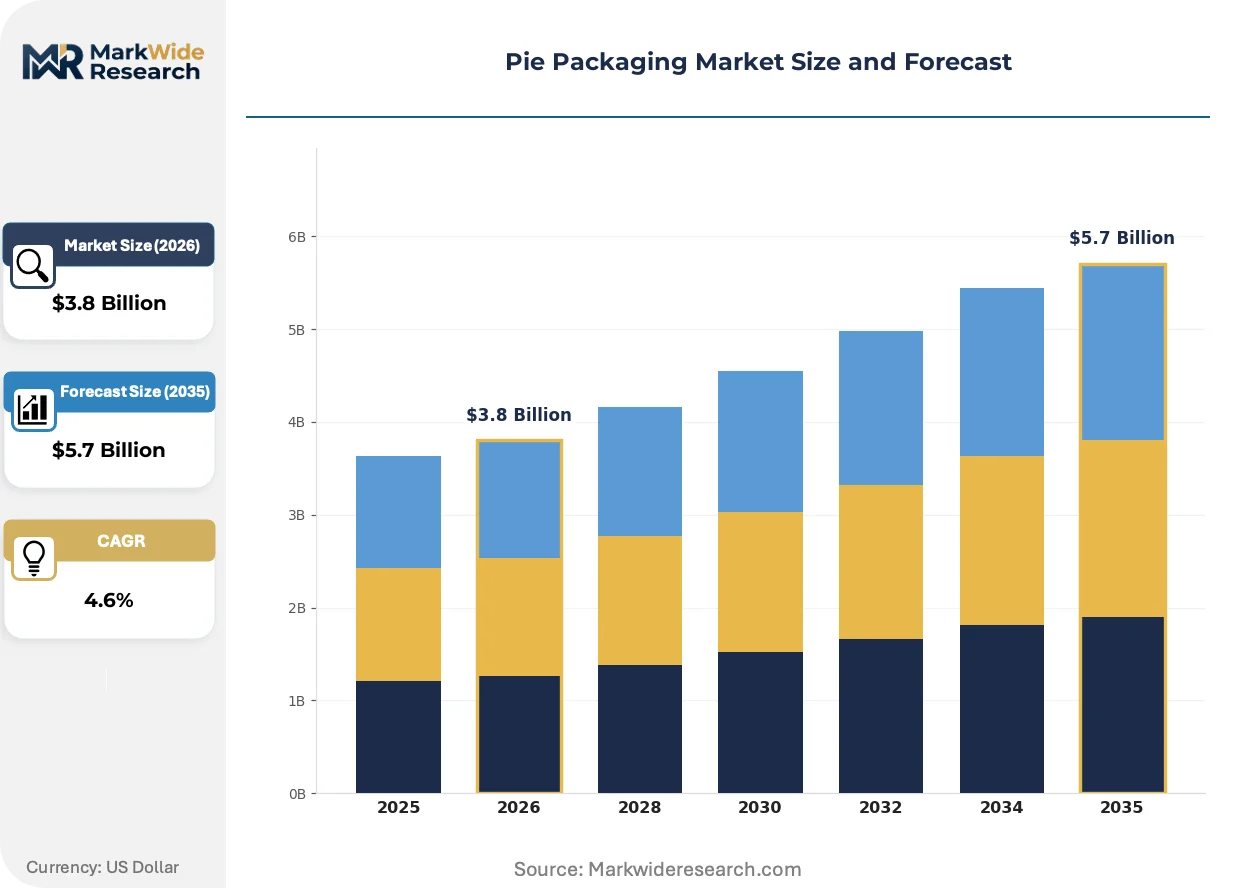
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Clamshells, Pouches, Trays Material: Cardboard, Plastic, Aluminum, Biodegradable Closure Type: Heat Seal, Snap-On, Lids, Tuck Top End User: Bakeries, Retailers, Food Service, Online Delivery |
| Companies Covered | Shijiazhuang Chuangmei Paper Products Co., Ltd., Jessica Liu Dongguan A1 Packing & Stationery Co., Ltd., PieBox Ltd., Albany Packaging, Cassel Bear Ltd., Amcor plc, Berry Global Inc., WestRock Company, Huhtamaki Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pie Packaging Market Evolving Landscape
Barrier material innovation is bifurcating between petroleum-derived high-performance films and emerging bio-based alternatives, with regulatory pressure accelerating the transition timeline beyond what current manufacturing infrastructure can absorb.
Water-based barrier coatings derived from nanocellulose and alginate biopolymers are fragmenting the incumbent fluorochemical-treated paperboard segment. Boutique organic pie brands and regional co-packers are piloting these formats for 90-day shelf life claims. The technology is fragmenting converter customer bases into sustainability-prioritized versus performance-prioritized procurement camps with incompatible specification requirements.
The EU Green Deal's 2030 packaging recyclability targets are forcing redesign of single-use pie trays around mono-material fiber recovery streams. German and French converters are retooling thermoforming lines to produce pressed pulp domes with integrated locking tabs. Frozen pie exporters to the EU are absorbing redesign costs to maintain market access, while domestic US producers face diverging specification demands.
Club-store buyers are consolidating supplier relationships around vertically integrated packaging partners capable of delivering primary containment, shelf-ready display, and pallet optimization as bundled programs. This procurement concentration is displacing specialized clamshell-only vendors from national account consideration. The shift is most visible in Texas and Florida distribution hubs where Costco and BJ's Wholesale Club operate consolidated frozen bakery procurement centers.
Pie Packaging Market Segmentation
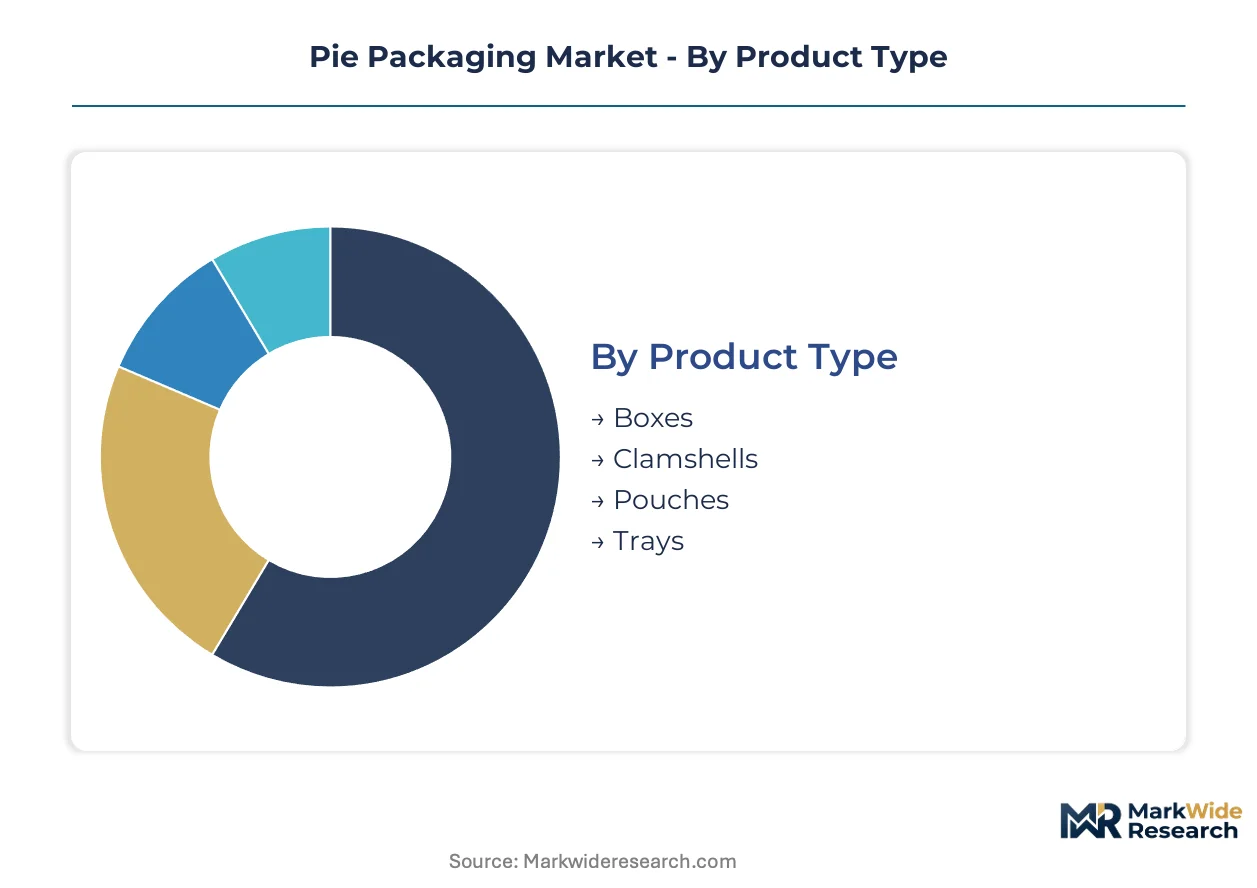
Pie packaging segmentation reveals how technical specifications diverge across frozen, fresh, and ambient distribution channels. Material and format selection directly determines barrier performance, recyclability compliance, and total landed cost for pie manufacturers.
Product Type:
Substitution pressure from fiber-based alternatives is reshaping format preferences as retailers enforce plastic reduction timelines.
- Boxes:Paperboard constructions with grease-resistant coatings rated for butter-fat content above 18% serve frozen pie gifting and seasonal retail programs. Costco and Sam's Club procurement centers in Texas and Florida are consolidating supplier relationships around lithographic display cases with die-cut windows for club-store pie programs.
- Clamshells:Thermoformed PET or PP structures with reclosable hinges dominate quick-service deli channels and grab-and-go hot-held pie applications. Convenience store chains are standardizing specifications with anti-fog coatings and vented domes for visual merchandising advantages.
- Pouches:Flexible multilayer films with vapor transmission barriers below 2 g/m²/day protect single-serve pie slices in vending and convenience formats.
- Trays:Molded pulp or pressed fiber platforms with integrated locking tabs support EU Green Deal recyclability targets for frozen pie exports.
Clamshells retain volume leadership across food service channels; biodegradable tray alternatives hold the steepest expansion curve as EU PPWR compliance deadlines approach.
Material:
Cost tier stratification separates premium barrier specifications from economy-grade fiber alternatives in procurement decisions.
- Cardboard:Solid bleached sulfate and coated unbleached kraft grades provide structural integrity for secondary shipping cases with stack-load capacities of 15-25 kg. WestRock's integrated paperboard and display packaging combinations reduce total landed cost for club-store programs.
- Plastic:Multilayer coextrusion films incorporating ethylene vinyl alcohol copolymers deliver vapor transmission performance required for extended shelf stability without refrigeration. Amcor plc serves high-volume frozen pie accounts across the United States through this technology.
- Aluminum:Foil-laminated structures provide absolute moisture and oxygen barriers for premium frozen pie exports with transit times exceeding 48 hours.
- Biodegradable:Nanocellulose and alginate biopolymer coatings are fragmenting the incumbent fluorochemical-treated paperboard segment as boutique organic brands pilot 90-day shelf life claims.
Plastic materials command premium pricing tiers for barrier-critical applications; biodegradable alternatives are gaining share fastest in private-label and sustainability-prioritized procurement camps.
Closure Type:
Application requirements determine seal integrity versus reclosability trade-offs across distribution channels.
- Heat Seal:Induction or conduction sealing creates hermetic barriers for frozen pie distribution through e-commerce fulfillment requiring temperature integrity across 48-hour transit windows.
- Snap-On:Injection-molded PP lids with perimeter locking rings enable repeated access for multi-serve pie formats in retail deli cases.
- Lids:Separate thermoformed or pressed pulp covers support hot-held and chilled applications with venting options for steam management.
- Tuck Top:Paperboard friction-fit closures reduce material cost for ambient shelf-stable pie formats with shorter distribution cycles.
Snap-on closures dominate food service reclosability requirements; heat seal formats are expanding most quickly in direct-to-consumer frozen pie shipping channels.
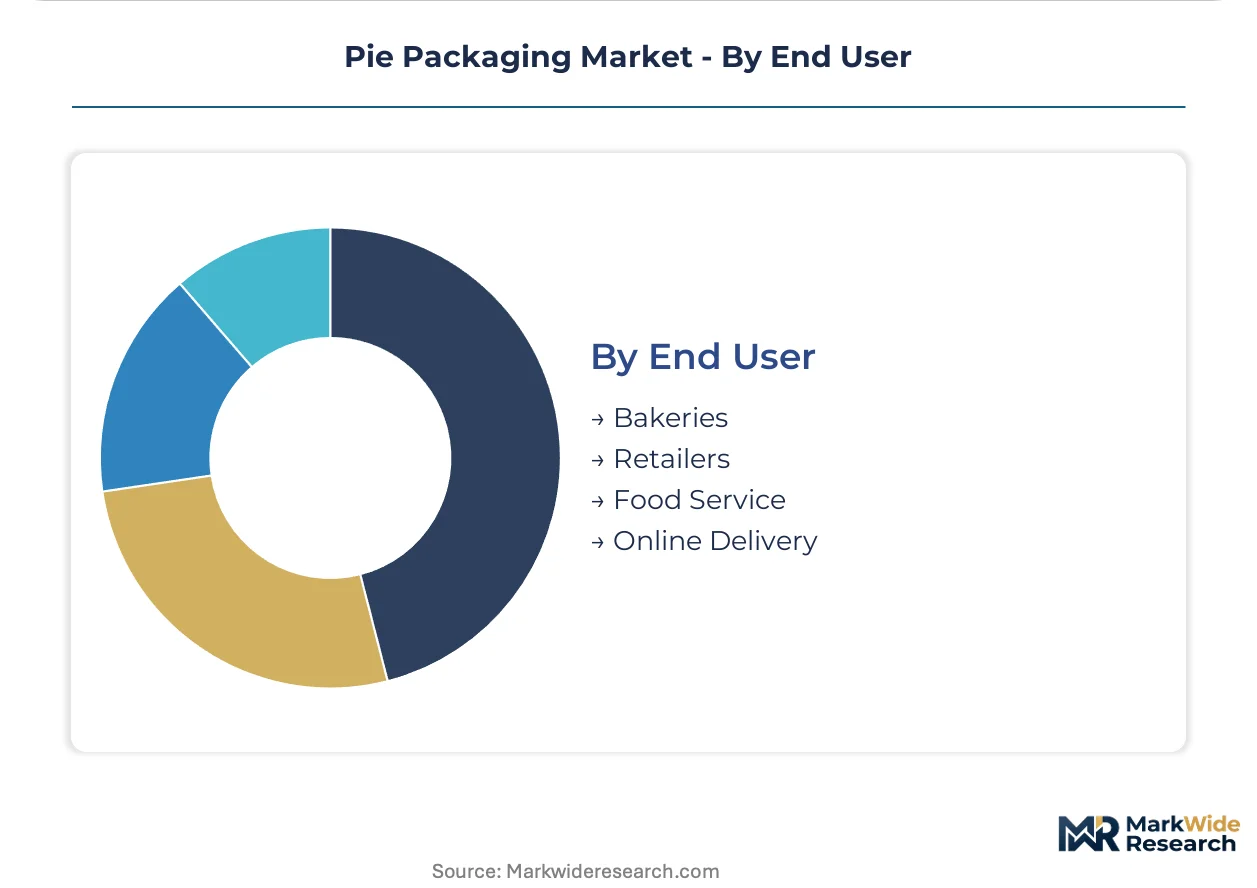
End User:
Customer type dictates volume scale, specification complexity, and sustainability credential requirements in supplier relationships.
- Bakeries:In-store bakery counters at Kroger, Albertsons, and Publix are expanding private-label pie offerings and requiring shorter-run, higher-SKU packaging formats with faster changeover cycles.
- Retailers:Consolidated procurement at major grocery chains compresses supplier margins while demanding simultaneous investment in barrier innovation and sustainability credentials.
- Food Service:Quick-service deli channel expansion at convenience stores is standardizing clamshell specifications with anti-fog coatings for grab-and-go hot-held pie programs.
- Online Delivery:E-commerce fulfillment requirements are pulling demand for insulated box liners and phase-change material integration in direct-to-consumer frozen pie shipping.
Retailers retain volume leadership through consolidated national account procurement; online delivery channels hold the steepest expansion curve as frozen pie consumption in direct-to-consumer formats continues to expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frozen pie export flows from the United States and European Union dominate cross-border trade volumes, while import-dependent markets in Asia-Pacific and Middle East absorb premium packaged formats. Regulatory divergence between FDA grease-resistant standards and EU PPWR fiber-recovery mandates is forcing manufacturers to maintain parallel packaging specifications. Distribution infrastructure investments cluster around coastal logistics hubs serving temperature-controlled supply chains.
United States
Frozen pie consumption through direct-to-consumer channels and club-store gifting programs sustains import demand for high-barrier multilayer films. EPA phase-outs of PFAS-based grease-resistant treatments are accelerating reformulation timelines for butter-fat barrier coatings. Texas and Florida distribution hubs for Costco and BJ's Wholesale Club procurement centers are consolidating supplier relationships around vertically integrated packaging partners.
Germany
EU Green Deal 2030 recyclability targets are redirecting converter R&D budgets toward molded pulp and pressed fiber tray systems for frozen pie exports. The country's national packaging regulator enforces strict fiber-recovery minimums under PPWR implementation timelines. Bavaria-based thermoforming operations are retooling lines to produce pressed pulp domes with integrated locking tabs for hot-held and chilled applications.
France
Boutique organic pie brands are piloting nanocellulose and alginate biopolymer coatings for 90-day shelf life claims in premium retail channels. ECHA restrictions on fluorochemical treatments align with corporate sustainability commitments from major food manufacturers. The Île-de-France region hosts pilot production facilities for water-based barrier coatings fragmenting incumbent paperboard segments.
United Kingdom
Post-Brexit regulatory divergence from EU PPWR standards is creating parallel compliance pathways for pie packaging exporters. Domestic demand concentrates in seasonal gifting segments where lithographic display cases command price premiums. Midlands-based converters are developing integrated paperboard and display packaging combinations for club-store programs.
China
Domestic frozen bakery consumption is pulling demand for imported barrier film technologies and phase-change material integration in e-commerce fulfillment. The country's national food safety regulator maintains food-contact substance standards under GB protocols for imported packaging materials. Yangtze River Delta manufacturing clusters are expanding capacity for ethylene vinyl alcohol copolymer films serving regional frozen pie processors.
Pie Packaging Market Competitive Landscape
Listed leaders compete with private specialists across barrier technology and sustainability credential dimensions, creating a tiered structure where scale advantages clash with customization agility. Three strategic archetypes dominate: multinational converters with multilayer coextrusion expertise, integrated paperboard suppliers with display packaging capabilities, and regional molded fiber specialists serving EU compliance deadlines. Competitive moves concentrate on backward integration into raw material supply and strategic partnerships with retailer private-label programs.
Within the multinational converter tier, Amcor plc and Huhtamaki Group exemplify scale-driven positioning across frozen and chilled pie applications. WestRock Company occupies a position bridging integrated paperboard supply with club-store display packaging. Among specialized regional fabricators, PieBox Ltd. and Cassel Bear Ltd. represent the private specialist archetype focused on premium gifting formats. Albany Packaging anchors North American demand for corrugated secondary shipping cases with stack-load optimization. These named entities serve as reference points for structural analysis without implying specific strategic actions or market positions.
| Leading Market Players |
|---|
| Shijiazhuang Chuangmei Paper Products Co., Ltd. |
| Jessica Liu Dongguan A1 Packing & Stationery Co., Ltd. |
| PieBox Ltd. |
| Albany Packaging |
| Cassel Bear Ltd. |
| Amcor plc |
| Berry Global Inc. |
| WestRock Company |
| Huhtamaki Group |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR food-contact substance compliance gates both supplier qualification and price differentiation simultaneously, as converters must absorb 14-18 month notification timelines while retailers demand simultaneous barrier innovation and sustainability credentials. This regulatory threshold stratifies the vendor base into certified incumbents commanding premium positioning versus uncertified competitors trapped in commodity tiers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers driven by barrier specification grade and EVOH copolymer content. Price differentiation stems from vapor transmission performance certification and volume scale commitments. Cost compression in the standard tier is intensifying because Kroger and Albertsons procurement consolidation demands shorter-run flexibility without corresponding price adjustment. Private-label bakery programs exhibit highest price sensitivity; premium frozen pie exporters to the EU show least sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Strait of Malacca transit underwrites ethylene vinyl alcohol copolymer feedstock flows from South Korean and Japanese petrochemical complexes to North American converters. Raw material sourcing draws from limited Asian ethylene vinyl alcohol production, PFAS-free grease-resistant coating chemistries, and phase-change materials for insulated shipping. Single-source vulnerability concentrates in EVOH resin supply where three complexes serve global demand. Distribution runs through temperature-controlled coastal logistics hubs serving frozen pie export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multilayer coextrusion technician scarcity constrains capacity expansion timelines, with 18-24 month training pipelines misaligned with retailer sustainability deadline commitments. This capability gap rewards early movers who secured vocational pipeline partnerships.
For Market Incumbents: Fortify barrier film capacity in Texas and Florida distribution corridors where Costco and BJ's Wholesale Club procurement consolidation is displacing specialized clamshell-only vendors. Deepen upstream control over EVOH copolymer supply through captive offtake agreements with South Korean petrochemical complexes. Invest in FDA 21 CFR pre-submission programs to compress novel grease-resistant chemistry timelines below the 14-month average. For New Entrants and Emerging Players: Anchor in the club-store pie gifting segment where Costco and Sam's Club seasonal programs currently use generic corrugated, creating white-space for lithographic display cases with die-cut windows. Target California extended producer responsibility implementation under SB 54, where compliance cost burdens on brand owners create packaging-as-a-service revenue streams. Lead with consulting-led packaging redesign rather than commodity supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molded fiber specialists who retooled German and French thermoforming lines for EU PPWR compliance ahead of 2030 deadlines. Long-term viability hinges on fiber-recovery technology ownership rather than plastic barrier film exposure. Watch EU Packaging and Packaging Waste Regulation enforcement velocity as the inflection indicator for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Copolymer Supply | Captive resin access insulates Amcor and Huhtamaki from Asian petrochemical volatility. |
| EU PPWR-Compliant Molded Pulp Line Conversion | Bavaria-based thermoforming operations capture frozen pie export demand from US manufacturers. |
| California SB 54 Compliance Service Launch | Packaging-as-a-service models shift cost burden from brand owners to converter balance sheets. |
| Nanocellulose Barrier Coating Pilot Scale-Up | Île-de-France production facilities fragment incumbent fluorochemical-treated paperboard segments. |
| Direct-to-Consumer Insulated Shipping Format Development | Phase-change material integration captures e-commerce fulfillment growth in frozen pie channels. |
Research Methodology
The analysis maps barrier film specifications, molded fiber tray systems, and corrugated display formats, each validated through converter operations directors, bakery procurement managers at Kroger and Albertsons, and quick-service deli channel buyers. Primary interviews with FDA regulatory affairs consultants and EU PPWR compliance officers combined with secondary validation from EPA PFAS phase-out documentation, EU Green Deal implementation timelines, and customs trade data for ethylene vinyl alcohol copolymer flows. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, material grade tier, closure mechanism, and end-user channel. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs incorporated retailer private-label expansion timelines and EU fiber-recovery target compliance costs.
Decision-makers should treat outputs as directional under assumptions of steady EPA PFAS phase-out enforcement and EU PPWR timeline adherence; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as state-level extended producer responsibility implementation and EVOH supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Egg Cartons Market