
 Ice Cream Cones Market | 2026-2036
Ice Cream Cones Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Cones Market Insights
Italy is fragmenting the traditional ice cream cone supply base as artisanal gelato culture spreads cone demand across smaller, specialized bakeries rather than consolidated manufacturers. Joy Cone Company leverages its North American production scale to sustain bulk supply contracts with major quick-service chains. Unilever competes through backward integration into in-house cone production for its premium frozen dessert portfolio.
An ice cream cone is a thin, edible vessel formed from batter-based doughs—typically wheat flour, sugar, oil, and emulsifiers—baked into rigid, conical shapes to hold frozen dessert servings; specifications range from 2.5-inch mini cones to 6-inch oversized formats with wall thicknesses between 1.2mm and 2.0mm. Waffle cones command premium shelf positioning due to higher egg-butter content and structural rigidity, while cake cones dominate volume through cost-efficient, neutral-flavor profiles suited to mass-market supermarket channels. Sugar cones occupy a narrowing mid-tier as consumer preference polarizes between artisanal waffle formats and value-oriented cake alternatives.
FDA food-contact substance regulations and EU framework standards under EFSA govern cone ingredient safety, additive limits, and labeling for direct food contact, compelling manufacturers to reformulate emulsifier systems and strengthen supply-chain documentation. The EU Green Deal packaging directives are pressuring cone producers toward fiber-based or compostable individual wrappers, reshaping procurement criteria for retail and foodservice buyers. Stakeholders must monitor evolving biodegradable packaging mandates and decide whether to invest in wrapper conversion ahead of regulatory deadlines or absorb compliance costs through supplier pass-through.
Market Dynamics
Foodservice channel expansion and tightening food-contact regulations are restructuring procurement relationships across the ice cream cone supply base, forcing manufacturers to reconcile artisanal quality demands with mass-scale compliance documentation.
Growth Catalysts
- EU Green Deal packaging mandates:Compostable wrapper requirements are accelerating R&D investment in fiber-based packaging solutions, opening premium positioning for early-compliant producers.
- Artisanal gelato culture:Italy's specialized bakery networks are fragmenting demand toward small-batch cone suppliers, creating niche growth corridors outside consolidated manufacturing.
- Quick-service chain standardization:Bulk procurement contracts from major foodservice operators are stabilizing volume throughput for large-scale wafer and sugar cone producers.
Market Restraints
- Wheat flour input volatility:Commodity price swings in grain markets compress margin predictability for batter-based cone formulations.
- Supply concentration in North America:Dominant production clusters create geographic risk exposure for buyers seeking supply diversification.
- Technical limitation in gluten-free structurals:Alternative flours lack the protein network to achieve equivalent rigidity in waffle cone formats without additive loading.
Strategic Opportunities
- Underpenetrated Southeast Asian foodservice:Emerging ice cream parlor chains in Thailand and Vietnam present first-mover expansion potential for premium waffle cone exporters.
- Regulatory tailwind from FDA food-contact modernization:Updated substance notification pathways reward proactive emulsifier reformulation with accelerated market access.
- Direct-to-creamery distribution platforms:Digital procurement channels are disintermediating traditional broker networks, enabling margin capture by specialized cone artisans.
Industry Challenges
- Certification timeline compression:EFSA additive re-evaluations and FDA notification reviews are extending product launch cycles for reformulated emulsifier systems.
- Equipment reconfiguration capex:Compostable wrapper conversion requires thermal sealing line upgrades that strain mid-tier producer balance sheets.
- Cross-functional formulation expertise:Shortage of food chemists versed in both structural engineering and biodegradable packaging compatibility limits innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Cones Market |
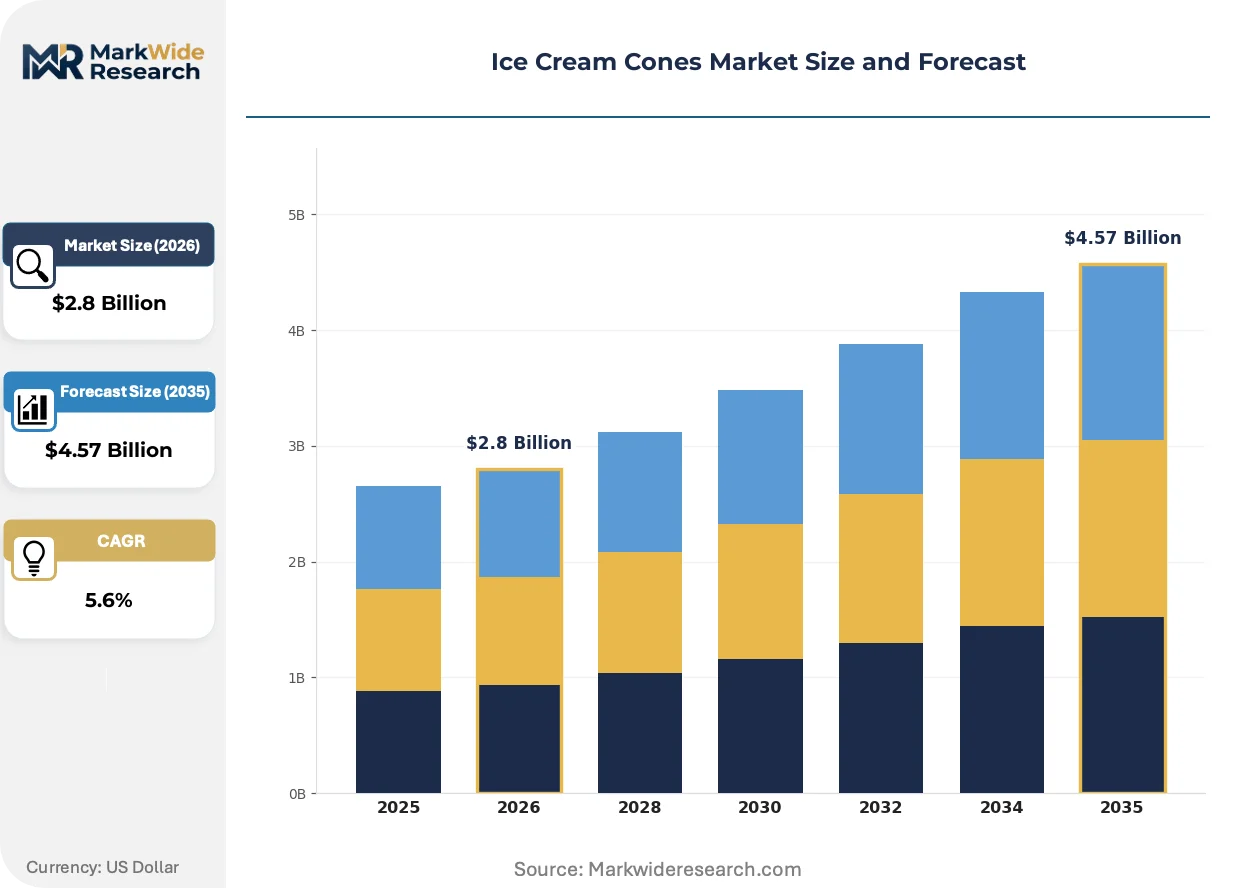
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waffle Cones, Sugar Cones, Cake Cones, Chocolate-Dipped Cones End User: Retail Outlets, Foodservice, Ice Cream Shops, Supermarkets Flavor Profile: Vanilla, Chocolate, Strawberry, Mixed Flavors Packaging Type: Bags, Boxes, Bulk Packaging, Individual Wrappers |
| Companies Covered | Joy Cone Company, Edward & Sons, Nestle, M&M, Blue Bunny, Unilever, Kri Kri, Magnolia, Häagen-Dazs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Cones Market Trends and Innovations
Automation and sustainability mandates are converging to reshape production economics and material specifications across the ice cream cone value chain. Three developments warrant particular attention.
Vision-guided robotic batter deposition is digitizing quality consistency in waffle cone manufacturing, replacing manual ladle operators with precision-controlled dispensing systems. Mid-scale creamery suppliers are adopting these units to reduce thickness variation and reject rates. The technology is digitizing the interface between artisanal product specifications and mass-production throughput, compressing the cost gap between premium and standard formats.
REACH substance restriction updates are tightening emulsifier approval thresholds for direct food-contact applications in European markets. Manufacturers must substitute legacy lecithin sources with certified-clean alternatives or exit EU supply chains. Cake cone producers serving retail supermarkets face the steepest reformulation burden, with several accelerating supplier audits ahead of 2027 implementation deadlines.
Specialty creameries are consolidating procurement through cooperative buying platforms that aggregate volume across independent operators. These digital collectives are displacing traditional distributor relationships in the United States, where regional gelato chains negotiate directly with cone artisans. The shift is most visible in California and New York metro clusters, where platform-mediated sourcing now captures significant premium waffle cone volume.
Ice Cream Cones Market Segmentation
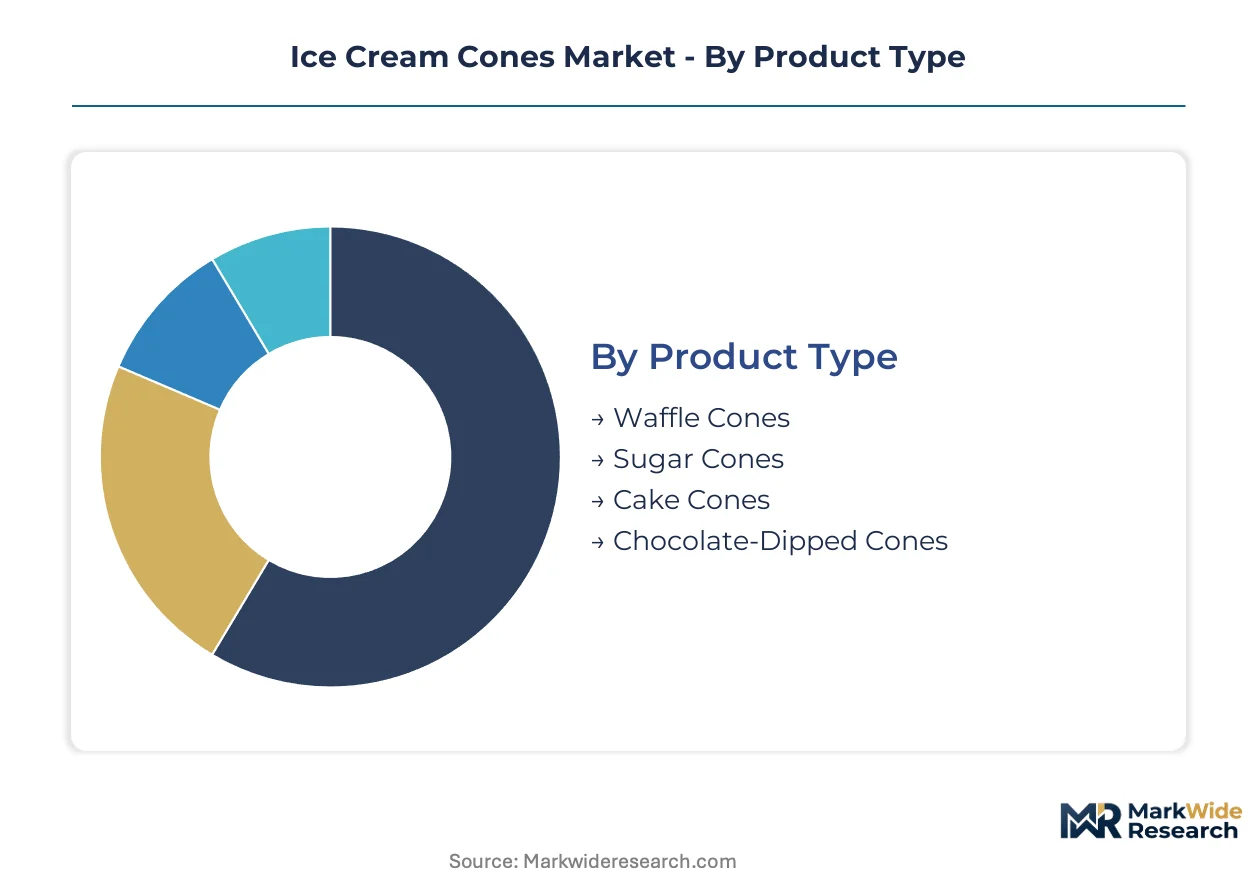
Segmentation in the ice cream cone market reveals how formulation choices, distribution channels, and packaging specifications create distinct competitive arenas with divergent margin profiles and regulatory exposure.
Product Type:
The use-case spectrum spans artisanal premium formats to mass-market utility vessels, with structural composition dictating thermal stability and flavor compatibility.
- Waffle Cones:These cones incorporate egg-butter enriched batters baked into lattice-patterned structures with 2.0mm wall thickness. Demand concentrates at specialty creameries in California and New York metro clusters, driven by consumer willingness to pay structural premiums for artisanal presentation.
- Sugar Cones:Mid-tier formats with higher sucrose content and caramelized surfaces occupy narrowing shelf positioning. Quick-service chains in the United States are standardizing procurement around this format for operational consistency.
- Cake Cones:Neutral-flavor, cost-efficient vessels with minimal egg content dominate supermarket retail channels through volume-scale production economics.
- Chocolate-Dipped Cones:Value-added formats with compound coating on rim or full-dip configurations command impulse purchase positioning at convenience retail.
The dominant share belongs to cake cones, while waffle cones are closing the gap fastest.
End User:
Customer type determines order frequency, specification tolerance, and compliance documentation burden across the value chain.
- Foodservice:Restaurants, cafeterias, and institutional operators purchase in bulk with strict diameter and breakage-rate specifications. Procurement is consolidating through cooperative buying platforms that displace traditional distributor networks.
- Ice Cream Shops:Independent and chain creameries source premium waffle formats with customized branding opportunities. Italian gelato culture is fragmenting this segment toward specialized bakery suppliers rather than consolidated manufacturers.
- Retail Outlets:Convenience stores and gas stations stock impulse formats with extended shelf-life packaging requirements.
- Supermarkets:Mass-market retailers demand cake cone multipacks with compostable wrapper compliance under EU Green Deal timelines.
Foodservice captures the highest volume throughput, yet ice cream shops generate the steepest expansion trajectory in premium tier sourcing.
Flavor Profile:
Ingredient layering strategies create differentiation without altering structural engineering, appealing to seasonal and demographic targeting.
- Vanilla:The baseline flavor standard provides neutral compatibility across ice cream varieties and dominates unflavored cone formulations.
- Chocolate:Cocoa-infused batters or coating applications target younger demographics and premium positioning at specialty retailers.
- Strawberry:Fruit-derived flavoring systems occupy seasonal limited-edition positioning with shorter production runs.
- Mixed Flavors:Swirled or dual-tone formats support brand differentiation campaigns at chain creameries seeking visual distinction.
Vanilla maintains the foundational position, though chocolate is gaining share fastest through coating and batter integration innovations.
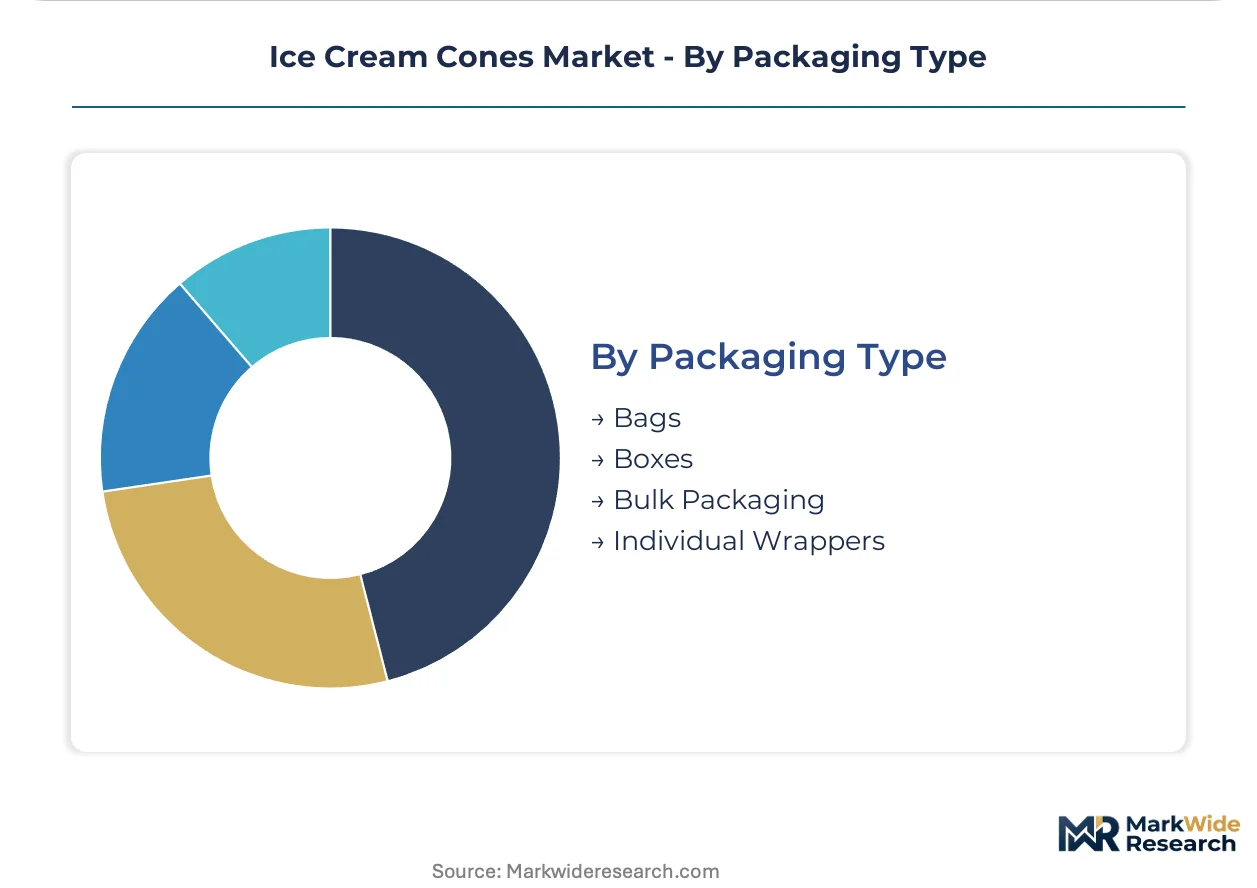
Packaging Type:
Material specifications are restructuring under sustainability mandates, with regulatory deadlines forcing capital allocation decisions.
- Individual Wrappers:Single-unit protection using fiber-based or compostable materials is becoming mandatory under EU Green Deal directives. Thermal sealing line upgrades strain mid-tier producer balance sheets.
- Bulk Packaging:Foodservice cartons without individual wrapping minimize unit economics for high-throughput operators with rapid inventory turnover.
- Boxes:Retail multipacks with display-ready graphics support supermarket shelf positioning and seasonal promotional cycles.
- Bags:Flexible film formats for value-tier cake cones face substitution pressure as biodegradable alternatives achieve cost parity.
Individual wrappers command regulatory attention and R&D investment, while bulk packaging retains the largest volume footprint in foodservice procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact modernization anchors the United States as the regulatory reference point for cone safety standards, while EU Green Deal packaging directives reshape procurement economics across Atlantic supply chains. Artisanal gelato culture fragments Mediterranean demand toward specialized bakery networks. Asian foodservice expansion creates first-mover corridors for premium waffle format exporters.
United States
Specialty creameries in California and New York metro clusters drive premium waffle cone procurement, with cooperative buying platforms displacing traditional distributor networks. FDA food-contact substance regulations compel emulsifier reformulation and strengthened supply-chain documentation. Joy Cone Company leverages North American production scale to sustain bulk supply contracts with major quick-service chains.
Italy
Artisanal gelato culture spreads cone demand across smaller, specialized bakeries rather than consolidated manufacturers, fragmenting the traditional supply base. EFSA framework standards govern ingredient safety and additive limits for direct food contact. Regional bakery networks in Lombardy and Veneto capture niche growth corridors through small-batch production.
Germany
REACH substance restriction updates tighten emulsifier approval thresholds, forcing substitution of legacy lecithin sources with certified-clean alternatives. EU Green Deal packaging directives pressure producers toward fiber-based or compostable individual wrappers. Industrial clusters in Bavaria and North Rhine-Westphalia accelerate thermal sealing line upgrades ahead of 2027 compliance deadlines.
Thailand
Emerging ice cream parlor chains present first-mover expansion potential for premium waffle cone exporters seeking underpenetrated Southeast Asian foodservice. The country's national food safety regulator enforces additive notification pathways for imported food-contact materials. Bangkok-based foodservice operators standardize procurement around sugar cone formats for operational consistency.
France
ANSM oversight of food-contact materials intersects with CSRD sustainability disclosure requirements, elevating documentation burdens for cone suppliers serving retail supermarket channels. Île-de-France and Auvergne-Rhône-Alpes concentrate artisanal creamery demand for chocolate-dipped and premium waffle formats. Regional cooperative buying platforms aggregate volume across independent operators.
Ice Cream Cones Market Competitive Landscape
Capability concentration sits with artisanal specialists who command premium positioning through structural engineering expertise; scale advantage sits with mass-market producers who dominate volume throughput through automated batter deposition systems. The vendor base stratifies across three tiers: consolidated manufacturers serving quick-service chains, mid-scale creamery suppliers adopting vision-guided robotics, and fragmented artisanal bakeries capturing gelato culture demand. Two competitive moves define current positioning: backward integration into in-house cone production by frozen dessert multinationals, and cooperative platform formation by independent creameries to disintermediate traditional distribution.
Among North American specialists, Joy Cone Company anchors the scale-driven tier through bulk supply relationships with major foodservice operators. Unilever exemplifies backward integration strategy through captive cone production for its premium frozen dessert portfolio. Edward & Sons occupies a position within the alternative-format segment, representing the specialist archetype focused on dietary-specific and organic positioning.
| Leading Market Players |
|---|
| Joy Cone Company |
| Edward & Sons |
| Nestle |
| M&M |
| Blue Bunny |
| Unilever |
| Kri Kri |
| Magnolia |
| Häagen-Dazs |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in North American wafer cone production is compressing contract renewal terms for bulk foodservice suppliers while simultaneously elevating premium positioning for artisanal waffle formats with constrained Italian bakery output. This utilization asymmetry between mass-scale and craft segments dictates divergent pricing postures across procurement tiers.
Pricing Analysis
Geographic price spreads between Italian artisanal waffle cones and North American mass-produced cake formats exceed threefold at wholesale tier. Three-tier pricing structure across premium, standard, and economy levels anchors on formulation complexity, with egg-butter content and wall thickness as primary differentiation drivers. Cost compression in cake cone segments is intensifying because wheat flour commodity volatility passes through without brand premium absorption. Quick-service chains exhibit highest price sensitivity through consolidated volume leverage, while specialty creameries in California and New York metro clusters demonstrate lowest sensitivity due to presentation-value capture.
Supply Chain Analysis
EU REACH substance restriction updates on emulsifier approvals function as de facto export controls limiting legacy lecithin sourcing flows into European markets. Supply concentrates in the United States, Italy, and Germany, with production drawing from wheat flour milled in the Great Plains, egg processors in the Midwest, and specialty butter suppliers in Lombardy. Single-source vulnerability concentrates in North American automated batter deposition equipment, where vision-guided robotics suppliers number fewer than five globally. Distribution runs through cooperative buying platforms that disintermediate traditional broker networks for independent creamery procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward foodservice operators consolidating procurement through cooperative platforms, fragmenting manufacturer leverage across the ice cream cone supply base.
For Market Incumbents: Insulate bulk contract margins by securing multi-year supply agreements with quick-service chains ahead of EU Green Deal wrapper compliance deadlines. Accelerate thermal sealing line upgrades to capture early-compliant premium positioning. Backward integration into captive egg processing buffers input cost volatility from Midwest supplier concentration. For New Entrants and Emerging Players: Establish a beachhead in Thailand's emerging ice cream parlor segment before incumbent exporters consolidate distribution relationships. Target Vietnam's underpenetrated premium waffle cone demand through direct-to-creamery digital platforms. Lead with compostable wrapper compliance as differentiated entry credential against legacy suppliers facing 2027 conversion capex burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among artisanal waffle cone specialists serving cooperative buying platforms in California and New York metro clusters. Five-to-ten-year viability favors mid-scale producers with installed vision-guided robotics and established EFSA-compliant emulsifier formulations. Watch FDA food-contact substance notification pathway acceleration as inflection signal for reformulation-ready acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Wrapper Conversion | EU Green Deal compliance deadlines force thermal sealing line upgrades ahead of 2027 implementation. |
| Vision-Guided Robotics Deployment | Automated batter deposition reduces thickness variation and reject rates for mid-scale creamery suppliers. |
| Cooperative Platform Integration | Direct-to-creamery digital channels disintermediate traditional broker networks in United States metro clusters. |
| EFSA-Compliant Emulsifier Reformulation | REACH substance restrictions compel substitution of legacy lecithin sources to maintain EU market access. |
| Southeast Asian Foodservice Expansion | First-mover positioning in Thailand and Vietnam captures emerging ice cream parlor chain procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact substance filings, EFSA additive safety assessments, EU Green Deal packaging directive drafts, and North American grain commodity trade data. Interviews conducted with specialty creamery procurement managers, quick-service chain supply chain directors, waffle cone production plant managers, and food-contact regulatory consultants informed demand-side and compliance dynamics. Bottom-up volume modeling from individual producer capacity and top-down market sizing from foodservice channel throughput were cross-validated for convergence.
Forecast inputs include artisanal versus mass-market format mix shifts, EU packaging mandate implementation timelines, and Southeast Asian foodservice expansion trajectories across the analysis window. Segmentation dimensions encompass product type, end-user channel, flavor profile, and packaging specification. CAGRs were derived from weighted scenario analysis across regulatory compliance and channel migration assumptions. Wheat flour commodity volatility and emulsifier reformulation cost pass-through were modeled as industry-specific demand elasticity factors.
Stress conditions across EFSA additive re-evaluation timelines, EU biodegradable packaging cost parity achievement, and Southeast Asian import tariff regimes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cooperative platform adoption rates and vision-guided robotics penetration curves. Material shifts in FDA food-contact modernization implementation pace or REACH substance restriction scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Specialty Bakery Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Cake Concentrate Market
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
North America Bakery Products Market
Bakery Products
United States Bread Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Global Cake Mix Market
Bakery Products
Wedding Cakes Market