
 Premix Bread Flour Market | 2026-2036
Premix Bread Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Premix Bread Flour Market Analysis
Millwright and process engineering talent shortages across industrial milling is reorganizing capital deployment timelines for premix bread flour manufacturers. Lesaffre Group leverages its yeast-to-premix vertical network to secure captive supply of fermentation-active ingredients. Associated British Foods plc anchors British retail channels through its AB Mauri division, while Puratos Group differentiates through sourdough starter integration and clean-label enzyme systems. Archer Daniels Midland Company competes on North American grain origination and in-house wheat protein extraction.
Premix bread flour consists of wheat flour or alternative grain bases pre-blended with functional ingredients including emulsifiers, enzymes, oxidizing agents, and nutrient fortificants at specified inclusion rates typically between 0.5% and 5% by weight, designed to deliver consistent dough rheology and finished loaf characteristics without separate ingredient scaling. Its primary commercial purpose is to standardize bakery output while reducing labor, inventory complexity, and batch-to-batch variation in high-throughput operations. Whole wheat and high-protein variants command margin premiums as health-positioned retail products, whereas gluten-free formulations sustain the fastest growth trajectory amid celiac awareness and free-from portfolio expansion by supermarket chains. Organic premix lines occupy a smaller volume position but attract dedicated shelf space through specialty stores and direct-to-baker distribution.
EU REACH and EFSA novel food evaluations govern enzyme and additive approvals for premix formulations sold across member states, while FDA GRAS self-affirmation and FSMA preventive controls shape U.S. import and domestic manufacturing compliance burdens. BIS fortification standards in India and China's GB food safety standards for wheat-based products create divergent formulation requirements that fragment regional product specifications. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon footprint disclosure rules that will soon differentiate market-accessible premix offerings from excluded alternatives.
Market Dynamics
Millwright and process engineering talent shortages across industrial milling are compressing capital deployment timelines and forcing premix manufacturers toward modular equipment architectures. This labor scarcity intersects with tightening EU energy standards to reshape facility investment patterns.
Growth Catalysts
- EU Green Deal energy mandates:Industrial bakeries face binding efficiency targets that accelerate replacement of legacy mixing and proofing equipment, creating pull-through demand for optimized premix formulations designed for lower-temperature processing.
- Artisan bakery segment expansion:Craft chains in Germany and France are standardizing procurement through centralized commissaries that specify premix-based production to maintain consistency across multiple retail locations.
- Enzyme stabilization advances:Novel encapsulation technologies extend enzyme activity windows in frozen dough applications, enabling premix suppliers to penetrate extended-shelf-life channels previously served by scratch formulations.
Market Restraints
- Wheat protein concentrate volatility:Drought cycles in Black Sea origination zones create input cost swings that compress premix margin structures and complicate annual contract pricing.
- Gluten-free supply concentration:Tapioca and rice starch sourcing depends on Southeast Asian processors, exposing European premix manufacturers to container freight disruptions and currency translation risks.
- EFSA novel food evaluation timelines:Fermentation-derived ingredients face 18-24 month approval windows that delay product launches and tie up R&D expenditure without revenue offset.
Strategic Opportunities
- Direct-to-baker distribution platforms:Specialty stores and regional craft chains are bypassing traditional ingredient distributors, creating margin capture opportunities for premix suppliers with last-mile logistics capabilities.
- Carbon footprint disclosure mandates:Upcoming CSRD requirements will differentiate low-carbon premix offerings, rewarding suppliers with verified supply chain data and renewable energy procurement.
- Sourdough starter integration:Freeze-dried live culture systems enable clean-label positioning without refrigeration infrastructure, opening convenience-oriented retail channels to premium positioning.
Industry Challenges
- Millwright and process engineering scarcity:Industrial milling equipment installation and commissioning face 6-9 month delays as specialized technicians command premium wages and limited availability.
- Legacy ERP integration friction:Premix batch control systems must interface with decades-old bakery production software, requiring custom middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premix Bread Flour Market |
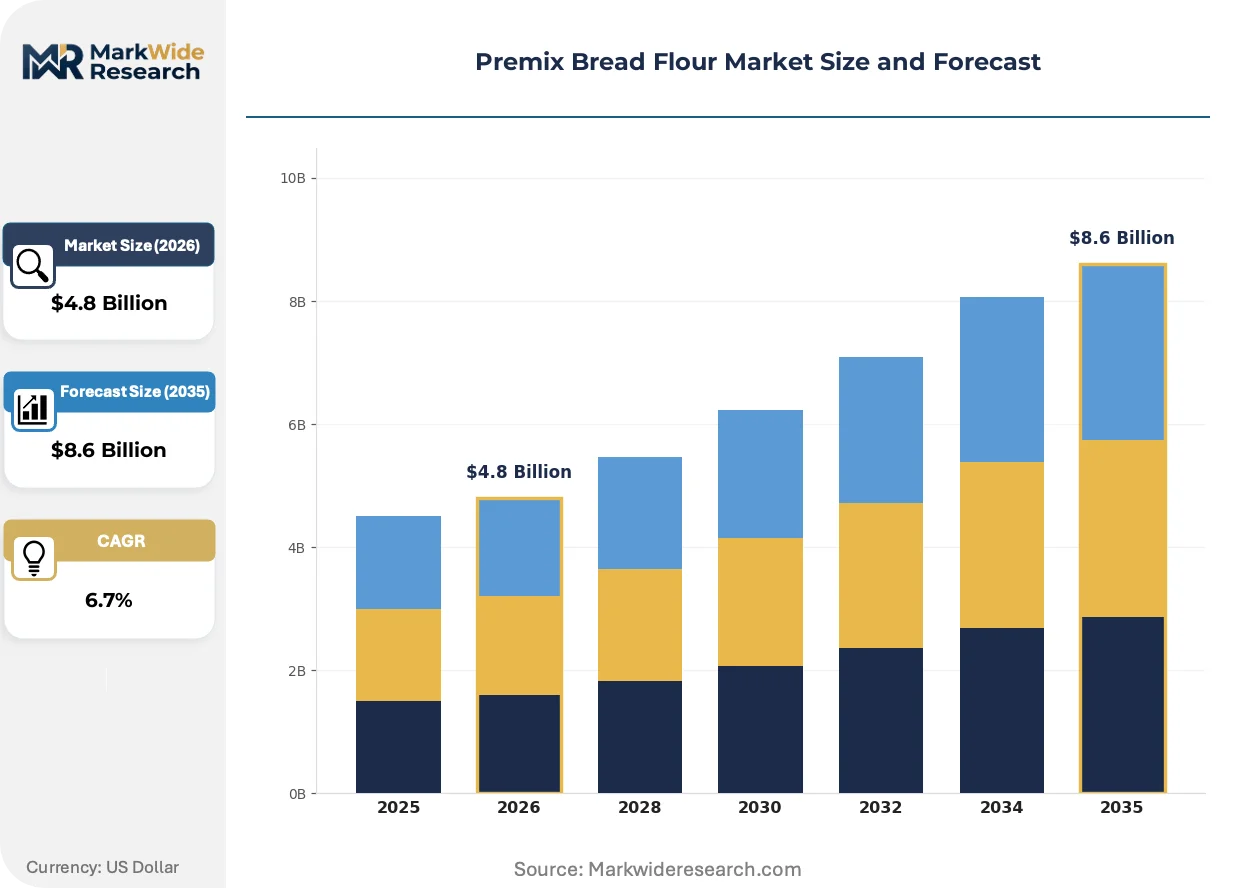
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Gluten-Free, Organic, High-Protein End User: Bakeries, Restaurants, Retailers, Home Bakers Packaging Type: Bags, Boxes, Bulk, Sachets Distribution Channel: Online, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Lesaffre Group, Associated British Foods plc, Archer Daniels Midland Company, Bunge Limited, Nisshin Seifun Group Inc., Cargill, Incorporated, Bakels Group, Allied Pinnacle Pty. Ltd., Puratos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premix Bread Flour Market Emerging Trajectories
Clean-label enzyme systems and fermentation-derived ingredients are displacing chemical oxidizers across premium premix lines. This biotechnology pivot intersects with carbon accounting mandates to reshape supplier qualification criteria.
Encapsulated enzyme technology is fragmenting the frozen dough premix segment. These systems protect amylase and xylanase activity through freeze-thaw cycles, enabling craft bakeries to adopt par-baked distribution models without specialized fermentation infrastructure. Industrial producers in Germany are retrofitting existing lines to accommodate these temperature-sensitive formulations, compressing the addressable market for conventional chemical-based alternatives.
EU F-Gas Regulation phase-down schedules are forcing industrial bakeries to replace hydrofluorocarbon-based refrigeration with ammonia or CO2 systems. This equipment transition creates formulation compatibility requirements, as premixes must perform across wider temperature and humidity ranges during proofing. Northern European industrial producers are responding by specifying climate-adaptive enzyme blends that maintain dough tolerance across variable processing environments.
Buying committees at supermarket chains are consolidating ingredient procurement through category management structures that demand annual cost reductions. This concentration shifts negotiation leverage toward volume-committed premix suppliers with integrated grain origination capabilities. The pattern is most visible in British retail channels, where hard discounters and premium banners alike are reducing supplier rosters to simplify compliance auditing and traceability documentation.
Premix Bread Flour Market Segmentation
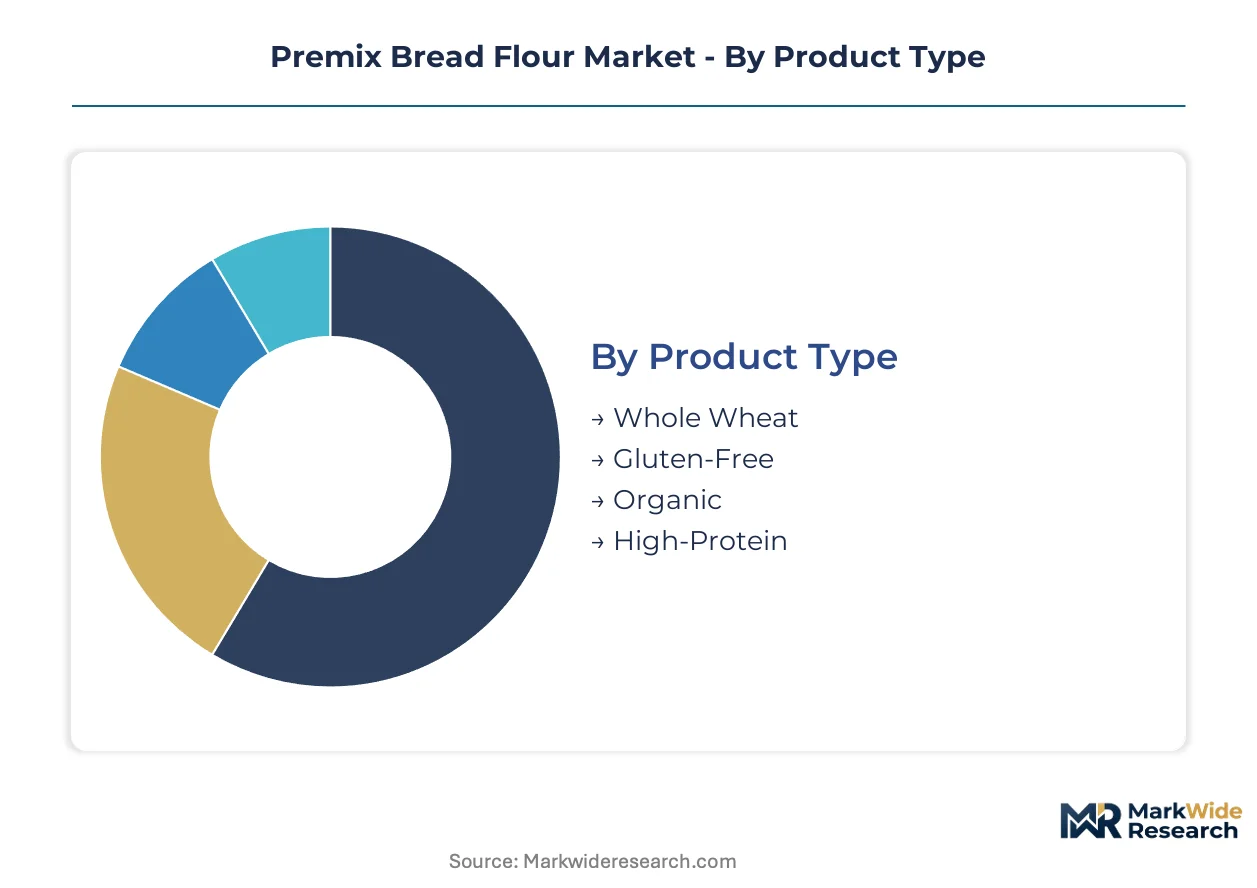
Premix bread flour segmentation reveals how formulation complexity, end-use operational requirements, and channel access costs create distinct competitive arenas. Each category carries different margin profiles and regulatory exposure, shaping where manufacturers concentrate R&D and distribution investments.
Product Type:
Substitution pressure from alternative grain bases and clean-label positioning is fragmenting traditional wheat-dominant formulations fastest in this category.
- Whole Wheat:Retains bran and germ fractions at 12-14% protein content, delivering fiber positioning and denser crumb structure. German craft bakery chains specify whole wheat premixes for their commissary operations to standardize output across retail locations. Health-positioned supermarket banners in France dedicate expanding shelf space to this segment.
- Gluten-Free:Tapioca, rice, and sorghum starch bases replace wheat protein entirely, requiring hydrocolloid and enzyme systems to replicate dough elasticity. Southeast Asian starch sourcing concentration exposes European manufacturers to freight disruption and currency risk. Celiac awareness campaigns and supermarket free-from portfolio expansion are pulling volume fastest here.
- Organic:Certified grain bases with restricted additive lists command specialty store placement and direct-to-baker distribution premiums.
- High-Protein:Vital wheat gluten fortification targets 14-16% protein for artisan loaf structure and extended shelf life in par-baked applications.
Whole wheat retains volume leadership; gluten-free holds the steepest expansion curve.
End User:
Customer operational scale determines formulation sophistication, with centralized procurement systems favoring specification-heavy contracts over spot purchasing.
- Bakeries:Industrial producers demand 25kg bulk formats with batch-to-batch rheological consistency guarantees, while artisan operations prioritize 5-10kg bags with sourdough starter integration. German industrial bakeries are retrofitting lines for climate-adaptive enzyme blends under EU F-Gas Regulation compliance timelines.
- Restaurants:Frozen dough compatibility and par-bake flexibility dominate procurement criteria for chain kitchen operations with limited fermentation infrastructure.
- Retailers:Private-label development teams specify clean-label enzyme systems to meet front-of-pack labeling mandates and carbon disclosure requirements.
- Home Bakers:500g-1kg sachet formats with foolproof hydration instructions target convenience positioning in online and supermarket impulse locations.
Bakeries command the largest revenue pool; retailers are gaining share fastest through private-label consolidation.
Packaging Type:
Packaging cost tiering directly reflects customer handling infrastructure and inventory turnover velocity across the value chain.
- Bags:Multi-wall paper and woven polypropylene formats dominate 10-25kg industrial procurement, with moisture barrier specifications critical for enzyme stability in humid climates.
- Boxes:Corrugated retail cases protect 1-5kg consumer formats through e-commerce fulfillment channels where dimensional weight pricing applies.
- Bulk:Tanker and silo delivery eliminates packaging cost for high-volume industrial users with dedicated pneumatic handling systems.
- Sachets:Single-use metallized film packets enable precise portion control for small-batch artisan operations and trial-size marketing.
Bags retain shipment volume dominance; sachets are climbing fastest through specialty channel expansion.
Distribution Channel:
Channel margin capture is restructuring as buying committees consolidate supplier rosters and direct platforms bypass traditional ingredient distributors.
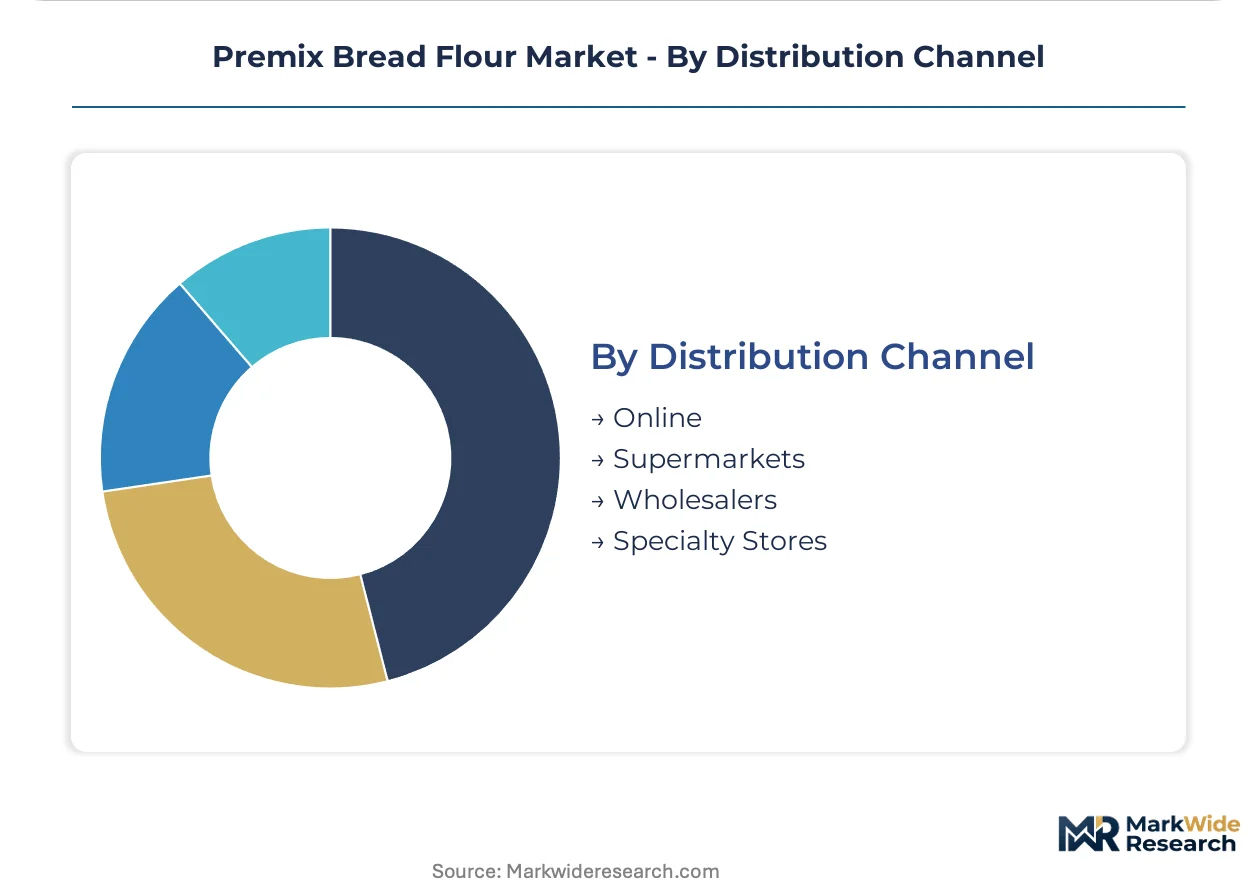
- Online:Direct-to-baker platforms and marketplace fulfillment are capturing specialty and organic segment growth, with last-mile logistics capabilities becoming a competitive differentiator. British hard discounters and premium banners alike are reducing supplier counts to simplify compliance auditing.
- Supermarkets:Category management structures demand annual cost reductions and verified supply chain data for carbon footprint disclosure mandates.
- Wholesalers:Traditional broadline distributors face margin compression as volume-committed suppliers with integrated grain origination bypass their warehousing functions.
- Specialty Stores:Regional craft chains and organic retailers specify small-batch formulations with fermentation-derived ingredient positioning.
Supermarkets anchor volume throughput; online is expanding most quickly through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes premix bread flour through industrial bakeries and craft commissary chains, while the United States channels volume through supermarket private-label programs and India drives growth via fortification mandates and artisan sector expansion.
Germany
Craft bakery chains in Bavaria and North Rhine-Westphalia are centralizing procurement through commissary operations that specify premix-based production for consistency across retail locations. The EU F-Gas Regulation is forcing industrial bakeries in Lower Saxony to replace hydrofluorocarbon refrigeration with ammonia systems, creating formulation compatibility requirements for wider temperature ranges during proofing. Berlin-Brandenburg industrial producers are retrofitting lines for climate-adaptive enzyme blends to meet these new processing environments.
United States
Supermarket buying committees are consolidating ingredient procurement through category management structures that demand annual cost reductions and verified supply chain data for carbon disclosure. FDA GRAS self-affirmation and FSMA preventive controls shape import and domestic manufacturing compliance burdens for premix formulations. Midwest grain origination clusters in Illinois and Iowa anchor integrated suppliers with captive wheat protein extraction capabilities serving retail private-label programs.
France
Artisan bakery segment expansion in Île-de-France and Auvergne-Rhône-Alpes is standardizing procurement through centralized commissaries specifying premix production. EFSA novel food evaluations govern enzyme and additive approvals, with fermentation-derived ingredients facing 18-24 month approval windows. Health-positioned supermarket banners in Provence-Alpes-Côte d'Azur are dedicating expanding shelf space to whole wheat premix variants with fiber positioning.
India
BIS fortification standards mandate nutrient premix inclusion in wheat-based products, creating divergent formulation requirements from Western specifications. Maharashtra and Gujarat industrial bakeries are scaling premix procurement to meet standardized output demands across fragmented retail networks. Karnataka craft chains are adopting direct-to-baker distribution platforms to bypass traditional ingredient distributors and capture margin.
China
GB food safety standards for wheat-based products create regional specification fragmentation that complicates multinational premix formulation strategies. Yangtze River Delta industrial bakeries in Shanghai and Jiangsu are demanding 25kg bulk formats with batch-to-batch rheological consistency guarantees. Pearl River Delta frozen dough applications are driving encapsulation technology adoption to extend enzyme activity windows through extended supply chains.
Premix Bread Flour Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in premix bread flour supply. The upper tier combines grain origination, protein extraction, and fermentation ingredient capabilities under unified ownership. The specialist tier concentrates on clean-label enzyme systems, sourdough starter integration, or regional distribution density. Three archetypes dominate: integrated agribusiness conglomerates with captive supply chains, fermentation-focused ingredient houses leveraging yeast-to-enzyme vertical networks, and regional millers with direct-to-baker logistics platforms. Competitive moves center on backward integration into wheat protein extraction and strategic partnerships with craft bakery chains for commissary specification lock-in.
Within the integrated agribusiness tier, Archer Daniels Midland Company exemplifies North American grain origination dominance with in-house wheat protein extraction capabilities. Associated British Foods plc anchors British retail channels through its AB Mauri division, representing the fermentation-to-premix network archetype. Puratos Group occupies a position exemplifying clean-label differentiation through sourdough starter integration and enzyme system specialization. These three anchors illustrate how geographic origination, vertical network depth, and formulation technology each define competitive positioning in fragmented national markets.
| Leading Market Players |
|---|
| Lesaffre Group |
| Associated British Foods plc |
| Archer Daniels Midland Company |
| Bunge Limited |
| Nisshin Seifun Group Inc. |
| Cargill, Incorporated |
| Bakels Group |
| Allied Pinnacle Pty. Ltd. |
| Puratos Group |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down schedules gate both supply qualification and price differentiation simultaneously, as industrial bakeries must source climate-adaptive enzyme blends compatible with ammonia refrigeration systems while premium formulations command margin premiums for verified low-carbon processing. This regulatory threshold fragments supplier tiers between certified-compliant premix manufacturers and legacy operators facing equipment retrofit costs.
Pricing Analysis
Long-term offtake contracts dominate industrial bakery procurement, with annual volume commitments securing preferential pricing against spot-market volatility in wheat protein concentrates. Three-tier pricing structure across premium clean-label enzyme systems, standard fortified formulations, and economy bulk blends differentiates based on certification grade and customization level. Cost compression in economy tiers is intensifying because supermarket buying committees demand annual price reductions through category management consolidation. Artisan craft chains exhibit lowest price sensitivity, prioritizing batch consistency guarantees over per-kilogram cost.
Supply Chain Analysis
Germany and France anchor European premix formulation and commissary distribution, while Southeast Asian processors concentrate tapioca and rice starch supply for gluten-free bases. Wheat protein extraction draws from Black Sea origination zones and North American grain clusters, with enzyme systems sourcing from fermentation facilities in the Netherlands and Belgium. Container freight disruptions through Southeast Asian starch corridors present single-source vulnerability for European gluten-free manufacturers. Distribution runs through integrated suppliers with captive grain origination bypassing traditional broadline wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through supermarket category management structures and craft bakery chain commissary consolidation, shifting negotiation leverage toward volume-committed suppliers with verified supply chain data capabilities.
For Market Incumbents: Secure backward integration into wheat protein extraction to buffer Black Sea drought-cycle volatility and compress input cost swings. Lock in commissary specification contracts with German and French craft bakery chains before climate-adaptive enzyme blend standardization spreads. This defends margin position against fermentation-focused ingredient houses leveraging yeast-to-enzyme vertical networks. For New Entrants and Emerging Players: Differentiate on direct-to-baker distribution platforms with last-mile logistics capabilities, targeting specialty stores and regional organic retailers bypassing traditional ingredient distributors. The most penetrable white space sits in freeze-dried sourdough starter systems for clean-label positioning without refrigeration infrastructure. Pursue platform-based go-to-market partnerships with online marketplace fulfillment operators. For Investors and Strategic Acquirers: CSRD carbon footprint disclosure mandates reshape the acquisition landscape by rewarding targets with verified supply chain data and renewable energy procurement documentation. Five-to-ten-year viability favors fermentation-derived ingredient specialists with EFSA-approved novel food dossiers already cleared. Watch EFSA evaluation timeline acceleration as the signal indicating regulatory arbitrage closure for late entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Protein Extraction | Captive supply from Black Sea and North American grain origination clusters compresses input cost volatility exposure. |
| Climate-Adaptive Enzyme Blend Development | EU F-Gas Regulation compliance enables specification lock-in with industrial bakeries retrofitting ammonia refrigeration systems. |
| Direct-to-Baker Distribution Platform Launch | Last-mile logistics capabilities capture margin from specialty stores and craft chains bypassing traditional wholesalers. |
| Freeze-Dried Sourdough Starter Integration | Clean-label positioning without refrigeration infrastructure opens convenience-oriented retail channels to premium pricing. |
| Verified Carbon Footprint Disclosure Program | CSRD-compliant supply chain data differentiates offerings for supermarket buying committees consolidating supplier rosters. |
Methodological Framework
A standing panel of industrial bakery procurement directors, craft commissary operations managers, enzyme systems R&D leads, and grain origination traders provided ongoing calibration against secondary validation from EU REACH registration databases, EFSA novel food evaluation records, BIS fortification standard filings, and customs trade flow data. Bottom-up volume modeling triangulated with top-down value estimates across premix formulation tiers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type complexity, end-user operational scale, packaging format tier, and distribution channel access cost. CAGRs were derived from fitted growth curves incorporating enzyme stabilization technology adoption rates and EU energy mandate compliance timelines.
Material uncertainties — Black Sea drought recurrence, Southeast Asian container freight disruption, EFSA evaluation timeline extension — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and technology diffusion rates. Recalibration cycles align with material shifts in EU Green Deal enforcement intensity and carbon disclosure mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Ezekiel Bread Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Pastry Premixes Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Marzipan Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Baking Mats Market
Bakery Products
Ice Cream Cones Market
Bakery Products
South America Ice Cream Market
Bakery Products
Pizza Crust Market
Bakery Products
Bakery Fats Market