
 Folliculitis Market | 2026-2036
Folliculitis Market Size, Share, and Industry Trends Forecast 2026-2036
Folliculitis Market Analysis
Dermatology-trained clinical staff is rotating toward outpatient procedural settings, expanding capacity for folliculitis diagnosis and management outside traditional hospital wards. AbbVie Inc. leverages its immunology R&D infrastructure to sustain pipeline activity in inflammatory skin conditions. Pfizer Inc. anchors commercial reach through established dermatology and primary care channels across North American and European markets. Johnson & Johnson Services, Inc. competes via consumer-facing antiseptic and wound-care portfolios that intersect with folliculitis prevention protocols.
Folliculitis denotes inflammation of the hair follicle, typically triggered by bacterial colonization, fungal infection, mechanical irritation, or chemical exposure, with lesions ranging from superficial pustules to deep furuncles requiring drainage. The condition serves clinical and commercial purposes across acne management, post-operative skin integrity, and cosmetic hair removal workflows. Topical treatments dominate current prescription volumes due to favorable safety profiles and direct site delivery, while light therapy segments capture premium positioning in wellness centers and elective dermatology settings. Oral medications retain structural importance for recurrent or deep-seated infections, though resistance surveillance pressures shape formulary decisions.
FDA antimicrobial development guidelines and EPA surface antiseptic registrations jointly determine product eligibility and labeling claims for folliculitis therapeutics in the United States. EMA dermatology quality standards and REACH chemical safety protocols in Europe add compliance layers for topical formulations containing retinoids or antimicrobial peptides. Stakeholders must monitor evolving resistance patterns and regulatory shifts toward narrow-spectrum agents when allocating R&D budgets across treatment modalities.
Market Dynamics
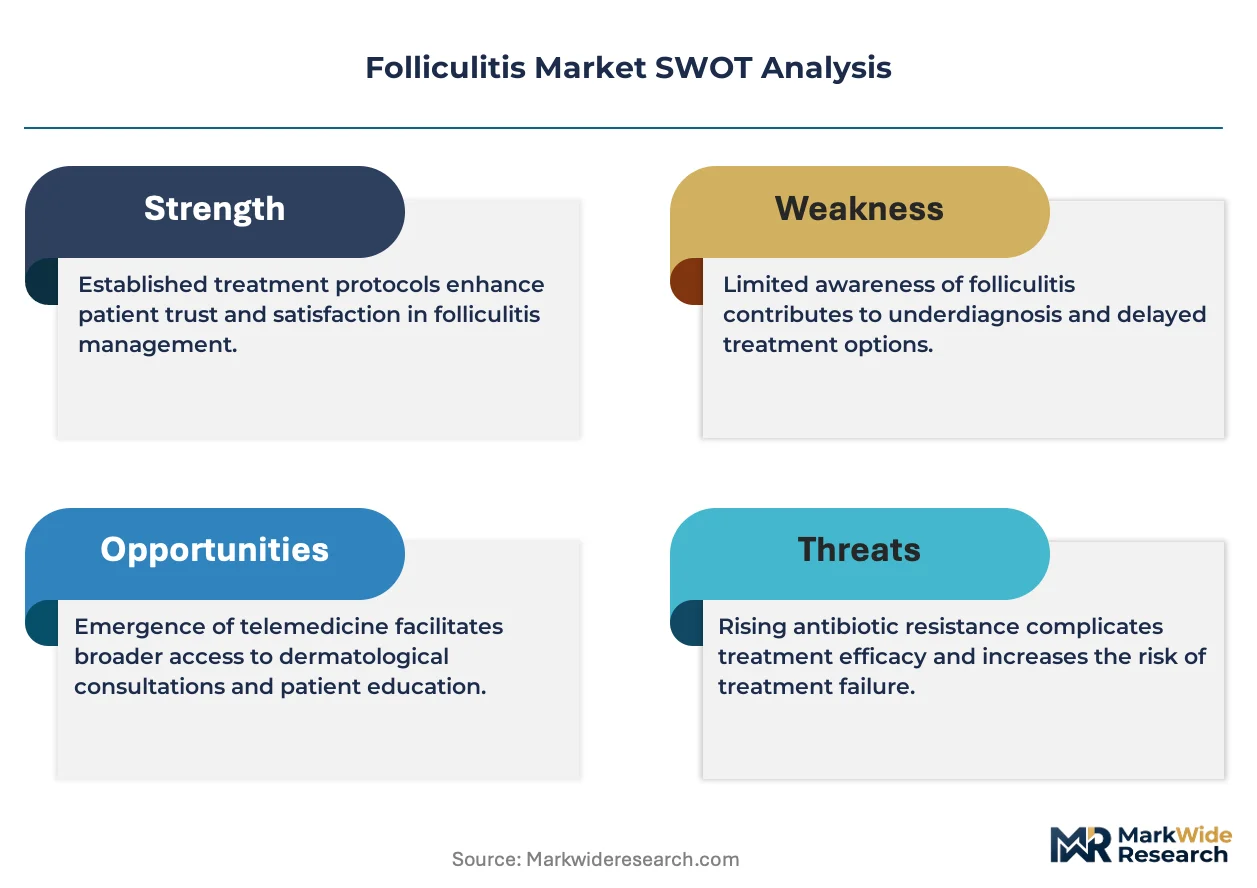
Antimicrobial resistance surveillance is compressing formulary flexibility for broad-spectrum agents, forcing developers toward narrow-spectrum alternatives with longer validation timelines and higher clinical trial costs.
Growth Catalysts
- REACH chemical safety protocols:ECHA registration requirements for topical retinoid formulations are accelerating investment in antimicrobial peptide alternatives across European dermatology pipelines.
- Post-operative skin integrity protocols:Surgical centers in the United States are expanding folliculitis prevention into standardized wound-care bundles, creating institutional purchasing demand.
- Photodynamic therapy systems:Wellness centers in South Korea are integrating blue-light devices into cosmetic hair removal workflows, extending treatment addressable markets beyond medical indications.
Market Restraints
- API supply concentration:Clindamycin and mupirocin active pharmaceutical ingredients concentrate among Chinese and Indian bulk manufacturers, exposing formulators to geopolitical supply disruptions.
- FDA antimicrobial development guidelines:Narrow-spectrum agent qualification pathways require larger non-inferiority trial populations, extending time-to-market by 18-24 months versus historical topical benchmarks.
- Over-the-counter antiseptic substitution:Chlorhexidine and benzoyl peroxide washes capture mild case volumes, compressing prescription capture rates in primary care settings.
Strategic Opportunities
- Brazilian ambulatory expansion:ANVISA's streamlined registration for Class III dermatological devices is enabling direct-to-clinic distribution models outside hospital purchasing consortia.
- Microbiome-targeted formulations:Convergence of 16S rRNA sequencing and topical delivery engineering is creating first-in-class agents that preserve commensal flora while suppressing pathogenic colonization.
- Telemedicine prescribing workflows:Asynchronous dermatology platforms in Australia are capturing recurrent case management, shifting prescription initiation from physical clinics to digital channels.
Industry Challenges
- Clinical microbiology specialization gaps:Dermatology practices lack in-house culture and sensitivity testing, creating diagnostic delays that complicate targeted therapy selection.
- ISO 13485 certification timelines:Light therapy device manufacturers face 12-18 month quality management system audits before obtaining CE marking under MDR requirements.
- Legacy EMR integration:Photographic lesion tracking tools require API development against fragmented electronic health record architectures, slowing deployment in multi-site clinic networks.
Report Scope
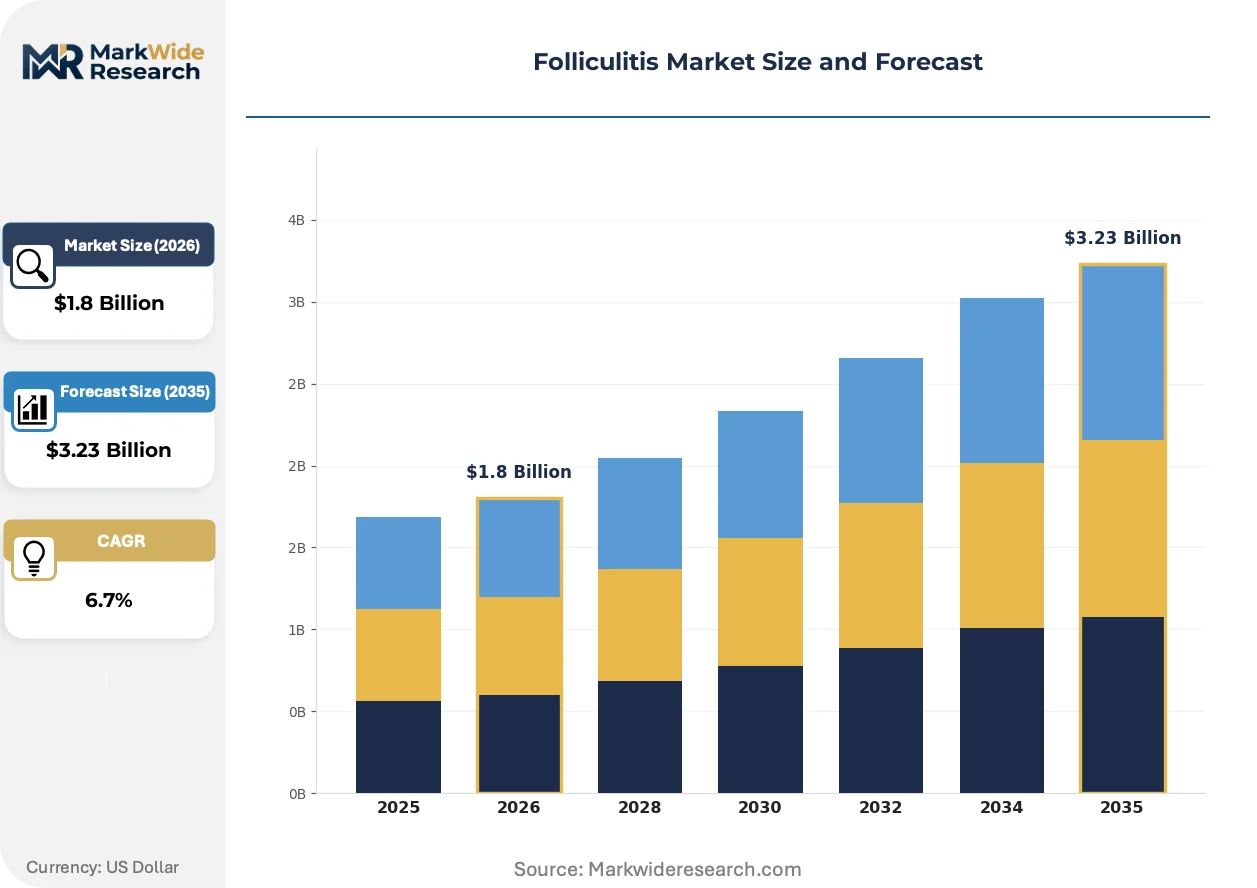
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folliculitis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Antiseptics, Light Therapy End User: Dermatology Clinics, Hospitals, Homecare Settings, Wellness Centers Application: Acne Management, Hair Removal, Skin Care, Post-Operative Care Treatment Modality: Conventional Medicine, Holistic Approaches, Laser Treatment, Chemical Peels |
| Companies Covered | AbbVie Inc., AstraZeneca, Johnson & Johnson Services, Inc., Novartis AG, Allergan, Pfizer Inc., Merck & Co., Inc., Bausch Health Companies Inc., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folliculitis Market Emerging Trajectories
Topical delivery engineering and diagnostic automation are redrawing competitive boundaries between pharmaceutical and device manufacturers, with regulatory science becoming the primary differentiator in pipeline prioritization.
Antimicrobial peptide formulations are fragmenting the topical therapeutics landscape. These biologically derived agents disrupt bacterial membranes without inducing resistance mechanisms. Academic medical centers in Germany and the Netherlands are piloting peptide-based protocols for recurrent Staphylococcus aureus folliculitis. The technology is fragmenting traditional antibiotic market segments by offering clinicians resistance-profile differentiation for refractory cases.
EMA's Medical Device Regulation (MDR) recast requirements for phototherapy equipment are elevating clinical evidence standards. Manufacturers must now submit post-market surveillance data for laser and LED devices previously grandfathered under directives. Light therapy segments in France and Italy are responding by consolidating clinical service contracts with academic dermatology departments to generate mandated outcome registries.
Subscription-based medication delivery is displacing traditional pharmacy fulfillment for chronic folliculitis management. Direct-to-consumer platforms in the United States are bundling topical compounds with teledermatology consultations. This model concentrates patient acquisition costs in digital marketing rather than clinician detailing, with highest penetration visible among millennial demographics seeking cosmetic hair removal aftercare.
Folliculitis Market Segmentation
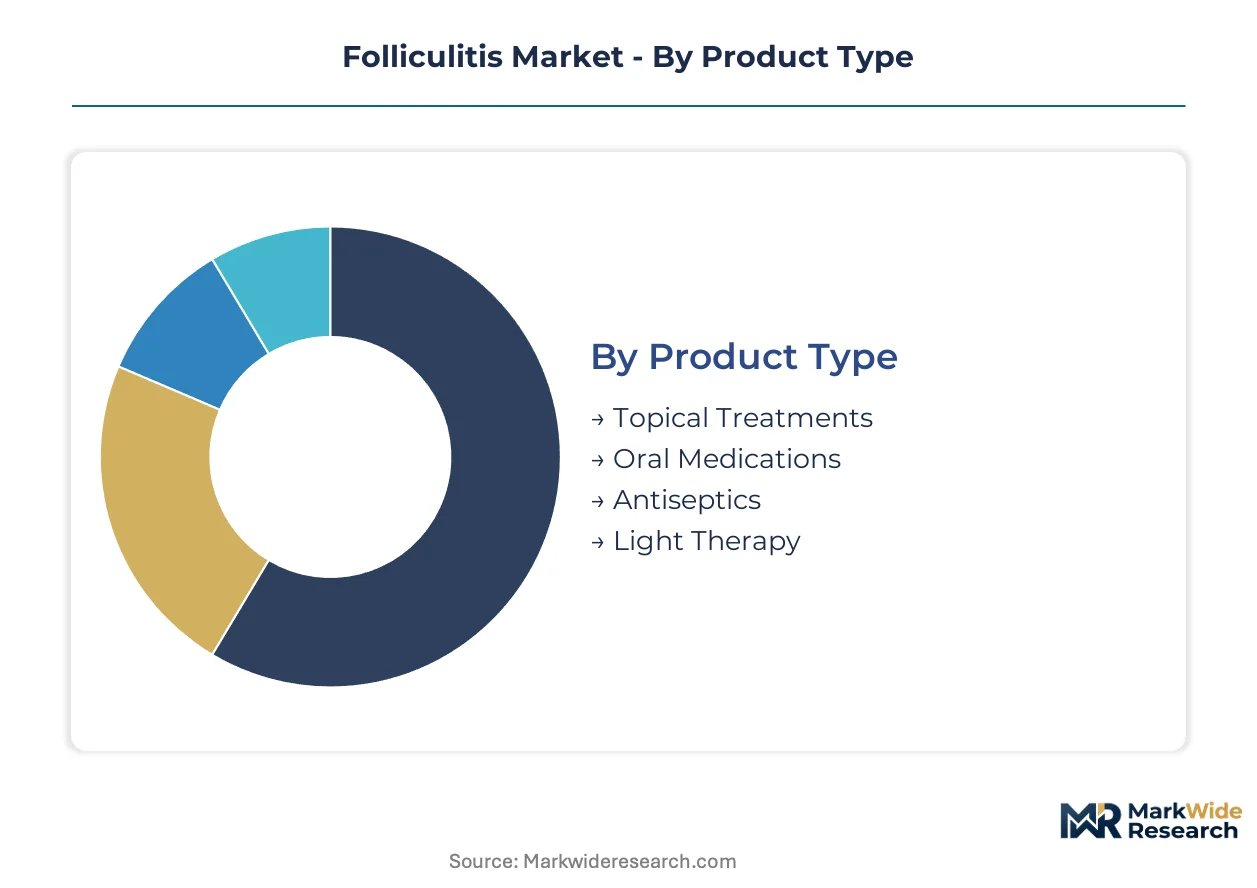
Folliculitis treatment flows through distinct procurement channels shaped by clinical setting, reimbursement pathways, and patient acuity. Channel-mix dynamics determine where manufacturers concentrate detailing resources versus direct-to-consumer investment.
Product Type:
Channel distribution splits sharply between prescription-dependent segments and retail-accessible formats, with institutional purchasing consortia dominating high-volume therapeutic categories.
- Topical Treatments:Creams, gels, and lotions containing antimicrobial or anti-inflammatory agents deliver site-specific therapy with minimized systemic exposure. Dermatology clinics in the United States generate the highest prescription volumes for clindamycin and mupirocin formulations, though pharmacy benefit managers increasingly require prior authorization for branded alternatives.
- Oral Medications:Systemic antibiotics including tetracyclines and macrolides address deep-seated or recurrent infections unresponsive to topical protocols. Hospital discharge workflows and infectious disease consultations drive initiation, with primary care renewal rates constrained by antimicrobial stewardship programs.
- Antiseptics:Chlorhexidine and benzoyl peroxide preparations compete in retail pharmacy and e-commerce channels for mild case self-management.
- Light Therapy:Blue-light and photodynamic devices command premium positioning in elective dermatology and wellness settings.
By volume, Topical Treatments leads. By growth pace, Light Therapy is expanding most quickly.
End User:
Cost-tier stratification separates high-acuity institutional settings from lower-intensity ambulatory and consumer-directed environments, with reimbursement density determining service line investment.
- Dermatology Clinics:Outpatient procedural centers concentrate diagnostic expertise and therapeutic delivery for moderate-to-severe presentations. Australian teledermatology platforms are shifting prescription initiation into asynchronous digital workflows, compressing physical visit requirements for recurrent case management.
- Hospitals:Inpatient services and surgical units manage complicated deep follicular infections requiring drainage or intravenous therapy. Post-operative skin integrity protocols in United States surgical centers are expanding prevention bundles into standardized wound-care purchasing.
- Homecare Settings:Self-administered topical regimens and maintenance protocols extend therapy beyond clinical supervision.
- Wellness Centers:Cosmetic hair removal aftercare and elective skin treatments drive device-based service revenue.
By patient throughput, Dermatology Clinics leads. By margin expansion, Wellness Centers is gaining share fastest.
Application:
Application segments map to distinct customer types, with cosmetic-motivated demand exhibiting higher price elasticity and lower insurance dependency than medically indicated use.
- Acne Management:Overlapping pathophysiology with follicular inflammation positions folliculitis therapeutics within broader dermatology acne protocols. Adolescent and young adult demographics in Germany and the Netherlands are piloting antimicrobial peptide alternatives for refractory Staphylococcus aureus presentations.
- Hair Removal:Laser, waxing, and electrolysis aftercare creates predictable seasonal demand patterns. South Korean wellness centers are integrating blue-light devices into cosmetic workflows, extending addressable markets beyond medical indications.
- Skin Care:General dermatologic maintenance and aesthetic protocols incorporate folliculitis prevention.
- Post-Operative Care:Surgical site preparation and infection prevention protocols create institutional purchasing demand.
By procedure volume, Acne Management leads. By growth trajectory, Hair Removal shows the steepest expansion.
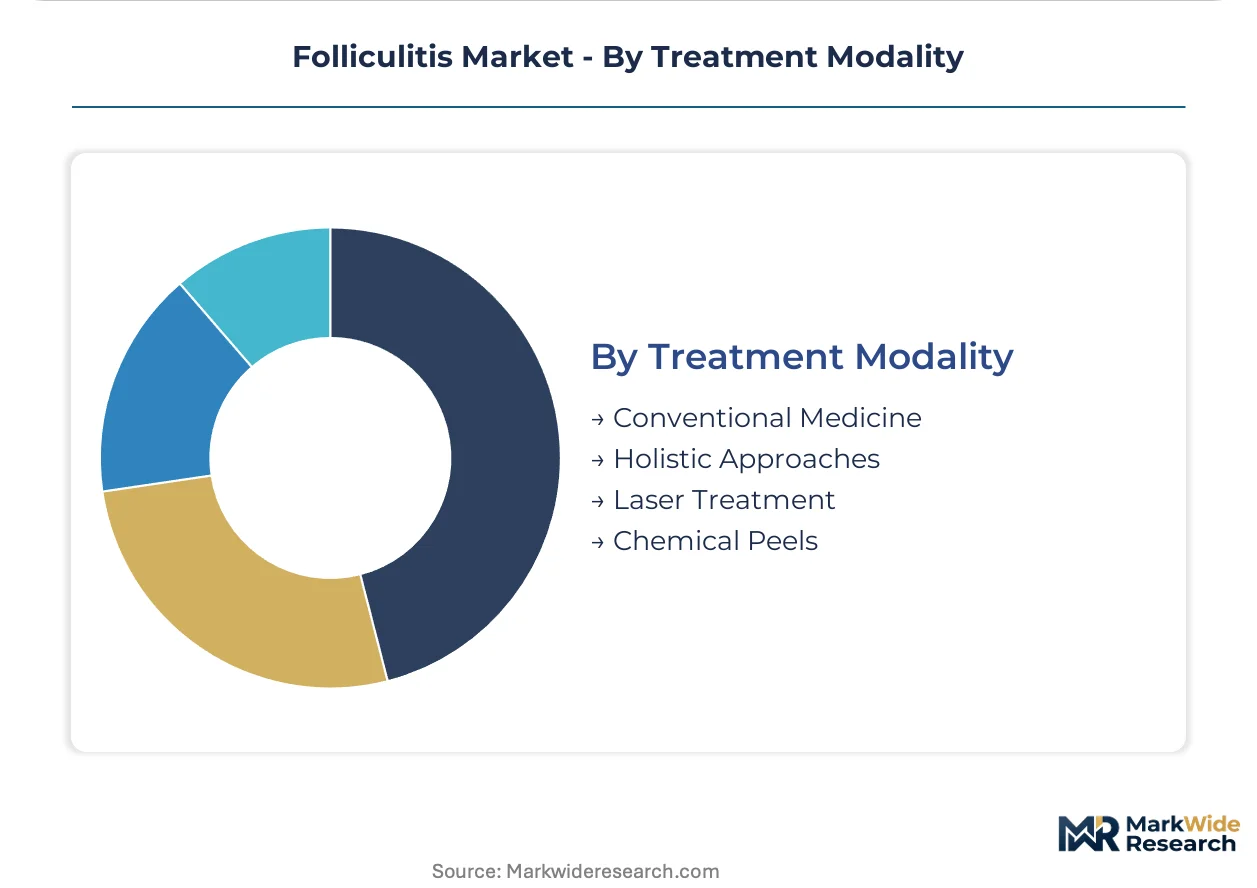
Treatment Modality:
Maturity differentiates established pharmaceutical formats from emerging technology segments, with regulatory validation timelines compressing competitive entry for novel approaches.
- Conventional Medicine:Antibiotic and antiseptic protocols dominate evidence bases and formularies. FDA antimicrobial development guidelines are extending narrow-spectrum agent qualification timelines by 18-24 months versus historical topical benchmarks.
- Laser Treatment:Ablative and non-ablative devices target hair follicle inflammation through thermal or photomechanical mechanisms. EMA Medical Device Regulation recast requirements are elevating clinical evidence standards for phototherapy equipment in France and Italy.
- Holistic Approaches:Natural topical preparations and dietary interventions occupy complementary and alternative medicine channels.
- Chemical Peels:Exfoliating acid formulations address superficial follicular obstruction in aesthetic dermatology settings.
By revenue concentration, Conventional Medicine leads. By technology investment, Laser Treatment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States ambulatory settings prioritize prescription antimicrobial protocols, while South Korean wellness centers integrate device-based folliculitis management into cosmetic service bundles. European markets emphasize narrow-spectrum alternatives under tightening chemical safety frameworks.
United States
Dermatology clinics and surgical centers drive institutional demand through post-operative skin integrity bundles. FDA antimicrobial development guidelines extend narrow-spectrum agent qualification timelines. Boston and New York Metro areas concentrate teledermatology platform development for asynchronous prescription workflows.
Germany
Academic medical centers pilot antimicrobial peptide protocols for recurrent Staphylococcus aureus presentations. EMA dermatology quality standards and REACH chemical safety protocols govern topical retinoid formulations. Munich and Heidelberg clusters advance 16S rRNA sequencing convergence with topical delivery engineering.
South Korea
Wellness centers integrate blue-light devices into cosmetic hair removal aftercare, extending addressable markets beyond medical indications. MFDS device registration pathways enable rapid aesthetic technology adoption. Seoul Capital Area dominates photodynamic therapy system distribution for elective dermatology settings.
Brazil
ANVISA's streamlined Class III dermatological device registration enables direct-to-clinic distribution outside hospital purchasing consortia. Ambulatory expansion concentrates in São Paulo and Rio de Janeiro metro areas. Private dermatology networks capture recurrent case management through subscription-based medication delivery models.
Australia
Asynchronous dermatology platforms shift prescription initiation from physical clinics to digital channels for recurrent folliculitis management. TGA oversight aligns with EMA dermatology standards for topical formulation approvals. Sydney and Melbourne concentrate telemedicine prescribing workflow development.
Folliculitis Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Large pharmaceutical incumbents leverage immunology R&D infrastructure and established dermatology channels to sustain pipeline activity. Mid-scale dermatology specialists concentrate on narrow-spectrum topical development and device-therapy integration. Competitive moves center on microbiome-targeted formulation partnerships and light therapy device consolidation under stricter MDR evidence requirements.
Within the integrated pharmaceutical tier, AbbVie Inc. and Pfizer Inc. exemplify archetypes leveraging immunology infrastructure and commercial reach across North American and European markets. Johnson & Johnson Services, Inc. occupies a position bridging consumer-facing antiseptic portfolios with institutional wound-care protocols. These three anchors represent distinct strategic postures: R&D-driven pipeline sustainability, channel-anchored geographic expansion, and consumer-to-clinical portfolio spanning.
| Leading Market Players |
|---|
| AbbVie Inc. |
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| Allergan |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Bausch Health Companies Inc. |
| GlaxoSmithKline plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for clindamycin and mupirocin active pharmaceutical ingredients lock in supply access for North American formulators while capping price volatility exposure against Indian and Chinese bulk manufacturing fluctuations. These contractual structures concentrate procurement leverage among integrated pharmaceutical incumbents, compressing margin flexibility for mid-scale topical developers competing on narrow-spectrum antimicrobial peptides.
Pricing Analysis
Project-based contracting dominates institutional purchasing for photodynamic therapy devices, with wellness centers in South Korea negotiating bundled service agreements that embed hardware costs within per-treatment fees. Price differentiation rests on FDA clearance tier and ISO 13485 certification status, with MDR-compliant devices commanding premium positioning in European elective dermatology. Cost compression in generic topical antibiotics is intensifying because pharmacy benefit managers increasingly mandate prior authorization for branded alternatives. Primary care settings exhibit highest price sensitivity due to over-the-counter antiseptic substitution, while academic medical centers demonstrate lowest sensitivity when selecting resistance-profile differentiated therapies.
Supply Chain Analysis
China and India anchor bulk manufacturing for clindamycin and mupirocin active pharmaceutical ingredients, with South Korean device manufacturers supplying phototherapy hardware components. Formulation draws from retinoid precursors subject to REACH registration requirements, antimicrobial peptide fermentation feedstocks, and LED diode arrays for blue-light systems. Single-source vulnerability concentrates in Chinese API production clusters exposed to geopolitical trade disruptions. Distribution runs through hospital purchasing consortia in the United States, direct-to-clinic networks in Brazil under ANVISA streamlined registration, and subscription-based digital platforms in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from over-the-counter antiseptic washes capturing mild folliculitis volumes, compressing prescription capture rates and forcing defensive portfolio repositioning toward resistance-differentiated narrow-spectrum agents.
For Market Incumbents: Shield formulary position by accelerating antimicrobial peptide pipeline investment to differentiate against generic topical antibiotic commoditization. Deepen backward integration into API supply through strategic sourcing agreements with Indian bulk manufacturers, reducing exposure to Chinese concentration risk. Prioritize certification investment for MDR-compliant phototherapy devices ahead of European consolidation waves. For New Entrants and Emerging Players: Lead with microbiome-targeted formulation development targeting recurrent Staphylococcus aureus presentations in German and Dutch academic medical centers, where 16S rRNA sequencing convergence creates first-mover white space. Capture Brazilian ambulatory expansion through ANVISA Class III device direct-to-clinic distribution models outside hospital purchasing consortia. Anchor go-to-market strategy on teledermatology platform partnerships in Australia, shifting prescription initiation into asynchronous digital workflows. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive API sourcing and dual regulatory footprints across FDA and EMA jurisdictions. Long-term viability centers on acquisition targets possessing narrow-spectrum topical pipelines and established clinician education infrastructure. Watch antimicrobial resistance surveillance data from CDC and ECDC as the inflection signal for formulary shift velocity toward premium-priced alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Peptide Pipeline Advancement | Creates resistance-profile differentiation against generic topical antibiotics in German academic centers. |
| MDR Compliance Certification | Enables CE marking retention for phototherapy devices under recast European evidence requirements. |
| Direct-to-Clinic Distribution Expansion | Bypasses hospital purchasing consortia in Brazil through ANVISA streamlined Class III registration pathways. |
| Teledermatology Platform Integration | Captures Australian recurrent case management through asynchronous prescription workflow deployment. |
| Microbiome Sequencing Partnership | Converges 16S rRNA diagnostics with topical delivery engineering for targeted pathogen suppression. |
Methodological Framework
The analysis maps topical antimicrobial formulations, phototherapy devices, oral systemic therapies, and antiseptic preparations, each validated through dermatology practice administrators, hospital formulary directors, pharmaceutical regulatory affairs leads, and wellness center procurement officers. Primary interview intelligence triangulates against FDA 510(k) filings, EMA dermatology quality standard submissions, ANVISA device registration databases, and REACH chemical safety protocol registrations. Bottom-up prescription volume modeling reconciles with top-down market sizing across therapeutic modality segments.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare Part D claims data, hospital procurement database extracts, and GPO contract disclosure filings. The analytical framework segments by product type, end-user setting, application indication, and treatment modality across the projection horizon. CAGRs derive from patient incidence modeling, procedure volume trajectories, and pricing elasticity assumptions for prescription versus over-the-counter substitution patterns. Forecast inputs incorporate antimicrobial resistance surveillance trends, regulatory pathway timeline revisions, and telemedicine adoption curves.
Forecasts assume regulatory continuity in FDA antimicrobial development guidelines, EMA MDR device requirements, and REACH chemical safety protocols; material policy shifts would require re-modeling qualification timelines and formulary access assumptions. Specific risks include API supply disruptions from geopolitical trade measures, accelerated resistance surveillance compressing broad-spectrum agent viability, and reimbursement restriction on device-based therapies. Recalibration cycles align with material shifts in CDC resistance reporting, EMA guidance updates, and teledermatology platform penetration metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Skin Excision Market
Dermatology
Erythema Treatment Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Impetigo Treatment Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Scar Treatment Oils Market
Dermatology
Global Dermatology Cro Market
Dermatology
Australia Skin Treatment Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Microdermabrasion Market
Dermatology
Skin Cancer Market
Dermatology
Androgenetic Alopecia Market