
 North America Marketing Automation Software Market | 2026-2036
North America Marketing Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Marketing Automation Software Market Analytics
Subscription-based financing and asset-light deployment models are tilting competitive dynamics toward vendors with scalable cloud infrastructure. HubSpot leverages freemium-to-paid conversion funnels to dominate the SME entry point across the United States. Adobe anchors enterprise creative-to-marketing workflows through deep integration of content production with campaign orchestration. Salesforce sustains its position by extending CRM-native automation into cross-channel journey management for Fortune 500 accounts.
North America marketing automation software encompasses platforms that orchestrate multi-channel campaign execution, lead scoring, and behavioral analytics through API-connected data pipelines, typically processing millions of customer touchpoints in real time. These systems serve commercial organizations by replacing manual segmentation with algorithmic audience targeting and trigger-based engagement workflows. Cloud-based and SaaS deployments command the largest addressable base due to elastic scaling and reduced IT overhead, while on-premises installations persist among financial institutions with stringent data residency requirements. Email marketing remains the most mature revenue pool, though lead management capabilities are capturing disproportionate investment as B2B organizations prioritize pipeline velocity over broadcast reach.
The Federal Trade Commission and state attorneys general in California, Virginia, and Colorado are enforcing granular consent standards that reshape how platforms collect and activate first-party data. Sector-specific oversight from the Health Insurance Portability and Accountability Act constrains healthcare marketing automation architectures, while the Securities and Exchange Commission's marketing compliance rules govern financial services campaign disclosures. Stakeholders must monitor the divergence between federal privacy preemption debates and proliferating state-level statutes to determine whether centralized or federated data architectures offer sustainable compliance pathways.
Market Dynamics
Enterprise procurement of marketing automation software is pivoting from perpetual licenses to consumption-based SaaS contracts, compressing vendor cash cycles while democratizing access for mid-market retailers previously locked out by upfront capital requirements.
Growth Catalysts
- State-level privacy statutes:The California Consumer Privacy Act and Virginia Consumer Data Protection Act compel organizations to invest in first-party data infrastructure, directly expanding addressable demand for compliant orchestration platforms.
- Real-time behavioral analytics:API-connected data pipelines processing millions of touchpoints enable algorithmic audience targeting that displaces manual segmentation workflows across B2B sales organizations.
- Mexican e-commerce expansion:Cross-border digital retail platforms are deploying automation infrastructure to manage multi-channel campaign execution at scale, creating new installation velocity in Latin America's northern corridor.
Market Restraints
- Cloud infrastructure concentration:Elastic scaling capabilities depend on hyperscaler availability zones concentrated in limited metropolitan clusters, creating systemic resilience exposure for real-time campaign delivery.
- HIPAA architectural constraints:Healthcare marketing automation requires federated data architectures that segment protected health information, adding deployment complexity and extending implementation timelines.
- First-party data depreciation:Granular consent standards enforced by state attorneys general restrict third-party cookie activation, forcing costly infrastructure rebuilds for behavioral targeting pipelines.
Strategic Opportunities
- Canadian financial services:Banks and insurers are expanding automation adoption for regulatory campaign disclosures, creating vertical-specific product development white space.
- AI-native journey orchestration:Convergence of generative content production with predictive lead scoring enables dynamic creative adaptation without manual intervention.
- SEC marketing compliance automation:Investment advisors face mandated disclosure workflows that automated platforms can standardize, reducing manual review overhead.
Industry Challenges
- API integration complexity:Legacy CRM systems require custom middleware development to connect with modern orchestration platforms, extending deployment cycles and inflating professional services costs.
- Cross-border data residency:Divergent state-level privacy preemption debates force architecture decisions between centralized and federated data models, complicating multi-jurisdictional rollout strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Marketing Automation Software Market |
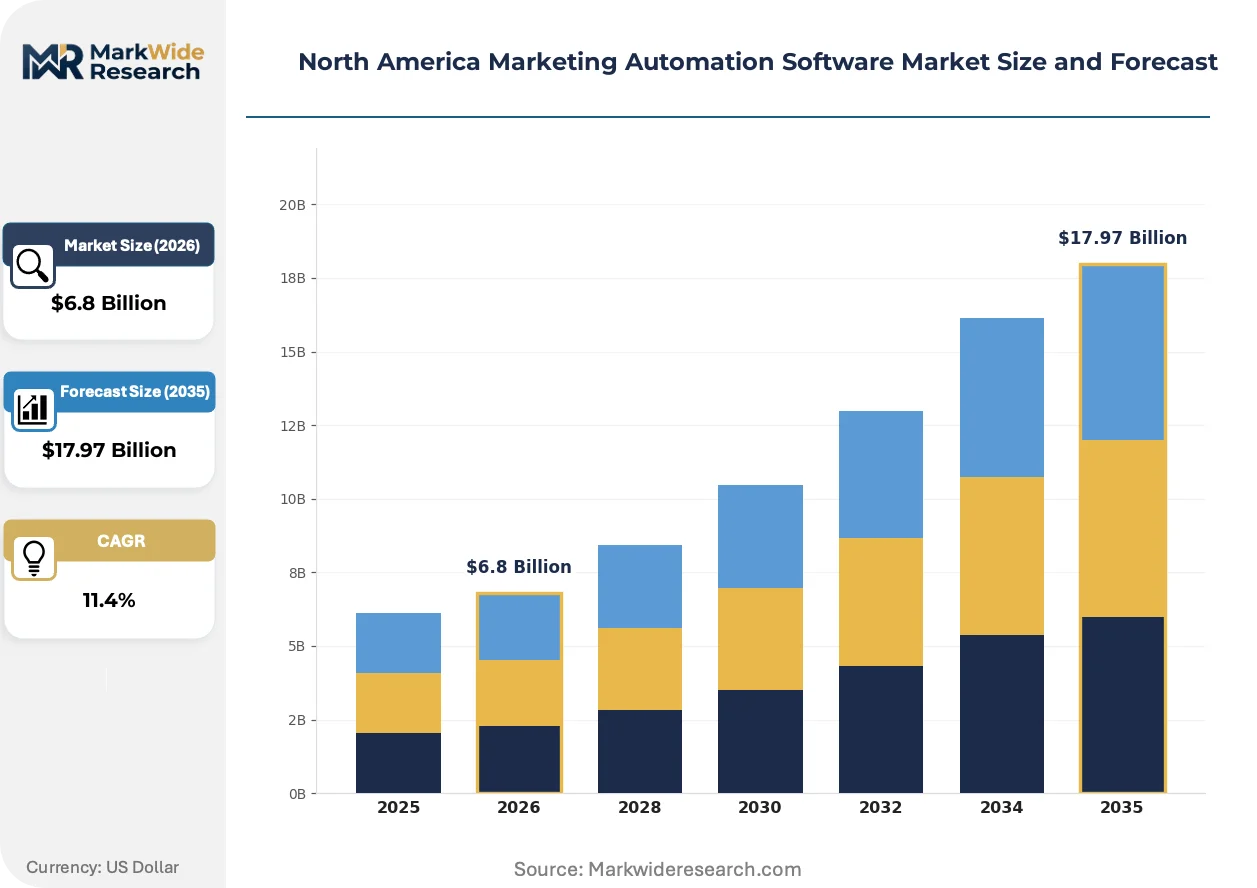
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Email Marketing, Social Media Marketing, Lead Management, Analytics Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: SMEs, Large Enterprises, Agencies, Nonprofits Feature: Personalization, Integration, Automation, Reporting |
| Companies Covered | Oracle Corporation, Act-on Software, HubSpot, ActiveCampaign, Microsoft Corporation, Adobe, IBM Corporation, Creatio, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Marketing Automation Software Market Evolving Landscape
Artificial intelligence is rewriting the functional boundary between content creation and campaign deployment, collapsing historically separate workflows into unified production-to-activation pipelines.
Predictive lead scoring is migrating from rule-based point assignment to machine-learned behavioral propensity models. Mid-market B2B organizations are adopting these systems fastest, drawn by compressed sales cycle visibility. This migration is compressing the competitive moat between enterprise-grade and entry-level platform tiers.
The FTC and state attorneys general are enforcing granular consent standards that reshape first-party data collection mechanics. Industrial consequence includes mandatory audit trails for customer touchpoint activation. Healthcare and financial services verticals are responding with dedicated compliance modules embedded within automation architectures.
Buyers are consolidating vendor relationships around platforms offering native CRM connectivity rather than standalone point solutions. Value-added resellers and systems integrators are capturing implementation margins previously retained by software publishers. This consolidation pattern is most visible among United States-based Fortune 500 accounts with complex multi-brand portfolio structures.
North America Marketing Automation Software Market Segmentation
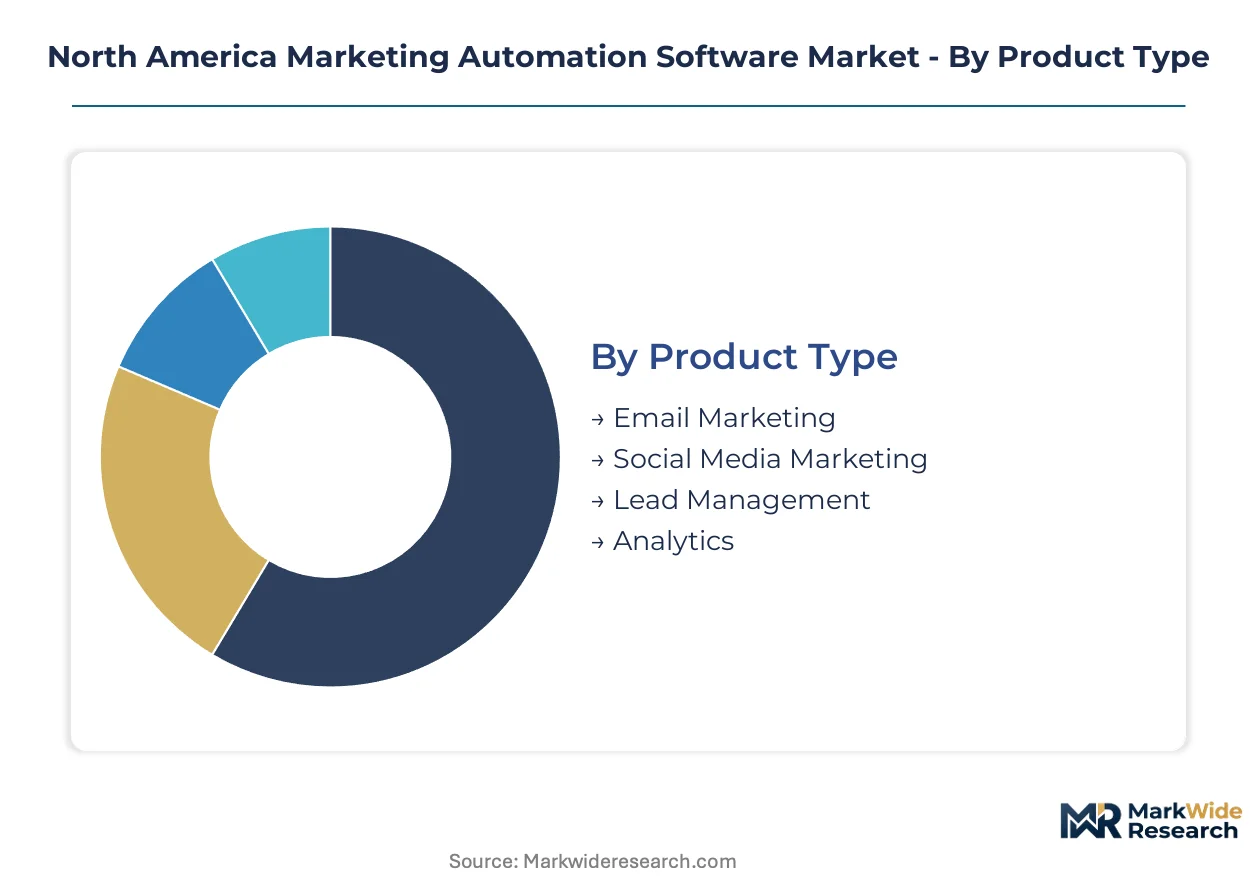
Marketing automation software segments reflect divergent technical requirements across customer scale, data sovereignty needs, and workflow complexity. Procurement patterns vary sharply between organizations prioritizing elastic infrastructure versus those mandating on-premises control for regulatory compliance.
Product Type:
Functional modules span the campaign lifecycle from audience acquisition through conversion attribution, with each addressing distinct operational pain points.
- Email Marketing:Mature orchestration capabilities include dynamic template rendering, deliverability optimization, and behavioral trigger sequences. United States retail and financial services sectors concentrate replacement demand as legacy ESP contracts expire and teams consolidate vendors.
- Lead Management:Pipeline velocity tools encompass scoring algorithms, routing logic, and sales handoff automation. B2B technology vendors in Canada and the United States drive disproportionate investment here, prioritizing SQL conversion rates over broadcast reach metrics.
- Social Media Marketing:Cross-platform publishing, paid amplification, and sentiment monitoring unified within campaign calendars. Mexican e-commerce platforms are expanding adoption fastest for cross-border audience targeting.
- Analytics:Attribution modeling, cohort analysis, and predictive forecasting layered across first-party data lakes. Healthcare systems face HIPAA constraints that segment protected health information from marketing datasets.
Established volume favors Email Marketing; emerging adoption favors Lead Management.
Deployment:
Architecture decisions hinge on data residency mandates, IT headcount constraints, and elasticity requirements during seasonal demand spikes.
- Cloud-Based:Hyperscaler-hosted infrastructure delivering elastic compute and storage without capital expenditure. Mid-market retailers across the United States default here to bypass dedicated operations teams.
- SaaS:Subscription-licensed platforms with vendor-managed updates and shared-tenant security models. Agencies serving multiple client verticals prefer this for rapid tenant provisioning and role-based access isolation.
- On-Premises:Self-hosted installations within customer data centers satisfying stringent residency requirements. United States federal contractors and Canadian banks maintain this posture for audit trail sovereignty.
- Hybrid:Federated architectures partitioning sensitive data on-premises while pushing campaign execution to cloud edge nodes. Healthcare networks deploy this to isolate patient identifiers from activation pipelines.
SaaS and Cloud-Based deployments capture the majority of new installations; On-Premises retains defensive positions in regulated verticals.
End User:
Customer scale determines feature depth requirements, integration complexity tolerance, and professional services dependency.
- Large Enterprises:Multi-brand portfolios requiring centralized governance with subsidiary-level autonomy. Fortune 500 accounts in the United States demand API-first architectures connecting to existing CRM and ERP investments.
- SMEs:Resource-constrained teams prioritizing out-of-box workflows over customization. Freemium conversion funnels dominate acquisition here, with pricing sensitivity driving consolidation toward all-in-one platforms.
- Agencies:Multi-tenant management needs spanning dozens of client instances with isolated data and billing. Creative-to-campaign workflow integration determines vendor selection more than pure automation depth.
- Nonprofits:Donor stewardship and volunteer coordination workflows with constrained technical staffing. Grant-funded procurement cycles favor predictable subscription costs over consumption-based pricing.
Large Enterprises command the highest annual contract values; SMEs represent the steepest expansion trajectory for platform-native adoption.
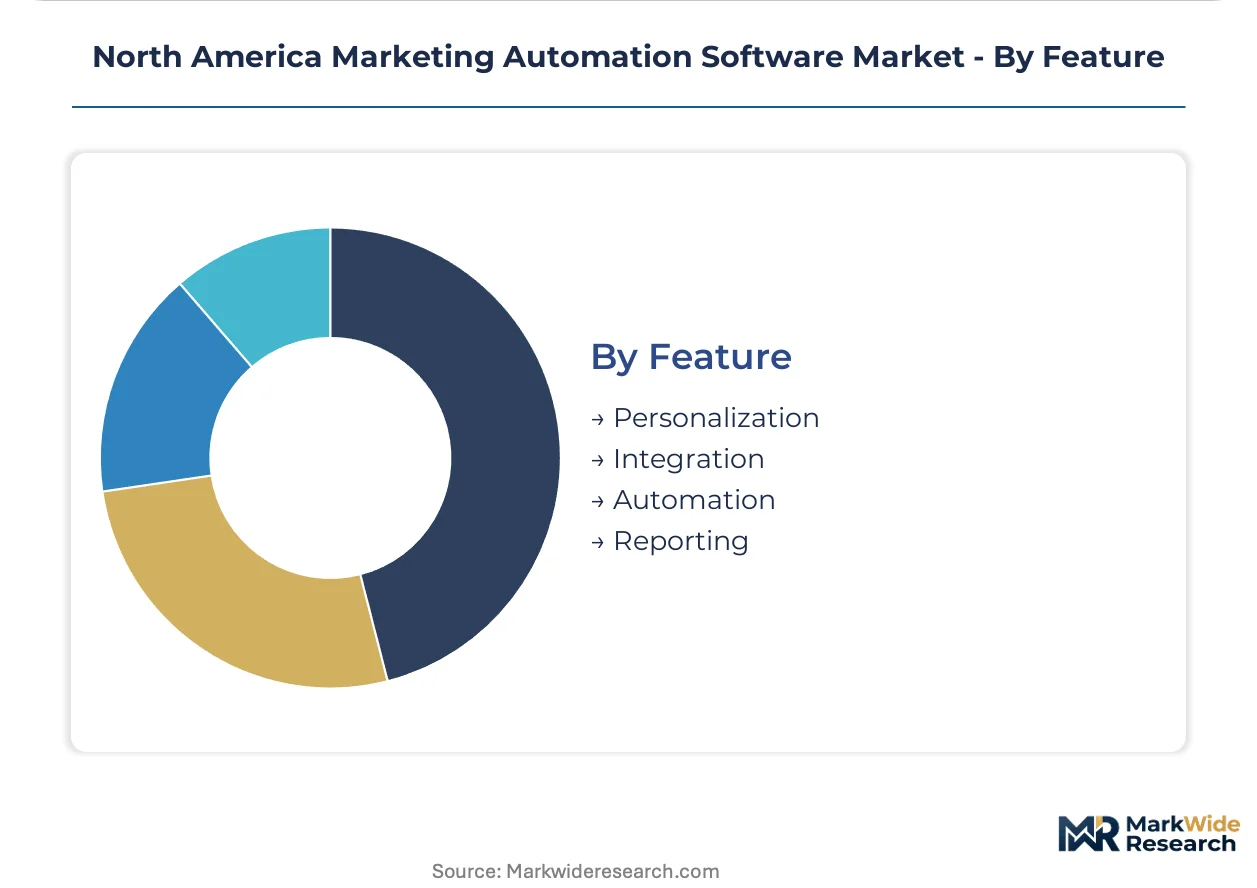
Feature:
Capability modules differentiate vendor positioning and determine integration architecture requirements for implementation teams.
- Automation:Trigger-based workflow engines executing multi-step sequences across channels. Behavioral event processing at scale separates enterprise-grade from entry-tier platform performance.
- Personalization:Dynamic content assembly from unified customer profiles, including product recommendations and send-time optimization. Retailers with extensive SKU catalogs extract disproportionate value here.
- Integration:Pre-built connectors and API extensibility bridging CRM, e-commerce, and advertising platforms. Legacy system connectivity inflates professional services costs for United States manufacturing verticals.
- Reporting:Attribution dashboards, funnel visualization, and executive summary generation. Marketing operations teams demand this for budget justification and cross-functional alignment.
Automation and Personalization anchor competitive differentiation; Integration quality determines implementation success rates across customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America marketing automation software trade flows reflect a services surplus, with United States-based vendors exporting SaaS platforms to Canadian and Mexican enterprises while importing specialized compliance modules from Toronto and Mexico City development centers.
United States
Fortune 500 retailers and B2B technology vendors drive enterprise contract values, with procurement teams consolidating around API-first architectures. The Federal Trade Commission enforces granular consent standards under evolving state privacy frameworks. Silicon Valley and Boston corridor clusters concentrate vendor headquarters and implementation partner networks.
Canada
Toronto-based financial services institutions and Vancouver e-commerce platforms expand automation adoption for regulatory disclosure workflows. The Office of the Privacy Commissioner administers federal data protection standards alongside provincial health information statutes. Montreal and Calgary emerge as secondary demand centers for French-language campaign orchestration tools.
Mexico
Cross-border digital retail platforms in Mexico City and Guadalajara deploy automation infrastructure for multi-channel campaign execution targeting United States consumers. The Federal Law on Protection of Personal Data Held by Private Parties governs cross-border data transfers. Monterrey manufacturing clusters adopt lead management systems for distributor network coordination.
North America Marketing Automation Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct competitive tiers: hyperscaler-backed platforms with native cloud infrastructure, independent SaaS vendors with vertical specialization, and legacy enterprise software providers pivoting from perpetual licenses. Strategic archetypes include CRM-native automation suites, content-to-campaign integrated stacks, and freemium-conversion specialists targeting mid-market entry points. Dominant competitive moves encompass API ecosystem expansion and compliance module development for regulated verticals.
Within the CRM-native tier, Salesforce and Microsoft Corporation occupy positions exemplifying enterprise workflow integration, while HubSpot represents the freemium-conversion archetype dominating SME acquisition funnels. Adobe anchors the content-to-campaign integrated stack category through creative production connectivity. These three entities collectively illustrate the strategic divergence between ecosystem breadth and vertical depth that defines vendor positioning across United States, Canadian, and Mexican procurement contexts.
| Leading Market Players |
|---|
| Oracle Corporation |
| Act-on Software |
| HubSpot |
| ActiveCampaign |
| Microsoft Corporation |
| Adobe |
| IBM Corporation |
| Creatio |
| Salesforce |
| Others |
Value Network & Pricing Analysis
Hyperscaler cloud infrastructure concentration in United States metropolitan clusters anchors margin capture for SaaS vendors, while downstream pricing power fragments across buyer segments with divergent integration complexity tolerance.
Pricing Analysis
Large enterprise buyers anchor annual contract value negotiations through multi-year SaaS commitments with volume-scaled unit economics. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, API call volume, and dedicated support tier. Cost compression in the mid-market tier is intensifying because freemium conversion funnels subsidize acquisition spend. SMEs exhibit highest price sensitivity, while Fortune 500 accounts with complex CRM investments prioritize feature depth over per-seat cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates infrastructure procurement risk for hardware-dependent edge deployments. Software supply chains draw from United States hyperscaler regions, Canadian data residency zones, and Mexican nearshore development centers. Dependencies center on cloud compute instances, API middleware licenses, and compliance audit services. Single-source vulnerability concentrates in hyperscaler availability zones. Distribution runs through direct vendor sales teams, value-added resellers, and systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Fortune 500 procurement teams consolidate vendor relationships around API-first platforms, compressing pricing leverage for point-solution specialists.
For Market Incumbents: Pre-empt displacement by embedding generative AI capabilities into existing workflow automation before challengers capture the interface layer. Defend position through backward integration into proprietary data lakes that reduce third-party API dependency. Prioritize HIPAA and SEC compliance module development to lock out horizontal competitors in healthcare and financial services verticals. For New Entrants and Emerging Players: Mexican e-commerce platforms serving cross-border United States consumers represent the most penetrable geography, with automation infrastructure gaps in Guadalajara and Monterrey manufacturing clusters. Target Canadian financial services disclosure automation as a regulatory-complexity moat against horizontal SaaS incumbents. Lead with localized Spanish-language campaign orchestration and peso-denominated pricing to bypass incumbent contract friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-native automation sub-segments as foundation-model APIs reduce proprietary R&D requirements. Long-term viability favors platforms with embedded workflow data flywheels rather than standalone point tools. Acquisition target archetype: vertical specialists with regulatory certification depth in healthcare or financial services. Watch hyperscaler partnership exclusivity announcements as inflection indicators for distribution access.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Journey Orchestration | Generative content production collapses creative-to-campaign workflows into unified pipelines for B2B velocity. |
| Compliance Module Development | HIPAA and SEC audit trail automation creates vertical moats against horizontal platform competition. |
| API Ecosystem Expansion | Pre-built CRM connectors reduce implementation cycles and capture professional services margins from integrators. |
| Geographic Expansion | Mexican e-commerce infrastructure addresses cross-border campaign execution for United States consumer targeting. |
| Strategic Partnership | Hyperscaler co-sell agreements unlock enterprise procurement channels and subsidize customer acquisition economics. |
Research Methodology
A standing panel of marketing operations directors, CRM platform engineers, compliance officers at financial institutions, and systems integrators provided ongoing calibration across the study. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, and healthcare GPO contract databases. Bottom-up deployment counts triangulated against top-down SaaS revenue estimates.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning deployment architecture, organization size tier, vertical industry, and integration complexity level. CAGRs derived from fitted adoption curves applied to addressable base estimates. Industry-specific inputs included state-level privacy statute enforcement timelines and healthcare marketing compliance rule evolution.
Macroeconomic conditions sit as an overlay; deviation in enterprise software budget cycles or cloud infrastructure pricing would shift the trajectory. Forecasts reflect assumptions about API standardization velocity and first-party data infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
United States Laboratory Automation Market
Automation
Middle East and Africa Workforce Management Market
Automation
Global Cloud Automation Market
Automation
Modular Laboratory Automation Market
Automation
Automation-As-A-Service Market
Automation
Database Automation Market
Automation
Lab Automation Market
Automation
IoT Home Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Automated Cell Block Systems Market
Automation
Automation Testing Market
Automation
Global Automated Sample Storage Systems Market
Automation
Automation Lifecycle Services Market
Automation
Voice Picking Solutions Market
Automation
Postal Automation System Market