
 Netherlands Digital Transformation Market | 2026-2036
Netherlands Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Digital Transformation Market Insights
Edge-to-cloud distributed architectures is reconfiguring how Dutch enterprises deploy software workloads across fragmented infrastructure. Microsoft Corporation leverages its Azure stack to anchor hybrid cloud deployments in Rotterdam's port logistics corridor. SAP SE sustains deep ERP integration capabilities for manufacturing clients navigating Industry 4.0 transitions. IBM Corporation competes through quantum-safe cryptography services targeting Dutch financial institutions.
Netherlands digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, and IoT sensors into enterprise operational technology, typically executed through API-native platforms with sub-100 millisecond latency requirements for real-time process control. The primary purpose is to replace legacy batch-processing systems with event-driven architectures that enable predictive maintenance and automated decision loops. Hybrid cloud deployments now dominate enterprise roadmaps as organizations balance sovereignty requirements against elasticity needs, while AI services capture expanding margin pools through recurring model-retraining contracts. Managed services across IoT device fleets represent the fastest-growing revenue line as industrial clients outsource edge infrastructure management.
The EU AI Act and GDPR jointly shape Dutch procurement standards by mandating risk-classification documentation and data residency guarantees for high-stakes algorithmic applications. The Netherlands Authority for Consumers and Markets enforces platform neutrality rules that constrain vertical lock-in by hyperscale providers. Stakeholders must monitor how the EU Cyber Resilience Act's forthcoming hardware certification requirements will ripple through IoT deployment timelines and supplier qualification protocols.
Market Dynamics
EU AI Act compliance deadlines are compressing Dutch enterprise procurement cycles, forcing organizations to accelerate vendor qualification and renegotiate cloud contracts with embedded algorithmic transparency clauses before enforcement phases activate.
Growth Catalysts
- GDPR-aligned data residency mandates:Dutch financial institutions and healthcare providers must maintain sovereign data storage, creating sustained demand for domestic hyperscale facilities and edge nodes.
- Rotterdam port logistics automation:Maritime cargo handlers are deploying IoT sensor networks and predictive analytics to optimize container throughput and reduce berth congestion.
- North Holland data center cluster expansion:Amsterdam's fiber-dense infrastructure and submarine cable landing points attract cloud providers establishing EU gateway operations.
Market Restraints
- Specialized cloud engineering talent scarcity:Dutch enterprises face recruitment bottlenecks for Kubernetes platform engineers and MLOps specialists, inflating project timelines.
- EU Cyber Resilience Act hardware certification delays:IoT device manufacturers must navigate extended approval processes for connected industrial equipment, stretching product launch schedules.
- Limited domestic semiconductor fabrication:Netherlands lacks advanced chip foundry capacity, creating dependency on Taiwanese and South Korean suppliers for edge computing hardware.
Strategic Opportunities
- Zeeland and Limburg secondary data center development:Lower land costs and renewable energy availability in southern provinces enable distributed infrastructure expansion beyond Amsterdam's constrained market.
- Quantum-safe cryptography services:Dutch banks and government agencies require post-quantum encryption migration pathways as quantum computing threats materialize.
- AI model retraining as recurring revenue:Managed services providers can capture margin pools through continuous fine-tuning contracts for domain-specific large language models in regulated industries.
Industry Challenges
- SAP ERP modernization complexity:Manufacturing firms struggle to decouple decades-old custom code modules from core systems during S/4HANA transitions, inflating integration costs.
- EU AI Act risk classification documentation:Enterprises deploying high-risk algorithmic systems must assemble technical files and conformity assessments with limited precedent guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Digital Transformation Market |
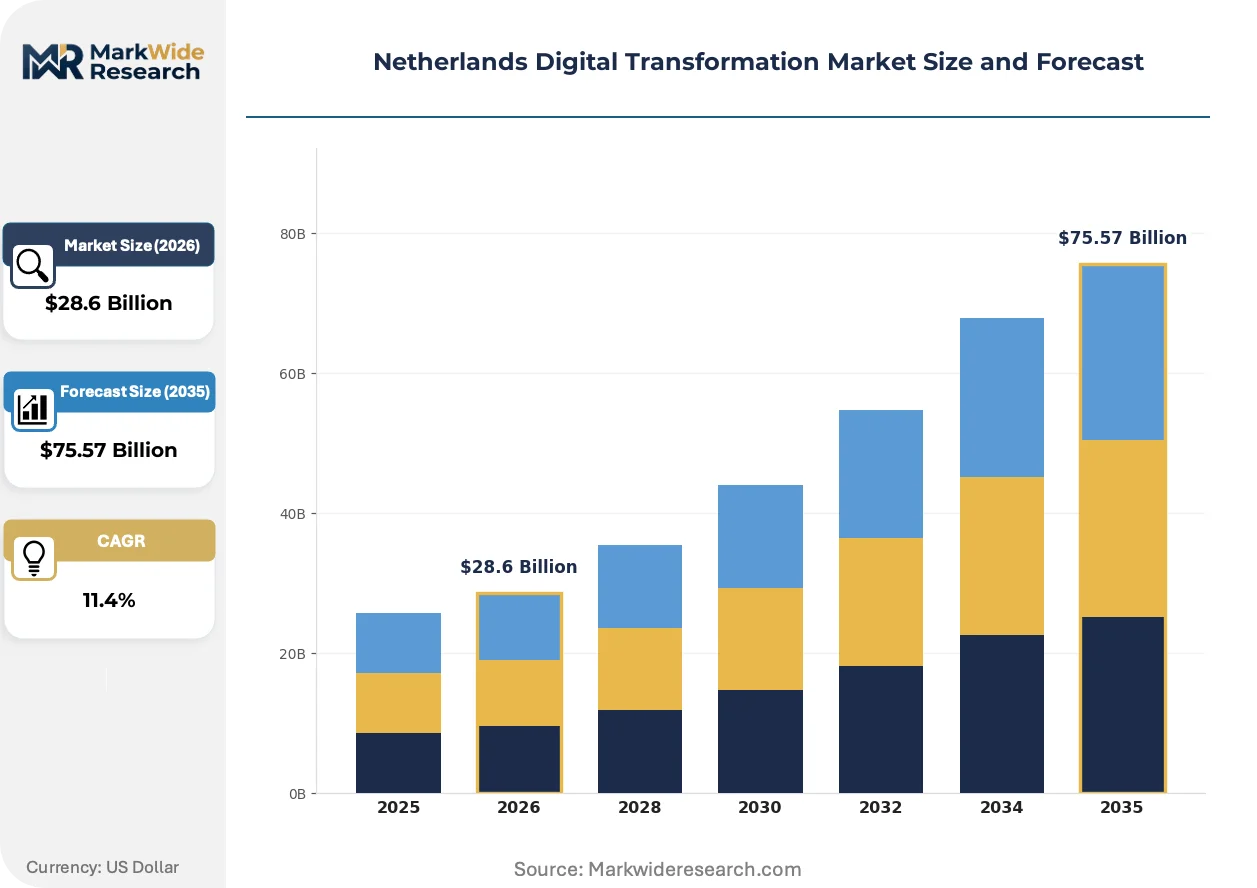
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Service Type: Consulting, Implementation, Managed Services, Support Industry Vertical: Healthcare, Retail, Education, Manufacturing Technology: AI, IoT, Big Data, Blockchain |
| Companies Covered | Accenture PLC, Google LLC (Alphabet Inc.), IBM Corporation, Microsoft Corporation, Oracle Corporation, Hewlett Packard Enterprise Company, SAP SE, Capgemini SE, Cognizant Technology Solutions Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Digital Transformation Market Trends and Innovations
Dutch digital infrastructure is fragmenting across hybrid topologies as sovereignty requirements clash with elasticity demands, creating architectural complexity that vendors must address through unified management platforms.
Event-driven microservices architecture is migrating from batch-processing legacy systems in Dutch manufacturing and logistics operations. Process industry firms in the Port of Rotterdam corridor are adopting Apache Kafka-based streaming pipelines to enable real-time inventory positioning. This migration from monolithic ERP modules is compressing decision latency from hours to seconds for automated supply chain responses.
The EU AI Act's risk-based classification framework is reshaping Dutch enterprise AI procurement by mandating algorithmic impact assessments for high-stakes applications. Financial services firms deploying credit scoring models must now document training data provenance and bias testing protocols. Dutch insurers and pension funds are restructuring vendor contracts to embed audit rights and model explainability requirements.
Industrial buyers are consolidating managed services contracts for edge device fleets under single-source agreements rather than fragmented point solutions. Dutch chemical and food processing plants are outsourcing sensor maintenance, firmware updates, and security patching to specialized infrastructure operators. This concentration is most visible in North Brabant's high-tech manufacturing belt, where ASML suppliers seek unified IoT operations partners.
Netherlands Digital Transformation Market Segmentation

Segmentation reveals how Dutch enterprises allocate digital budgets across infrastructure models and service layers. Procurement cycles vary dramatically by deployment complexity and regulatory exposure.
Deployment Model:
Contract renewal cycles stretch from 12-month SaaS subscriptions to 5-year on-premise capital deployments, creating distinct vendor engagement rhythms across Dutch IT procurement.
- Public Cloud:Elastic compute and storage resources delivered through shared multi-tenant infrastructure. Amsterdam-based financial services firms favor public cloud for customer-facing applications requiring burst capacity during quarterly reporting periods.
- Hybrid Cloud:Orchestrated workload distribution across on-premise and cloud environments with unified management planes. Dutch manufacturers in North Brabant deploy hybrid architectures to keep proprietary process data on-site while leveraging cloud analytics for demand forecasting.
- Private Cloud:Dedicated infrastructure serving single-tenant environments with sovereign data guarantees. Healthcare providers in Utrecht mandate private cloud for patient records to satisfy GDPR Article 9 processing restrictions.
- On-Premise:Legacy infrastructure retained for latency-sensitive industrial control systems or regulatory holdback requirements. Rotterdam port operators maintain on-premise SCADA systems for berth automation where sub-10 millisecond response times are non-negotiable.
Hybrid Cloud anchors the volume base while Public Cloud gains share at the steepest rate as Dutch enterprises accelerate workload migration to EU-sovereign hyperscale regions.
Service Type:
Margin structures diverge sharply between one-time professional services and recurring managed contracts, reshaping how vendors build Dutch delivery organizations.
- Managed Services:Ongoing operational responsibility for infrastructure, applications, or security post-deployment. Dutch chemical producers in Zeeland outsource entire IoT sensor fleets to specialized operators, converting capital expenditure into predictable operational budgets.
- Implementation:Project-based system integration, data migration, and cutover execution. SAP S/4HANA transitions dominate implementation pipelines as manufacturing clients confront decade-old custom code entanglements.
- Consulting:Advisory engagements spanning digital strategy, architecture design, and change management. EU AI Act readiness assessments drive consulting demand among Dutch insurers preparing high-risk algorithmic system documentation.
- Support:Break-fix maintenance, patch management, and tiered helpdesk operations. Support contracts attach to nearly every on-premise deployment, though cloud-native architectures are compressing traditional support attach rates.
Implementation commands the largest project values while Managed Services delivers the stickiest recurring revenue streams across Dutch enterprise accounts.
Industry Vertical:
Regulatory intensity and legacy system age create divergent transformation velocities across Dutch sectoral buyers.
- Manufacturing:Industry 4.0 automation spanning predictive maintenance, digital twins, and supply chain orchestration. ASML's supplier ecosystem in Eindhoven drives concentrated demand for edge computing and real-time quality analytics.
- Healthcare:Electronic health record modernization, telemedicine platforms, and clinical AI diagnostics. Dutch hospital networks face GDPR Article 9 constraints that slow cloud adoption relative to less regulated sectors.
- Retail:Omnichannel commerce, inventory optimization, and customer data platforms. Amsterdam-headquartered e-commerce operators deploy event-streaming architectures for real-time personalization.
- Education:Learning management systems, campus IoT networks, and research computing infrastructure. Dutch technical universities require high-performance computing for simulation workloads that strain standard cloud configurations.
Manufacturing anchors the volume base while Healthcare expands most quickly as post-pandemic funding unlocks delayed infrastructure modernization.
Technology:
Technology layers stack unevenly, with foundational infrastructure enabling higher-order intelligent applications.
- AI:Machine learning model development, deployment pipelines, and MLOps governance. Dutch banks deploy credit scoring algorithms that must satisfy EU AI Act risk-classification documentation requirements.
- IoT:Sensor networks, edge gateways, and device management platforms at industrial scale. Port of Rotterdam cargo handlers instrument container movements with RFID and environmental monitors to optimize berth utilization.
- Big Data:Distributed storage, stream processing, and analytics platforms handling petabyte-scale datasets. Dutch logistics aggregators combine vessel tracking, weather feeds, and customs data for predictive arrival forecasting.
- Blockchain:Distributed ledger applications for supply chain provenance and trade finance documentation. Rotterdam port pilots blockchain for container bill-of-lading digitization, though enterprise adoption remains narrower than IoT or AI deployments.
IoT anchors the volume base while AI climbs the fastest as Dutch enterprises renegotiate cloud contracts to embed model-retraining services.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch digital infrastructure exports service demand across the Rhine corridor into Germany and Benelux neighbors, with Amsterdam's submarine cable landing points anchoring transatlantic data flows to London and New York financial centers.
Randstad
North Holland's data center cluster concentrates hyperscale cloud capacity and fintech algorithmic trading infrastructure. GDPR Article 9 enforcement by the Dutch Data Protection Authority accelerates sovereign cloud procurement among Amsterdam-headquartered insurers. The Amsterdam Internet Exchange processes traffic for European digital service providers expanding EU gateway operations.
Brabant
Eindhoven's high-tech manufacturing belt drives edge computing demand for ASML supplier ecosystem quality analytics. The EU AI Act's high-risk system documentation requirements compress procurement cycles for predictive maintenance platforms. Waalre-based chemical processors outsource IoT fleet management to specialized infrastructure operators under consolidated managed services contracts.
Rotterdam Port Logistics Corridor
Maritime cargo handlers deploy container-tracking sensor networks and berth-optimization algorithms. The Netherlands Authority for Consumers and Markets enforces platform neutrality rules constraining vertical lock-in by hyperscale providers. Maasvlakte terminal operators maintain sub-10 millisecond SCADA response times through on-premise industrial control systems.
Zeeland
Lower land costs and North Sea wind energy availability attract secondary data center development beyond Amsterdam's constrained market. The EU Cyber Resilience Act's forthcoming hardware certification requirements delay IoT device approvals for connected industrial equipment. Vlissingen chemical producers convert capital expenditure to operational budgets through outsourced sensor fleet management.
Northern Netherlands
Groningen's energy transition infrastructure requires digital twin deployment for grid modernization and renewable integration. Dutch national broadband rollout programs accelerate fiber-to-the-premises coverage for rural enterprise connectivity. Leeuwarden agritech clusters adopt precision farming sensor networks under EU Common Agricultural Policy digitization incentives.
Netherlands Digital Transformation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Dutch enterprise accounts, with consolidated hyperscale providers anchoring public cloud volume while fragmented service specialists capture implementation and managed services margin. The vendor base stratifies into three archetypes: full-stack platform operators, ERP-centric system integrators, and boutique compliance consultancies. M&A activity concentrates among mid-cap service firms seeking EU AI Act documentation capabilities, while strategic partnerships between cloud hyperscalers and domestic data center operators accelerate sovereign infrastructure deployment.
Within the full-stack platform tier, Microsoft Corporation and Google LLC exemplify channel-controlling players leveraging Amsterdam-region cloud regions to anchor hybrid deployments. SAP SE occupies a position as the ERP-centric system integrator archetype, with S/4HANA transitions dominating manufacturing client pipelines. IBM Corporation sits within the specialized services tier, representing quantum-safe cryptography and compliance advisory positioning for Dutch financial institutions navigating post-quantum encryption migration pathways.
| Leading Market Players |
|---|
| Accenture PLC |
| Google LLC (Alphabet Inc.) |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Hewlett Packard Enterprise Company |
| SAP SE |
| Capgemini SE |
| Cognizant Technology Solutions Corporation |
| Others |
Pricing and Supply Chain Analysis
Rotterdam port logistics corridor freight dynamics compress margin structures for edge computing hardware flowing into Dutch manufacturing zones, amplifying price differentiation between hyperscale-integrated deployments and fragmented point solutions while accelerating buyer consolidation around managed services contracts.
Pricing Analysis
Legacy ERP-to-cloud migration pricing gaps separate on-premise perpetual licenses from subscription SaaS tiers and emerging consumption-based AI model hosting. Three-tier pricing structure across premium sovereign-cloud, standard public-cloud, and economy shared-tenant levels reflects GDPR compliance certification and data residency guarantees as primary differentiation drivers. Cost compression in standard tiers intensifies as Microsoft and Google expand Amsterdam-region capacity. Mid-market manufacturers exhibit highest price sensitivity, while Dutch financial institutions prioritize compliance premiums over unit economics.
Supply Chain Analysis
US export controls on advanced GPU and AI accelerator chips constrain flows into Dutch cloud infrastructure buildouts, forcing reliance on approved-channel procurement. Taiwan and South Korea anchor semiconductor supply for edge devices, while Chinese sensor manufacturers feed IoT deployment pipelines. Memory modules, networking silicon, and specialized AI training hardware constitute critical input dependencies. Single-source vulnerability concentrates around advanced node foundry capacity. Distribution runs through Amsterdam-based value-added resellers and direct hyperscale enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dutch digital transformation is approaching a platform-economics inflection as API-native interoperability standards displace monolithic ERP lock-in, with ASML supplier ecosystem demands accelerating ecosystem openness requirements.
For Market Incumbents: Pre-empt margin erosion in implementation services by embedding AI model retraining into recurring managed services contracts before cloud hyperscalers capture this revenue pool. Acquire boutique EU AI Act compliance consultancies to defend documentation service attach rates against SAP and Oracle vertical integration moves.
For New Entrants and Emerging Players: Pursue Zeeland and Limburg secondary data center development white space where land costs and renewable energy availability undercut Amsterdam-region pricing. Target chemical processing and agritech segments in North Brabant with unified IoT fleet management offerings, leveraging outsourced sensor maintenance demand as the beachhead entry angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap system integrators stranded between hyperscale channel compression and ERP vendor consolidation. Position for five-to-ten year viability around quantum-safe cryptography and post-quantum migration service capabilities. Watch for EU Cyber Resilience Act hardware certification bottlenecks as the signal indicating distressed asset availability among IoT device manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Hyperscaler alliances with Dutch data center operators accelerate sovereign cloud deployment timelines. |
| Acquisition of Specialist Firm | EU AI Act documentation capabilities capture compliance-driven procurement budgets from insurers. |
| Platform Integration | Apache Kafka streaming pipelines displace batch ERP modules in Rotterdam port logistics. |
| Geographic Expansion | Zeeland secondary data center development exploits renewable energy and land cost arbitrage. |
| Product Launch | Quantum-safe cryptography services address Dutch bank post-quantum encryption migration requirements. |
Research Methodology
Operator-level perspectives from cloud infrastructure architects, MLOps specialists, data protection officers, and industrial IoT procurement leads anchored the qualitative base. Primary interviews combined with secondary validation drawn from ACM enforcement decisions, Autoriteit Persoonsgegevens GDPR rulings, hyperscaler capex disclosures, and Dutch Customs trade flow data. Bottom-up project pipeline aggregation and top-down macroeconomic scaling triangulated market size estimates.
Scenario-bracketing framed projections across deployment model, service type, industry vertical, and technology layer dimensions. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion. Edge device shipment forecasts and cloud region capacity buildout timelines fed industry-specific inputs. Modeling spanned the projection horizon without year-specific anchoring.
Sensitivities concentrate around EU AI Act enforcement phase timing, EU Cyber Resilience Act hardware certification delays, and Taiwan semiconductor supply continuity. Forecasts embody documented assumptions subject to revision from regulatory implementation shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Digital Platform Scale Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Digital Transformation in Healthcare Market