
 United States Conversational AI Market | 2026-2036
United States Conversational AI Market Size, Share, and Industry Trends Forecast 2026-2036
United States Conversational AI Market Analytics
Enterprise software licensing is reconfiguring margin pools away from perpetual on-premises contracts toward consumption-based cloud APIs. Microsoft Corporation leverages its Azure OpenAI Service to anchor enterprise deployments across healthcare and financial services. Google LLC competes through deep integration of its Gemini models into Workspace and Contact Center AI, while Amazon Web Services, Inc. sustains market presence via Lex and Connect powering call-center automation at scale.
Conversational AI denotes software systems that process, interpret, and generate human language through natural language processing pipelines, transformer-based neural architectures, and real-time speech-to-text engines operating at sub-200-millisecond latency for interactive response. These systems automate dialog-driven tasks across customer service, internal IT helpdesks, and sales qualification workflows. Natural Language Processing occupies the dominant technology tier, as foundational large language models subsume narrower speech recognition and predictive analytics modules into unified inference stacks. Cloud-based deployment leads volume adoption, though hybrid configurations gain traction among banking end users subject to data residency requirements.
The Federal Trade Commission scrutinizes deceptive claims about AI capabilities under Section 5 of the FTC Act, while the Food and Drug Administration regulates conversational AI deployed as Software as a Medical Device in clinical decision support. NIST's AI Risk Management Framework shapes procurement criteria for federal contractors and primes enterprise buyers to demand model cards, bias audits, and red-team documentation. Stakeholders must monitor how state-level algorithmic accountability bills in California and New York fragment compliance obligations beyond federal baselines.
Market Dynamics
Enterprise procurement criteria for conversational AI systems are hardening around explainability mandates as NIST's AI Risk Management Framework permeates federal contracting requirements and cascades into private-sector RFP templates.
Growth Catalysts
- NIST AI Risk Management Framework:Federal contractors must now document model cards and bias audits, creating procurement pull-through that standardizes vendor capabilities across healthcare and financial services deployments.
- Healthcare patient intake automation:Providers embed conversational AI into triage workflows to reduce administrative burden and accelerate clinical decision timelines.
- Cloud API consumption models:Enterprise software licensing is reconfiguring margin pools away from perpetual on-premises contracts toward metered inference pricing.
Market Restraints
- GPU supply concentration:Training and inference workloads depend on NVIDIA hardware, creating chokepoint vulnerability for domestic model development.
- Data residency requirements:Banking end users subject to state-level financial privacy statutes impose hybrid deployment complexity that slows cloud-native adoption.
- Section 5 FTC Act enforcement:The Federal Trade Commission scrutinizes deceptive claims about AI capabilities, chilling marketing velocity for vendors without legal-review bandwidth.
Strategic Opportunities
- FDA Software as a Medical Device pathway:Conversational AI deployed in clinical decision support faces structured regulatory channels that, once cleared, create defensible market positioning.
- State algorithmic accountability legislation:California and New York bills fragment compliance obligations, creating advisory and audit service revenue streams for compliance-native vendors.
- Real-time speech-to-text latency compression:Sub-200-millisecond interactive response standards are enabling new use cases in high-stakes customer service environments.
Industry Challenges
- Transformer architecture specialization:The talent pool for large language model fine-tuning and alignment remains thin, inflating compensation for qualified ML engineers.
- Legacy system integration friction:Enterprise IT helpdesk automation requires API bridges to decades-old ticketing systems that lack modern webhook or REST interfaces.
- Red-team documentation burdens:Federal procurement now requires adversarial testing records that many vendors lack capacity to produce at RFP velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Conversational AI Market |
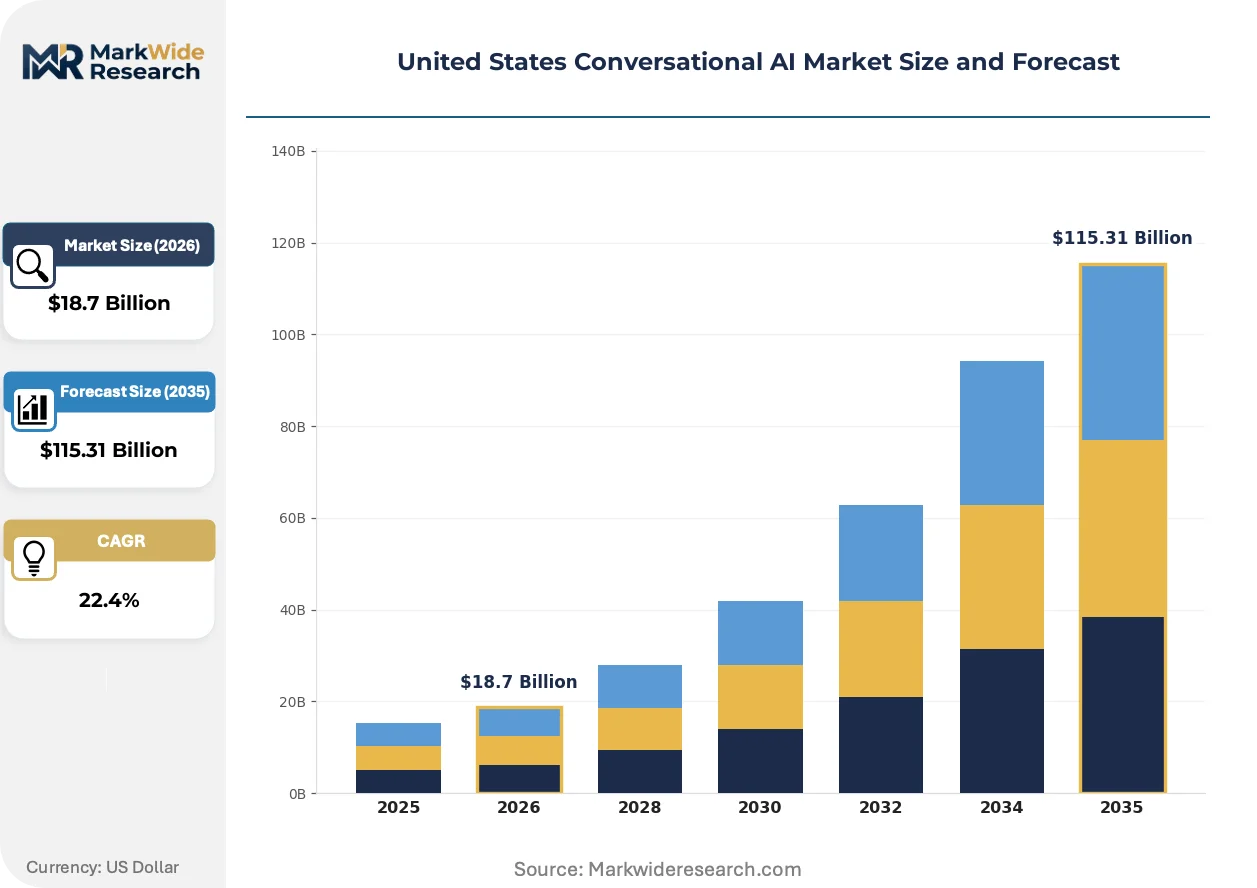
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Speech Recognition, Predictive Analytics End User: Retail, Healthcare, E-commerce, Banking Deployment: Cloud-based, On-premises, Hybrid, Managed Service Application: Customer Support, Virtual Assistants, Survey Automation, Lead Generation |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon Web Services, Inc., IBM Corporation, OpenAI, Nuance Communications, Inc., Salesforce, Inc., Oracle Corporation, Yellow.ai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Conversational AI Market Evolving Landscape
Foundation model architectures are consolidating previously discrete NLP pipelines into unified inference stacks, compressing vendor specialization and reshaping competitive differentiation toward data moats and domain-specific fine-tuning.
Natural language processing is migrating from narrow intent-classification systems toward transformer-based neural architectures that subsume speech recognition and predictive analytics modules. Healthcare providers and financial services enterprises are adopting these unified stacks fastest, drawn by reduced integration overhead. The technology is migrating from fragmented point solutions toward consolidated inference platforms that collapse vendor count and compress procurement cycles.
The Food and Drug Administration's Software as a Medical Device framework is formalizing clinical validation requirements for conversational AI deployed in patient-facing triage. Vendors must now submit algorithm change control protocols and real-world performance monitoring plans. Healthcare systems in Massachusetts and Minnesota are responding by establishing internal AI governance committees that parallel traditional pharmacy and therapeutics committees.
Enterprise buyers are unbundling after-sales service contracts from core platform licenses, demanding itemized pricing for implementation, fine-tuning, and ongoing model maintenance. This pattern is most visible among Fortune 500 manufacturers in the Midwest that previously accepted bundled SaaS terms. Channel partners are responding by building specialized practices around conversational AI deployment rather than reselling generic cloud credits.
United States Conversational AI Market Segmentation
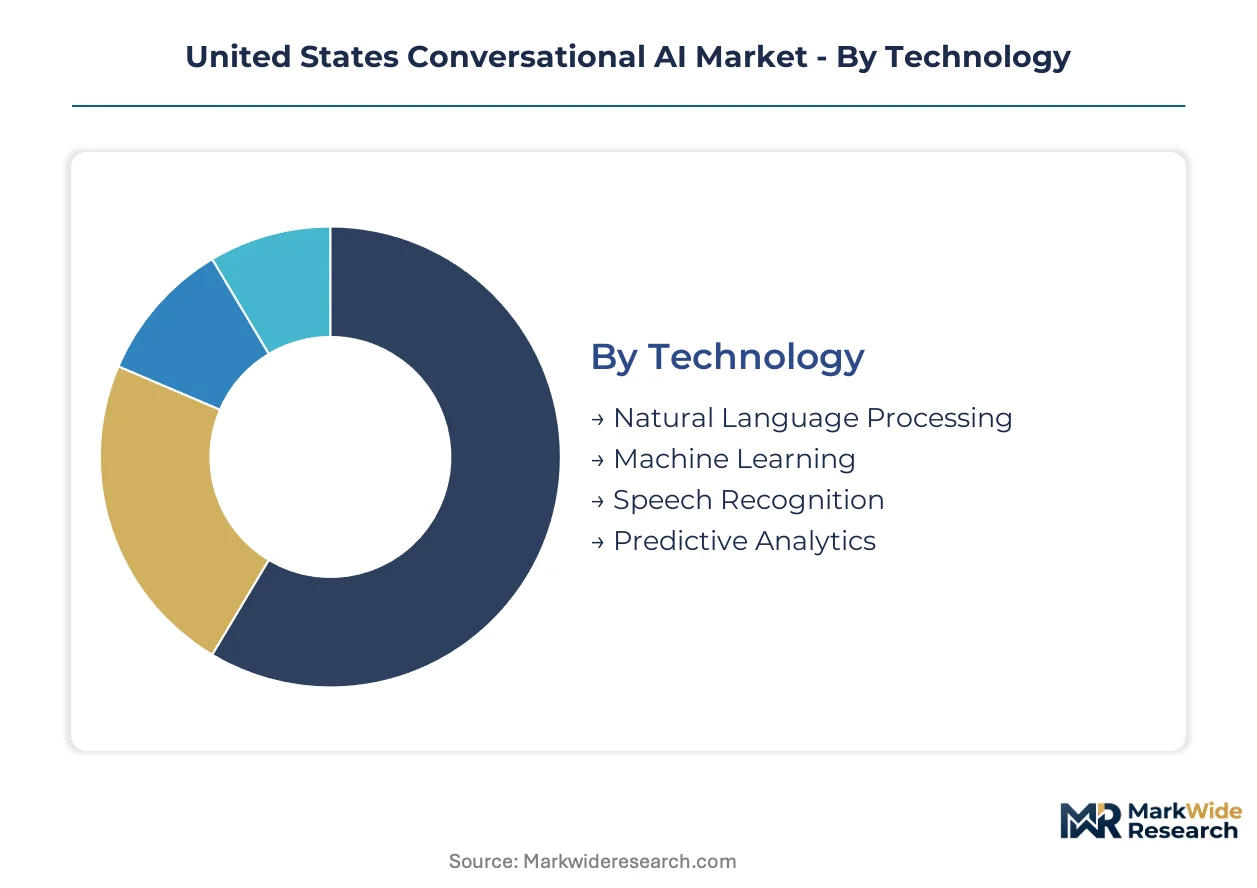
Segmentation reveals how conversational AI procurement diverges across technical stacks, regulatory exposure, and operational maturity. Buyers in regulated industries demand hybrid architectures, while cloud-native deployment dominates high-velocity retail and e-commerce channels.
Technology:
Natural language processing pipelines anchor use-case spectrum from clinical triage to real-time sales qualification, with transformer architectures subsuming narrower modules.
- Natural Language Processing:Foundational large language models power unified inference stacks that collapse previously discrete intent-classification and entity-extraction pipelines. Healthcare providers in Massachusetts and Minnesota deploy these systems for patient-facing triage, driven by FDA Software as a Medical Device pathway requirements that mandate explainable outputs.
- Machine Learning:Supervised and reinforcement learning frameworks enable domain-specific fine-tuning on proprietary enterprise corpora. Financial services institutions in New York and California concentrate procurement here, constrained by NIST AI Risk Management Framework documentation mandates for model cards and bias audits.
- Speech Recognition:Real-time speech-to-text engines operating at sub-200-millisecond latency.
- Predictive Analytics:Prognostic modules anticipating user intent from conversational context.
Established volume favors Natural Language Processing; emerging adoption favors Machine Learning.
End User:
Customer type determines deployment complexity, with banking and healthcare imposing data residency and audit requirements absent from retail and e-commerce.
- Healthcare:Providers embed conversational AI into patient intake and clinical decision support workflows, subject to FDA regulation as Software as a Medical Device. Systems must submit algorithm change control protocols and real-world performance monitoring plans, creating procurement friction that favors established vendors with regulatory affairs capacity.
- Banking:State-level financial privacy statutes impose hybrid deployment requirements that slow cloud-native adoption. Institutions concentrate in New York and California, where algorithmic accountability bills fragment compliance obligations beyond federal FTC Act baselines.
- Retail:High-velocity customer service automation with minimal regulatory overlay.
- E-commerce:Lead qualification and cart abandonment recovery at scale.
Healthcare commands premium pricing for compliance-heavy implementations; retail offers volume expansion with faster procurement cycles.
Deployment:
Margin structure varies sharply across infrastructure ownership models, with consumption-based APIs compressing upfront licensing revenue.
- Cloud-based:Metered inference pricing dominates volume adoption, particularly among e-commerce and retail end users seeking elastic capacity. Enterprise software licensing is reconfiguring margin pools away from perpetual on-premises contracts toward consumption-based cloud APIs.
- Hybrid:Configurations gain traction among banking end users subject to data residency requirements, combining on-premises inference with cloud-based model training. This architecture imposes integration complexity that slows deployment velocity but satisfies state-level financial privacy statutes.
- On-premises:Captive infrastructure for highest-sensitivity workloads.
- Managed Service:Outsourced operations with vendor assumption of maintenance burden.
Cloud-based deployment captures the steepest expansion trajectory; hybrid architectures secure longest contract tenures in regulated sectors.
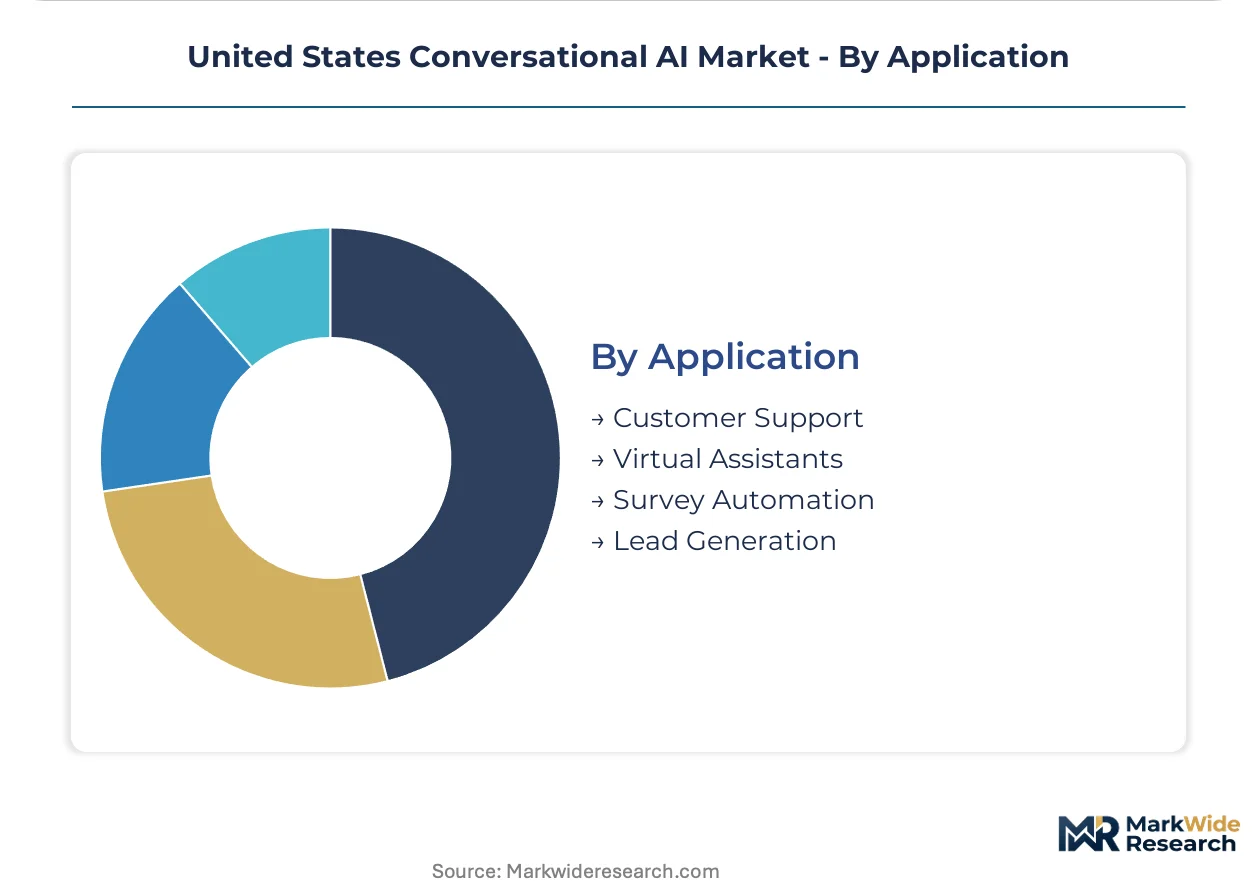
Application:
Functional use case shapes vendor selection criteria, with high-stakes environments demanding sub-200-millisecond latency and adversarial testing documentation.
- Customer Support:Call-center automation at scale powers enterprise procurement, with Amazon Web Services sustaining market presence via Lex and Connect. Real-time speech-to-text latency compression enables new use cases in high-stakes service environments where interactive response standards are tightening.
- Virtual Assistants:Internal IT helpdesk automation requires API bridges to decades-old ticketing systems that lack modern webhook or REST interfaces. Microsoft Corporation leverages Azure OpenAI Service to anchor these deployments across healthcare and financial services.
- Survey Automation:Structured data collection with conversational interfaces.
- Lead Generation:Sales qualification workflows with CRM integration.
Customer Support anchors current revenue concentration; Virtual Assistants are gaining share fastest as internal IT automation budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Bay Area and Seattle technology corridors concentrate enterprise procurement for cloud-native conversational AI, while healthcare systems in Massachusetts and Minnesota embed these systems into FDA-regulated clinical workflows. Banking institutions in New York and Texas impose hybrid deployment requirements that fragment adoption patterns across state-level privacy statutes.
California
Enterprise buyers cluster near major cloud providers in the Bay Area, driving consumption-based API adoption for customer service automation. The California Consumer Privacy Act and pending algorithmic accountability legislation impose documentation burdens on vendors deploying patient-facing triage systems. Healthcare providers in San Francisco and San Jose embed conversational AI into clinical decision support workflows subject to FDA Software as a Medical Device pathways.
Washington
Seattle's technology corridor anchors Azure OpenAI Service deployments across healthcare and financial services verticals. State-level financial privacy statutes complement federal FTC Act enforcement, creating layered compliance obligations for banking end users. Amazon Web Services sustains market presence via Lex and Connect powering call-center automation at scale from its Puget Sound infrastructure footprint.
New York
Financial services institutions concentrate procurement of machine learning frameworks for domain-specific fine-tuning on proprietary enterprise corpora. The state's algorithmic accountability bill fragments compliance obligations beyond federal NIST AI Risk Management Framework baselines. New York City metropolitan area banks impose hybrid deployment requirements that slow cloud-native adoption while satisfying data residency mandates.
Massachusetts
Healthcare systems establish internal AI governance committees that parallel traditional pharmacy and therapeutics committees for conversational AI deployment. FDA regulation as Software as a Medical Device requires algorithm change control protocols and real-world performance monitoring plans. Boston-area providers embed these systems into patient intake workflows to reduce administrative burden and accelerate clinical decision timelines.
Texas
Fortune 500 manufacturers in the Dallas-Fort Worth corridor unbundle after-sales service contracts from core platform licenses, demanding itemized pricing for implementation and ongoing model maintenance. State-level financial privacy statutes impose hybrid deployment complexity on banking end users. Austin's technology cluster attracts vendors building specialized practices around conversational AI deployment rather than reselling generic cloud credits.
United States Conversational AI Market Competitive Landscape
Capability concentration sits with specialized AI research organizations; scale advantage sits with hyperscale cloud providers with existing enterprise distribution. The market structures around three tiers: foundation model developers with proprietary architectures, cloud platforms with API monetization infrastructure, and vertical specialists with regulatory compliance expertise. Dominant competitive moves include strategic partnerships between model developers and cloud platforms, plus portfolio diversification into adjacent automation software.
Within the foundation model tier, OpenAI and Google LLC exemplify capability concentration through transformer architecture specialization. Microsoft Corporation and Amazon Web Services, Inc. occupy positions at the scale-driven end, leveraging existing enterprise relationships to anchor Azure OpenAI Service and Lex deployments. Nuance Communications, Inc. represents the vertical specialist archetype, with regulatory affairs capacity for FDA-cleared clinical applications. These three groupings—capability-first, scale-first, and compliance-native—define competitive positioning as procurement criteria harden around explainability mandates.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services, Inc. |
| IBM Corporation |
| OpenAI |
| Nuance Communications, Inc. |
| Salesforce, Inc. |
| Oracle Corporation |
| Yellow.ai |
| Others |
Value Network & Pricing Analysis
Northern California's GPU cluster capacity dynamics directly shape downstream pricing power for conversational AI vendors, as NVIDIA hardware concentration in San Jose and Santa Clara creates chokepoint leverage that propagates through cloud API tiers.
Pricing Analysis
Long-term offtake contracts between hyperscale cloud providers and enterprise buyers dominate procurement structures, though metered inference pricing gains share among retail and e-commerce adopters seeking elastic capacity. Price differentiation separates FDA-cleared clinical deployments from standard customer service tiers, with compliance documentation and adversarial testing records commanding substantial premiums. Cost compression in mid-market SaaS tiers is intensifying because GPU supply concentration limits vendor bargaining power with upstream hardware suppliers. Fortune 500 manufacturers exhibit highest price sensitivity, while healthcare systems facing FDA Software as a Medical Device pathways show lowest elasticity due to regulatory switching costs.
Supply Chain Analysis
Upstream feedstock dependencies center on advanced semiconductor manufacturing anchored in Taiwan, South Korea, and the United States, with NVIDIA's foundry arrangements determining training and inference workload capacity. Specialized AI accelerators, high-bandwidth memory modules, and precision cooling systems constitute critical component inputs. Single-source vulnerability around leading-edge GPU architectures creates systemic exposure for domestic model development. Distribution runs through hyperscale cloud platforms—Microsoft Azure, Amazon Web Services, and Google Cloud—who intermediate hardware access via API monetization infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conversational AI incumbents face acute substitution pressure from open-source foundation models that erode proprietary API differentiation, requiring defensive repositioning around compliance-native capabilities and vertical integration.
For Market Incumbents: Entrench regulatory affairs capacity as the primary defensive moat, particularly FDA Software as a Medical Device clearance pathways that create switching costs for healthcare deployments. Pursue backward integration into specialized fine-tuning infrastructure to reduce dependency on hyperscaler compute pricing. Open-source model proliferation represents the core substitution threat; counter by embedding explainability documentation and bias audit capabilities that exceed NIST AI Risk Management Framework baselines. For New Entrants and Emerging Players: Mid-market banking institutions in Texas and Florida represent the most penetrable entry point, as state-level financial privacy statutes fragment compliance obligations and slow incumbent response velocity. Healthcare AI governance committees in Massachusetts and Minnesota offer advisory service entry angles before full platform deployment. A compliance-native go-to-market positioning—leading with model cards and red-team documentation rather than raw capability—differentiates against scale-first competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with regulatory clearance capacity over undifferentiated API resellers. Long-term viability hinges on data moat sustainability and domain-specific fine-tuning expertise rather than foundational model access. The signal to watch is FDA enforcement velocity against uncleared clinical decision support deployments, which would accelerate consolidation toward compliance-native vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Clearance Pathway | FDA Software as a Medical Device submission creates defensible positioning in clinical triage workflows. |
| Strategic Partnership | Alliances between foundation model developers and hyperscale cloud platforms anchor enterprise distribution. |
| Acquisition of Specialist Firm | Purchasing compliance-native vendors with bias audit capabilities accelerates federal contractor eligibility. |
| Platform Integration | Deep embedding into Workspace and Contact Center AI stacks captures high-velocity retail automation demand. |
| Geographic Expansion | Seattle and Bay Area technology corridor presence clusters procurement near major cloud provider headquarters. |
Research Methodology
Operator-level perspectives from CTOs at healthcare systems, IT procurement officers at financial institutions, platform engineers at hyperscale cloud providers, and integration specialists at channel partners anchored the qualitative base. These primary insights combined with secondary validation from SEC filings, hyperscaler capex disclosures, FDA 510(k) and De Novo submission databases, and state-level algorithmic accountability bill tracking. Bottom-up deployment estimates and top-down market sizing triangulated through cross-reference against enterprise software licensing trend analysis.
Scenario-bracketing around GPU supply constraints, federal procurement velocity, and state regulatory fragmentation informed the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, technology stack, and regional adoption pattern. CAGRs derived from elasticity-adjusted demand curves incorporating NIST framework compliance timelines and FDA clearance pathway durations.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT capital expenditure cycles and cloud consumption growth rates would shift the trajectory. Forecasts reflect documented assumptions regarding hyperscaler pricing discipline and regulatory enforcement velocity. Cross-checking against hyperscaler earnings call commentary on AI infrastructure revenue is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
Artificial Intelligence of Things (Aiot) Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations Platform Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
AI Datasets Market