
 ACE Inhibitors Market | 2026-2036
ACE Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
ACE Inhibitors Market Analysis
The gap between patented combination therapies and commoditized monotherapy generics is broadening in the ACE inhibitors space. Pfizer Inc sustains its position through vertical integration into active pharmaceutical ingredient sourcing for lisinopril. Novartis AG differentiates via sustained-release formulation technology that extends patent-protected revenue streams. Teva Pharmaceutical Industries Ltd competes aggressively on cost, leveraging its scale in oral solid dose manufacturing to occupy the generic tier.
ACE inhibitors constitute a class of vasodilating agents that suppress angiotensin-converting enzyme activity, thereby reducing angiotensin II production and lowering systemic vascular resistance; most members are small-molecule prodrugs or active acids administered in 2.5 mg to 40 mg daily doses for hypertension and heart failure management. The oral delivery mode dominates prescription volumes, though the injectable segment leads in acute myocardial infarction settings where rapid hemodynamic control matters. Among applications, hypertension represents the mature volume base while diabetic nephropathy protocols are driving faster label expansion as nephrology societies tighten proteinuria targets.
The FDA governs bioequivalence standards for generic substitutions, while the EMA's MDR framework shapes post-market surveillance obligations for European suppliers. Health Canada and the TGA enforce comparable chemistry, manufacturing, and controls requirements that determine which manufacturers gain multi-region market access. Stakeholders must monitor evolving pharmacovigilance mandates and biosimilar guidance documents that could redraw competitive boundaries between originator and generic portfolios.
Market Dynamics
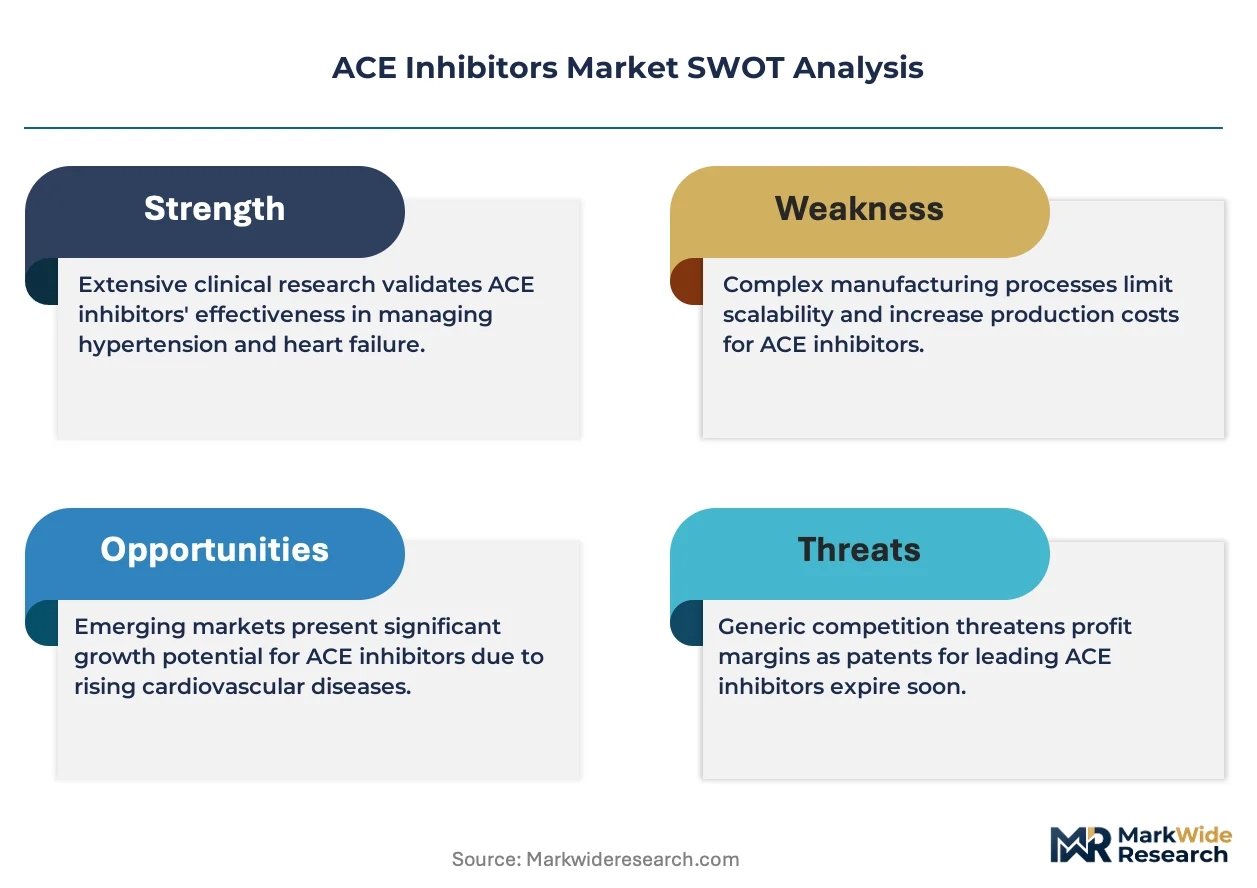
The ACE inhibitors market is experiencing a structural bifurcation between commoditized monotherapy generics and patent-protected combination formulations, driven by tightening bioequivalence standards from the FDA and EMA that favor manufacturers with advanced analytical capabilities.
Growth Catalysts
- Diabetic nephropathy protocol expansion:Nephrology societies in the United States and Germany are tightening proteinuria targets, expanding ACE inhibitor prescriptions beyond hypertension into renal protection.
- EMA MDR framework implementation:Post-market surveillance obligations are consolidating manufacturing capacity among suppliers with robust pharmacovigilance systems, reducing fragmentation.
- Hospital procurement standardization:Cardiovascular disease treatment protocols in acute care settings are mandating specific ACE inhibitor formularies, locking in volume commitments.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for lisinopril and enalapril concentrates in China and India, exposing formulators to geopolitical disruption and quality variability.
- ARB substitution threat:Angiotensin receptor blockers with superior side-effect profiles are displacing ACE inhibitors in first-line hypertension protocols, particularly in Japan.
- FDA bioequivalence compliance costs:Updated guidance on generic ACE inhibitor dissolution profiles requires expensive analytical method redevelopment for smaller manufacturers.
Strategic Opportunities
- Sustained-release formulation patents:Novel delivery technologies extending half-life profiles offer pathway to differentiated pricing in markets where Medicare and NHS reimbursement favors incremental innovation.
- Injectable segment expansion:Acute myocardial infarction protocols in emergency departments present underpenetrated channel for rapid-onset ACE inhibitor administration.
- Health Canada harmonization:Alignment of chemistry manufacturing controls with FDA standards creates streamlined multi-region access for compliant suppliers.
Industry Challenges
- Analytical method transfer complexity:Bioequivalence testing for generic ACE inhibitors requires specialized dissolution apparatus and trained personnel that contract research organizations struggle to scale.
- Legacy inventory reconciliation:Wholesaler stocking patterns for oral solid doses create working capital strain when regulatory batch recalls disrupt distribution continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ACE Inhibitors Market |
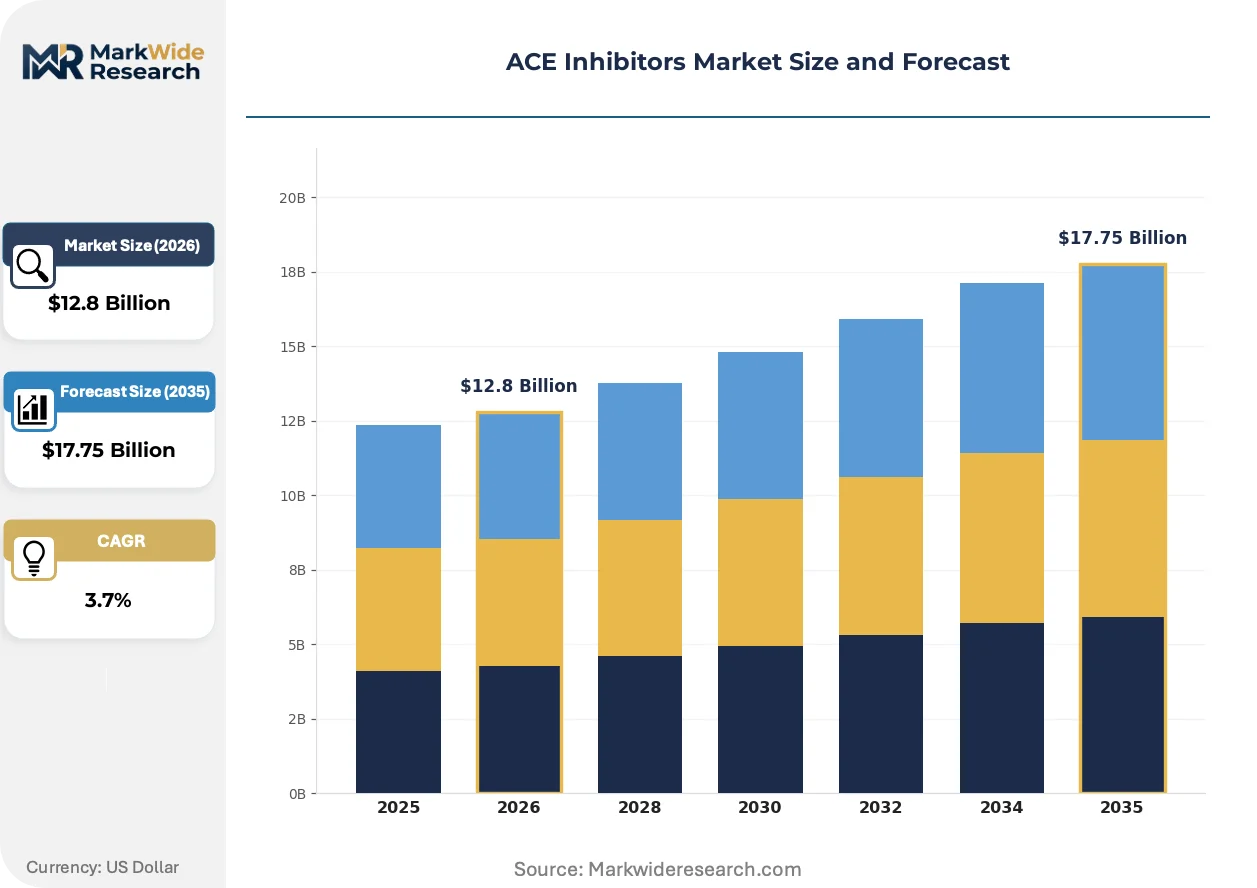
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.75 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ramipril, Lisinopril, Enalapril, Benazepril Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Clinics, Hospitals, Home Care, Pharmacies Application: Hypertension, Heart Failure, Diabetic Nephropathy, Acute Myocardial Infarction |
| Companies Covered | Merck KGaA, Bayer AG, Pfizer Inc, Boehringer Ingelheim International GmbH, AstraZeneca Plc., Novartis AG, Sanofi S.A, Teva Pharmaceutical Industries Ltd., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ACE Inhibitors Market Emerging Trajectories
Sustained-release formulation technologies are reshaping competitive boundaries in the ACE inhibitors space, enabling patent extensions and therapeutic differentiation. Manufacturing compliance requirements are intensifying as regulators harmonize bioequivalence standards across major markets.
Fixed-dose combination tablets pairing ACE inhibitors with diuretics or calcium channel blockers are expanding into standard hypertension protocols. Hospital formularies in the United States and Germany are adopting these combinations at accelerating rates, compressing demand for standalone monotherapy products.
The FDA's updated bioequivalence guidelines for generic ACE inhibitors are mandating more rigorous dissolution profile matching. Manufacturers with in-house analytical development capabilities are capturing multi-source contract opportunities, while smaller generic suppliers face forced exit or acquisition.
Hospital procurement consortia are consolidating purchasing decisions for oral cardiovascular medications. Group purchasing organizations in the United States are unbundling traditional wholesaler relationships, direct-contracting with manufacturers that demonstrate supply reliability and formulary compliance.
ACE Inhibitors Market Segmentation
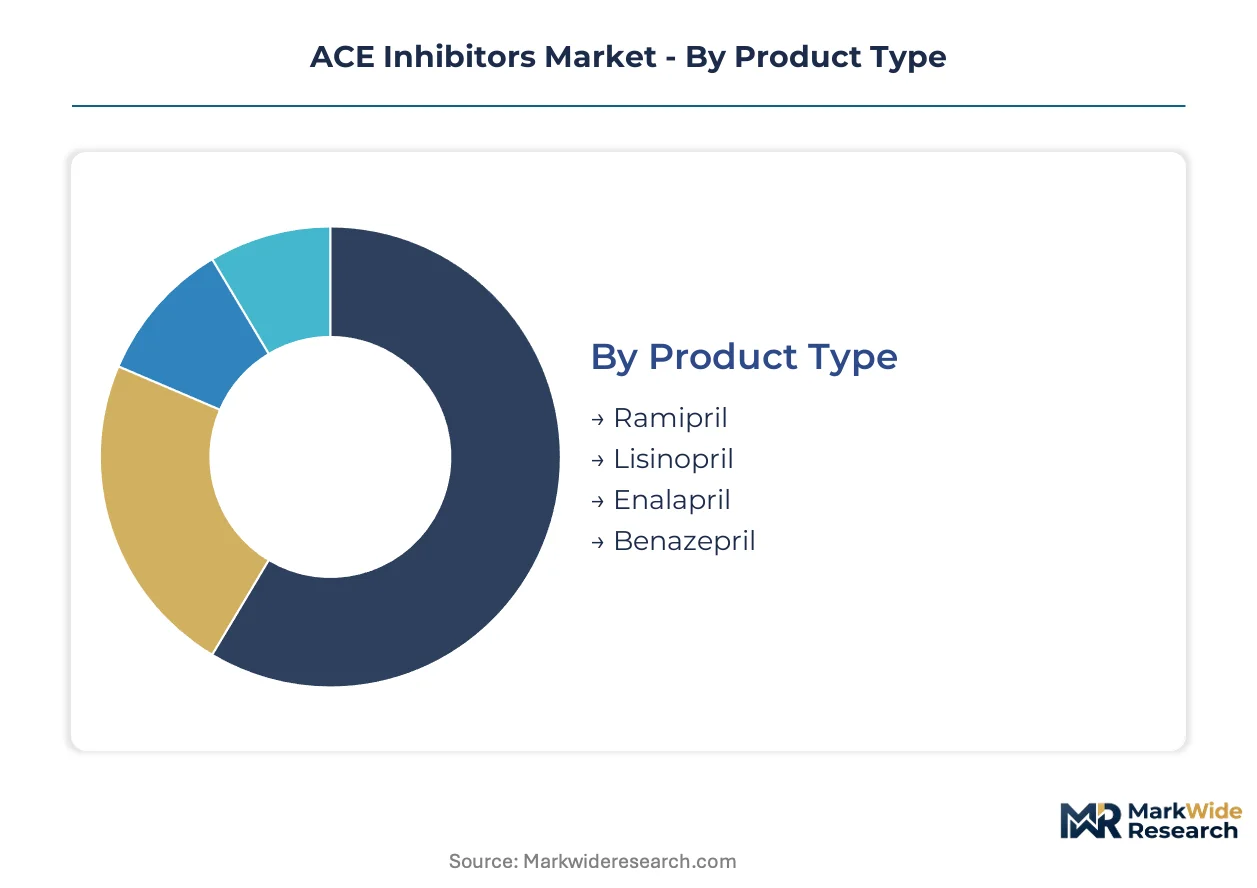
Segmentation in the ACE inhibitors market reveals how formulation choices and delivery pathways determine reimbursement eligibility and procurement access. Understanding these divisions exposes where manufacturers capture margin versus where commoditization erodes pricing power.
Product Type:
Upgrade cycles in ACE inhibitor prescribing follow patent expiration timelines and generic substitution protocols, with physicians switching patients based on bioequivalence confidence rather than molecular preference.
- Ramipril:This lipophilic prodrug exhibits superior tissue penetration and extended duration of action compared to hydrophilic alternatives. Hospital formularies in Germany and the United States favor ramipril for post-myocardial infarction protocols where cardiac remodeling prevention matters. EMA post-market surveillance requirements have tightened manufacturing documentation for this segment.
- Lisinopril:The only ACE inhibitor administered as an active drug rather than prodrug, lisinopril skips hepatic metabolism and offers predictable pharmacokinetics. Medicare Part D claims data show lisinopril dominating outpatient volume in the United States, though FDA dissolution profile updates are forcing analytical method upgrades among generic suppliers.
- Enalapril:This prodrug requires hepatic activation to enalaprilat, creating variable efficacy in patients with liver impairment.
- Benazepril:A lipophilic agent with dual renal and biliary elimination pathways, benazepril serves patients with declining kidney function.
Volume placements concentrate in lisinopril; the faster expansion belongs to ramipril.
Delivery Mode:
Cost tiering separates acute intervention formats from maintenance therapy, with injectable commanding premium reimbursement and oral solid doses competing on manufacturing scale.
- Oral:Tablets and capsules dominate prescription volumes through convenient once-daily dosing and established bioequivalence frameworks. Hospital procurement consortia in the United States are consolidating oral ACE inhibitor purchasing through group purchasing organizations that demand supply reliability documentation.
- Injectable:Intravenous formulations enable rapid hemodynamic control in emergency departments and intensive care units. Acute myocardial infarction protocols in German and United States hospitals mandate injectable ACE inhibitors for hemodynamically unstable patients where oral absorption is compromised.
- Transdermal:Patch delivery systems remain investigational for ACE inhibitors due to molecular size and polarity challenges.
- Inhalation:Pulmonary delivery routes are preclinical for this drug class, with no approved products in major markets.
Oral formulations capture the volume base; injectable delivery is climbing the fastest as acute cardiovascular protocols standardize.
End User:
Customer type determines formulary access complexity, with hospitals demanding pharmacoeconomic evidence and home care requiring patient adherence support.
- Hospitals:Acute care facilities drive protocol-driven prescribing through cardiovascular treatment pathways. German hospital networks and United States health systems are mandating specific ACE inhibitor formularies for heart failure and myocardial infarction admission bundles.
- Clinics:Outpatient cardiology and nephrology practices manage dose titration and therapeutic monitoring. United States accountable care organizations are steering clinic prescribing toward generic lisinopril to meet Medicare quality metrics.
- Home Care:Post-discharge administration relies on patient self-management and caregiver training.
- Pharmacies:Retail dispensing channels handle the majority of maintenance prescriptions through automated refill programs.
Hospital procurement locks in the highest-value contracts; home care is gaining share fastest as discharge planning emphasizes outpatient continuity.
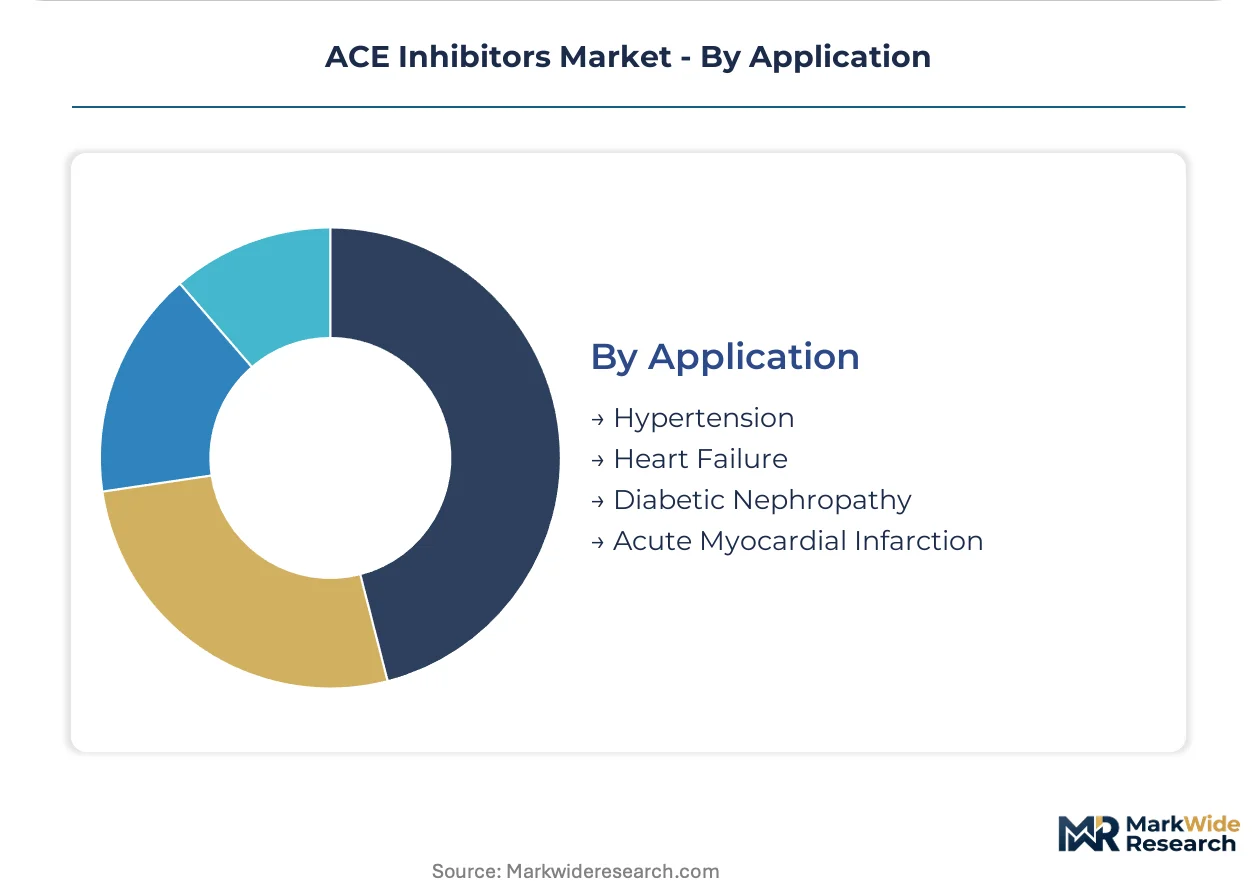
Application:
Maturity gradients separate established hypertension management from emerging renal protection indications where label expansion drives new prescriptions.
- Hypertension:First-line ACE inhibitor therapy for blood pressure reduction represents the mature volume foundation. United States Joint National Committee guidelines and European Society of Hypertension protocols maintain ACE inhibitors as initial therapy, though ARB substitution threatens share in Japan.
- Diabetic Nephropathy:Renal protection through proteinuria reduction is expanding fastest as nephrology societies tighten targets. American Diabetes Association and German Diabetes Society guidelines now recommend ACE inhibitors for all diabetic patients with elevated albuminuria, regardless of blood pressure status.
- Heart Failure:Chronic systolic dysfunction management relies on ACE inhibitors to reduce mortality and hospitalization.
- Acute Myocardial Infarction:Early post-infarction administration reduces ventricular remodeling and cardiovascular events.
Hypertension prescriptions represent the installed base; diabetic nephropathy is expanding most quickly as renal protection protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indianapolis anchors North American ACE inhibitor manufacturing through Eli Lilly's legacy infrastructure and surrounding contract research clusters. The city's pharmaceutical corridor supplies analytical services for FDA bioequivalence testing that generic manufacturers require.
United States
Medicare Part D reimbursement policies favor established ACE inhibitor therapeutic classes over novel alternatives. The FDA's updated dissolution profile guidelines mandate expensive analytical method redevelopment for generic suppliers. Indianapolis and Research Triangle Park host contract research organizations scaling bioequivalence testing capacity.
Germany
Hospital procurement networks in Bavaria and North Rhine-Westphalia mandate specific ACE inhibitor formularies for cardiovascular admission bundles. The EMA's MDR framework tightens post-market surveillance documentation requirements. Frankfurt's pharmaceutical logistics corridor consolidates distribution for Central European hospital consortia.
India
Active pharmaceutical ingredient production for lisinopril and enalapril concentrates in Hyderabad and Ahmedabad manufacturing zones. CDSCO harmonization with FDA chemistry manufacturing controls determines multi-region market access eligibility. Andhra Pradesh's bulk drug parks attract investment from formulators seeking backward integration into API supply.
China
Domestic cardiovascular disease protocols expand ACE inhibitor prescriptions in tier-one hospital systems across Shanghai and Beijing. NMPA bioequivalence standards for generic substitutions reshape manufacturing compliance requirements. Jiangsu province's pharmaceutical industrial parks scale oral solid dose capacity for export markets.
Japan
Angiotensin receptor blockers displace ACE inhibitors in first-line hypertension protocols at Tokyo and Osaka academic medical centers. PMDA pharmacovigilance mandates tighten post-approval safety reporting for renal protection indications. Kansai region's generic manufacturers face margin pressure from ARB substitution trends.
ACE Inhibitors Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and patent protection status. The market structures into three tiers: originators with sustained-release technologies, scaled generic manufacturers with FDA-compliant analytical capabilities, and regional suppliers serving price-sensitive hospital procurement. Strategic archetypes include patent-extending formulators, cost-optimized generic producers, and vertically integrated API-to-tablet suppliers. Competitive moves concentrate on sustained-release formulation licensing and hospital direct-contracting to bypass wholesaler relationships.
Among originator-tier pharmaceutical groups, Pfizer Inc and Novartis AG exemplify divergent approaches to ACE inhibitor market positioning. Pfizer's captive supply of active pharmaceutical ingredients for lisinopril production anchors its generic-tier competitiveness. Novartis occupies a position within patent-protected formulation development through sustained-release technologies. Teva Pharmaceutical Industries Ltd represents the scale-driven archetype, leveraging oral solid dose manufacturing volume to capture hospital procurement contracts.
| Leading Market Players |
|---|
| Merck KGaA |
| Bayer AG |
| Pfizer Inc |
| Boehringer Ingelheim International GmbH |
| AstraZeneca Plc. |
| Novartis AG |
| Sanofi S.A |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consortia in the United States and Germany dictate pricing power through volume commitments and formulary compliance requirements, compressing margins for generic manufacturers while sustaining premiums for patent-protected sustained-release formulations. This buyer concentration forces suppliers to absorb bioequivalence testing costs or exit the market entirely.
Pricing Analysis
Value-based pricing anchors on renal protection outcomes in diabetic nephropathy protocols, with reimbursement tied to proteinuria reduction metrics rather than pill count. Pricing stratifies across patent-protected combination tablets, FDA-compliant generic monotherapies, and commodity-grade oral solids from regional suppliers. Cost compression in the generic tier intensifies as Medicare Part D steers prescribing toward lowest-bid lisinopril suppliers. Hospital formularies exhibit lowest price sensitivity; retail pharmacy channels face highest pressure from automated substitution algorithms.
Supply Chain Analysis
FDA and EMA chemistry manufacturing controls certification gates market access, filtering out suppliers lacking validated analytical methods for dissolution profile matching. Active pharmaceutical ingredient production concentrates in India and China, with formulation finishing in the United States and Germany. Supply chains draw from lisinopril base, enalapril maleate, and ramipril intermediates. Single-source vulnerability in Hyderabad's bulk drug parks threatens continuity. Distribution runs through wholesaler networks and direct hospital contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API supply concentration in India and China props pricing for compliant manufacturers, as EMA MDR documentation requirements create capacity scarcity among European formulators. This bottleneck sustains margin premiums for suppliers with validated pharmacovigilance systems.
For Market Incumbents: Cement formulary lock-in through sustained-release formulation patents that extend exclusivity windows beyond base compound expiration. Secure backward integration into lisinopril API supply to insulate against Hyderabad quality variability. ARB substitution in Japan represents the primary demand threat; counter with renal protection label expansion in diabetic nephropathy protocols. For New Entrants and Emerging Players: Begin with injectable ACE inhibitor manufacturing for acute myocardial infarction protocols in German and United States emergency departments, where hospital procurement standardization creates volume commitments without entrenched generic competition. Target this underpenetrated channel through direct contracting with cardiovascular admission bundle administrators. For Investors and Strategic Acquirers: Distressed-cycle entries favor scaled generic manufacturers with FDA-compliant analytical capabilities in the United States Midwest, as bioequivalence guideline updates force smaller suppliers toward exit. Long-term viability hinges on sustained-release patent portfolios and hospital GPO relationships. Watch EMA MDR enforcement intensity as inflection signal for European manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sustained-Release Formulation Patent | Novartis extends revenue streams through half-life extension technology protected by EMA documentation. |
| API Backward Integration | Pfizer's captive lisinopril supply insulates margins from Hyderabad quality variability and tariff exposure. |
| Hospital Direct Contracting | Teva bypasses wholesaler relationships through group purchasing organization volume commitments in United States. |
| Injectable Segment Expansion | Manufacturers target acute myocardial infarction protocols in German hospital networks for premium reimbursement. |
| Health Canada Harmonization | Compliant suppliers unlock multi-region access through aligned chemistry manufacturing controls with FDA standards. |
Methodological Framework
Independent corroboration across regulatory filings, hospital procurement databases, and API trade flows underwrites the qualitative findings in this study. Primary interviews with formulary directors, regulatory affairs leads, and hospital procurement managers at cardiovascular treatment centers in the United States and Germany combined with secondary validation from FDA bioequivalence guidance documents, EMA MDR submissions, ClinicalTrials.gov renal protection studies, and Medicare Part D claims data. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis triangulate market sizing.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions include product type, delivery mode, end user, and application, with additional modeling of regional regulatory cluster dynamics. CAGRs derive from patent expiration timelines, generic substitution protocol adoption curves, and nephrology society guideline revision schedules. Forecast inputs incorporate EMA MDR implementation pace and Medicare reimbursement policy stability.
API supply disruption, ARB substitution acceleration, and bioequivalence guideline revision are the dominant revision risks to the modeling assumptions. A model refresh is warranted upon material change in FDA dissolution profile requirements or EMA pharmacovigilance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Propranolol Drug Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Antimycotics Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Olanzapine API Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Global Olanzapine Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market