
 Thromboprophylactic Drugs Market | 2026-2036
Thromboprophylactic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Thromboprophylactic Drugs Market Insights
A shift from hospital-exclusive procurement toward multi-source distribution is hardening across the thromboprophylactic drugs supply chain. Pfizer leverages its manufacturing scale to anchor heparin-based portfolios across North American and European channels. Boehringer Ingelheim differentiates through R&D intensity in direct oral anticoagulant innovation, while Sanofi competes on geographic dominance in injectable anticoagulant segments.
Thromboprophylactic drugs are pharmacological agents designed to prevent thrombus formation through anticoagulant, antiplatelet, or factor-specific inhibition mechanisms, typically administered via subcutaneous injection or oral tablet formulations with defined therapeutic windows. Their primary purpose centers on reducing venous thromboembolism incidence in surgical, immobilized, and at-risk cardiovascular populations. Direct oral anticoagulants command the fastest-expanding share of the product type landscape due to simplified dosing and reduced monitoring burden. Hospital end users retain the dominant volume position, though ambulatory surgical centers represent the most rapidly growing channel as same-day procedures expand prophylaxis into outpatient settings.
The US FDA, EMA, and WHO set divergent but converging standards for anticoagulant efficacy endpoints and bleeding-risk labeling, directly shaping clinical trial design and market access pathways for new entrants. Japan's PMDA maintains distinct pharmacokinetic requirements that delay or accelerate launch timelines depending on ethnic bridging data completeness. Stakeholders must monitor evolving pharmacovigilance mandates and regional bioequivalence standards to align portfolio investments with regulatory trajectories.
Market Dynamics
The thromboprophylactic drugs market is restructuring around pharmacovigilance intensification, with FDA and EMA tightening bleeding-risk labeling requirements that compress clinical trial timelines and elevate post-market surveillance costs for novel anticoagulant entrants.
Growth Catalysts
- Pre-operative anticoagulant protocols:Hospital-based surgical units in the United States, Germany, and Japan are hardening adoption of standardized prophylaxis regimens ahead of orthopedic and oncology procedures.
- REACH compliance pathways:European manufacturers leveraging streamlined chemical safety documentation are accelerating bioequivalence approvals for heparin derivatives across EU member states.
- Same-day surgical expansion:Ambulatory surgical centers in Japan and the United States represent the fastest-growing channel as outpatient procedure volumes displace inpatient stays.
Market Restraints
- Porcine mucosa supply concentration:Unfractionated heparin production depends on Chinese and European abattoir sourcing, exposing manufacturers to veterinary health policy disruptions and input cost volatility.
- Ethnic bridging data requirements:Japan's PMDA maintains distinct pharmacokinetic standards that delay launch timelines for direct oral anticoagulants lacking region-specific trial cohorts.
- Factor-specific inhibitor substitution:Antiplatelet agents and mechanical compression devices compete for prophylaxis share in low-risk surgical populations, pressuring anticoagulant volume in elective orthopedic settings.
Strategic Opportunities
- Underpenetrated oncology prophylaxis:Chemotherapy-associated thrombosis prevention remains inconsistently applied in German and Japanese outpatient infusion centers, creating white space for protocol standardization.
- Pharmacovigilance technology convergence:Integration of real-world evidence platforms with electronic health record systems is automating adverse event detection and compressing signal validation timelines for novel agents.
- IRA price negotiation carve-outs:Medicare reimbursement stability for preventive anticoagulants in the United States protects margin structures for manufacturers with established hospital formularies.
Industry Challenges
- Specialized hematology talent scarcity:Clinical pharmacologists with anticoagulant dosing expertise command premium compensation, constraining trial site activation and medical affairs scaling.
- Legacy heparin monitoring infrastructure:Hospital laboratories maintaining activated partial thromboplastin time testing capacity face capital allocation tension against DOA-specific assay investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thromboprophylactic Drugs Market |
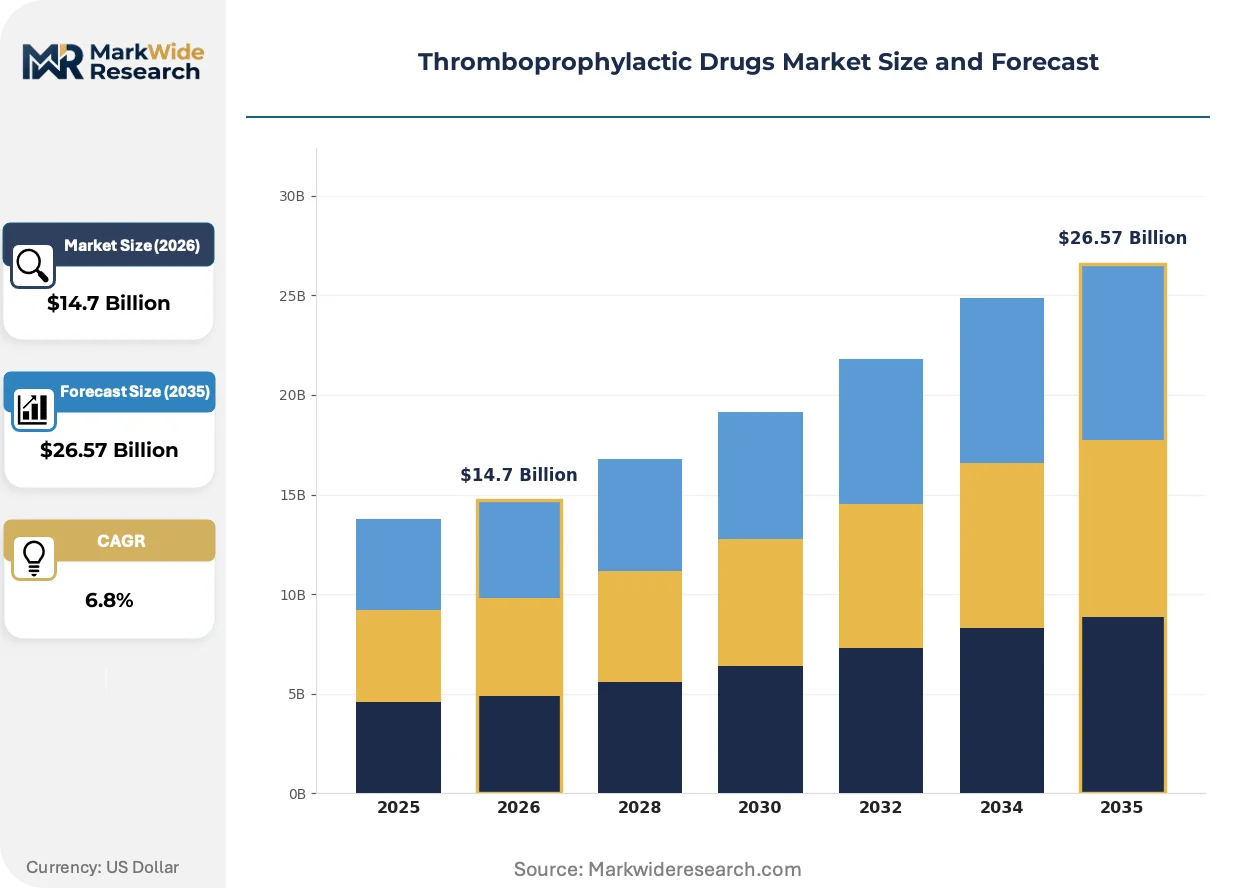
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Molecular Weight Heparin, Direct Oral Anticoagulants, Vitamin K Antagonists, Antiplatelet Agents, Factor Xa Inhibitors Indication: Deep Vein Thrombosis, Pulmonary Embolism, Atrial Fibrillation, Myocardial Infarction, Stroke Prevention End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories, Rehabilitation Centers Formulation: Injectable, Oral Tablets, Subcutaneous, Intravenous, Extended Release Capsules |
| Companies Covered | Bristol Myers Squibb, Bayer, Boehringer Ingelheim, Johnson & Johnson, Pfizer, Sanofi, Daiichi Sankyo, AstraZeneca, Dr. Reddy’s Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thromboprophylactic Drugs Market Trends and Innovations
Anticoagulant development is pivoting toward reduced-monitoring formulations and real-world evidence integration, compressing the gap between regulatory approval and clinical adoption while reshaping how hospital pharmacies manage formulary transitions.
Machine learning algorithms applied to electronic health record data are automating bleeding-risk stratification for surgical candidates. Large academic medical centers in the United States are deploying these tools pre-operatively to personalize prophylaxis selection. The technology is automating previously manual pharmacist review processes and accelerating protocol adherence.
EMA's tightened pharmacovigilance guidelines for novel oral anticoagulants now mandate extended post-authorization safety studies with active comparator arms. This policy shift is extending development timelines and elevating trial costs for factor Xa inhibitor programs. German and French regulators are enforcing these standards most stringently, prompting sponsors to front-load European trial recruitment.
Hospital procurement committees are consolidating anticoagulant purchasing through single-source contracts tied to bleeding complication outcome guarantees. This model is displacing traditional multi-source generic bidding in United States health systems and select German hospital networks. The shift is most visible in integrated delivery networks with captive pharmacy benefit management.
Thromboprophylactic Drugs Market Segmentation
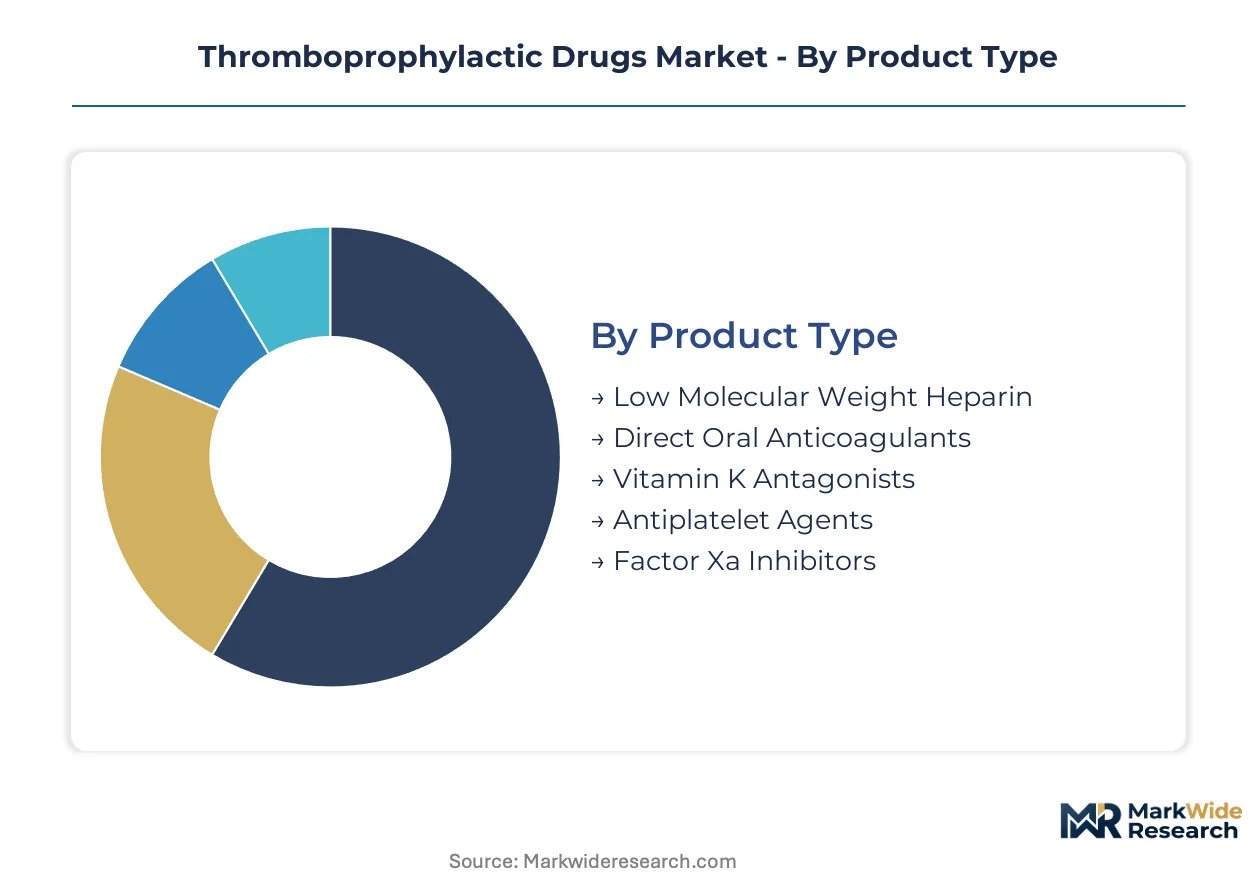
Thromboprophylactic drugs stratify across multiple dimensions that determine dosing protocols, reimbursement pathways, and procurement concentration. Product chemistry dictates monitoring infrastructure requirements, while end-user setting shapes administration training and formulary placement decisions.
Product Type:
Upgrade cycles from heparin-based monitoring to oral alternatives are compressing hospital pharmacy transition timelines as institutions weigh capital investment against nursing labor savings.
- Direct Oral Anticoagulants:Factor-specific inhibitors delivered in fixed-dose oral formulations eliminate activated partial thromboplastin time monitoring requirements. United States integrated delivery networks are prioritizing these agents in orthopedic surgery protocols to reduce nursing burden and accelerate discharge readiness.
- Low Molecular Weight Heparin:Fractionated porcine-derived polysaccharides with predictable pharmacokinetic profiles administered via subcutaneous injection. German hospital pharmacies maintain substantial procurement volumes due to established reversal protocols and cost containment pressures in statutory insurance reimbursement.
- Vitamin K Antagonists:Coumarin-derived compounds requiring international normalized ratio monitoring and dietary restriction counseling.
- Antiplatelet Agents:P2Y12 and cyclooxygenase inhibitors deployed in dual-antiplatelet regimens for cardiac surgical populations.
- Factor Xa Inhibitors:Direct synthetic inhibitors targeting coagulation cascade amplification with renal clearance dependency.
Low Molecular Weight Heparin sits at the top of the volume ranking, with Direct Oral Anticoagulants climbing the fastest.
Indication:
Cost tiering across indications separates prophylactic from therapeutic dosing markets, with prophylaxis commanding higher volume but lower per-dose reimbursement in ambulatory settings.
- Deep Vein Thrombosis:Lower extremity venous clot formation requiring immediate anticoagulation to prevent propagation. United States orthopedic surgery units in academic medical centers deploy extended prophylaxis protocols in total joint replacement populations.
- Atrial Fibrillation:Cardiac arrhythmia-associated stroke risk managed through chronic oral anticoagulation. Japanese cardiology clinics are expanding direct oral anticoagulant prescribing as PMDA labeling updates simplify dosing in elderly populations with renal impairment.
- Pulmonary Embolism:Acute thromboembolic occlusion of pulmonary vasculature requiring therapeutic anticoagulation.
- Myocardial Infarction:Coronary thrombosis events managed with combined antiplatelet and anticoagulant strategies.
- Stroke Prevention:Cerebrovascular event prophylaxis in high-risk cardiovascular populations.
Deep Vein Thrombosis anchors the indication landscape by procedure volume, with Atrial Fibrillation expanding most quickly as aging demographics broaden chronic therapy populations.
End User:
Customer type concentration determines sales force deployment, with hospital formulary committees requiring specialized clinical pharmacology engagement distinct from ambulatory procurement patterns.
- Hospitals:Inpatient surgical and medical units with pharmacy and therapeutics committees controlling formulary access. German hospital networks consolidate purchasing through regional procurement alliances that negotiate outcome-based contracts with bleeding complication guarantees.
- Ambulatory Surgical Centers:Same-day procedure facilities requiring rapid-onset, short-duration prophylaxis options. United States outpatient surgery expansion is displacing inpatient joint replacement volumes and redirecting anticoagulant demand toward take-home oral regimens.
- Specialty Clinics:Cardiology and hematology outpatient practices managing chronic anticoagulation therapy.
- Diagnostic Laboratories:Coagulation testing facilities supporting therapeutic drug monitoring for heparin and vitamin K antagonist therapy.
- Rehabilitation Centers:Post-acute care settings managing extended prophylaxis in immobilized patient populations.
Hospitals retain the dominant procurement position by value, with Ambulatory Surgical Centers gaining share fastest as procedure migration accelerates.
Formulation:
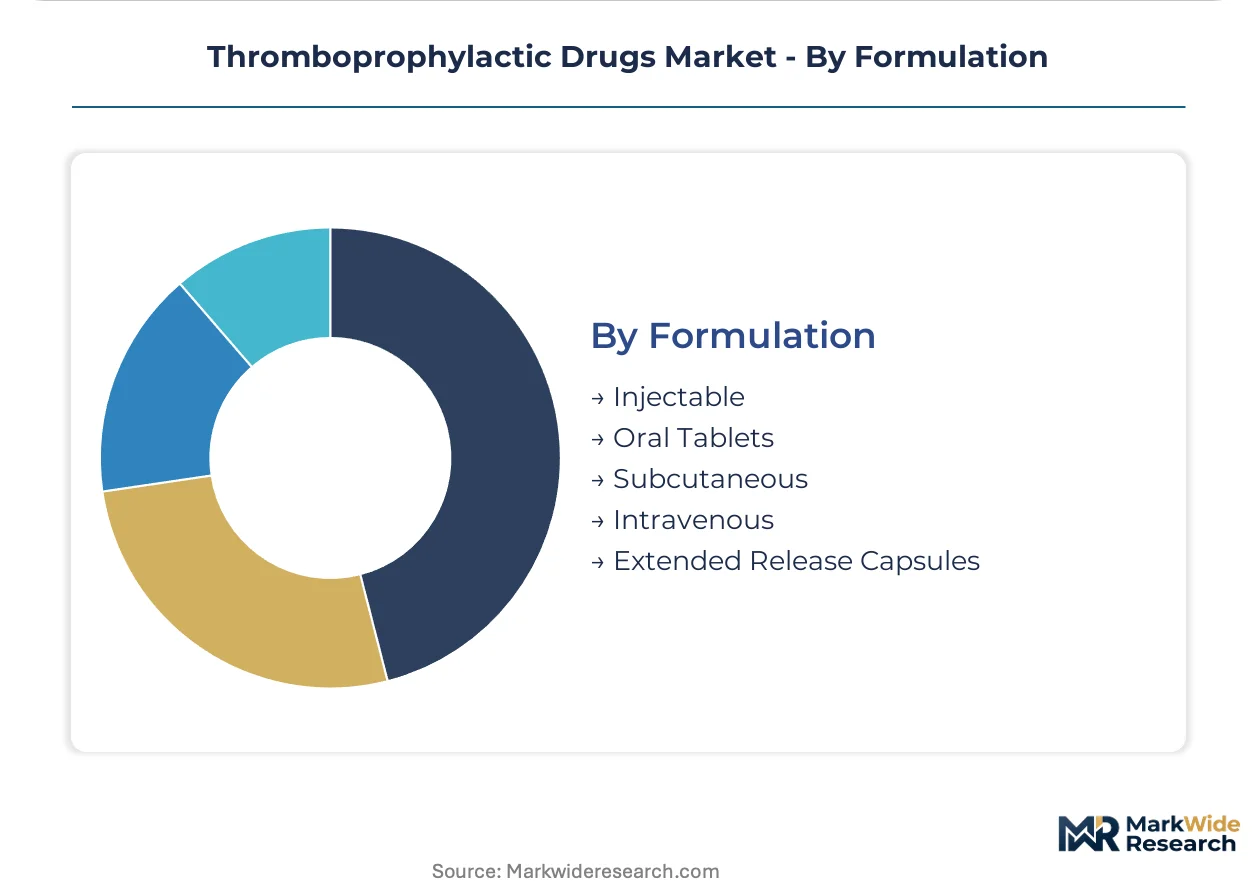
Supply concentration in injectable manufacturing creates margin pressure points distinct from oral solid dose production, where generic competition has intensified.
- Injectable:Parenteral formulations including unfractionated heparin and low molecular weight heparin requiring aseptic manufacturing capacity. Chinese active pharmaceutical ingredient suppliers dominate heparin sodium precursor production, exposing finished dose manufacturers to veterinary health policy disruptions.
- Oral Tablets:Solid dose direct oral anticoagulants with defined bioequivalence standards enabling generic substitution. United States FDA ANDA approvals for factor Xa inhibitor generics are compressing originator pricing power in Medicare Part D channels.
- Subcutaneous:Prefilled syringe and autoinjector presentations for patient self-administration.
- Intravenous:Hospital-administered unfractionated heparin for acute therapeutic anticoagulation.
- Extended Release Capsules:Modified-release formulations for reduced dosing frequency in chronic indications.
Injectable formulations command the highest manufacturing complexity premium, with Oral Tablets following the steepest expansion trajectory as outpatient prescribing displaces inpatient administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging regulatory compliance costs by concentrating heparin precursor production in jurisdictions with streamlined veterinary oversight, while finished-dose formulation migrates toward markets with favorable reimbursement velocity for direct oral anticoagulants.
United States
Hospital formulary committees at academic medical centers in Massachusetts and North Carolina are hardening adoption of extended prophylaxis protocols for total joint replacement populations. FDA bleeding-risk labeling updates for factor Xa inhibitors are compressing clinical trial timelines for novel entrants seeking Medicare Part D coverage. Integrated delivery networks in the Midwest are consolidating anticoagulant purchasing through single-source contracts tied to bleeding complication outcome guarantees.
Germany
Statutory insurance reimbursement pressures are sustaining procurement volumes for low molecular weight heparin in Bavarian and North Rhine-Westphalian hospital networks. EMA pharmacovigilance mandates for extended post-authorization safety studies are elevating trial costs for sponsors recruiting across Berlin and Frankfurt sites. Regional procurement alliances in Baden-Württemberg are negotiating outcome-based contracts that displace traditional multi-source generic bidding.
Japan
Aging demographics in the Kanto region are broadening chronic therapy populations for atrial fibrillation prophylaxis in Tokyo cardiology clinics. PMDA ethnic bridging data requirements for direct oral anticoagulants are delaying launch timelines for sponsors lacking region-specific trial cohorts. Ambulatory surgical centers in Osaka are expanding same-day procedure volumes and redirecting anticoagulant demand toward take-home oral regimens.
China
Veterinary health policy disruptions in Shandong and Jiangsu provinces are exposing heparin sodium precursor supply to input cost volatility. NMPA bioequivalence standards for generic factor Xa inhibitors are intensifying pricing pressure in hospital procurement channels. Active pharmaceutical ingredient manufacturers in the Yangtze River Delta are consolidating unfractionated heparin production capacity.
India
CDSCO abbreviated new drug application pathways for heparin derivatives are accelerating generic substitution in Maharashtra and Gujarat hospital networks. Cost-containment pressures in Tamil Nadu government procurement are sustaining demand for injectable anticoagulant formulations. Contract research organizations in Hyderabad are expanding pharmacokinetic study capacity to support ethnic bridging data generation for Japanese regulatory submissions.
Thromboprophylactic Drugs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar heparin and regional generic substitution. The vendor base stratifies across multinational originators with integrated hospital formulary access, mid-cap specialists concentrating on injectable manufacturing scale, and regional generic houses exploiting abbreviated approval pathways. Three archetypes dominate: R&D-intensive innovators with factor-specific inhibitor pipelines, manufacturing-scale operators anchoring heparin supply security, and geographic-focused distributors with deep ambulatory channel relationships. Competitive moves center on outcome-based contracting with integrated delivery networks and backward integration into porcine mucosa sourcing.
Within the manufacturing-scale tier, Pfizer anchors North American and European heparin-based portfolio distribution through production scale advantages. Boehringer Ingelheim occupies a position exemplifying R&D intensity in direct oral anticoagulant innovation. Sanofi represents geographic dominance in injectable anticoagulant segments across multiple continental markets.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Bayer |
| Boehringer Ingelheim |
| Johnson & Johnson |
| Pfizer |
| Sanofi |
| Daiichi Sankyo |
| AstraZeneca |
| Dr. Reddy's Laboratories |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks in the United States and regional procurement alliances in Germany anchor pricing power through single-source contracts tied to bleeding complication outcome guarantees, compressing margin structures for manufacturers outside preferred formularies. Hospital pharmacy and therapeutics committees exploit this buyer concentration to extract volume discounts against nursing labor savings from reduced-monitoring oral alternatives.
Pricing Analysis
Hospital formulary committee rebates determine net realized pricing across direct oral anticoagulant portfolios, with originator brands defending position through outcome guarantees while generic factor Xa inhibitors compete on bioequivalence certification and CMS Part D channel access. Price differentiation separates premium fixed-dose oral formulations from standard low molecular weight heparin injectables and economy-tier unfractionated heparin vials. Cost compression in the economy injectable tier intensifies as Chinese active pharmaceutical ingredient suppliers consolidate unfractionated heparin sodium precursor capacity. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement compression, while academic medical centers with captive pharmacy benefit management show lowest sensitivity to per-dose pricing.
Supply Chain Analysis
Single-source vulnerability sits with Chinese abattoir networks in Shandong and Jiangsu provinces supplying porcine mucosa for unfractionated heparin precursor extraction. Finished dose formulation draws from manufacturing scale in the United States, Germany, and India, with German statutory insurance channels sustaining procurement volumes for injectable anticoagulants. Tariff exposure runs through veterinary health policy disruptions affecting porcine herd availability and input cost volatility. Distribution runs through hospital pharmacy and therapeutics committees controlling formulary access, with regional procurement alliances in Baden-Württemberg and Bavaria consolidating purchasing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory intensification, with FDA and EMA pharmacovigilance mandates for extended post-authorization safety studies elevating trial costs and extending development timelines for novel entrants.
For Market Incumbents: Anticipate generic substitution pressure in oral anticoagulant segments by securing backward integration into porcine mucosa sourcing and expanding manufacturing scale for low molecular weight heparin in European channels. Defend hospital formulary position through outcome-based contracts with bleeding complication guarantees that displace multi-source generic bidding in integrated delivery networks. For New Entrants and Emerging Players: Ambulatory surgical centers represent the most penetrable channel as same-day procedure volumes displace inpatient stays and redirect demand toward take-home oral regimens. Target oncology prophylaxis white space in German and Japanese outpatient infusion centers where chemotherapy-associated thrombosis prevention remains inconsistently applied. Pursue go-to-market positioning through real-world evidence platforms automating adverse event detection to compress signal validation timelines. For Investors and Strategic Acquirers: Mid-cap pharmaceutical manufacturers with established injectable anticoagulant manufacturing scale are the most active acquirer in this space, seeking geographic expansion and formulary access. Long-term viability over the projection horizon rests on regulatory compliance infrastructure and pharmacovigilance technology convergence capabilities. Monitor PMDA ethnic bridging data requirement enforcement as inflection indicator for Japanese market entry cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA pharmacovigilance mandates compress trial timelines for European recruitment front-loading. |
| Backward Integration | Porcine mucosa sourcing control insulates against Chinese veterinary health policy disruptions. |
| Hospital System Partnership | Single-source contracts with bleeding outcome guarantees displace multi-source generic bidding. |
| Real-World Evidence Platform | FDA and EMA post-authorization study requirements automate adverse event detection validation. |
| Geographic Expansion | PMDA ethnic bridging data investments accelerate Japanese launch timelines for oral anticoagulants. |
Research Methodology
Direct dialogue with hospital formulary directors, clinical pharmacologists, regulatory affairs leads at pharmaceutical manufacturers, and procurement managers at integrated delivery networks grounded qualitative insight development. Secondary validation drew from FDA ANDA filings, EMA pharmacovigilance guidelines, ClinicalTrials.gov enrollment data, and hospital procurement database records. Bottom-up and top-down triangulation reconciled volume estimates across product type, indication, and end-user segmentation dimensions.
Bottom-up modeling anchored forecast construction, with top-down macroeconomic and demographic cross-checks applied across the analysis window. Segmentation dimensions included product chemistry class, administration route, therapeutic indication, end-user setting, and regional regulatory cluster. CAGRs derived from procedure volume growth rates, aging demographic expansion, and prophylaxis protocol penetration curves. Forecast inputs incorporated orthopedic surgery volume projections, atrial fibrillation prevalence estimates, and ambulatory surgical center expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA ethnic bridging requirement evolution, porcine mucosa supply disruptions, and pharmacovigilance mandate enforcement intensity across EMA member states. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Medication Adherence Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Cough Remedies Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Influenza Medication Market
Pharmacology
Aspirin API Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market