
 Immunotherapy Drugs Market | 2026-2036
Immunotherapy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Immunotherapy Drugs Market Intelligence
The established purchasing model centered on large academic institutes is unwinding as specialized oncology clinics increase their procurement of targeted immunotherapies. This shift favors companies with strong commercial-stage portfolios. Bristol-Myers Squibb sustains its leadership in checkpoint inhibitors for multiple cancer types. Meanwhile, Gilead Sciences, through its subsidiary Kite Pharma, specializes in cell therapies like CAR-T. Merck & Co. leverages its extensive clinical trial data to expand indications for its flagship products.
Immunotherapy drugs are biologic agents designed to stimulate or suppress the body's immune system to fight diseases, primarily cancer. These therapies function by targeting specific molecular pathways, such as the PD-1/PD-L1 axis, to enhance T-cell activity against malignant cells. Monoclonal antibodies represent the most mature product type, commanding a significant share of revenue. Within therapy areas, oncology applications dominate the development pipeline and commercial landscape, while research into autoimmune disorders is a growing secondary focus.
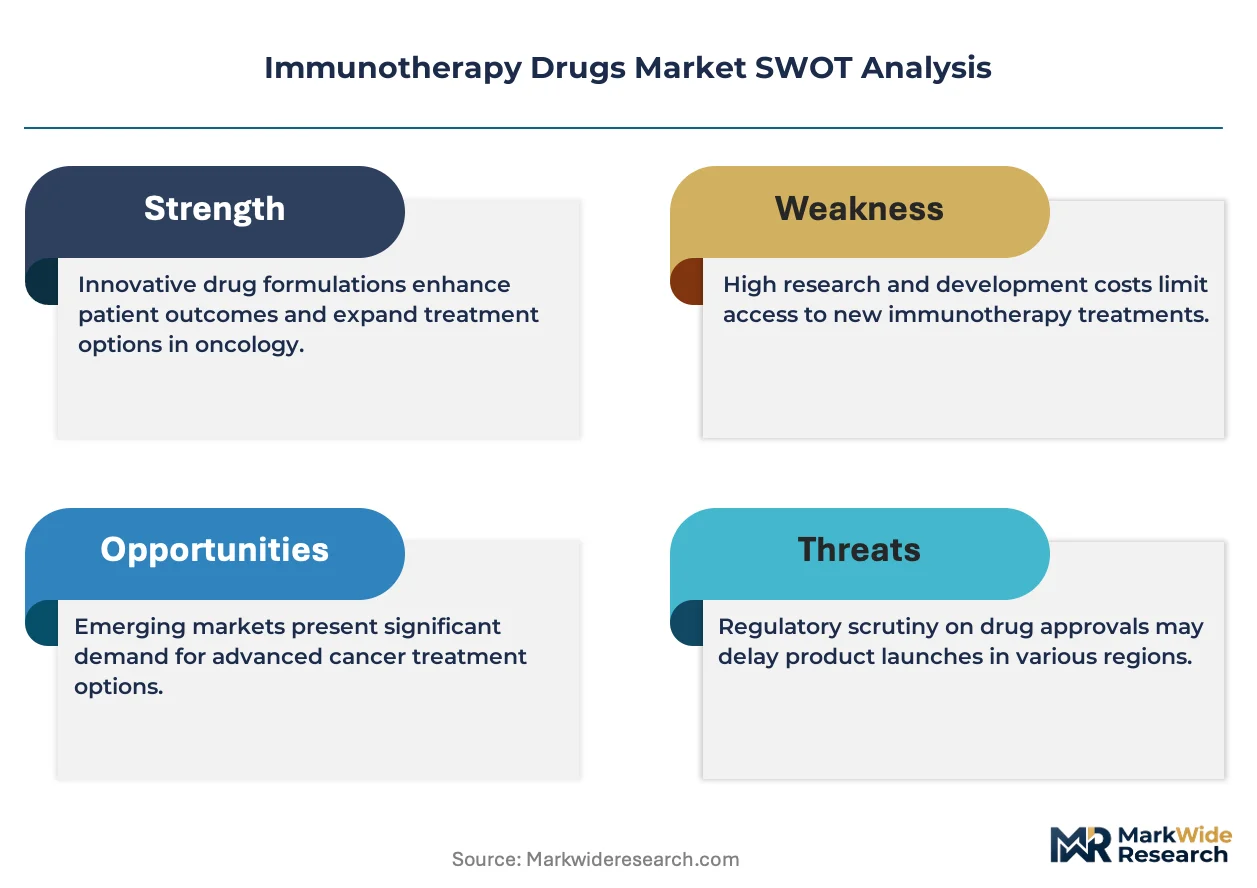
Market access is governed by stringent regulatory frameworks, including those from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These bodies set high standards for clinical trial data and manufacturing quality, with agencies like China's NMPA increasingly aligning with international guidelines. Successfully navigating the distinct reimbursement policies and pricing negotiations within each major national healthcare system remains a critical determinant of commercial success.
Market Dynamics
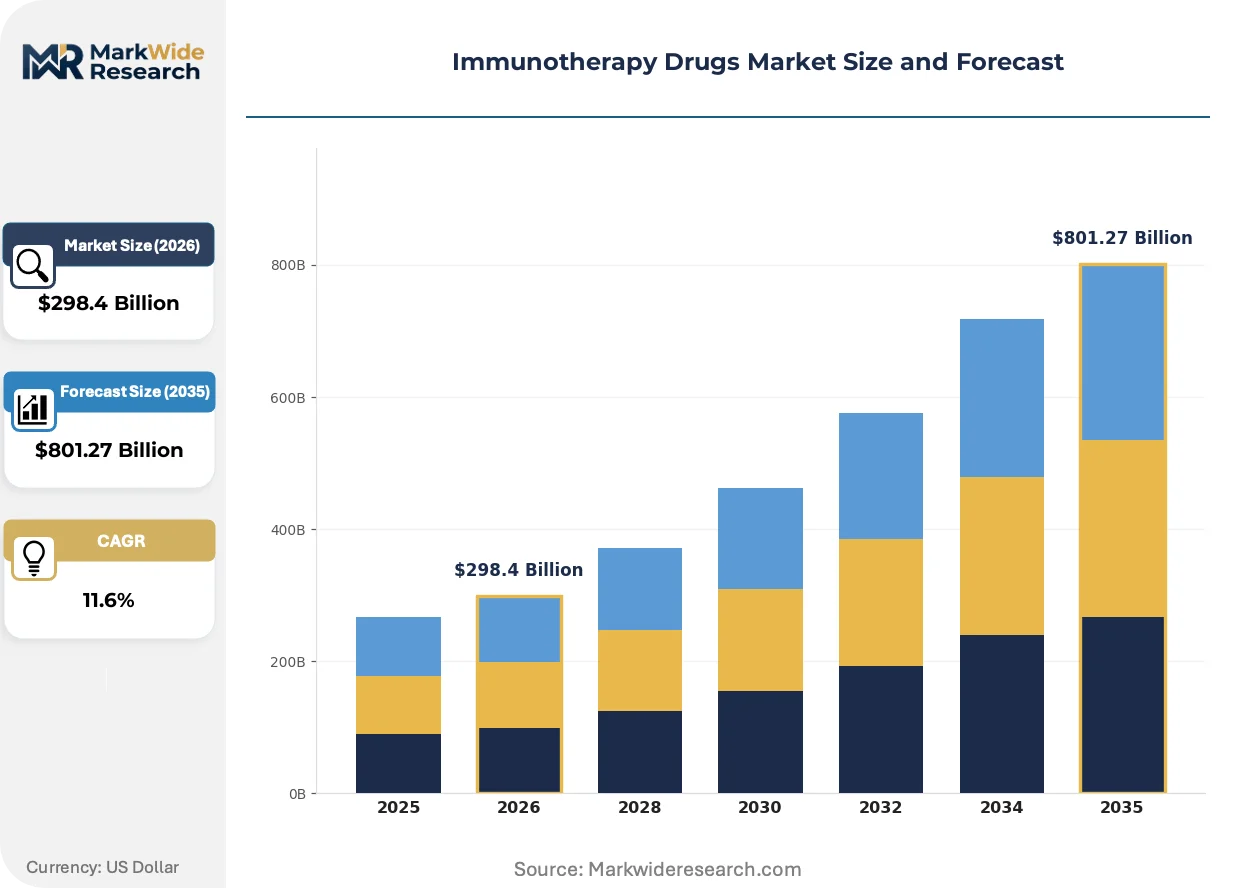
The central dynamic is the transition from broad-spectrum treatments to biomarker-guided therapies. This pivot, driven by advances in genomic sequencing and a deeper understanding of tumor immunology, prioritizes patient-specific molecular profiles over simple disease location in treatment decisions.
Growth Catalysts
- Accelerated Approval Pathways:Regulatory bodies like the US FDA and EMA offer expedited review processes for therapies addressing significant unmet medical needs, particularly in oncology, which shortens the time from clinical trial to market availability.
- Genomic Data Integration:The increasing use of next-generation sequencing in clinical research helps identify novel targets and predictive biomarkers, enabling the development of more precise and effective immunotherapies for specific patient subpopulations.
- Oncology Pipeline Expansion:Substantial R&D investment from both established biopharma and venture-backed startups is fueling a robust pipeline of novel immunotherapy candidates, especially for treating solid tumors and hematologic malignancies.
Market Restraints
- High Treatment Costs:The six-figure price tags for many immunotherapies, particularly cell therapies, create significant reimbursement challenges for national healthcare systems and private payers, limiting patient access despite clinical benefits.
- Manufacturing Complexity:Autologous cell therapies like CAR-T involve highly complex, patient-specific manufacturing logistics that are difficult to scale, leading to supply constraints and high production costs under stringent GMP standards.
- Immune-Related Adverse Events:The potential for severe, sometimes life-threatening, side effects from an overactivated immune system requires specialized clinical management, restricting the administration of these drugs to well-equipped medical centers.
Strategic Opportunities
- Autoimmune Disease Applications:Expanding immunotherapy research beyond cancer into chronic autoimmune disorders, such as Crohn's disease or lupus, represents a substantial opportunity to address a different set of unmet medical needs.
- Novel Combination Therapies:Exploring synergies between different classes of immunotherapies or combining them with targeted therapies and traditional chemotherapy offers a path to overcome treatment resistance and improve patient outcomes.
- Emerging Market Expansion:As regulatory frameworks in countries like Brazil and India align more closely with international standards, there is a significant opportunity for market entry, provided pricing strategies are adapted to local economic conditions.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of skilled professionals, including immunologists, bioinformaticians, and technicians trained in cell therapy manufacturing, creates a bottleneck for both research and commercial production.
- Complex Clinical Trial Design:Recruiting patients with specific genetic biomarkers for targeted therapy trials is logistically difficult and expensive, often leading to prolonged development timelines and increased R&D costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunotherapy Drugs Market |
| Market Size in 2026 | $298.4 Billion |
| Market Size in 2035 | $801.27 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Cancer Vaccines, Immune Checkpoint Inhibitors, Cytokines, Oncolytic Virus Therapies Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Allergies, Transplantation Medicine End User: Specialty Clinics, Research Laboratories, Diagnostic Centers, Home Healthcare Providers, Academic Institutes Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular, Topical |
| Companies Covered | Johnson & Johnson, Novartis, Merck & Co., Bristol-Myers Squibb, Pfizer, Gilead Sciences, AstraZeneca, Kite Pharma, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunotherapy Drugs Market Strategic Shifts & Innovations
Personalization is reshaping the therapeutic landscape, moving the industry away from monolithic treatment protocols. The focus now centers on developing therapies tailored to the unique immunological and genetic characteristics of an individual patient's disease, particularly within oncology.
Liquid biopsy technology provides a non-invasive method for detecting circulating tumor DNA and other biomarkers from a blood sample. Oncology clinics are increasingly adopting this tool for patient stratification and treatment monitoring. This capability is fragmenting broad cancer categories like "lung cancer" into numerous distinct, biomarker-defined sub-segments, each requiring a targeted therapeutic approach.
Regulatory frameworks are adapting to the pace of innovation. The US FDA's accelerated approval program, for instance, allows for earlier market access for drugs that treat serious conditions and fill an unmet medical need based on a surrogate endpoint. This policy predominantly affects the oncology segment, compelling developers to commit to extensive post-approval studies to confirm clinical benefit.
A notable shift in purchasing behavior is decentralizing the point of care. The traditional model, dominated by large academic medical centers, is being complemented by specialized community oncology clinics that are now procuring advanced immunotherapies directly. This trend is most pronounced in the United States, altering sales strategies and logistical support models for drug manufacturers.
Immunotherapy Drugs Market Segmentation
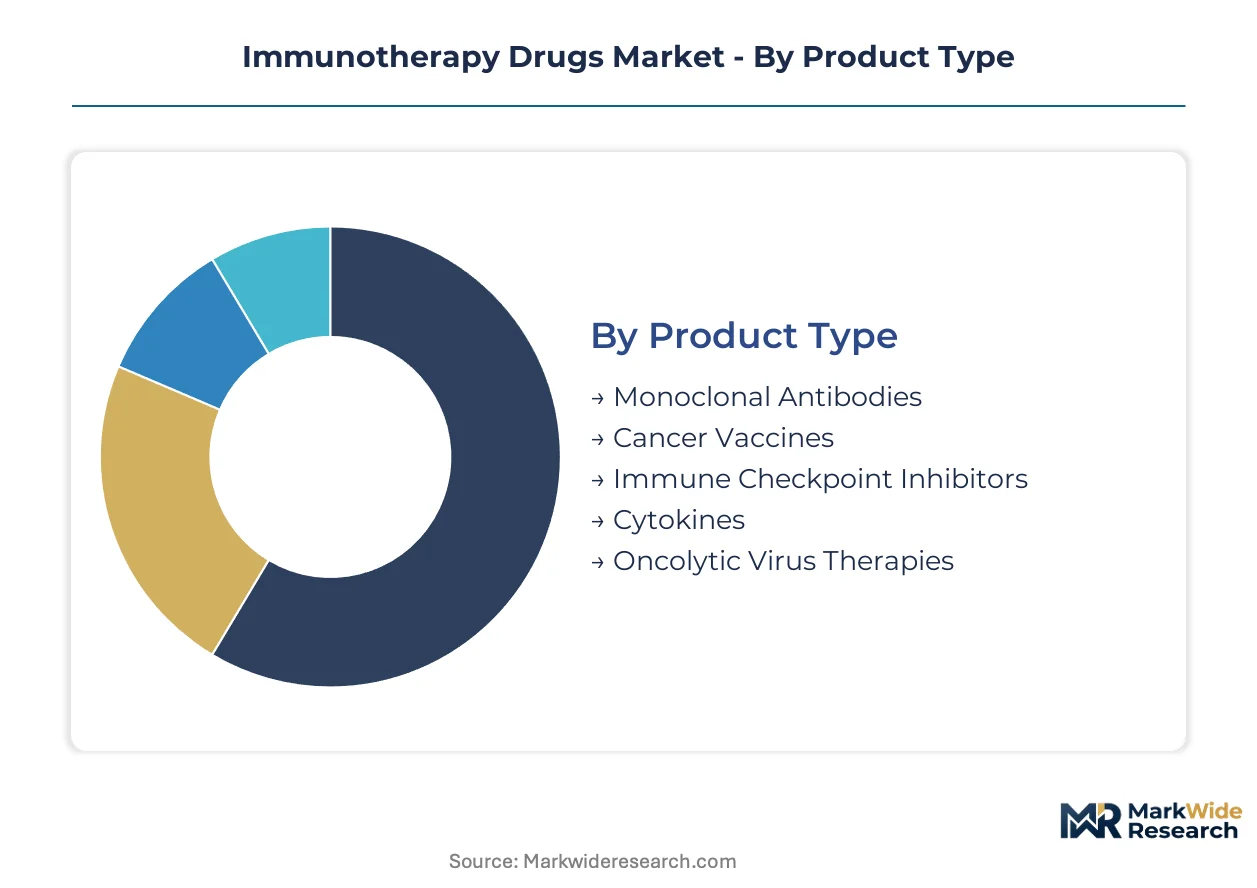
The Immunotherapy Drugs Market segments reveal distinct dynamics shaping therapeutic development and commercialization. Understanding these categories is critical for stakeholders to identify areas of concentrated demand and emerging opportunities. Each segment reflects unique patient needs, regulatory pathways, and technological advancements within the broader immunotherapy landscape.
Product Type:
Regulatory differentiation significantly influences the market entry and commercial viability of various immunotherapy product types.
- Monoclonal Antibodies:These biologic agents target specific antigens on cancer cells or immune cells, neutralizing disease pathways or enhancing immune responses. Demand concentrates in oncology for established targets like PD-1/PD-L1, driven by extensive clinical evidence and broad regulatory approvals from the US FDA and EMA.
- Immune Checkpoint Inhibitors:This class of monoclonal antibodies blocks immune checkpoints like PD-1 or CTLA-4, unleashing the body's T-cells to attack cancer. Patient access is high in the United States and Germany, supported by accelerated approval pathways and robust reimbursement for multiple solid tumor indications.
- Cancer Vaccines:These products stimulate the immune system to recognize and destroy cancer cells, either preventatively or therapeutically.
- Cytokines:These signaling proteins modulate immune responses, often used to enhance the activity of other immunotherapies or conventional treatments.
- Oncolytic Virus Therapies:Genetically modified viruses selectively infect and lyse cancer cells while also stimulating an anti-tumor immune response.
Monoclonal Antibodies handle the majority of throughput; Immune Checkpoint Inhibitors are the fastest mover on share.
Therapy Area:
Application-specific research and development investments dictate the commercial success and market size within different therapy areas.
- Oncology:Immunotherapies in oncology aim to harness the immune system to fight cancer, representing the largest and most dynamic segment. High R&D investment from companies like Merck & Co. and Bristol-Myers Squibb drives continuous expansion into new indications and patient populations.
- Autoimmune Disorders:This area involves suppressing an overactive immune system to treat conditions like Crohn's disease or rheumatoid arthritis. Research into novel targets for these chronic diseases offers a substantial opportunity beyond cancer, with growing interest from biopharmaceutical firms.
- Infectious Diseases:Immunotherapies for infectious diseases aim to boost the body's natural defenses against pathogens, including chronic viral infections.
- Allergies:These therapies involve modulating immune responses to reduce hypersensitivity reactions to allergens, often through desensitization approaches.
- Transplantation Medicine:Immunosuppressive immunotherapies are vital in preventing organ rejection in transplant recipients, ensuring long-term graft survival.
Oncology dominates the market landscape; Autoimmune Disorders show the steepest expansion trajectory.
End User:
Customer type preferences and operational capabilities significantly influence procurement patterns and distribution strategies for immunotherapy drugs.
- Specialty Clinics:These facilities, particularly community oncology clinics, are increasingly procuring advanced immunotherapies directly for patient administration. The shift in purchasing behavior in the United States requires drug manufacturers to adapt their sales and logistical models.
- Academic Institutes:Large academic medical centers remain crucial hubs for clinical trials, advanced research, and the initial adoption of complex immunotherapies like CAR-T cell therapies. These institutes often lead early-stage development and specialized patient care.
- Research Laboratories:These entities focus on discovery and preclinical development of novel immunotherapy candidates and biomarkers.
- Diagnostic Centers:These centers provide critical support by identifying patient biomarkers and monitoring treatment efficacy for targeted immunotherapies.
- Home Healthcare Providers:While limited for complex immunotherapies, this segment may grow for simpler, self-administered formulations as the market matures.
Specialty Clinics represent the primary point of care for many patients; Academic Institutes retain leadership in research and early adoption.
Delivery Mode:
Volume of administration and patient convenience are key factors determining the prevalence and development of different delivery modes.
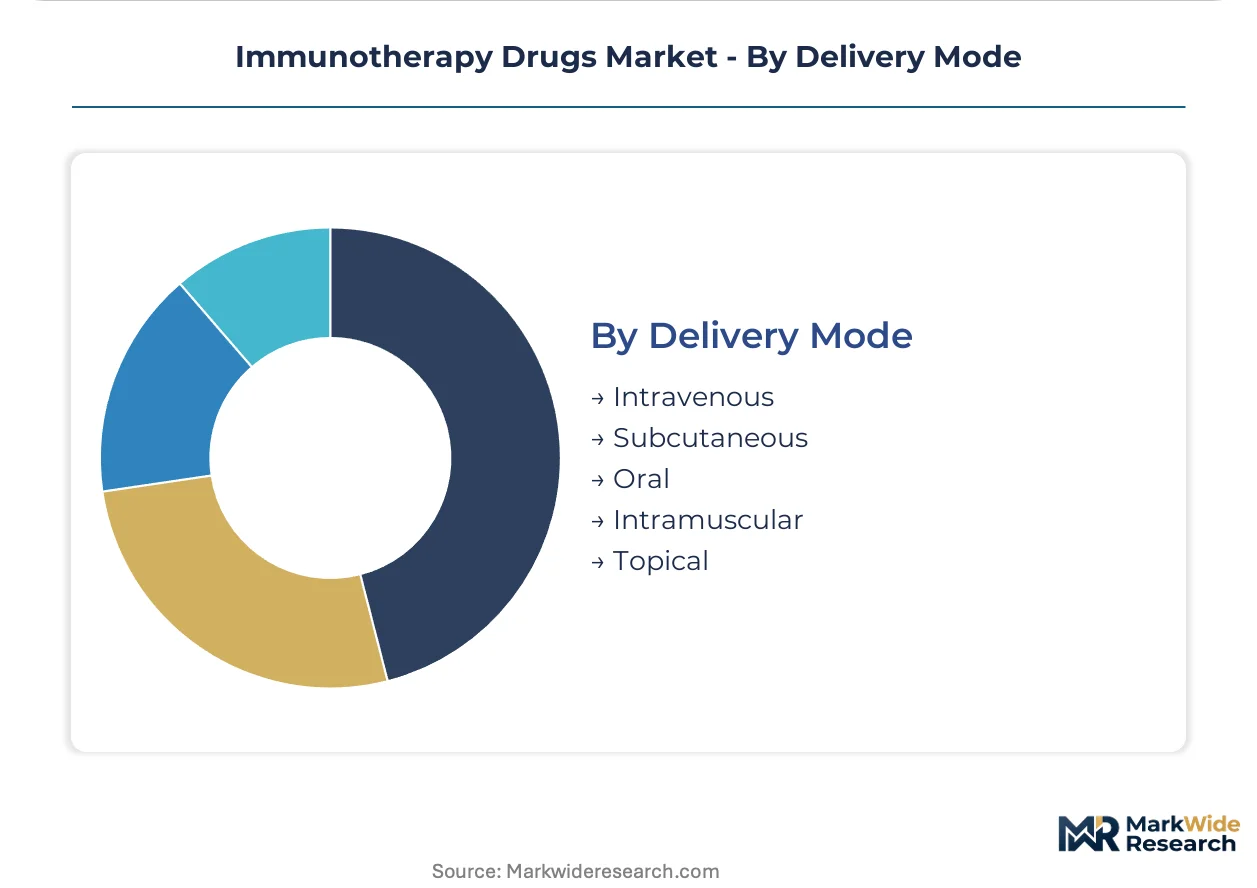
- Intravenous:This mode involves administering immunotherapy drugs directly into a vein, ensuring rapid and complete systemic exposure. Many monoclonal antibodies and cell therapies are delivered intravenously, requiring administration in clinical settings under medical supervision.
- Subcutaneous:Subcutaneous injections involve administering drugs under the skin, offering greater patient convenience and potential for home administration for certain therapies. This mode is gaining traction for established biologics to improve patient quality of life and reduce healthcare resource utilization.
- Oral:Oral formulations offer the highest patient convenience but are challenging for biologics due to degradation in the digestive system.
- Intramuscular:This delivery method involves injecting drugs into muscle tissue, often used for vaccines and some long-acting formulations.
- Topical:Topical delivery is primarily for localized immune modulation, such as for certain skin cancers or inflammatory skin conditions.
Intravenous administration accounts for the largest share of immunotherapy drug delivery; Subcutaneous delivery is rapidly expanding due to patient preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Immunotherapy drugs production, R&D, and commercialization are concentrated in specific geographic regions. These areas benefit from robust research infrastructure, significant investment in biotechnology, and supportive regulatory environments. Demand for advanced cancer treatments drives innovation in these key markets.
United States
High R&D investment and comprehensive patient access programs drive significant demand for immunotherapies in the United States. The US FDA's accelerated approval pathways shorten time to market for novel oncology treatments. Major biotech clusters in Boston and the San Francisco Bay Area lead in discovery and clinical development.
Germany
Germany possesses a strong pharmaceutical industry and a robust healthcare system, fostering significant oncology research and adoption of advanced immunotherapies. European Medicines Agency (EMA) guidelines ensure high standards for clinical data and product quality. Biotech hubs in Frankfurt and Munich are centers for immunotherapy innovation.
Japan
Japan's aging population and advanced medical technology contribute to a high demand for innovative therapies, including immunotherapies. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent regulatory processes for new drug approvals. Research centers in Tokyo and Osaka are actively engaged in developing novel cancer treatments.
China
China's increasing healthcare expenditure and growing cancer burden are fueling rapid expansion in the immunotherapy market. The National Medical Products Administration (NMPA) is increasingly aligning with international regulatory standards for drug evaluation. Innovation zones in Shanghai and Beijing are attracting substantial investment in biotech R&D.
India
India is expanding its pharmaceutical manufacturing capabilities and experiencing a rising prevalence of chronic diseases, including cancer, driving interest in immunotherapy. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals and manufacturing quality within the country. Hyderabad and Bengaluru feature prominent pharmaceutical clusters focusing on biopharmaceutical development.
Immunotherapy Drugs Market Key Industry Players
Concentration sits with large, diversified biopharmaceutical companies possessing extensive R&D capabilities and commercial-stage portfolios. The market structure exhibits a tiered consolidation, with established players dominating the immune checkpoint inhibitor space. Strategic archetypes include global pharmaceutical giants, specialized biotech firms, and emerging cell therapy innovators. Companies are pursuing strategic partnerships and portfolio diversification to enhance their market presence.
Among the established global pharmaceutical firms, Bristol-Myers Squibb and Merck & Co. represent leaders in traditional immunotherapy development, particularly within monoclonal antibodies and checkpoint inhibitors. Bristol-Myers Squibb sustains leadership across multiple cancer types. Merck & Co. leverages extensive clinical trial data to expand indications for its flagship products. Gilead Sciences, through its subsidiary Kite Pharma, exemplifies specialized biotech firms focusing on advanced cell therapies like CAR-T. These companies anchor significant portions of the market by leveraging extensive clinical data and broad regulatory approvals across key global markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Novartis |
| Merck & Co. |
| Bristol-Myers Squibb |
| Pfizer |
| Gilead Sciences |
| AstraZeneca |
| Kite Pharma |
| AbbVie |
| Others |
Cost & Logistics Intelligence
Long-term supply contracts for critical biologic components lock in both supply access and price visibility for immunotherapy drug manufacturers. This model mitigates volatility in complex manufacturing processes and ensures consistent product availability for patient treatment.
Pricing Analysis
US FDA and EMA guidelines dictate the pricing tier structure for novel immunotherapy drugs. Value-based pricing models dominate, reflecting the significant clinical benefits and high R&D investments. Price differentiation occurs based on clinical efficacy for specific indications and manufacturing complexity, particularly for cell therapies. Pricing softness stems from national healthcare systems' reimbursement challenges and payer negotiations. National healthcare systems and private payers represent the most price-sensitive buyers, while academic institutes often prioritize early access to innovative treatments.
Supply Chain Analysis
Just-in-time manufacturing and delivery protocols are essential for patient-specific autologous cell therapies to manage their short shelf-life and complex logistics. Supply concentrates in the United States and Germany, driven by robust R&D infrastructure and advanced biopharmaceutical manufacturing capabilities. The supply chain draws from specialized reagents, viral vectors, and advanced bioreactor technologies. Manufacturing complexity, especially for CAR-T cell therapies, presents a significant structural risk. Distribution channels run directly through specialized clinics and academic institutes, requiring stringent cold chain management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Immunotherapy Drugs Market is experiencing a buyer-power shift, driven by the fragmentation of procurement points with the rise of specialized oncology clinics.
For Market Incumbents:
Shield market share by expanding indications for established checkpoint inhibitors, leveraging extensive clinical data. Invest in advanced cell therapy manufacturing capabilities to address supply constraints and high production costs. Deepen R&D into novel combination therapies, targeting resistance mechanisms to maintain clinical relevance against emerging biotech firms. Expand into autoimmune disease applications to diversify revenue streams.
For New Entrants and Emerging Players:
Accelerated approval pathways present a certification fast-track for therapies addressing unmet medical needs in oncology. Target niche, biomarker-defined solid tumor sub-segments with novel mechanisms of action. Focus initial go-to-market strategies on academic centers and specialized clinics for early adoption. Develop therapies for rare diseases with orphan drug designations to gain market traction. Explore novel delivery modes to improve patient convenience.
For Investors and Strategic Acquirers:
Capital is best deployed toward specialized biotech firms with validated early-stage assets in cell therapy or novel immunotherapy platforms. Focus on companies possessing proprietary manufacturing technologies or strong intellectual property in combination approaches for a 5-10 year horizon. The signal to watch for long-term viability is successful Phase 2/3 clinical trial readouts for novel targets, particularly in solid tumors. Prioritize firms with robust market access strategies for complex biologics.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expands indications for existing drugs, reaching broader patient populations and securing market longevity. |
| Manufacturing Scale-Up | Addresses supply constraints for complex cell therapies, enhancing patient access and reducing costs. |
| Pipeline Diversification | Mitigates reliance on single product types, exploring new targets in oncology and autoimmune disorders. |
| Regulatory Approval Pathway | Leverages accelerated programs to expedite market entry for novel, high-impact therapies. |
| Strategic Partnership | Accesses complementary technologies or expands geographic reach, strengthening competitive positioning. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through extensive desk research. This approach combined qualitative insights from drug development executives, hospital formulary managers, and regulatory affairs leads with quantitative data. Secondary sources included US FDA filings, EMA submissions, ClinicalTrials.gov, and company financial reports. Bottom-up aggregation and top-down validation ensured comprehensive market sizing and forecast accuracy.
The forecast horizon for this study extends across the analysis window, modeling key segmentation dimensions including product type, therapy area, end user, and delivery mode. CAGRs were derived through a rigorous process of trend analysis and market growth projections at the segment level. Industry-specific forecast inputs included clinical trial success rates and evolving regulatory approval timelines. This framework provides a robust outlook for the Immunotherapy Drugs Market.
Decision-makers should treat outputs as directional under base assumptions regarding R&D success and regulatory landscape stability; material deviation would warrant model refresh. Forecasts reflect assumptions concerning healthcare expenditure and biomarker discovery trends. Revision becomes warranted when major clinical trial failures or significant policy shifts cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Cough Remedies Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Ketoprofen API Market
Pharmacology
Propranolol Drug Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Aspirin API Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
ACE Inhibitors Market