
 Clot Busting Drugs Market | 2026-2036
Clot Busting Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Clot Busting Drugs Market Outlook
Third-generation recombinant tissue plasminogen activator formulations is rotating the Clot Busting Drugs Market toward higher-efficacy, longer-half-life products that reduce door-to-needle time in acute settings. Boehringer Ingelheim GmbH leverages its recombinant protein manufacturing scale to dominate European thrombolytic supply. Genentech Inc. anchors North American alteplase production through integrated biologics facilities. Pfizer Inc. competes across multiple therapy areas with diversified fibrinolytic portfolios.
Clot busting drugs comprise serine protease biologics that catalyze plasminogen conversion to plasmin, dissolving fibrin clots through intravenous or intra-arterial administration at therapeutic doses measured in milligrams per kilogram of patient body weight. Their primary purpose is rapid revascularization during acute ischemic events where minutes determine tissue salvage outcomes. The therapy area dimension shows ischemic stroke commanding the largest revenue pool while pulmonary embolism segments expand fastest as catheter-directed protocols proliferate. The delivery mode dimension reveals intravenous administration maintaining volume leadership though intra-arterial methods capture premium pricing in comprehensive stroke centers.
FDA, EMA, and WHO prequalification standards govern clot busting drug approval, with FDA breakthrough therapy designations compressing development timelines and EMA orphan drug incentives stimulating innovation in rare thrombotic indications. These regulatory frameworks shape market access by mandating Phase III mortality endpoint trials that raise capital barriers for new entrants. Stakeholders must monitor biosimilar erosion timelines for legacy alteplase molecules and position tenecteplase portfolios before patent cliffs accelerate.
Market Dynamics
The transition from alteplase to tenecteplase as the standard-of-care thrombolytic is compressing manufacturing margins while demanding new cold-chain logistics investments across hospital networks.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval timelines for novel thrombolytic formulations reduce time-to-market for biologics targeting extended therapeutic windows in stroke protocols.
- Comprehensive Stroke Center Certification:US hospital accreditation programs mandate 24/7 thrombolytic administration capability, institutionalizing demand for rapid-infusion clot busting drugs.
- Catheter-Directed Thrombolysis:Interventional radiology expansion into pulmonary embolism treatment creates procedural volume growth beyond traditional intravenous stroke applications.
Market Restraints
- Recombinant Protein Production Concentration:Mammalian cell culture capacity for plasminogen activators clusters in contract manufacturing organizations across Switzerland and Germany, creating single-source vulnerability.
- EMA Orphan Drug Incentive Complexity:Rare thrombotic indication pathways require mortality endpoint trials that extend development cycles and elevate capital requirements for specialty indications.
- Neuroprotection Adjunct Threat:Endovascular thrombectomy device adoption in anterior circulation large vessel occlusion cases reduces addressable patient pool for standalone pharmacological intervention.
Strategic Opportunities
- Prehospital Thrombolysis:Mobile stroke unit deployment in Germany and Japan enables ambulance-based tenecteplase administration before hospital arrival, compressing door-to-needle intervals.
- WHO Prequalification Pathway:Emerging market access expansion for generic thrombolytics in India and Brazil through international procurement mechanisms.
- AI-Enabled Triage Integration:Machine learning algorithms for automated large vessel occlusion detection in CT angiography are converging with thrombolytic decision support systems.
Industry Challenges
- Cold-Chain Distribution Integrity:Temperature excursion risks during last-mile delivery to rural emergency departments compromise drug stability and efficacy.
- Biologics Manufacturing Skill Scarcity:Recombinant protein purification expertise concentrates in legacy facilities, constraining workforce expansion for tenecteplase production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clot Busting Drugs Market |
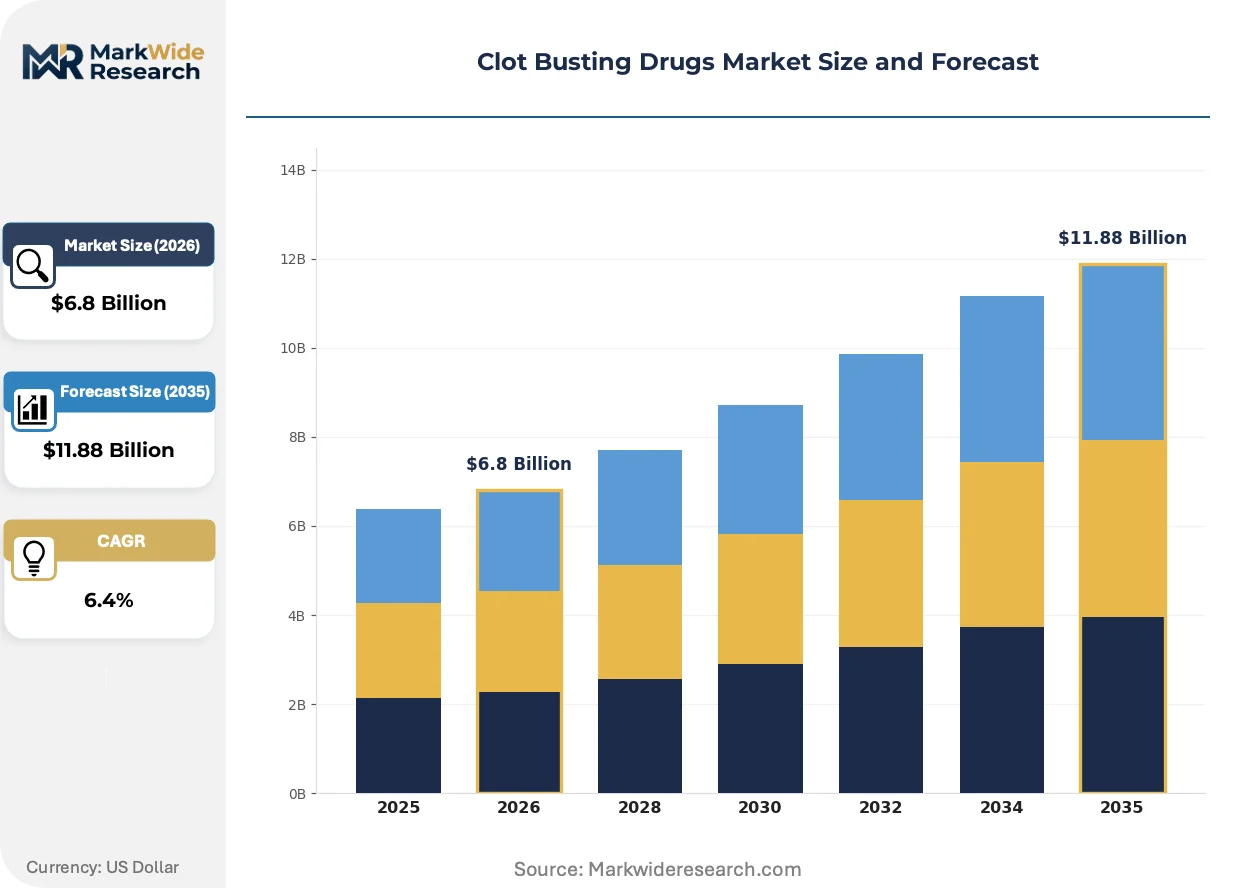
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alteplase, Tenecteplase, Reteplase, Urokinase Therapy Area: Ischemic Stroke, Myocardial Infarction, Pulmonary Embolism, Deep Vein Thrombosis Delivery Mode: Intravenous, Intra-arterial, Subcutaneous, Oral End User: Hospitals, Clinics, Ambulance Services, Homecare |
| Companies Covered | Boehringer Ingelheim GmbH, Genentech Inc., Pfizer Inc., Sanofi, Bayer AG, Dr. Reddy’s Laboratories, Roche Holding AG, Johnson & Johnson Services Inc., Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clot Busting Drugs Market Strategic Shifts
Digital health infrastructure and next-generation biologics manufacturing are reconfiguring how clot busting drugs reach patients and how their efficacy is measured in real time.
Tenecteplase's single-bolus administration protocol is fragmenting the traditional alteplase-infusion infrastructure that dominated emergency department workflows for three decades. Comprehensive stroke centers in the United States and Japan are adopting the simplified dosing regimen to reduce pharmacy preparation time and nursing monitoring burden. This shift is fragmenting vendor relationships as hospitals decouple from legacy infusion pump ecosystems and renegotiate supply contracts around bolus-compatible delivery systems.
EMA's Medical Device Regulation (MDR) reclassification of drug-device combination products is imposing new conformity assessment requirements on thrombolytic delivery systems. Manufacturers must now submit technical documentation for integrated infusion sets and safety syringes alongside pharmaceutical dossiers. European cath lab networks are responding by consolidating procurement around MDR-certified suppliers, compressing the vendor base for clot busting drug administration hardware.
Hospital pharmacy committees are consolidating thrombolytic purchasing decisions at the health system level rather than allowing individual facility autonomy. This behavioral shift concentrates negotiating leverage with integrated delivery networks in the United States and hospital chains in Germany. The concentration is most visible in multi-state US systems where standardized formularies now mandate tenecteplase over alteplase across all affiliated emergency departments.
Clot Busting Drugs Market Segmentation
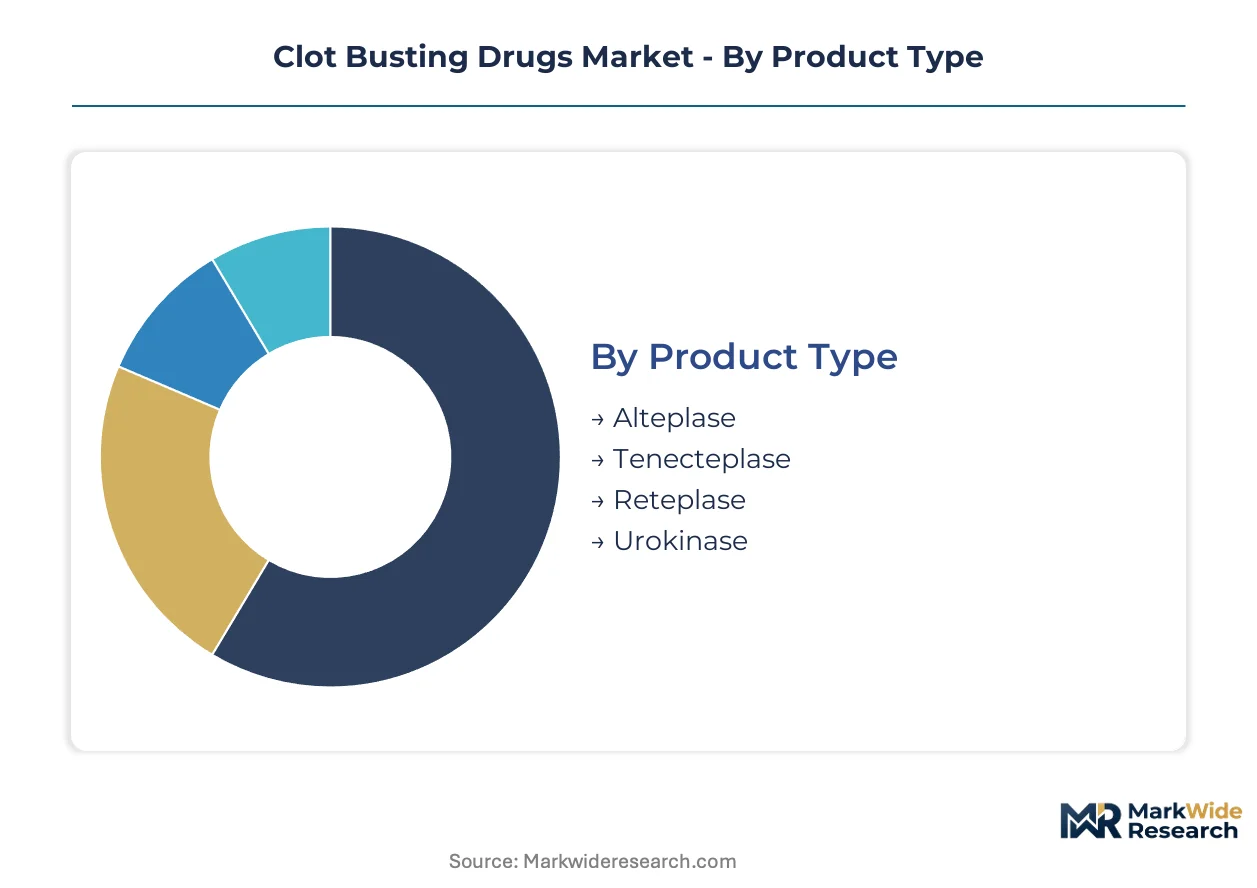
Segmentation in the clot busting drugs market reveals how clinical protocols, regulatory pathways, and delivery infrastructure fragment demand across product generations and care settings. Manufacturers must align formulation development with specific thrombotic indications and administration environments to secure formulary placement.
Product Type:
Geographic concentration of manufacturing capacity and patent status create divergent domestic versus export-led demand patterns across recombinant thrombolytic generations.
- Tenecteplase:Third-generation recombinant tissue plasminogen activator engineered with longer half-life and single-bolus dosing profile. Demand concentrates in Germany and Japan where mobile stroke units and comprehensive stroke centers prioritize door-to-needle time reduction; FDA accelerated approval pathways are compressing US adoption timelines.
- Alteplase:First-generation recombinant tissue plasminogen activator requiring continuous intravenous infusion over 60-90 minutes. Established reimbursement codes in the United States sustain volume leadership despite tenecteplase displacement; biosimilar erosion in European markets is fragmenting pricing power.
- Reteplase:Second-generation variant with intermediate half-life used primarily in myocardial infarction protocols.
- Urokinase:Non-recombinant plasminogen activator derived from human kidney cells with established WHO prequalification for emerging market procurement.
Tenecteplase commands the established base. The steepest expansion runs through alteplase biosimilar conversions in price-sensitive European markets.
Therapy Area:
Clinical trial endpoint requirements and mortality risk stratification create tiered development cost structures across thrombotic indications.
- Ischemic Stroke:Acute cerebrovascular occlusion requiring thrombolytic administration within 4.5 hours of symptom onset. Volume leadership concentrates in the United States where comprehensive stroke center certification mandates 24/7 thrombolytic capability; EMA orphan drug incentives are stimulating pediatric stroke indication development.
- Pulmonary Embolism:Pulmonary artery obstruction with hemodynamic compromise or right heart strain. Catheter-directed thrombolysis protocols in German and Japanese interventional radiology departments are expanding procedural volumes beyond traditional intravenous administration.
- Myocardial Infarction:Coronary artery occlusion managed through primary percutaneous coronary intervention with adjunctive thrombolytic reserve.
- Deep Vein Thrombosis:Lower extremity venous thrombosis typically managed with anticoagulation rather than thrombolysis except in phlegmasia cases.
Ischemic stroke commands the established base. The steepest expansion runs through pulmonary embolism as catheter-directed protocols proliferate.
Delivery Mode:
Administration route selection hinges on thrombus location, bleeding risk assessment, and institutional capability for interventional procedures.
- Intravenous:Systemic administration through peripheral or central venous access enabling rapid deployment in emergency department settings. Volume concentration in US hospital networks where nursing protocols and infusion pump infrastructure favor established workflows; tenecteplase single-bolus compatibility is reducing pharmacy preparation burden.
- Intra-arterial:Catheter-directed delivery to thrombus site enabling localized drug concentration with reduced systemic exposure. Premium pricing in Japanese and German comprehensive stroke centers with 24/7 interventional neuroradiology coverage; EMA Medical Device Regulation reclassification is imposing new conformity requirements on delivery systems.
- Subcutaneous:Limited application for low-dose prophylactic regimens rather than acute thrombolysis.
- Oral:Not commercially viable for acute thrombolytic therapy due to gastrointestinal degradation and absorption variability.
Intravenous administration commands the established base. The steepest expansion runs through intra-arterial methods as interventional radiology networks mature.
End User:
Care setting determines time-to-treatment constraints, cold-chain logistics requirements, and reimbursement pathway complexity.
- Hospitals:Emergency department and inpatient settings with pharmacy infrastructure for biologic storage and preparation. Revenue concentration in US integrated delivery networks and German hospital chains where formulary standardization across multi-facility systems is consolidating purchasing decisions; Joint Commission stroke certification mandates sustain institutional demand.
- Ambulance Services:Prehospital administration through mobile stroke units and advanced life support vehicles. Fastest volume growth in Germany and Japan where physician-staffed ambulance protocols enable tenecteplase delivery before hospital arrival; cold-chain integrity during transport remains the operational constraint.
- Clinics:Outpatient settings with limited application for acute thrombolytic administration.
- Homecare:Minimal penetration due to bleeding risk monitoring requirements and emergency backup necessity.
Hospitals command the established base. The steepest expansion runs through ambulance services as prehospital thrombolysis protocols deploy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of recombinant thrombolytics concentrate in Swiss and German manufacturing hubs, while import dependence shapes procurement strategies in Japan and emerging Asian markets. Trade balances reflect patent-protected originator dominance versus biosimilar penetration in price-sensitive European markets.
United States
Comprehensive stroke center certification mandates 24/7 thrombolytic capability across Joint Commission-accredited hospitals. FDA breakthrough therapy designations compress development timelines for novel formulations. The Cleveland Clinic and Mayo Clinic networks anchor demand concentration in the Midwest, where integrated delivery systems standardize tenecteplase formularies.
Germany
Mobile stroke unit deployment enables prehospital tenecteplase administration before hospital arrival. EMA orphan drug incentives stimulate pediatric stroke indication development. The Ruhr-Rhine corridor concentrates interventional radiology capacity, with catheter-directed thrombolysis protocols expanding beyond traditional intravenous applications.
Japan
Aging demographics sustain high procedural volumes in acute cerebrovascular care. PMDA accelerated review pathways align with FDA timelines for thrombolytic approvals. The Kanto region around Tokyo hosts the highest density of comprehensive stroke centers with 24/7 neuroradiology coverage.
Switzerland
Contract manufacturing organizations cluster recombinant protein production capacity for European supply. Swissmedic maintains stringent batch release standards that influence EMA regulatory harmonization. Basel and Zurich anchor biologics manufacturing infrastructure serving export markets.
India
WHO prequalification pathways enable generic thrombolytic access through international procurement mechanisms. CDSCO manufacturing facility inspections govern export eligibility to regulated markets. Hyderabad and Ahmedabad concentrate active pharmaceutical ingredient production for cost-competitive urokinase supply.
Clot Busting Drugs Market Competitive Environment
Listed leaders compete with private specialists across recombinant manufacturing scale and distribution reach. Market structure consolidates around three to five originator manufacturers with established cold-chain networks, while biosimilar entrants fragment pricing power in European tenders. Strategic archetypes span integrated biopharma conglomerates, recombinant protein specialists, and emerging market generic manufacturers. Dominant competitive moves include capacity expansion in mammalian cell culture facilities and strategic partnerships for prehospital administration protocols.
Among German-based manufacturers, Boehringer Ingelheim GmbH exemplifies the recombinant protein specialist archetype with European thrombolytic supply concentration. Genentech Inc. and Roche Holding AG occupy positions across the integrated biopharma tier, with Genentech anchoring North American alteplase production through captive biologics infrastructure. Pfizer Inc. represents the diversified pharmaceutical conglomerate model competing across multiple fibrinolytic therapy areas.
| Leading Market Players |
|---|
| Boehringer Ingelheim GmbH |
| Genentech Inc. |
| Pfizer Inc. |
| Sanofi |
| Bayer AG |
| Dr. Reddy's Laboratories |
| Roche Holding AG |
| Johnson & Johnson Services Inc. |
| Lupin |
| Others |
Value Chain & Pricing Dynamics
Mammalian cell culture capacity utilization above 85 percent in Swiss and German contract manufacturing organizations creates scale-driven cost floors that propagate through tenecteplase and alteplase pricing tiers. This concentration of recombinant protein production infrastructure simultaneously limits new entrant supply access and sustains originator pricing power across European hospital procurement networks.
Pricing Analysis
Hospital pharmacy committees anchor three-tier pricing structure across premium, standard, and economy levels in the Clot Busting Drugs Market. Price differentiation separates FDA breakthrough-designated originators from EMA-certified biosimilars and WHO-prequalified generic urokinase, with volume scale and cold-chain reliability as secondary tiering factors. Cost compression in the biosimilar tier intensifies as Indian and Chinese manufacturers expand EMA-compliant capacity. Integrated delivery networks in the United States exhibit lowest price sensitivity due to Joint Commission certification mandates, while emerging market tenders show highest elasticity.
Supply Chain Analysis
Basel-Zurich biologics corridor transit underwrites European thrombolytic supply security despite single-source vulnerability in recombinant protein purification. Manufacturing concentrates in Switzerland, Germany, and the United States, with active pharmaceutical ingredient production anchored in India for cost-competitive urokinase. Raw material dependencies center on fetal bovine serum, specialized cell culture media, and single-use bioreactor systems. Tariff exposure on Chinese-sourced filtration membranes presents structural risk. Distribution runs through cold-chain logistics networks with 2-8°C integrity requirements from manufacturing site to hospital pharmacy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Clot Busting Drugs Market functions as a regulatory-entrenchment defensive moat, where FDA breakthrough therapy designation and EMA orphan drug pathways create multi-year approval barriers that protect incumbent manufacturing scale advantages against biosimilar erosion.
For Market Incumbents: Fortify mammalian cell culture capacity through backward integration into bioreactor manufacturing or captive supply agreements with Swiss contract manufacturing organizations. Secure prehospital thrombolysis partnerships with German and Japanese mobile stroke unit operators to lock in tenecteplase formulary placement before biosimilar alteplase tenders accelerate margin compression in European hospital systems. For New Entrants and Emerging Players: Lead with WHO prequalification pathway for generic urokinase in India and Brazil, where international procurement mechanisms offer penetrable access without originator patent barriers. Target catheter-directed thrombolysis device-thrombolytic combination submissions under EMA Medical Device Regulation reclassification, exploiting regulatory complexity that disadvantages pure-pharma incumbents. Pursue strategic licensing with established cold-chain distributors rather than building de novo logistics infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors recombinant protein specialists with existing mammalian cell culture assets over diversified pharma conglomerates with fragmented fibrinolytic attention. Long-term viability hinges on tenecteplase patent cliff navigation and prehospital administration protocol capture. Acquisition target archetype: mid-cap European manufacturers with EMA-certified facilities and underutilized capacity. Monitor biosimilar alteplase erosion rates in German hospital tenders as inflection indicator for originator pricing power durability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands mammalian cell culture capacity in Basel corridor to meet tenecteplase demand from comprehensive stroke centers. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for extended therapeutic window formulations. |
| Strategic Partnership | Mobile stroke unit alliances in Germany and Japan enable prehospital tenecteplase administration before hospital arrival. |
| Pipeline Diversification | Pediatric stroke indication development leverages EMA orphan drug incentives for rare thrombotic conditions. |
| Reimbursement Strategy | Joint Commission stroke certification mandates sustain institutional demand and formulary standardization across US networks. |
Study Parameters
Desk research of FDA filings, EMA assessment reports, ClinicalTrials.gov protocols, and hospital formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork across pharmaceutical manufacturing clusters in Switzerland, Germany, and the United States was validated against secondary trade data and customs records. Bottom-up patient-flow modeling and top-down revenue triangulation were cross-referenced to ensure segmentation consistency.
Variance decomposition across product type, therapy area, delivery mode, and end user dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of procedural volumes, pricing trajectories, and regulatory approval timelines. Forecast inputs incorporated comprehensive stroke center certification expansion rates, mobile stroke unit deployment schedules, and biosimilar erosion assumptions in European tender markets.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA accelerated approval pathway utilization, or unexpected endovascular thrombectomy device adoption shifts, would require recalibration. Practitioners should keep alternative scenarios live as regulatory harmonization between FDA, EMA, and PMDA evolves and as cold-chain logistics infrastructure investments mature in emerging Asian markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Hepatitis C Drug Market
Pharmacology
Propranolol Drug Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Semaglutide API Market
Pharmacology
Olanzapine API Market
Pharmacology
Hypertension Drug Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Cough Remedies Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Influenza Medication Market
Pharmacology
Antimycotics Market