
 Asia-Pacific Protective Coatings Market | 2026-2036
Asia-Pacific Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Protective Coatings Market Outlook
Asset-light leasing models for coating application equipment is fragmenting competitive access across Asia-Pacific shipyards and industrial facilities. PPG Industries sustains its position through captive supply of epoxy formulations for marine newbuild programs. Kansai Paint Co., Ltd. dominates Japanese automotive OEM lines with high-solids polyurethane clearcoats. Hempel A/S navigates port infrastructure cycles through specialized zinc-rich primers for steel pile protection.
Asia-Pacific protective coatings comprise resin-based barrier systems formulated with pigments, extenders, and additives to prevent substrate degradation from moisture, chemicals, and ultraviolet exposure. Epoxy systems achieve dry film thicknesses of 250-500 microns for immersion service in ballast tanks and offshore platforms. Marine applications lead value generation due to IMO-compliant antifouling requirements and cyclical newbuild demand at Korean and Chinese yards. Waterborne technology expands fastest as China's MEE enforces VOC limits that displace solvent-borne alkyd formulations in architectural and light industrial uses.
China's MEE administers GB standards for hazardous substance limits in coatings, while India's BIS mandates performance testing for industrial protective grades under compulsory certification schemes. Japan's METI promotes JIS-compliant low-VOC systems through building energy codes that favor durable exterior coatings. South Korea's MFDS coordinates with shipyard safety regulators to enforce workplace exposure limits during spray application. Stakeholders must weigh formulation reformulation costs against compliance timelines as each jurisdiction tightens chemical restriction lists independently.
Market Dynamics
China's MEE enforcement of GB 30981 VOC limits is forcing simultaneous reformulation across solvent-borne alkyd and epoxy product lines, compressing margin structures for mid-tier suppliers while accelerating waterborne technology deployment in architectural and light industrial segments.
Growth Catalysts
- MEE GB Standards:China's hazardous substance limits mandate low-VOC coating systems across manufacturing zones, creating replacement demand for compliant waterborne and high-solids formulations in Jiangsu and Guangdong industrial clusters.
- Shipyard Concentration:Korean and Japanese newbuild programs sustain epoxy consumption for ballast tank and hull protection, with cyclical orders from Hyundai Heavy Industries and Imabari Shipbuilding driving specialty primer volumes.
- Polyurethane Clearcoat Technology:Automotive OEM specifications for exterior durability and scratch resistance sustain solvent-borne and emerging waterborne polyurethane growth across Japanese and Chinese assembly plants.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and isocyanate precursor prices fluctuate with naphtha and propylene contract movements, compressing formulation margins for coating manufacturers without backward integration into resin production.
- Supply Concentration in Titanium Dioxide:Chinese TiO2 producers control pigment feedstock pricing for architectural whites, exposing regional formulators to export quota disruptions and anti-dumping duty uncertainty.
- Technical Limitation in Waterborne Corrosion Resistance:Waterborne epoxies fail to match solvent-borne systems for immersion service above 150 microns dry film thickness, restricting penetration in offshore platform and subsea pipeline specifications.
Strategic Opportunities
- Vietnam Industrial Expansion:Northern manufacturing zones near Hai Phong attract electronics and automotive component investment, generating greenfield demand for protective coatings in facilities without legacy solvent-borne infrastructure.
- India BIS Compulsory Certification:Industrial protective coating grades now require BIS laboratory testing and mark licensing, creating barrier-to-entry advantages for pre-certified suppliers in infrastructure and power sector tenders.
- Asset-Light Application Equipment Leasing:Mobile spray units and plural-component proportioners rented by shift reduce capital barriers for small shipyards and fabricators, expanding addressable market for coating suppliers without in-house application assets.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in waterborne resin stabilization and corrosion inhibitor synergy is concentrated among senior chemists at established Japanese and Korean suppliers, limiting new entrant product development velocity.
- Dual Certification Timeline Compression:Simultaneous BIS approval for India and GB standard compliance for China requires parallel toxicology testing and documentation, extending product launch cycles by 18-24 months for multi-country portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Protective Coatings Market |
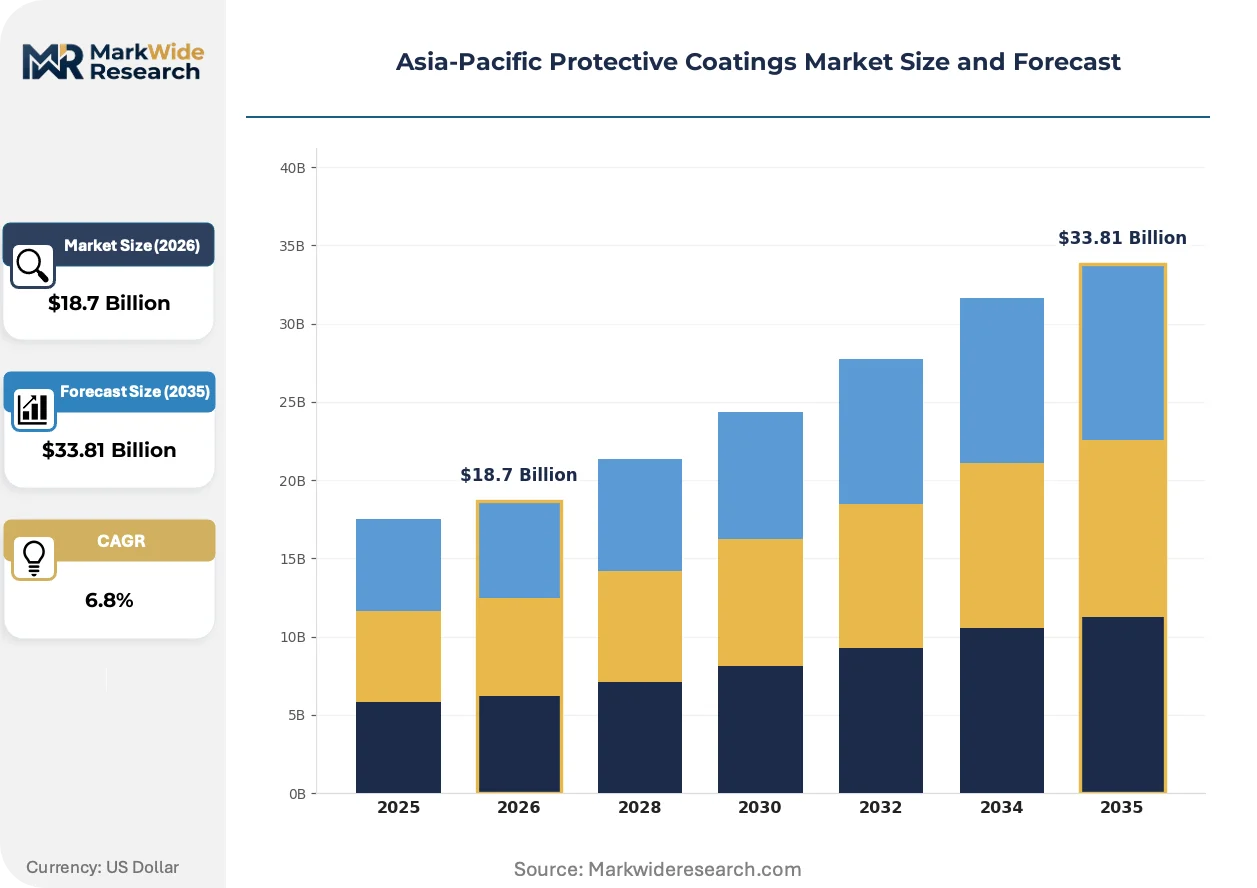
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Zinc Application: Marine, Industrial, Automotive, Architectural End User: Manufacturing, Construction, Energy, Transportation Technology: Waterborne, Solvent-borne, Powder Coating, UV Cure |
| Companies Covered | Akzo Nobel N.V., NIPSEA GROUP, The Sherwin Williams Company, PPG Industries, Inc., Hempel A/S, Jotun, Kansai Paint Co., Ltd., Nippon Paint Holdings Co., Ltd., Asian Paints, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Protective Coatings Market Strategic Shifts
Formulation science is pivoting toward bio-based resin platforms and application automation, with regulatory chemistry restrictions and shipyard labor costs driving concurrent investment in material substitution and process efficiency.
Waterborne epoxy technology is migrating from architectural maintenance into light industrial and marine non-immersion service. Japanese automotive parts suppliers and Chinese container manufacturers are adopting waterborne primers at accelerating rates for workplace exposure compliance. This migration is compressing the addressable market for conventional solvent-borne epoxies in segments previously considered technically protected.
Japan's METI building energy codes now mandate JIS-compliant low-VOC exterior coatings for commercial structures above specified floor areas. The regulation forces specification changes in architectural tenders across Tokyo and Osaka construction markets. High-performance fluoropolymer and silicone-modified acrylic suppliers capture premium positioning as certified compliant systems.
Shipyard procurement departments are unbundling coating supply from application service contracts that historically bundled material and labor. Korean and Chinese yards now source coatings through competitive tender while contracting application separately, compressing supplier margins and elevating technical service capabilities as differentiation factors. This unbundling is most visible at Hyundai Heavy Industries and COSCO Shipping Heavy Industry facilities.
Asia-Pacific Protective Coatings Market Segmentation
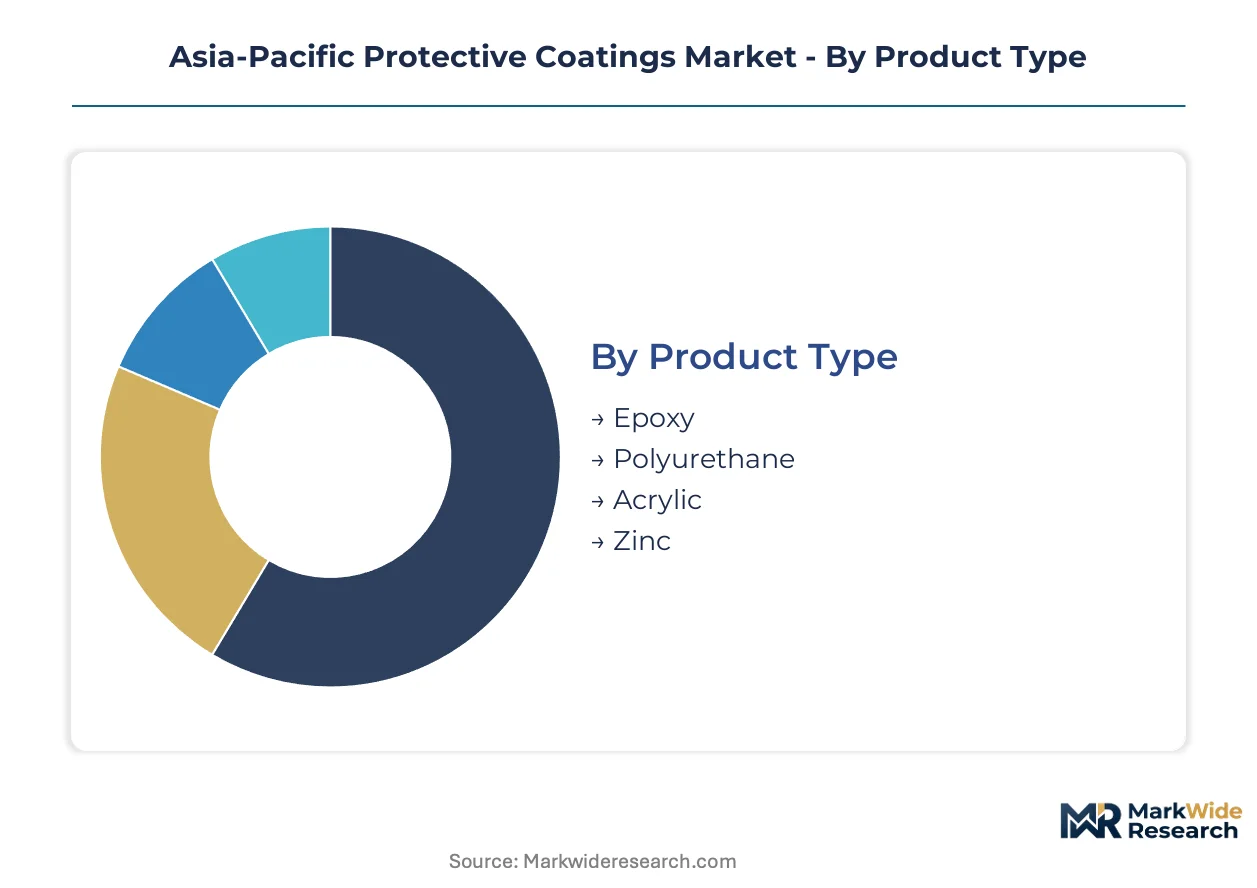
Protective coatings in Asia-Pacific serve fundamentally different performance requirements across immersion service, atmospheric exposure, and UV degradation environments. Segmentation reveals how resin chemistry, application method, and end-use severity drive specification divergence across Korean shipyards, Chinese industrial zones, and Japanese automotive assembly plants.
Product Type:
Resin chemistry determines barrier performance, adhesion mechanism, and cure kinetics for specific degradation modes.
- Epoxy:Two-part thermoset systems achieve 250-500 micron dry film thickness through amine or polyamide curing. Korean and Chinese shipyards specify these for ballast tank immersion and hull protection where cathodic disbondment resistance is mandatory. Reformulation pressure from China's MEE GB 30981 VOC limits is accelerating high-solids and waterborne epoxy development for compliant industrial maintenance.
- Polyurethane:Aliphatic isocyanate-cured films deliver gloss retention and UV stability for exterior exposure. Japanese automotive OEM lines specify high-solids polyurethane clearcoats for scratch resistance and long-term appearance durability. Polyurethane consumption concentrates in automotive refinishing and architectural metal cladding across Tokyo-Osaka industrial corridors.
- Acrylic:Thermoplastic emulsion and solvent-borne systems provide cost-effective atmospheric protection for infrastructure and commercial buildings. Waterborne acrylics dominate China's architectural maintenance sector under MEE enforcement.
- Zinc:Inorganic zinc silicate and organic zinc-rich primers supply sacrificial cathodic protection for steel structures. Port infrastructure projects across Busan and Shanghai specify zinc-rich systems for steel pile and offshore platform splash zone protection.
Epoxy commands the established base. The steepest expansion runs through waterborne acrylic reformulations.
Application:
Service environment severity dictates film thickness requirements, surface preparation standards, and recoat windows.
- Marine:IMO-compliant antifouling and corrosion protection for newbuild and maintenance cycles. Korean yards at Hyundai Heavy Industries and Imabari Shipbuilding in Japan drive specialty primer volumes through cyclical newbuild programs. Hull coating specifications now unbundle material supply from application contracts, compressing supplier margins while elevating technical service requirements.
- Industrial:Petrochemical, power generation, and manufacturing facility protection against chemical splash and atmospheric corrosion. China's coastal manufacturing clusters in Jiangsu and Guangdong sustain heavy coating volumes through infrastructure buildout and refinery expansion.
- Automotive:OEM assembly line coatings and refinishing systems for exterior panels and underbody protection. Japanese and Chinese assembly plants specify polyurethane clearcoats and waterborne primers for workplace exposure compliance and durability performance.
- Architectural:Commercial and residential building envelope protection including structural steel, roofing, and exterior walls. Japan's METI building energy codes mandate JIS-compliant low-VOC systems for commercial structures above specified floor areas.
Marine application anchors revenue concentration. Industrial maintenance is gaining share fastest as China's petrochemical expansion sustains recoating cycles.
End User:
Capital intensity and regulatory exposure create divergent procurement patterns across customer categories.
- Manufacturing:Electronics, automotive component, and consumer goods facilities require cleanroom-compatible and corrosion-resistant coatings. Northern Vietnam manufacturing zones near Hai Phong attract greenfield investment without legacy solvent-borne infrastructure.
- Construction:Commercial, residential, and infrastructure projects specify coatings for structural steel, concrete protection, and architectural metal. India's BIS compulsory certification for industrial protective grades creates barrier-to-entry advantages in infrastructure tenders.
- Energy:Power generation, transmission, and renewable energy installations demand high-performance corrosion protection. Offshore wind development in Chinese and Korean waters drives specialized coating specifications for splash zone and atmospheric service.
- Transportation:Rail, aerospace, and shipping logistics infrastructure require abrasion-resistant and chemically tolerant systems. Port terminal operators across Busan and Shanghai specify zinc-rich primers for steel pile protection in marine atmospheric zones.
Manufacturing end users concentrate specification authority. Energy sector demand is climbing fastest through offshore wind deployment.
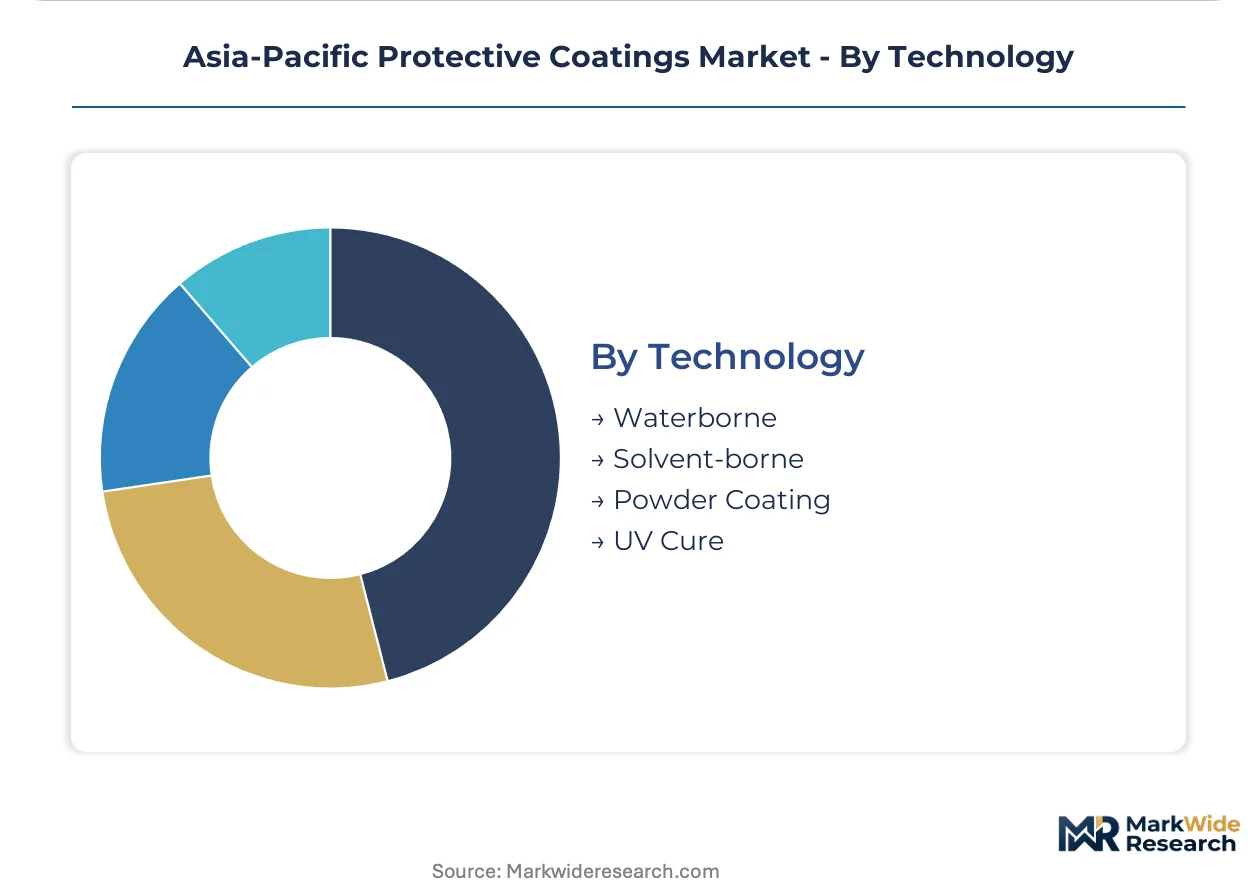
Technology:
Formulation platform determines VOC emissions, application efficiency, and cure energy requirements.
- Waterborne:Acrylic and epoxy emulsions displace solvent-borne systems under regulatory pressure. China's MEE GB standards enforce VOC limits that accelerate waterborne deployment in architectural and light industrial segments previously considered technically protected for solvent-borne epoxies.
- Solvent-borne:Conventional alkyd and epoxy systems retain dominance in immersion service above 150 microns dry film thickness. Technical limitations in waterborne corrosion resistance restrict penetration in offshore platform and subsea pipeline specifications.
- Powder Coating:Thermoset epoxy and polyester powders provide zero-VOC application for metal substrates. Automotive component and appliance manufacturers adopt powder systems for line efficiency and environmental compliance.
- UV Cure:Rapid-cure acrylic and epoxy formulations enable high-throughput industrial finishing. Electronics and wood coating applications in Japanese and Korean manufacturing facilities specify UV cure for energy efficiency and reduced work-in-process inventory.
Solvent-borne technology retains the installed base. Waterborne platforms are expanding most quickly through regulatory displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in South Korean shipyards exceeds that in Vietnamese manufacturing zones due to specification authority concentration at Hyundai Heavy Industries and Imabari Shipbuilding. China's coastal industrial clusters absorb the heaviest coating volumes through infrastructure buildout. Regulatory fragmentation across MEE GB standards, BIS certification, and METI codes creates parallel compliance tracks for multi-country suppliers.
China
Petrochemical expansion and offshore wind deployment in Jiangsu and Guangdong provinces sustain epoxy and zinc-rich primer consumption. MEE enforcement of GB 30981 VOC limits forces simultaneous reformulation across solvent-borne alkyd and epoxy lines. The Yangtze River Delta manufacturing corridor generates replacement demand for waterborne systems as coastal cities tighten workplace exposure rules.
Japan
Automotive OEM lines at Toyota and Honda assembly plants specify high-solids polyurethane clearcoats for scratch resistance and exterior durability. METI building energy codes mandate JIS-compliant low-VOC coatings for commercial structures above specified floor areas. The Kansai industrial corridor around Osaka anchors polyurethane consumption through refinishing and architectural metal cladding demand.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive cyclical epoxy primer volumes for ballast tank immersion and hull protection. MFDS coordination with shipyard safety regulators enforces workplace exposure limits during spray application. The Busan-Ulsan shipbuilding cluster sustains specialty coating demand through newbuild programs and maintenance cycles.
India
Infrastructure tenders and power sector expansion generate industrial protective coating demand across Maharashtra and Gujarat. BIS compulsory certification for industrial protective grades creates barrier-to-entry advantages for pre-certified suppliers in government contracts. The Delhi-Mumbai Industrial Corridor attracts coating specification for steel structures in logistics and manufacturing facilities.
Vietnam
Electronics and automotive component investment near Hai Phong generates greenfield demand for protective coatings in facilities without legacy solvent-borne infrastructure. The country's national environmental regulator enforces workplace safety standards that favor waterborne and powder coating adoption. Northern manufacturing zones specify compliant systems from project inception rather than retrofitting existing assets.
Asia-Pacific Protective Coatings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and pigment supply. The Asia-Pacific protective coatings market structures around consolidated multinational formulators with captive resin capabilities and fragmented regional applicators lacking backward integration. Three archetypes dominate: integrated chemical conglomerates with in-house epoxy production, coating specialists focused on marine and industrial niches, and diversified paint manufacturers serving automotive OEM lines. Competitive moves concentrate on formulation reformulation for VOC compliance and technical service expansion to capture unbundled shipyard procurement.
Among integrated chemical conglomerates, Akzo Nobel N.V. and PPG Industries, Inc. occupy positions defined by captive resin supply and marine specification authority. Japanese specialists Kansai Paint Co., Ltd. and Nippon Paint Holdings Co., Ltd. exemplify the automotive-focused archetype through polyurethane clearcoat positioning. Hempel A/S represents the marine-dedicated tier with zinc-rich primer specialization for port infrastructure. These named entities anchor competitive dynamics without exhaustively mapping strategic actions or financial performance.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| NIPSEA GROUP |
| The Sherwin Williams Company |
| PPG Industries, Inc. |
| Hempel A/S |
| Jotun |
| Kansai Paint Co., Ltd. |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints |
| Others |
Value Chain & Pricing Dynamics
Titanium dioxide export quota disruptions from Chinese pigment producers determine both the spread between premium and economy coating tiers and the geographic shape of regional resin supply networks. Formulators without captive TiO2 sourcing face margin compression that reshapes procurement toward integrated suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on BIS certification grade and volume scale, with pre-certified suppliers commanding premium positioning in Indian infrastructure tenders. Pricing pressure intensifies as waterborne epoxy reformulation costs compress mid-tier margins. Small fabricators and shipyards without captive application assets exhibit highest price sensitivity, while Hyundai Heavy Industries and Imabari Shipbuilding leverage specification authority to resist pass-through.
Supply Chain Analysis
Tariff exposure between China and key coating export destinations dominates supply chain risk assessment for Asia-Pacific formulators. Epoxy resin production concentrates in China, South Korea, and Japan, drawing from naphtha and propylene feedstocks tied to regional petrochemical contract movements. Single-source vulnerability sits with Chinese TiO2 producers controlling architectural white pigment pricing. Distribution runs through direct mill supply contracts to Korean shipyards and distributor networks serving Indian and Vietnamese industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne technology substitution threatens solvent-borne epoxy incumbents as China's MEE enforcement accelerates compliant formulation displacement. Incumbents must navigate this transition while defending specification authority in immersion service segments.
For Market Incumbents: Pre-empt waterborne corrosion resistance gaps by investing in resin stabilization R&D before technical limitations erode offshore platform market share. Secure captive TiO2 supply through backward integration or long-term offtake agreements to defend margin position against pigment volatility. BIS certification timelines create temporary moats—accelerate parallel toxicology documentation for India and China compliance.
For New Entrants and Emerging Players: Pursue Vietnam's northern manufacturing zones near Hai Phong, where greenfield electronics and automotive component facilities lack legacy solvent-borne infrastructure and specify compliant systems from project inception. Target waterborne primer demand from Japanese automotive parts suppliers and Chinese container manufacturers adopting workplace exposure-compliant coatings. Lead with asset-light application equipment leasing to reduce capital barriers for small fabricators.
For Investors and Strategic Acquirers: India's BIS compulsory certification for industrial protective grades reshapes the acquisition landscape by elevating pre-certified suppliers in government tender participation. Long-term viability favors formulators with captive resin capabilities and marine specification authority over pure-play applicators. Watch MEE enforcement intensity in Jiangsu and Guangdong as the signal for waterborne technology inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Captive resin supply insulates PPG Industries and Akzo Nobel from naphtha contract volatility. |
| BIS Certification Investment | Pre-certified suppliers capture barrier-to-entry advantages in Indian infrastructure and power sector tenders. |
| Waterborne Technology Migration | Formulation reformulation for China's MEE GB 30981 compliance displaces solvent-borne alkyd market share. |
| Asset-Light Equipment Leasing | Mobile spray unit rentals expand addressable market for coating suppliers without in-house application assets. |
| Technical Service Expansion | Unbundled shipyard procurement elevates technical capabilities as differentiation factors at Hyundai Heavy Industries. |
Study Parameters
Operator-level perspectives from plant managers at Korean and Chinese shipyards, procurement leads at Japanese automotive OEMs, technical R&D directors at resin suppliers, and distribution channel partners across India and Vietnam anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, ACC and Cefic regional reports, SEC 10-K filings of listed coating manufacturers, and BIS certification registries. Bottom-up coating volume estimates by application segment triangulated against top-down petrochemical feedstock consumption patterns.
Scenario-bracketing framed the analytical approach across the projection horizon, with CAGRs derived from segment-level volume trajectories and value-per-unit adjustments for technology mix shifts. Segmentation dimensions modeled include resin chemistry tier, application severity environment, end-use capital intensity, and formulation technology platform. Industry-specific forecast inputs incorporated shipyard newbuild order cycles from Hyundai Heavy Industries and Imabari Shipbuilding, plus MEE enforcement phase-in assumptions for VOC compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in naphtha contract pricing, Chinese TiO2 export policy, or shipyard capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Anti-Smudge Coatings Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Insulation Coating Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Epoxy Coating Market
Coatings
Noise and Vibration Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
Conductive Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Hull Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market