
 High Protein Yogurt Market | 2026-2036
High Protein Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
High Protein Yogurt Market Outlook
Greece is tilting toward expanded strained yogurt capacity as domestic dairies scale fermentation infrastructure. Chobani LLC leverages its U.S. manufacturing base to sustain volume leadership in Greek-style production. Danone anchors European distribution through refrigerated supply chain control. Fage SA specializes in authentic strained yogurt methods that differentiate its protein density claims.
High protein yogurt denotes fermented dairy containing elevated protein content, typically achieved through straining whey or fortification with milk protein concentrates, yielding textures from 10 to 20 grams per serving. It serves commercial and retail buyers seeking satiety, muscle recovery support, and meal replacement functionality. Greek Yogurt occupies the dominant margin pool due to consumer familiarity and premium positioning, while Skyr segments attract Nordic-origin branding premiums. Drinkable formats represent the fastest-growing form category as on-the-go consumption expands.
EFSA governs nutrition and health claims across Europe, compelling evidence-backed protein content declarations. The EU Green Deal pressures dairies toward lower-carbon production methods, reshaping ingredient sourcing requirements. USDA grade standards and FDA labeling rules enforce compositional thresholds in the United States. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs reshape competitive parity across export markets.
Market Dynamics
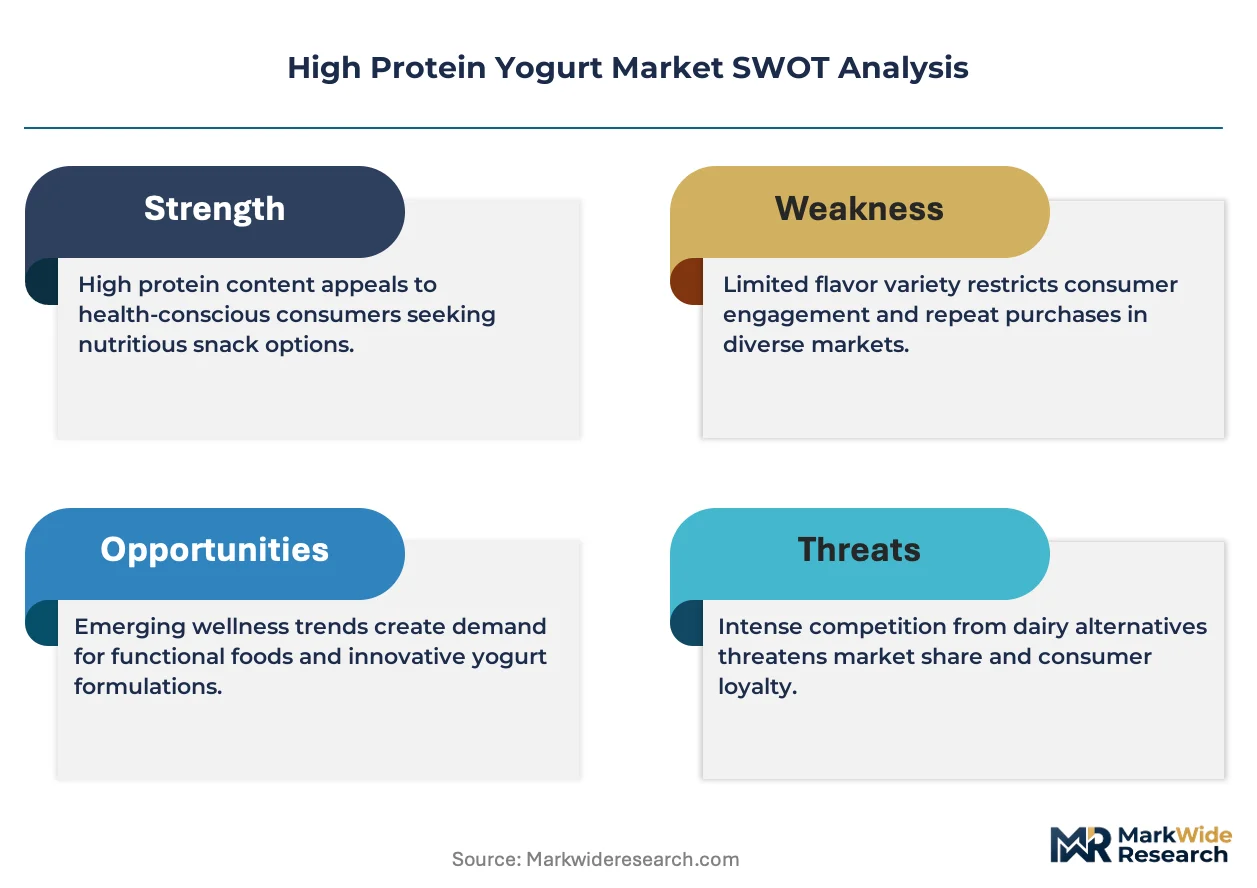
The High Protein Yogurt Market is being structurally reshaped by EFSA's tightening enforcement of nutrition claims under the EU Green Deal, which forces dairies to reformulate toward cleaner ingredient decks while maintaining protein density targets. This regulatory pressure intersects with consumer demand for functional post-workout nutrition, creating simultaneous pulls on formulation and sourcing.
Growth Catalysts
- Fitness Enthusiast Adoption:Post-workout nutrition routines drive repeat purchase frequency as consumers integrate high protein yogurt into daily recovery protocols.
- EU Green Deal:The framework's lower-carbon production mandates accelerate dairy investment in sustainable fermentation infrastructure and ingredient sourcing.
- Drinkable Format Expansion:On-the-go consumption patterns pull manufacturing capacity toward portable packaging lines and ambient-stable processing.
Market Restraints
- Milk Protein Concentrate Volatility:Input costs for fortification-grade concentrates fluctuate with global dairy commodity cycles, squeezing margin predictability.
- Strained Yogurt Capacity Concentration:Authentic Greek and Skyr production clusters in limited geographic zones, creating supply bottlenecks during demand spikes.
- Labeling Evidence Requirements:EFSA's substantiation demands for protein content claims extend product development timelines and raise compliance expenditure.
Strategic Opportunities
- Underpenetrated German Functional Dairy:Continental Europe's highest per-capita consumption of functional dairy creates expansion room for premium protein variants.
- Refrigerated Supply Chain Control:Investment in cold-chain distribution assets unlocks direct-to-retail placement and margin capture.
- Strained Method Convergence:Hybridization of traditional Greek straining with Nordic Skyr techniques enables differentiated texture and protein positioning.
Industry Challenges
- Fermentation Infrastructure Capex:Scaling authentic strained yogurt capacity requires substantial capital deployment for specialized equipment and extended culturing vessels.
- Cross-Jurisdictional Compliance Divergence:Reconciling EFSA evidence standards with USDA grade thresholds and FDA labeling rules fragments product portfolio management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Protein Yogurt Market |
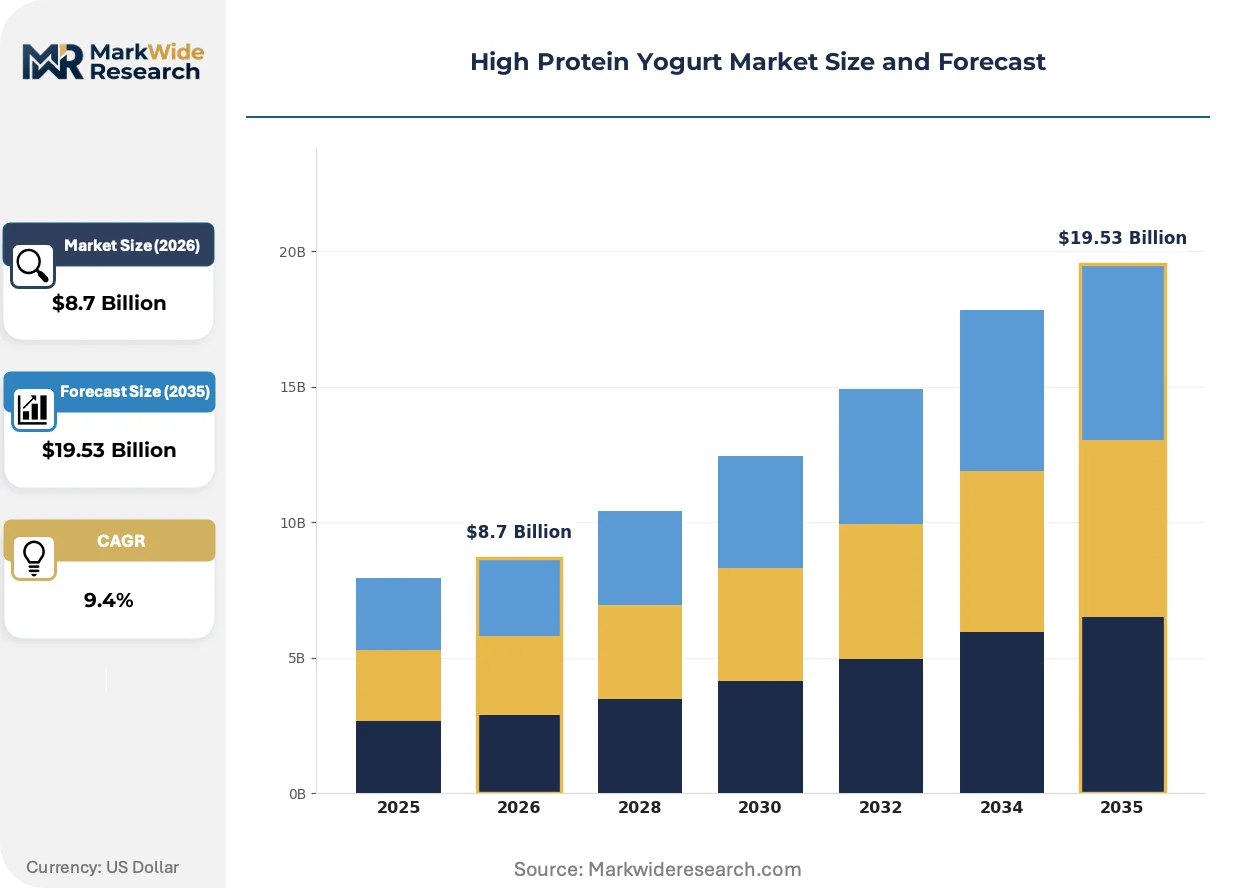
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Icelandic Yogurt, Skyr, Regular Yogurt Form: Liquid, Cup, Tub, Drinkable Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Customer Type: Fitness Enthusiasts, Busy Professionals, Health-Conscious Consumers, Athletes |
| Companies Covered | Arla Foods, Lifeway Foods Inc., Chobani LLC, Alpro Ltd., Noosa Holdings Inc., Danone, Müller Co. LLC, Yeo Valley Farms Ltd., Fage SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Protein Yogurt Market Strategic Shifts
Product format evolution and regulatory tightening are converging to reshape competitive positioning in high protein yogurt. Manufacturers must simultaneously navigate cleaner-label mandates, protein density maintenance, and shifting consumption occasions.
Ultrafiltration membrane technology is hybridizing traditional straining methods with precision protein concentration. Commercial dairies adopt these systems to achieve 15-20 gram protein targets without excessive whey loss. The technology compresses production timeframes while enabling texture consistency across batches.
EFSA's updated guidance on nutrition and health claims enforcement is tightening evidentiary standards for protein content declarations. Dairy processors must now maintain batch-level documentation linking analytical results to label statements. Greek Yogurt segments face the steepest compliance burden given their premium positioning on protein density.
On-the-go consumption patterns are fragmenting traditional retail channel dominance. Fitness-oriented buyers increasingly source high protein yogurt through convenience stores, gyms, and direct subscription models. Germany exhibits the most pronounced channel diversification as functional dairy permeates non-traditional points of purchase.
High Protein Yogurt Market Segmentation
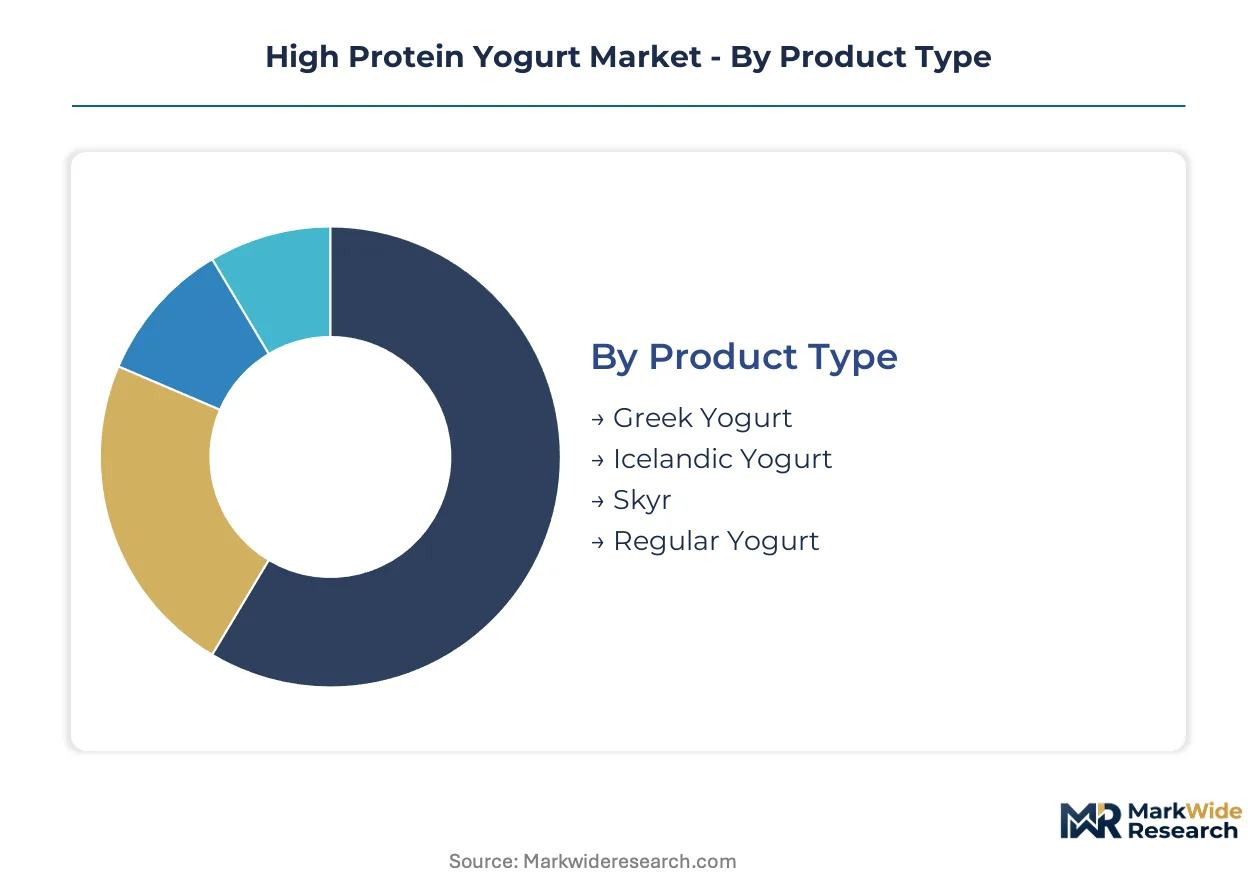
Segmentation in high protein yogurt reflects divergent consumption occasions, protein density preferences, and channel access patterns. Manufacturers configure formulation, packaging, and pricing strategies around distinct buyer workflows rather than demographic proxies alone.
Product Type:
Use-case spectrum spans post-workout recovery, meal replacement, and premium snacking, each demanding different protein concentration and texture profiles.
- Greek Yogurt:Strained through cloth or membrane separation to achieve 15-20 grams protein per serving with thick, spoonable consistency. Demand concentrates in Germany and US coastal metro areas where functional dairy commands shelf space premiums and repeat purchase rates exceed conventional yogurt by wide margins.
- Skyr:Icelandic strained method yields even higher protein density through longer fermentation cycles and quadruple straining, creating a tart, dense texture. Nordic-origin branding attracts premium positioning in UK and Netherlands markets where provenance storytelling supports price architecture.
- Icelandic Yogurt:Similar production heritage to Skyr but often differentiated through specific heirloom cultures and regional sourcing claims.
- Regular Yogurt:Protein-fortified through milk protein concentrate addition rather than straining, occupying accessible price tiers for cost-sensitive buyers.
The dominant share belongs to Greek Yogurt, while Skyr is closing the gap fastest.
Form:
Packaging configuration directly determines consumption occasion access and cold-chain investment requirements.
- Drinkable:Ambient-stable or chilled liquid formats in single-serve bottles enable gym bag, commute, and desk consumption without utensil dependency. German convenience retail and fitness center vending networks have expanded shelf facings most aggressively.
- Cup:Individual portion cups dominate supermarket dairy cases with portion-controlled servings and mix-in compartment options for texture contrast.
- Tub:Multi-serve containers target household pantry stocking and recipe integration for baking or smoothie bases.
- Liquid:Larger-format pourable options for foodservice and institutional channels requiring volume scalability.
Drinkable formats are expanding most quickly as on-the-go consumption fragments traditional sit-down breakfast occasions.
Distribution Channel:
Channel selection shapes margin capture, brand positioning, and consumer education requirements.
- Supermarkets:Refrigerated dairy cases provide primary discovery and trial environment with competitive shelf sets demanding trade investment.
- Health Food Stores:Curated assortments favor organic, grass-fed, and additive-free variants with educated staff enabling product education.
- Online Retail:Subscription models and direct-to-consumer shipping build loyalty through flavor customization and replenishment automation.
- Convenience Stores:Grab-and-go placement captures impulse and replenishment purchases in transit corridors and urban density zones.
Supermarkets retain volume leadership, though online retail is climbing the fastest as subscription mechanics reduce churn.
Customer Type:
Buyer archetypes align protein density, timing, and brand attributes with distinct lifestyle workflows.
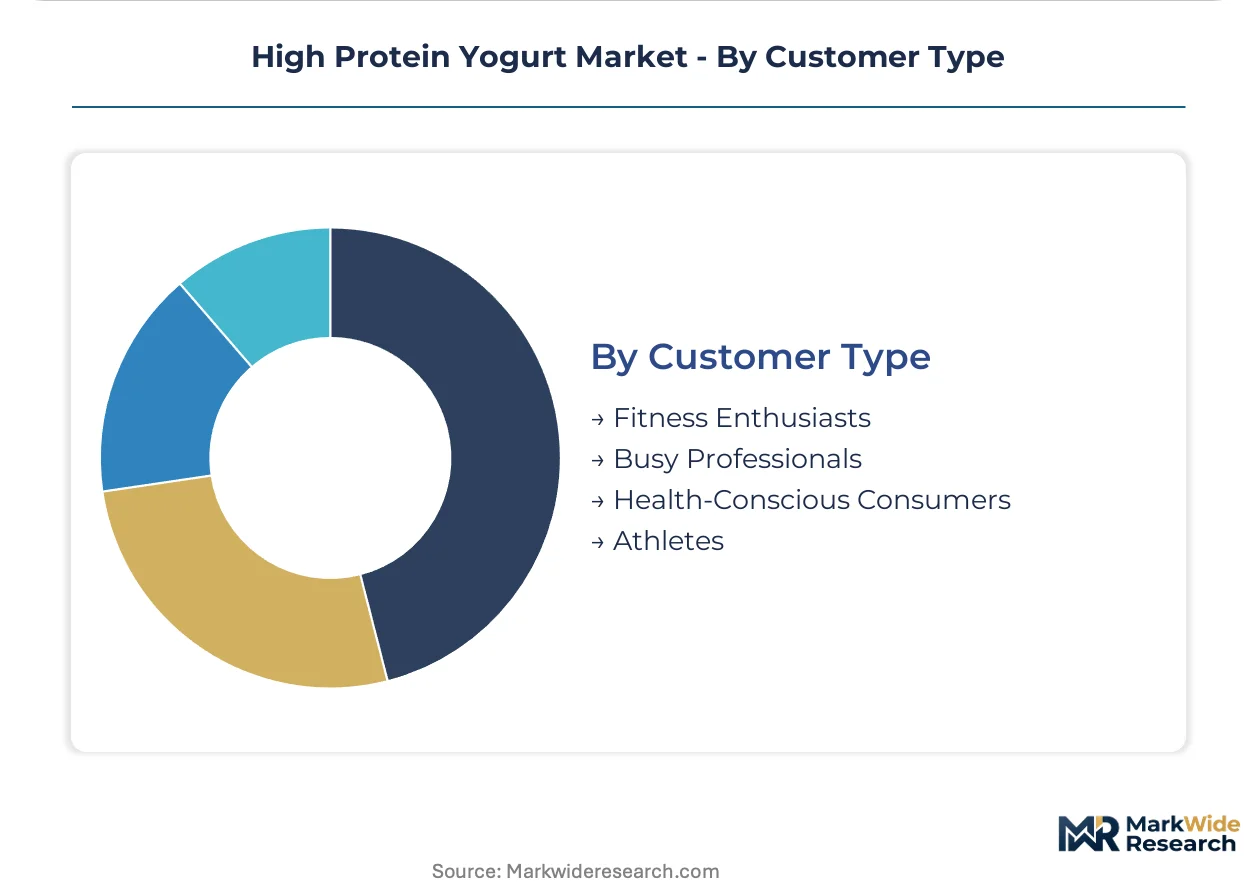
- Fitness Enthusiasts:Scheduled post-workout consumption drives 20-gram protein minimum requirements and batch purchasing behavior.
- Athletes:Competitive and recreational performers prioritize leucine content, digestive tolerability, and batch-tested certification for supplement regimen integration.
- Busy Professionals:Desk-drawer and commute-friendly formats with minimal preparation and mess risk support irregular meal timing.
- Health-Conscious Consumers:General wellness positioning around gut health, satiety, and clean label attributes without specific performance claims.
Fitness Enthusiasts anchor category volume, while Athletes are gaining share fastest as sports nutrition and dairy categories blur.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA governs nutrition claims enforcement across Germany, where functional dairy consumption per capita exceeds all other continental European markets. This regulatory anchor shapes formulation standards that neighboring jurisdictions increasingly reference.
Germany
Fitness enthusiasts in Berlin and Munich drive post-workout yogurt consumption through gym-affiliated retail partnerships. The EU Green Deal pressures Bavarian dairies toward lower-carbon fermentation infrastructure. The Munich-Stuttgart corridor hosts concentrated strained yogurt capacity expansion as domestic processors scale ultrafiltration membrane installations.
United States
USDA grade standards and FDA labeling rules enforce protein content thresholds that shape import acceptance criteria. Greek-style production clusters in upstate New York and Idaho where Chobani LLC maintains volume leadership through integrated manufacturing. The Northeast dairy belt sees sustained capacity investment for drinkable format lines targeting convenience store distribution.
United Kingdom
Nordic-origin Skyr branding commands premium positioning in London and Southeast England retail channels. The Food Standards Agency implements EFSA-aligned claim substantiation requirements that extend product development timelines. Yorkshire and Lancashire dairy cooperatives are retrofitting facilities for extended fermentation cycles that match Icelandic texture profiles.
France
ANSM and DGCCRF enforce strict additive disclosure rules that favor clean-label strained methods over fortification approaches. Parisian health food retailers curate artisanal Greek yogurt assortments with provenance storytelling. The Brittany-Normandy dairy basin experiments with heirloom culture strains that differentiate regional protein density claims.
Australia
FSANZ regulates protein content declarations with analytical documentation requirements comparable to EFSA standards. Melbourne and Sydney fitness center vending networks expand chilled drinkable yogurt facings for commuter consumption patterns. Victorian dairy processors invest in ambient-stable processing technology that extends distribution reach into remote interior markets.
High Protein Yogurt Market Competitive Environment
Capability concentration sits with authentic strained-method specialists; scale advantage sits with diversified dairy multinationals controlling refrigerated supply chains. The market structures around three tiers: heritage Greek producers, Nordic-origin Skyr specialists, and protein-fortified conventional yogurt extenders. Consolidation pressures favor players with captive milk supply and fermentation infrastructure ownership. Dominant competitive moves include hybrid straining technology licensing and direct-to-retail cold chain bypass strategies.
Within the heritage specialist tier, Fage SA exemplifies authentic strained yogurt positioning through traditional cloth-separation methods, while Chobani LLC occupies the scale-driven vector with integrated US manufacturing and volume leadership in Greek-style production. Danone represents the multinational archetype with European refrigerated distribution control and portfolio breadth spanning protein density segments.
| Leading Market Players |
|---|
| Arla Foods |
| Lifeway Foods Inc. |
| Chobani LLC |
| Alpro Ltd. |
| Noosa Holdings Inc. |
| Danone |
| Müller Co. LLC |
| Yeo Valley Farms Ltd. |
| Fage SA |
| Others |
Value Chain & Pricing Dynamics
Milk protein concentrate volatility determines both pricing tier spreads and supply chain shape in high protein yogurt, compressing margins for fortified variants while authentic strained methods capture premium positioning through captive whey processing infrastructure.
Pricing Analysis
German retail shelves exhibit the widest price spreads between economy fortified yogurts and authentic Greek or Skyr variants. Three-tier pricing structure across premium, standard, and economy levels reflects protein density claims, fermentation method authenticity, and organic certification status. Cost compression in economy tiers is intensifying because global dairy commodity cycles squeeze milk protein concentrate margins. Fitness enthusiasts demonstrate the lowest price sensitivity, while cost-conscious household buyers drive volume in protein-fortified regular yogurt segments.
Supply Chain Analysis
Extended payment terms from German supermarket chains strain working capital for smaller dairies investing in ultrafiltration membrane systems. Authentic strained yogurt capacity concentrates in Greece, Iceland, and upstate New York, drawing from specialized fermentation vessels and heirloom culture banks. Raw material dependencies center on milk protein concentrates, live active cultures, and temperature-controlled packaging. Single-source vulnerability in Icelandic Skyr cultures creates supply risk during demand spikes. Distribution runs through refrigerated logistics networks controlled by multinational dairy conglomerates with direct-to-retail bypass emerging in subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authentic strained-method fermentation expertise functions as a scarce capability in this market, with limited specialists capable of achieving EFSA-substantiated protein density claims through traditional cloth-separation or precision ultrafiltration.
For Market Incumbents: Pre-empt private-label encroachment by locking up exclusive milk supply contracts in Bavaria and Baden-Württemberg, while accelerating certification for EU Green Deal carbon accounting to defend premium shelf positioning against emerging Nordic-origin competitors. For New Entrants and Emerging Players: Eastern European convenience retail represents the most penetrable white space, where functional dairy familiarity lags German levels but disposable income growth supports premium trial. Target gym-affiliated vending networks in Prague and Warsaw with ambient-stable drinkable formats as the initial go-to-market angle. For Investors and Strategic Acquirers: EFSA's updated evidentiary standards for protein claims reshape the acquisition landscape toward targets with batch-level analytical documentation infrastructure. Five-to-ten-year viability favors dairies with captive fermentation equipment and direct milk supply rather than toll-processing arrangements. Monitor EU Green Deal implementation timelines as the signal for when carbon-labeled production becomes table stakes rather than differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrafiltration Membrane Installation | Compresses Greek yogurt production cycles while maintaining EFSA-substantiated protein density claims. |
| Heirloom Culture Banking Partnership | Secures proprietary strain access that differentiates texture profiles from commodity fermented products. |
| Direct-to-Subscription Channel Launch | Bypasses refrigerated supply chain markups and captures recurring revenue from fitness enthusiast segments. |
| Ambient-Stable Processing Line Addition | Extends distribution reach into convenience retail and gym vending networks without cold-chain dependency. |
| EU Green Deal Certification Program | Positions premium tiers for forthcoming carbon-labeling mandates in German and French retail channels. |
Study Parameters
Two parallel data streams informed the analysis: primary engagement with dairy processing executives, fermentation technology specialists, retail category buyers, and regulatory affairs consultants; and secondary validation through EFSA guidance documents, EU Green Deal implementation texts, customs trade data for milk protein concentrates, and refrigerated logistics capacity disclosures. Bottom-up triangulation against top-down market sizing anchored volume estimates.
Forecast inputs considered protein density segment trajectories, format evolution from cup to drinkable, channel shift toward online subscription, and geographic expansion patterns across the analysis window. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled variables included fermentation infrastructure capex cycles, EFSA claim substantiation timelines, and EU carbon accounting adoption curves.
Practitioners should monitor EFSA enforcement actions, milk protein concentrate price indices, and EU Green Deal dairy sector guidance for early signals of forecast deviation. Macroeconomic contraction, regulatory timeline acceleration, or breakthrough ambient-stable protein preservation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Butter and Margarine Market
Dairy Products
Europe Cheese Market
Dairy Products
North America Flavored Milk Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Dairy Products Market
Dairy Products
White Cheese Market
Dairy Products
South America Yogurt Market
Dairy Products
Dairy Blends Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Organic Milk Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
GCC Casein Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Dairy Dessert and Yogurt Market