
 Bio-Polybutadiene Market | 2026-2036
Bio-Polybutadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Polybutadiene Market Outlook
Petroleum-derived polybutadiene is restructuring around bio-based feedstock alternatives as tire makers face Scope 3 carbon accounting pressure. Arlanxeo leverages its butadiene expertise to anchor European supply chains for renewable elastomers. Lanxess AG sustains specialty polymer leadership through advanced functionalization capabilities. Zeon Corporation competes on high-cis polybutadiene purity standards that OEMs demand for performance tire formulations.
Bio-polybutadiene denotes a synthetic elastomer produced from renewable feedstocks such as biomass-derived butadiene or fermentation pathways, typically exhibiting 90-98% cis-1,4 content and Mooney viscosity ranges of 40-70 ML at 100°C for tire and industrial applications. The material delivers abrasion resistance and low rolling friction for automotive tire treads, conveyor belts, and golf ball cores. Thermoplastic elastomers command expanding application scope as processors seek recyclable alternatives to conventional vulcanized rubber in consumer goods. Styrene-butadiene rubber retains volume dominance in tire manufacturing where blending with natural rubber remains standard practice. Functionalized polymers capture premium positioning through grafted polar groups that improve silica filler compatibility in low-rolling-resistance tire compounds.
EPA renewable fuel standards and REACH registration requirements in the European Union shape feedstock qualification pathways for bio-based polymer producers seeking market access. Japan's METI bio-economy strategy and ISO 16620 biobased content certification frameworks establish measurement protocols that OEM procurement teams embed in supplier scorecards. Stakeholders must monitor fermentation yield improvements and catalytic dehydrogenation economics to determine when bio-polybutadiene achieves cost parity with naphtha-derived equivalents at commercial tire production scales.
Market Dynamics
Tire manufacturers in Germany and Japan face mounting pressure from automotive OEMs to decarbonize Scope 3 supply chains, forcing rapid feedstock transitions from naphtha-derived butadiene to biomass-based alternatives. This structural pull is compressing qualification timelines for renewable elastomers while fermentation economics remain unresolved.
Growth Catalysts
- EU REACH petrochemical limits:Registration requirements under REACH tighten allowable petrochemical content in tire formulations, compelling compounders to qualify bio-based synthetic rubber alternatives.
- Japan METI bio-economy roadmap:National targets for bio-based material adoption accelerate procurement mandates for domestic tire producers serving Toyota and Honda supply chains.
- High-cis polybutadiene purity standards:Performance tire specifications demanding 90-98% cis-1,4 content pull investment into precision fermentation and catalytic dehydrogenation technologies.
Market Restraints
- Fermentation yield volatility:Sugarcane and corn starch feedstock costs fluctuate with agricultural commodity markets, undermining cost predictability against naphtha benchmarks.
- Butadiene supply concentration:Three petrochemical corridors in Texas, Rotterdam, and Singapore control conventional butadiene flows, limiting bio-alternative distribution infrastructure.
- Mooney viscosity batch inconsistency:Renewable production pathways struggle to achieve the tight 40-70 ML viscosity ranges that tire compounders require for automated mixing lines.
Strategic Opportunities
- US Midwest tire cluster proximity:Bio-polybutadiene producers locating near Ohio and Indiana production hubs capture direct-to-mixer logistics advantages and bypass coastal import bottlenecks.
- Thermoplastic elastomer recyclability:Golf ball core and consumer goods manufacturers seek vulcanization-free alternatives, opening non-tire revenue streams with simpler processing requirements.
- ISO 16620 biobased certification:Third-party verification frameworks enable premium pricing differentiation for compounders documenting renewable carbon content in sustainability scorecards.
Industry Challenges
- Catalytic dehydrogenation engineering talent:Scarcity of process chemists experienced in biomass-to-butadiene pathways delays pilot-to-commercial scale-up timelines.
- Silica filler compatibility testing:Functionalized polymer variants require 18-24 month qualification cycles with tire OEMs before achieving approved supplier status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Polybutadiene Market |
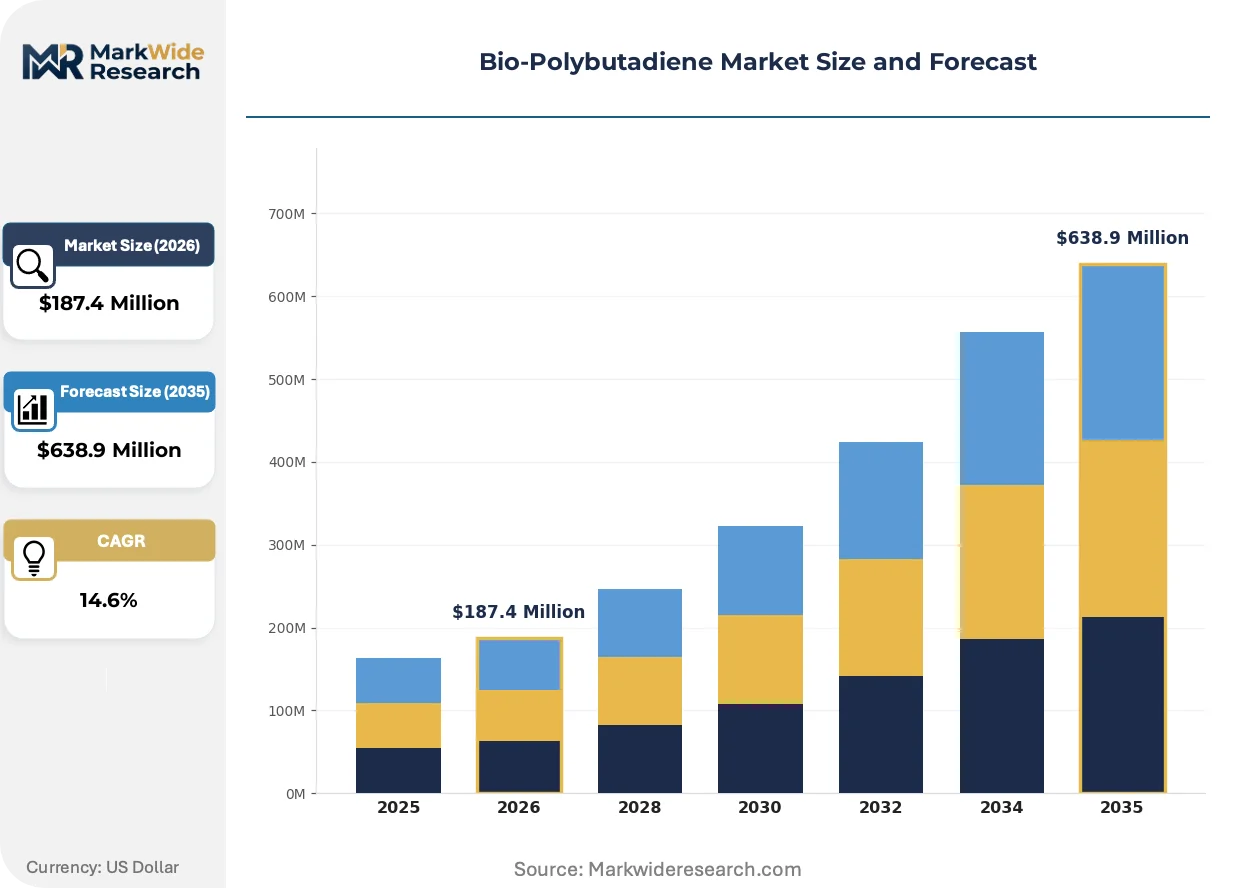
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Copolymers, Functionalized Polymers, Thermoplastic Elastomers, Styrene-Butadiene Rubber Application: Aerospace, Automotive, Consumer Goods, Medical Devices End User: Manufacturers, Distributors, Retailers, OEMs Technology: Polymerization, Blending, Compounding, Additive Manufacturing |
| Companies Covered | Evonik Industries, Lanxess AG, Kuraray Co., Ltd., Sinopec, LG Chem, Genomatica, Arlanxeo, Versalis, Zeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Polybutadiene Market Strategic Shifts
Fermentation-derived butadiene pathways are compressing the technical gap with petrochemical equivalents while regulatory measurement frameworks standardize bio-content verification. These forces are reconfiguring supplier qualification protocols and procurement evaluation criteria across automotive supply chains.
Biomass gasification coupled with catalytic dehydrogenation is absorbing capital allocation from tire compounders seeking supply security outside naphtha value chains. Bridgestone and Michelin procurement teams are trialing pilot volumes from European biorefinery partners. The technology is absorbing risk premiums previously assigned to renewable feedstock uncertainty, compressing the effective cost gap with conventional polybutadiene by eliminating intermediate trading margins.
Japan's METI bio-economy strategy and accompanying JIS standards for biobased content measurement create enforceable procurement thresholds for domestic tire exports. The policy mandates ISO 16620-aligned verification for suppliers seeking preferential treatment in government fleet contracts. High-performance tire segments in Germany and Japan are responding fastest, embedding biobased percentage targets directly into compounder scorecards alongside rolling resistance and wear metrics.
Automotive OEMs now require tier-one tire suppliers to submit Scope 3 emission disclosures with verified feedstock carbon intensity data. This unbundles the traditional rubber procurement bundle, separating base polymer sourcing from compounding and manufacturing steps. The shift is most visible in southern Germany, where BMW and Mercedes-Benz sustainability procurement teams audit supplier fermentation pathways and energy inputs for bio-polybutadiene qualification.
Bio-Polybutadiene Market Segmentation
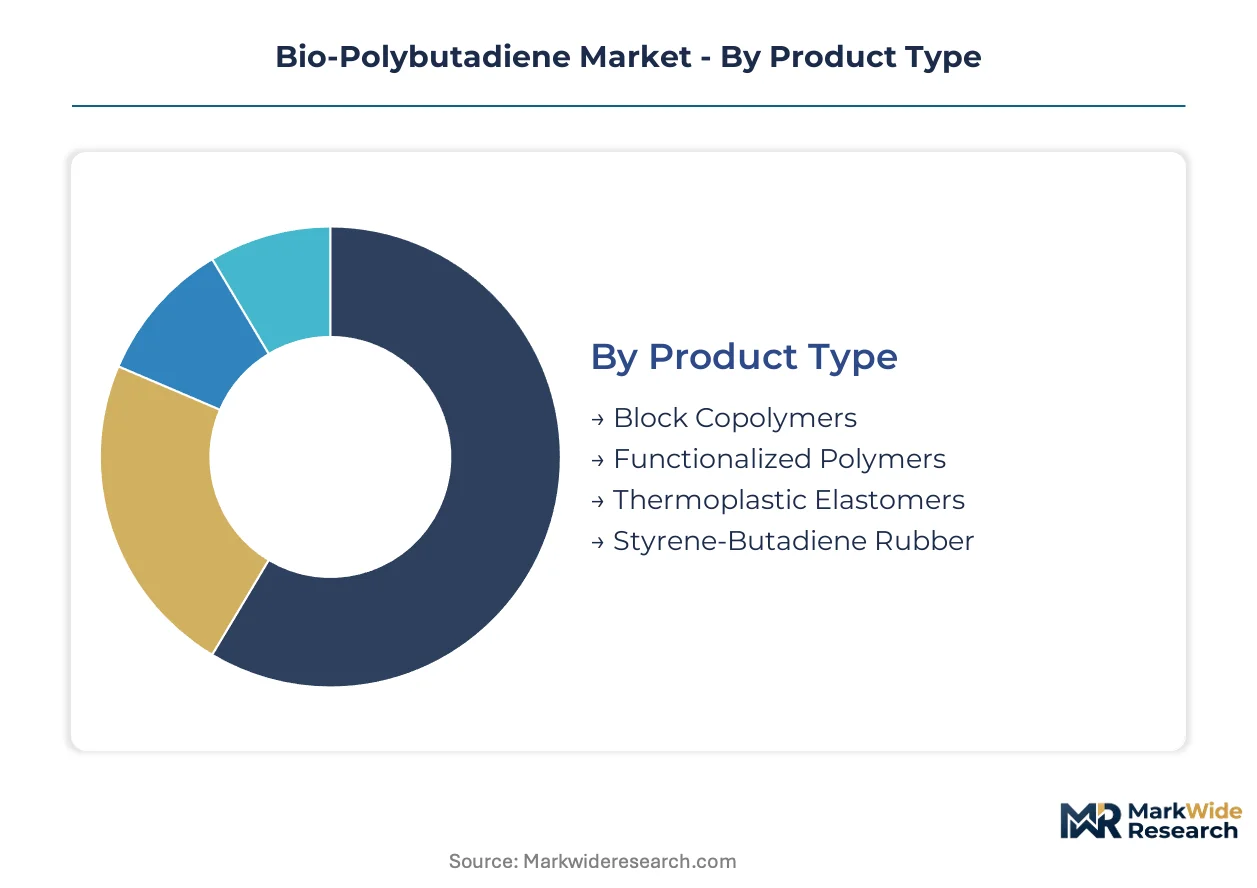
Bio-polybutadiene procurement decisions diverge sharply across product categories and end-use specifications. Tire compounders, medical device manufacturers, and consumer goods producers each impose distinct certification burdens that reshape supplier qualification timelines and feedstock sourcing strategies.
Product Type:
ISO 16620 biobased content verification applies unevenly across polymer architectures, with tire-grade materials facing the most stringent OEM audit protocols while thermoplastic variants navigate simpler recyclability standards.
- Block Copolymers:These materials combine hard polystyrene segments with rubbery polybutadiene blocks to deliver tunable elasticity and processability. Automotive under-the-hood applications in Germany and Japan concentrate demand, driven by vibration-damping specifications from BMW and Toyota procurement teams that now require documented renewable carbon percentages.
- Functionalized Polymers:Grafted polar groups—typically maleic anhydride or silane derivatives—enhance silica filler compatibility in low-rolling-resistance tire compounds. High-cis grades with 90-98% cis-1,4 content command premium positioning as Bridgestone and Michelin accelerate qualification of bio-based alternatives for performance tread formulations.
- Thermoplastic Elastomers:Vulcanization-free processing enables closed-loop recycling for golf ball cores and ergonomic consumer goods. Golf equipment manufacturers in the US Midwest favor these materials for simplified regrind operations.
- Styrene-Butadiene Rubber:Blending workhorse for tire sidewalls and industrial belting where cost efficiency outweighs biobased percentage targets. Volume concentration persists in legacy automotive supply chains with slower Scope 3 transition timelines.
Leading the category by volume: Styrene-Butadiene Rubber. Growing fastest: Functionalized Polymers.
Application:
Cost tier stratification separates aerospace qualification premiums from automotive volume plays and consumer goods margin compression.
- Automotive:Tire treads, sidewalls, and suspension bushings absorb the majority of bio-polybutadiene volume. Southern German production clusters adjacent to polymer R&D centers concentrate mixing operations for BMW, Mercedes-Benz, and Porsche supply chains.
- Consumer Goods:Golf ball cores, footwear midsoles, and ergonomic grips exploit thermoplastic processability. Sporting goods manufacturers in Ohio and Indiana seek localized supply to bypass coastal logistics bottlenecks.
- Aerospace:Seals, gaskets, and vibration isolation components for commercial aircraft require FAA-compliant flame resistance and outgassing specifications. Boeing and Airbus tier-two suppliers face extended 24-36 month qualification cycles.
- Medical Devices:Catheters, tubing, and drug-delivery components demand USP Class VI biocompatibility and ISO 10993 testing. FDA 510(k) pathways constrain feedstock variability more tightly than industrial applications.
Highest margin capture: Aerospace. Steepest expansion trajectory: Automotive.
End User:
Customer type determines whether bio-polybutadiene flows through specification-driven direct contracts or price-sensitive distribution channels.
- OEMs:Automotive and tire manufacturers with Scope 3 disclosure mandates source directly from biorefinery partners. Toyota and Honda procurement teams in Japan embed ISO 16620 verification into supplier scorecards alongside rolling resistance metrics.
- Manufacturers:Compounders and processors blending base polymers with fillers and curatives. US Midwest tire production hubs favor regional bio-polybutadiene supply to minimize inbound freight exposure.
- Distributors:Inventory-bearing intermediaries serving smaller compounders without direct biorefinery relationships. Margin pressure intensifies as naphtha-derived alternatives retain cost advantages at smaller volumes.
- Retailers:End-product channels for consumer goods with limited polymer specification influence. Biobased content marketing claims depend on upstream manufacturer certifications.
Contract value concentration: OEMs. Fastest procurement policy evolution: Manufacturers.
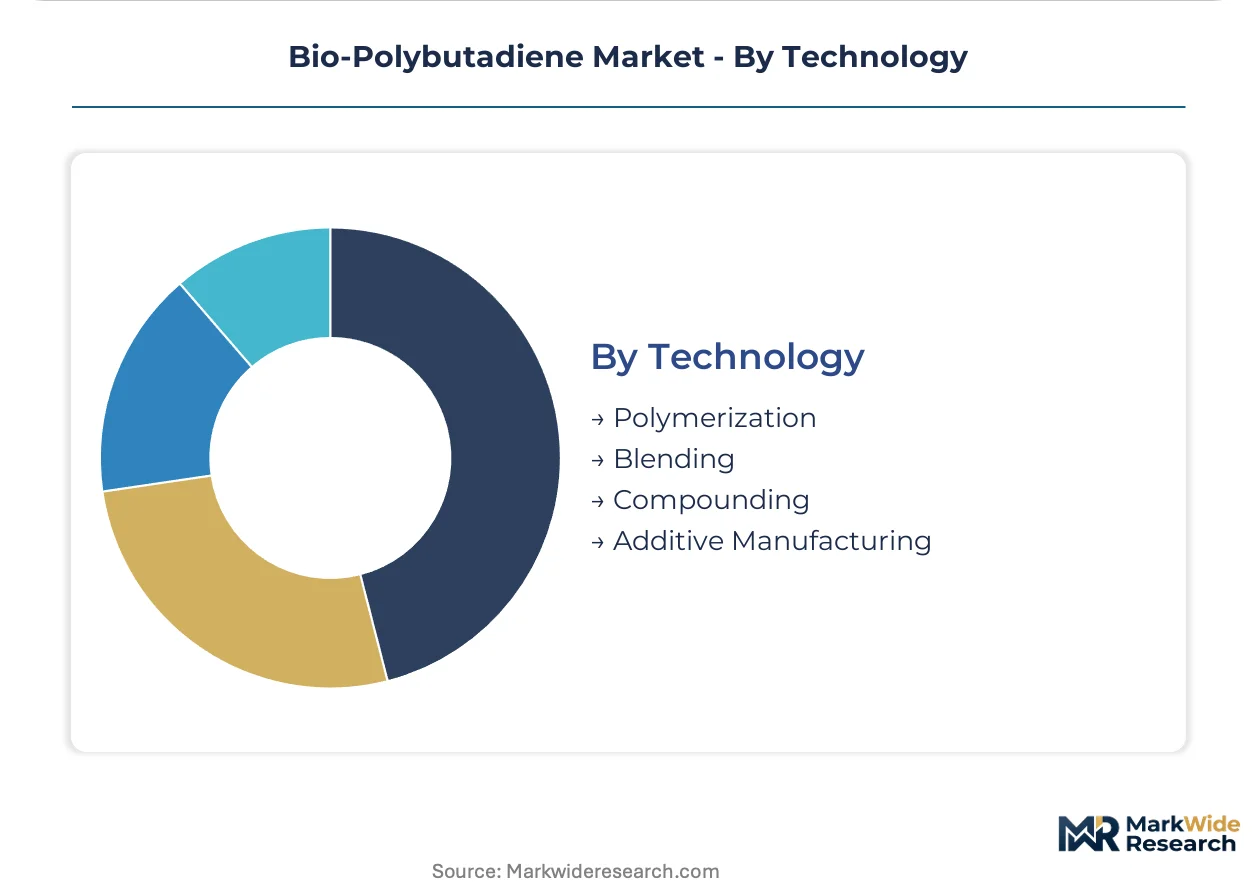
Technology:
Supply concentration in catalytic dehydrogenation expertise favors polymerization specialists over downstream processors.
- Polymerization:Precision fermentation and biomass gasification routes to butadiene monomer, followed by Ziegler-Natta or anionic coordination polymerization. Arlanxeo and Zeon Corporation anchor European and Japanese supply security for high-cis grades.
- Compounding:Masterbatch preparation with carbon black, silica, and curative packages. Automated mixing lines in Ohio and Indiana require tight Mooney viscosity ranges of 40-70 ML that renewable pathways struggle to achieve consistently.
- Blending:Physical combination with natural rubber, SBR, or EPDM to balance cost and performance. Standard practice in tire manufacturing where biobased percentage targets remain secondary to wear and traction specifications.
- Additive Manufacturing:Emerging powder-bed and extrusion-based methods for prototyping and low-volume production. Material qualification gaps limit aerospace and medical adoption despite design flexibility advantages.
Capital absorption leader: Polymerization. Fastest process improvement: Compounding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in southern Germany and Japan's coastal industrial corridors concentrate bio-polybutadiene demand through tire manufacturing clusters adjacent to automotive OEM headquarters. These zones channel investment into fermentation-based butadiene pathways as Scope 3 disclosure mandates tighten procurement specifications.
Germany
BMW and Mercedes-Benz procurement teams enforce biobased percentage targets in supplier scorecards, compressing qualification timelines for renewable elastomers. REACH registration requirements under ECHA tighten petrochemical content limits in tire formulations. The Stuttgart-Munich corridor anchors mixing operations for premium tire compounders serving southern German automotive hubs.
Japan
Toyota and Honda supply chains accelerate procurement of high-cis polybutadiene as METI's bio-economy roadmap mandates ISO 16620-aligned verification. JIS standards for biobased content measurement create enforceable thresholds for domestic tire exports. The Nagoya-Osaka industrial belt concentrates polymer R&D centers adjacent to tire production facilities.
United States
EPA renewable fuel standards shape feedstock qualification pathways for bio-based polymer producers seeking tire industry contracts. The Ohio-Indiana tire cluster favors regional bio-polybutadiene supply to minimize inbound freight exposure from coastal import terminals. Midwest compounders automate mixing lines requiring tight Mooney viscosity ranges that renewable pathways are refining.
China
Sinopec and domestic tire manufacturers trial biomass gasification routes under national dual carbon goals targeting petrochemical intensity reduction. GB standards for biobased content measurement are aligning with ISO frameworks to enable export qualification. The Yangtze River Delta concentrates synthetic rubber production capacity serving both domestic automotive OEMs and export markets.
South Korea
Hyundai and Kia sustainability procurement teams audit supplier fermentation pathways for Scope 3 emission disclosures in tire supply chains. The national chemical regulator enforces biobased content labeling requirements aligned with emerging ISO protocols. The Ulsan-Busan corridor anchors tire manufacturing clusters serving domestic automotive production and regional export demand.
Bio-Polybutadiene Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fermentation technology developers capturing premium positioning while petrochemical incumbents leverage existing butadiene infrastructure. The market exhibits tiered concentration: integrated polymer producers with biomass gasification capabilities occupy the top tier, specialty chemical houses with functionalization expertise sit in the middle, and regional compounders without direct biorefinery relationships populate the base. Three strategic archetypes dominate: upstream feedstock controllers securing renewable butadiene supply, midstream polymerization specialists achieving high-cis purity standards, and downstream compounders integrating bio-content into approved tire formulations. Competitive moves center on backward integration into fermentation capacity and strategic partnerships with automotive OEMs for qualification pipeline access.
Within the integrated polymer tier, Arlanxeo and Lanxess AG exemplify European anchors leveraging butadiene expertise for renewable elastomer supply security, while Zeon Corporation represents Japanese specialization in high-cis purity standards. These three occupy positions that bridge conventional petrochemical knowledge with emerging biomass pathways, anchoring regional supply chains as tire manufacturers compress feedstock transition timelines.
| Leading Market Players |
|---|
| Evonik Industries |
| Lanxess AG |
| Kuraray Co., Ltd. |
| Sinopec |
| LG Chem |
| Genomatica |
| Arlanxeo |
| Versalis |
| Zeon Corporation |
| Others |
Value Chain & Pricing Dynamics
Petrochemical incumbents with sovereign-backed financing in Germany and Japan anchor supply discipline, compressing spot-market volatility while enforcing long-term offtake premiums for bio-based alternatives. Their capital reserves buffer agricultural feedstock swings, translating fermentation yield uncertainty into contract-price stability for tire compounders.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with compounders paying markups for bio-polybutadiene delivered within 30-day windows versus standard 90-day fermentation batches. Three-tier pricing structure across high-cis purity grades, functionalized variants, and standard blends reflects ISO 16620 certification levels and silica compatibility testing completion. Cost compression in standard-grade tiers is intensifying because naphtha-derived alternatives retain volume leverage at smaller compounders. Tier-one tire OEMs show least price sensitivity, while regional distributors serving mid-size processors face margin erosion from dual-sourcing requirements.
Supply Chain Analysis
Domestic-content mandates under Japan's METI bio-economy roadmap and proposed EU localization rules are reshaping sourcing patterns, compelling tire manufacturers to qualify regional fermentation partners over Asian imports. Supply concentrates in Germany, Japan, and the US Midwest, with emerging capacity in South Korea's Ulsan corridor. Feedstock dependencies center on Brazilian sugarcane ethanol, US corn starch, and European wheat straw. Single-source vulnerability runs through catalytic dehydrogenation engineering talent pools. Distribution runs through direct biorefinery-to-mixer contracts for OEMs, with regional distributors serving smaller compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity bottlenecks prop pricing power, as qualified bio-polybutadiene supply trails automotive OEM procurement mandates by 18-24 months.
For Market Incumbents: Hedge against feedstock volatility through backward integration into Brazilian and US agricultural supply bases. Arlanxeo and Lanxess AG should lock multi-year sugarcane ethanol offtakes before commodity cycles tighten. Defend high-cis purity positioning by accelerating Ziegler-Natta catalyst R&D, as emerging fermentation players threaten technical parity. For New Entrants and Emerging Players: Precision fermentation technology offers the clearest wedge, particularly for thermoplastic elastomer variants where vulcanization-free processing commands recyclability premiums. Target Ohio and Indiana tire clusters with localized supply pitches emphasizing freight cost elimination. Pursue golf equipment and consumer goods verticals where qualification cycles compress to 6-12 months versus automotive tiers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European compounders with stranded petrochemical assets and renewable retrofit potential. Monitor fermentation yield breakthroughs at pilot scale as the inflection signal for cost-parity timing. Long-term viability hinges on 5-10 year automotive platform standardization windows, with bio-polybutadiene content locked into BMW and Mercedes-Benz supplier scorecards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive Brazilian sugarcane ethanol access insulates Arlanxeo from commodity price swings. |
| Long-term Supply Agreement with OEMs | Bridgestone and Michelin procurement teams prioritize qualified bio-based suppliers for Scope 3 compliance. |
| Joint Venture for Fermentation Scale-Up | Genomatica partnerships accelerate pilot-to-commercial pathways for biomass-derived butadiene. |
| Green Manufacturing Transition | ISO 16620 certification enables premium positioning in BMW and Toyota sustainability scorecards. |
| Capacity Expansion in US Midwest | Ohio and Indiana proximity captures direct-to-mixer logistics advantages for regional tire clusters. |
Study Parameters
Trade databases, ECHA REACH registration filings, and automotive OEM sustainability disclosures formed the secondary backbone, cross-referenced with primary interviews across tire compounder procurement leads, biorefinery plant managers, and polymer R&D directors. Bottom-up volume estimates triangulated against top-down market sizing from customs data and industry association reports.
Historical trendline analysis tracked fermentation yield improvements and catalytic dehydrogenation cost curves across the projection horizon. Segmentation modeling incorporated grade tier, end-use application, regional production hub, and certification status dimensions. CAGRs derived from elasticity-adjusted demand projections tied to automotive production forecasts and Scope 3 disclosure mandate timelines.
Several conditions sit outside the modeled scope, including abrupt agricultural commodity shocks, breakthroughs in alternative elastomer chemistries, and regulatory delays in biobased content verification frameworks. Forecasts reflect documented assumptions on fermentation scale-up economics and OEM qualification pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Polyamide-Imide (PAI) Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
PA66 Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market