

Marine-grade Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
Marine-grade Polyurethane Market Insights
The gap between premium and commodity tiers is broadening in marine-grade polyurethane as offshore operators demand certified long-cycle coatings while recreational craft buyers prioritize cost. BASF anchors its position through backward integration into isocyanate feedstocks, while Covestro differentiates via high-performance aliphatic systems for superyacht finishes. Hempel competes on geographic density, leveraging its service network across Nordic shipyards.
Marine-grade polyurethane denotes formulated polymer systems engineered to resist saltwater hydrolysis, ultraviolet degradation, and mechanical fatigue in maritime environments, typically specified with Shore hardness ranges from 40A to 75D and tensile strength above 15 MPa for elastomer grades. Coatings leads product type demand due to reapplication cycles on working vessels, while rigid foam for buoyancy aids represents the fastest-expanding application segment as offshore platform construction intensifies. Elastomers command margin concentration because of custom compounding requirements and limited qualified suppliers.
REACH in Europe, EPA VOC rules in the United States, and China's MEE emission standards are converging to restrict solvent-based formulations, redirecting R&D investment toward compliant waterborne and high-solids alternatives. Classification societies including DNV and Lloyd's Register now embed polyurethane performance into type-approval protocols, raising barriers for uncertified entrants. Stakeholders must monitor regulatory divergence between major maritime jurisdictions to avoid stranded formulation investments.
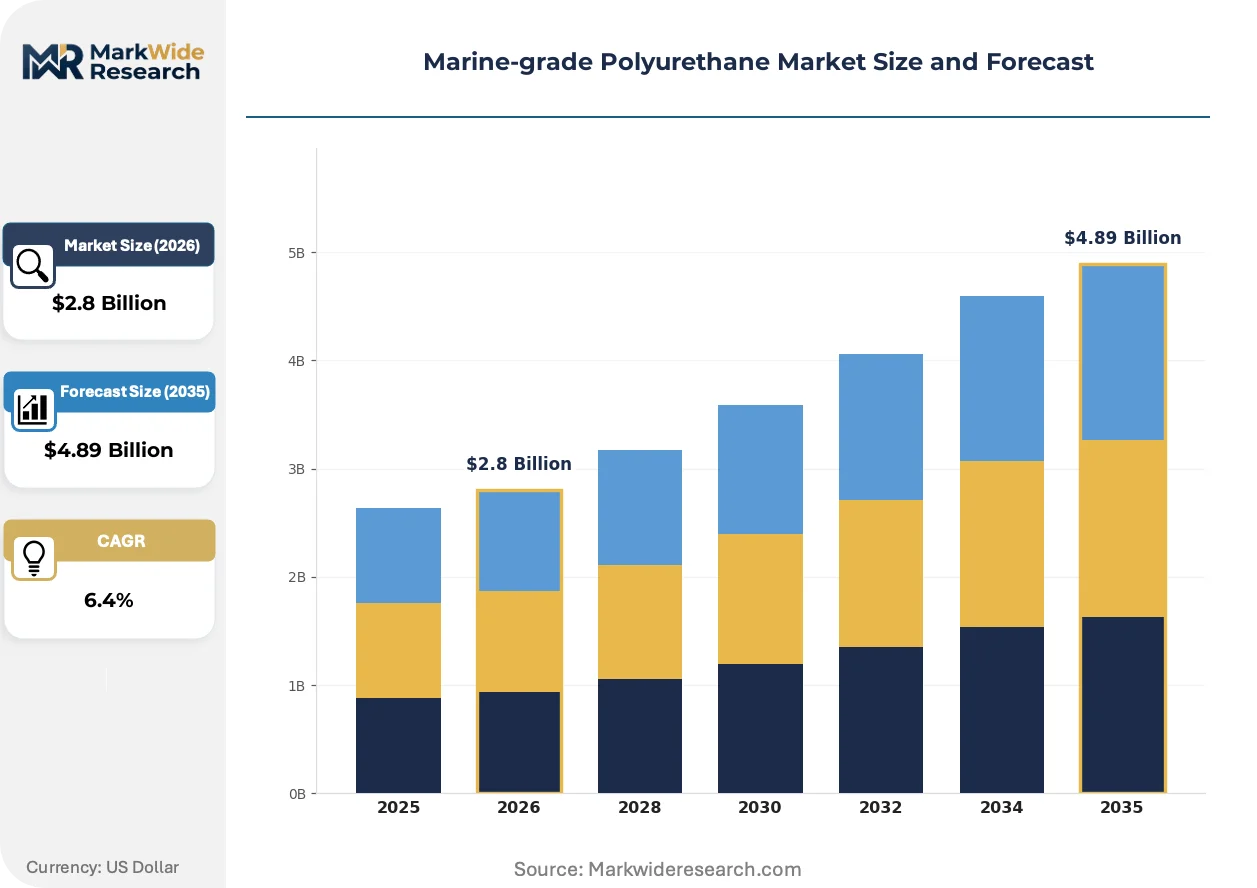
Market Dynamics
Offshore platform operators are compressing reapplication cycles for protective coatings while demanding certified long-cycle performance, forcing suppliers to bifurcate R&D investment between premium aliphatic systems and cost-optimized alternatives.
Growth Catalysts
- Offshore buoyancy systems:Floating wind and oil platform construction is accelerating rigid foam specifications for flotation modules. Norway's Equinor and Denmark's Ørsted are embedding polyurethane specifications into tender documents.
- REACH Phase 2 restrictions:ECHA's 2023-2025 VOC limits on solvent-based marine coatings are redirecting formulation spend toward waterborne polyurethanes in Hamburg, Rotterdam, and Singapore shipyards.
- DNV type-approval protocols:Classification society certification for elastomer fenders and deck coatings is locking out uncertified competitors from Nordic and Korean newbuild contracts.
Market Restraints
- MDI feedstock concentration:European and Chinese isocyanate supply is controlled by a handful of integrated petrochemical complexes, exposing coaters to price volatility and allocation risk during turnarounds.
- Aliphatic isocyanate scarcity:HDI and IPDI supply for non-yellowing yacht finishes is concentrated in German and Japanese chemical parks, creating bottlenecks for superyacht applicators in Italy and the Netherlands.
- Epoxy substitution in ballast tanks:Epoxy-amine systems retain cost advantage in cargo hold and tank applications where UV exposure is minimal, limiting polyurethane penetration in bulk carrier segments.
Strategic Opportunities
- India shipyard expansion:Cochin Shipyard and Mazagon Dock are expanding drydock capacity under the government's Maritime India Vision 2030, creating first-mover advantage for compliant coating suppliers.
- EU Green Deal carbon border adjustments:CBAM implementation from 2026 will penalize high-emission coating imports, rewarding European producers with integrated low-carbon isocyanate production.
- Digital formulation platforms:AI-driven resin matching and predictive curing analytics are converging with robotic spray application to reduce material waste and labor hours in Korean and Chinese newbuild yards.
Industry Challenges
- Certified applicator scarcity:Lloyd's Register and DNV surface preparation and spray certification programs have backlogs exceeding 18 months in Southeast Asian ship repair hubs, delaying project handovers.
- Legacy solvent inventory stranding:Coatings manufacturers holding pre-REACH formulations face write-downs as ECHA authorization deadlines approach, forcing accelerated reformulation timelines without guaranteed customer acceptance.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine-grade Polyurethane Market Trends and Innovations
Reformulation chemistry, regulatory compliance architecture, and procurement digitization are simultaneously reshaping how marine polyurethane systems are developed, specified, and purchased across vessel construction and maintenance cycles.
Waterborne 2K polyurethane technology is overtaking conventional high-solids solvent systems in European and East Asian shipyard specifications. Commercial ferry operators in the Baltic and container lines calling at Rotterdam are mandating waterborne deck coatings to meet ECHA VOC limits and port authority emission protocols. This transition is compressing margins for mid-tier formulators lacking captive resin production, while integrated suppliers capture specification control through guaranteed supply continuity.
REACH authorization and restriction processes are forcing molecular redesign of biocidal additives and isocyanate hardeners used in antifouling and topcoat layers. ECHA's 2024-2026 substance evaluation roadmap is eliminating several tin-based catalysts and certain aromatic isocyanates from marine formulations, compelling suppliers to validate alternative curing chemistries. Nordic shipyards are responding fastest, embedding ECHA-compliant material declarations into supplier scorecards ahead of Mediterranean and Asian competitors.
Shipowners are unbundling coating procurement from newbuild construction contracts, establishing direct relationships with certified applicators and material suppliers. Container lines based in Hamburg and Copenhagen are negotiating multi-year coating service agreements separate from yard contracts, shifting specification authority from shipbuilders to fleet technical managers. This disintermediation is most pronounced in the cruise and ferry segments, where Carnival Corporation and Viking Line are centralizing global coating standards across their fleets.
Marine-grade Polyurethane Market Segmentation
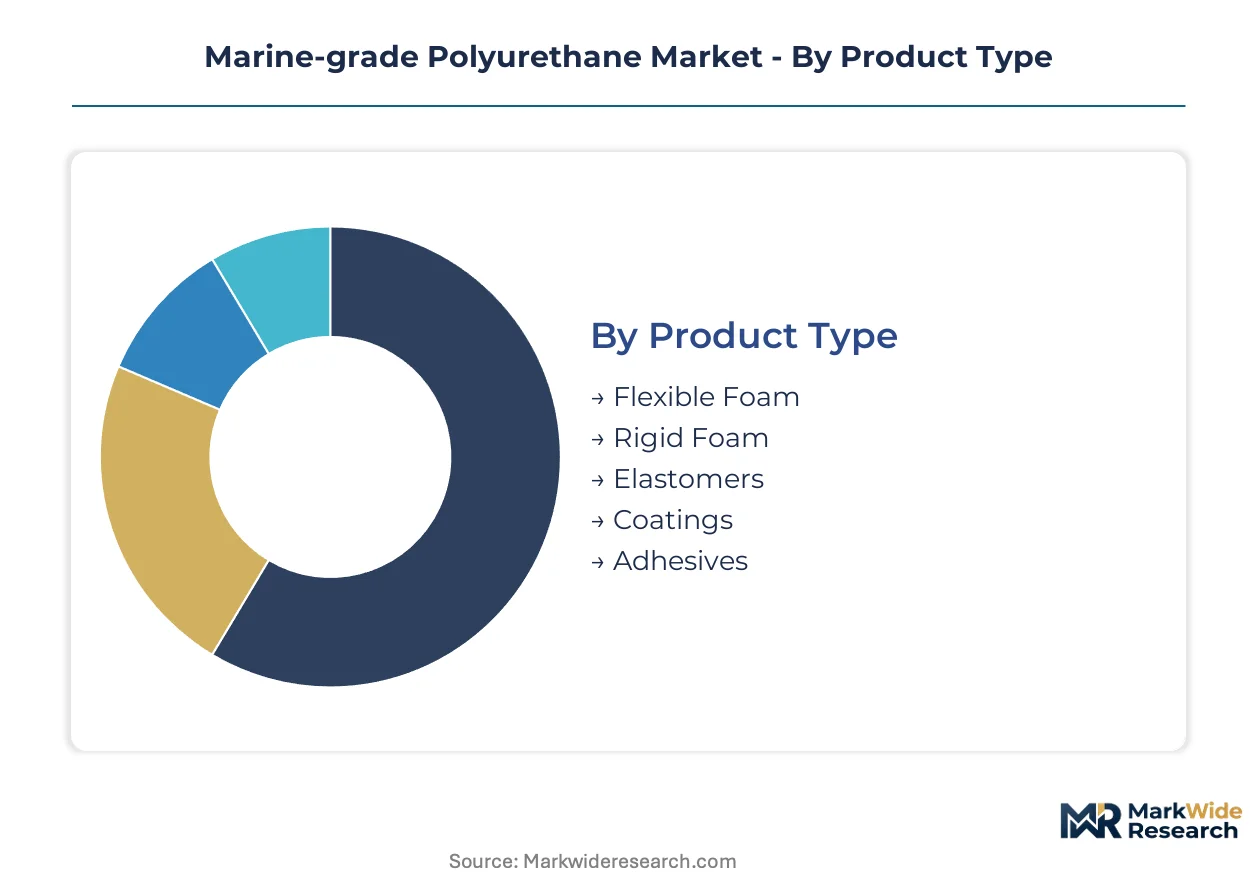
Marine-grade polyurethane specifications diverge sharply between embedded structural components and standalone protective systems, driving distinct procurement patterns across vessel construction cycles. Understanding where each segment sits along this integration spectrum clarifies margin structures and reformulation priorities for suppliers.
Product Type:
Coatings and foams occupy opposite ends of the integration spectrum—surface-applied systems versus embedded structural materials—with elastomers bridging both modes.
- Coatings:Applied films formulated with aliphatic or aromatic isocyanate hardeners, specified for reapplication intervals on working vessels. Demand clusters around Hamburg and Rotterdam ferry operators compressing maintenance windows under ECHA VOC protocols.
- Rigid Foam:Closed-cell polyurethane systems with density ranges of 32-80 kg/m³, specified as embedded buoyancy modules. Norway's Equinor and Denmark's Ørsted are embedding rigid foam specifications into North Sea floating wind tender documents.
- Flexible Foam:Open-cell cushioning materials for seating and insulation applications in passenger vessels.
- Elastomers:Cast or thermoplastic systems with Shore hardness from 40A to 75D, serving both fender applications and embedded deck coverings.
- Adhesives:Structural bonding systems for composite hull assembly and panel lamination in shipyards.
Coatings leads volumes today; rigid foam is gaining share fastest.
Formulation:
Cost tier separation runs deepest here—aliphatic systems command premium positioning for UV-exposed finishes while aromatic formulations serve protected structural applications.
- Aliphatic:HDI and IPDI-based systems engineered for non-yellowing performance in superyacht finishes and premium deck coatings. Supply bottlenecks at German and Japanese chemical parks constrain Italian and Dutch applicators.
- Aromatic:MDI-TDI formulations for submerged or UV-shielded applications where color stability is secondary to mechanical performance. Chinese shipyards specify aromatic systems for bulk carrier ballast protection.
- Thermoplastic:Melt-processable elastomers for extruded seals and gaskets in marine environments.
- Cast Elastomers:Two-component liquid systems cured in molds for fender and bumper fabrication.
- Prepolymers:Partially reacted isocyanate-terminated resins enabling customized cure profiles for large-scale deck casting.
Aromatic formulations dominate tonnage; aliphatic systems expand most quickly on specification upgrades.
Application:
Application segments map directly to vessel lifecycle phases—newbuild construction versus maintenance cycles—with divergent certification requirements.
- Protective Coatings:Film-forming systems for hull, deck, and superstructure protection against saltwater corrosion and UV degradation. Baltic ferry operators mandate waterborne specifications under port authority emission protocols.
- Buoyancy Aids:Flotation modules for offshore platforms, life rafts, and rescue equipment. Floating wind construction in the North Sea and South China Sea is accelerating rigid foam specifications.
- Boat Decking:Elastomeric surface coverings for slip resistance and impact absorption in recreational and commercial craft.
- Dock Construction:Fender systems and pile wraps for marine infrastructure protection.
- Sealants:Flexible joint fillers for hull-deck interfaces and window glazing in passenger vessels.
Protective coatings maintains the largest installed base; buoyancy aids shows the steepest expansion trajectory.
End User:
Customer type determines specification authority—shipbuilders versus fleet operators—with procurement centralization reshaping supplier relationships.
- Shipbuilders:Newbuild construction yards specifying materials under classification society protocols. Korean and Chinese yards are embedding DNV and Lloyd's Register certification requirements into supplier contracts.
- Offshore Platforms:Oil, gas, and wind energy operators demanding certified long-cycle performance for protective systems. Operators are unbundling coating procurement from construction contracts.
- Recreational Watercraft:Yacht and pleasure boat manufacturers prioritizing cost-optimized formulations over certified premium systems.
- Fishing Vessels:Commercial fleet operators with maintenance-focused purchasing patterns and price-sensitive specifications.
Shipbuilders consume the greatest volume; offshore platforms are driving the fastest specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces Germany in shipyard output volume, yet German chemical parks supply the aliphatic isocyanates that finish superyachts in Italian and Dutch yards. Regulatory divergence between ECHA's REACH Phase 2 and China's MEE emission standards is fragmenting formulation strategies across maritime clusters.
China
Yangtze River Delta shipyards in Shanghai and Nantong are expanding drydock capacity for bulk carriers and container vessels. MEE emission standards are pushing reformulation toward waterborne systems in these yards. Guangdong province's Pearl River Delta is concentrating rigid foam production for offshore buoyancy modules serving South China Sea wind projects.
Germany
Leverkusen and Ludwigshafen chemical complexes control HDI and IPDI supply for non-yellowing marine finishes. ECHA's 2024-2026 substance evaluation is eliminating tin-based catalysts from antifouling formulations. Hamburg's port authority mandates waterborne deck coatings for Baltic ferry operators under local emission protocols.
United States
Gulf Coast offshore platform construction in Texas and Louisiana is accelerating rigid foam specifications for flotation systems. EPA VOC rules are redirecting formulation investment toward high-solids alternatives in these yards. Houston's energy service cluster is embedding polyurethane performance standards into tender documents for floating wind projects.
Norway
Stavanger and Bergen offshore operators are compressing reapplication cycles for protective coatings on North Sea platforms. The country's national environmental regulator enforces strict volatile organic compound limits on solvent-based systems. Equinor's floating wind specifications are locking in rigid foam suppliers for hybrid platform construction.
South Korea
Ulsan and Geoje shipyards are embedding DNV type-approval requirements into supplier contracts for newbuild construction. The country's national chemical safety regulator aligns with REACH substance restrictions on aromatic isocyanates. Busan's repair hubs face certified applicator backlogs exceeding 18 months for Lloyd's Register spray programs.
Marine-grade Polyurethane Market Competitive Landscape
Top-tier vendors anchor premium aliphatic systems for superyacht and offshore platform specifications, while mid-tier formulators compete on cost-optimized aromatic formulations for bulk carrier segments. The vendor base stratifies across three archetypes: integrated petrochemical producers with captive isocyanate supply, specialized coating formulators with classification society certification, and regional applicators with shipyard service contracts. Competitive moves concentrate on backward integration into feedstock production and geographic expansion through certified service network density.
Among integrated chemical producers, BASF and Covestro exemplify the upstream-control archetype through their positions in isocyanate manufacturing. AkzoNobel, PPG Industries, and Hempel occupy the specialized formulator tier, anchoring their competitive positions through DNV and Lloyd's Register certification protocols. 3M and Sika represent the applied materials specialists, sitting within segments where adhesive and sealant specifications intersect with marine construction cycles.
| Leading Market Players |
|---|
| 3M |
| BASF |
| AkzoNobel |
| Jotun |
| PPG Industries |
| Hempel |
| Nippon Paint Marine Coatings |
| Sika |
| Covestro |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up coating specialists have consolidated regional applicator networks across Hamburg, Rotterdam, and Singapore, tightening pricing discipline while embedding long-term service contracts that lock out independent formulators from premium specification tiers.
Pricing Analysis
Bundled coating-plus-application contracts dominate superyacht and offshore platform segments, while unbundled material-only sales persist in bulk carrier maintenance cycles. Three-tier pricing structure across premium aliphatic systems, standard aromatic formulations, and economy-grade recoats separates certified long-cycle performance from commodity reapplication. Pricing pressure stems from MDI feedstock volatility at German and Chinese chemical complexes, compressing margins for non-integrated formulators. Recreational craft buyers exhibit highest price sensitivity, while Equinor and Ørsted procurement teams prioritize certified performance over unit cost.
Supply Chain Analysis
Certification gating through DNV and Lloyd's Register protocols constrains qualified supplier pools, concentrating specification authority among formulators with established type-approval track records. Isocyanate production concentrates in Germany, China, and Japan, with HDI and IPDI supply anchored in Leverkusen and Ludwigshafen chemical parks. Raw material dependencies center on MDI, polyols, and specialty aliphatic hardeners. Single-source vulnerability runs through Japanese IPDI production for Italian and Dutch superyacht finishers. Distribution runs through shipyard-integrated service networks and direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's 2024-2026 substance evaluation roadmap accelerates reformulation demand and locks in premium pricing for compliant suppliers.
For Market Incumbents: Deploy backward integration into captive isocyanate production to defend margin position against feedstock volatility at Chinese and German chemical complexes. Secure DNV type-approval extensions for waterborne 2K systems ahead of Mediterranean yard adoption. Consolidate certified applicator networks in Southeast Asian repair hubs to capture unbundled procurement flows from container lines. For New Entrants and Emerging Players: REACH Phase 2 restrictions in Europe open a window for compliant waterborne specialists to capture share from solvent-based incumbents facing inventory stranding. Target India's Maritime India Vision 2030 expansion at Cochin Shipyard and Mazagon Dock as the most penetrable geography. Lead with AI-driven formulation platforms that reduce material waste for Korean and Chinese newbuild yards. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier aromatic formulators without captive resin production or classification society certification. Five-to-ten year viability hinges on regulatory compliance moats rather than scale economics. Monitor Lloyd's Register and DNV certification backlogs as the signal indicating specification authority concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstocks | BASF and Covestro anchor competitive position through captive MDI and aliphatic hardener supply. |
| Waterborne 2K Formulation Transition | ECHA VOC limits in Hamburg and Rotterdam shipyards redirect R&D spend from solvent systems. |
| DNV Type-Approval Certification Investment | Classification society protocols lock out uncertified competitors from Nordic and Korean newbuild contracts. |
| Certified Applicator Network Expansion | Hempel leverages geographic density across shipyards to capture unbundled fleet procurement. |
| AI-Driven Curing Analytics Integration | Predictive platforms reduce labor hours and material waste in Korean and Chinese construction yards. |
Research Methodology
Bottom-up shipyard consumption modeling reconciled against top-down isocyanate production tracking forms the analytical core of this study. Primary interviews with coating formulators, shipyard procurement directors, classification society technical auditors, and offshore platform engineering teams informed demand segmentation. Secondary validation drew from ECHA substance evaluation databases, DNV type-approval registries, customs trade flows for isocyanate feedstocks, and SEC filings from integrated chemical producers. Triangulation between vessel construction schedules and raw material consumption patterns ensured cross-verification of volume estimates.
Historical trendline analysis of coating reapplication cycles and offshore platform installation rates established baseline growth parameters. Segmentation dimensions modeled include formulation chemistry tier, application type, vessel class, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections across the analysis window. Industry-specific forecast inputs incorporated floating wind tender pipelines from Equinor and Ørsted, plus shipyard capacity expansion timelines under India's Maritime India Vision 2030.
Revisions become necessary when ECHA authorization timelines accelerate, Chinese MEE standards diverge from REACH substance restrictions, or MDI supply disruptions at major chemical complexes materialize. A model refresh is warranted upon material change in classification society certification protocols or offshore platform procurement unbundling velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.