
 Hydrogen Purification Units Market | 2026-2036
Hydrogen Purification Units Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Purification Units Market Insights
Europe's F-Gas Regulation is pivoting industrial gas suppliers toward membrane and electrochemical alternatives that eliminate fluorinated refrigerants from cryogenic loops. Linde leverages its cryogenic distillation heritage to anchor large-scale refinery projects across the Gulf Coast. Air Products competes through proton-exchange membrane integration that sustains pipeline-grade purity at lower energy intensity. Nel Hydrogen specializes in compact, modular architectures that dominate on-site electrolysis-to-purification workflows.
Hydrogen purification units remove contaminants—carbon monoxide, carbon dioxide, nitrogen, moisture, and sulfur compounds—from hydrogen-rich process streams to achieve purity thresholds typically exceeding 99.97 percent for fuel cell and semiconductor applications. Pressure swing adsorption currently occupies the majority of installed base in refinery and chemical production settings due to mature zeolite chemistry and decades of operational validation. Membrane separation is displacing legacy systems in smaller-scale and modular deployments where capital flexibility and footprint constraints override marginal efficiency losses. Cryogenic distillation retains margin concentration in ultra-high-purity electronics applications where parts-per-billion contamination control justifies energy-intensive separation.
The EPA enforces hydrogen quality standards for fuel cell vehicles under Clean Air Act frameworks, while the EU AI Act and CSRD indirectly shape procurement by mandating supply-chain emissions transparency that favors low-carbon purification pathways. Japan's METI hydrogen roadmap and South Korea's MFDS pharmaceutical-grade gas standards further fragment certification requirements across export markets. Stakeholders must monitor regulatory divergence between pipeline hydrogen specifications and fuel cell purity tiers to avoid stranded capital in multi-regional deployment strategies.
Market Dynamics
The hydrogen purification landscape is tightening around energy intensity differentials as electrolysis capacity scales and refinery operators face carbon border adjustment exposure. Technology selection now hinges on whether purity requirements justify cryogenic energy costs or whether membrane and pressure swing adsorption systems can meet evolving fuel cell specifications.
Growth Catalysts
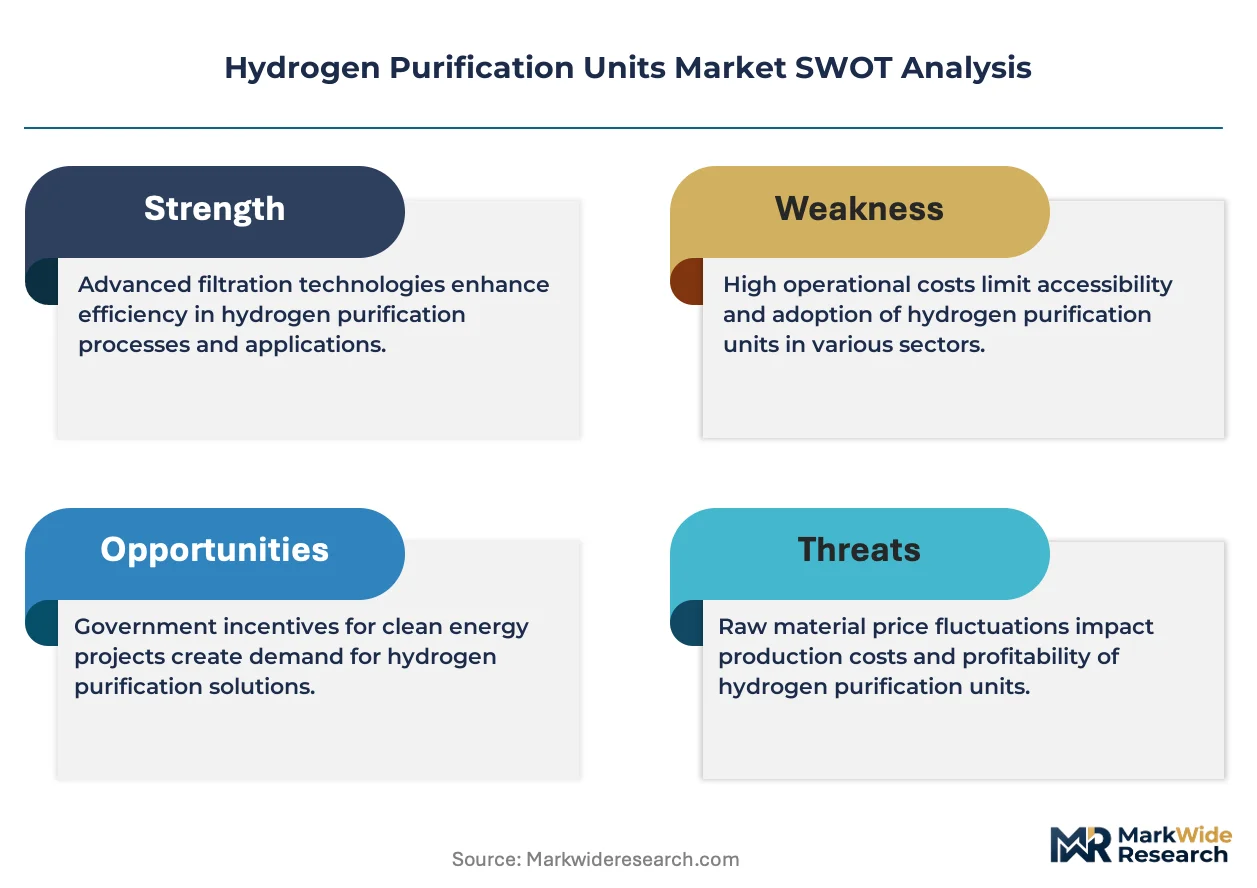
- EU Green Deal renewable hydrogen mandates:Binding targets for electrolytic hydrogen in industrial feedstocks are pulling high-purity system demand into German steel and Dutch chemical clusters.
- Pressure swing adsorption maturation:Decades of zeolite chemistry validation in refinery settings now supports rapid deployment for ammonia loop purge gas recovery.
- Middle East refinery expansion:Operators processing heavier crude slates are adding hydrogen purification capacity to maintain hydrocracker performance and product slate flexibility.
Market Restraints
- Palladium membrane cost volatility:Precious metal price swings in hydrogen-selective membrane fabrication compress margins for modular system suppliers.
- Cryogenic energy intensity:Ultra-high-purity electronics applications face margin pressure from electricity costs in distillation-based separation.
- F-Gas Regulation compliance burden:Europe's phasedown of fluorinated refrigerants forces cryogenic loop redesigns and extended qualification timelines.
Strategic Opportunities
- India electrolysis-to-purification integration:PLI scheme incentives for green hydrogen production create first-mover positioning for packaged PSA-membrane hybrid systems.
- Carbon capture coupling:CO2 separation from reformer off-gas streams enables dual-product revenue streams for purification operators.
- Pipeline-grade hydrogen certification:Emerging purity tiers for grid injection create specification gaps that electrochemical polishing can fill.
Industry Challenges
- Cryogenic technician scarcity:Specialized cold-box maintenance expertise concentrates in legacy industrial gas regions, constraining Middle East and Asia-Pacific deployment velocity.
- Multi-regional certification fragmentation:Divergent EPA fuel cell vehicle standards, EU CSRD supply-chain transparency mandates, and Japan METI hydrogen roadmaps force redundant qualification testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Purification Units Market |
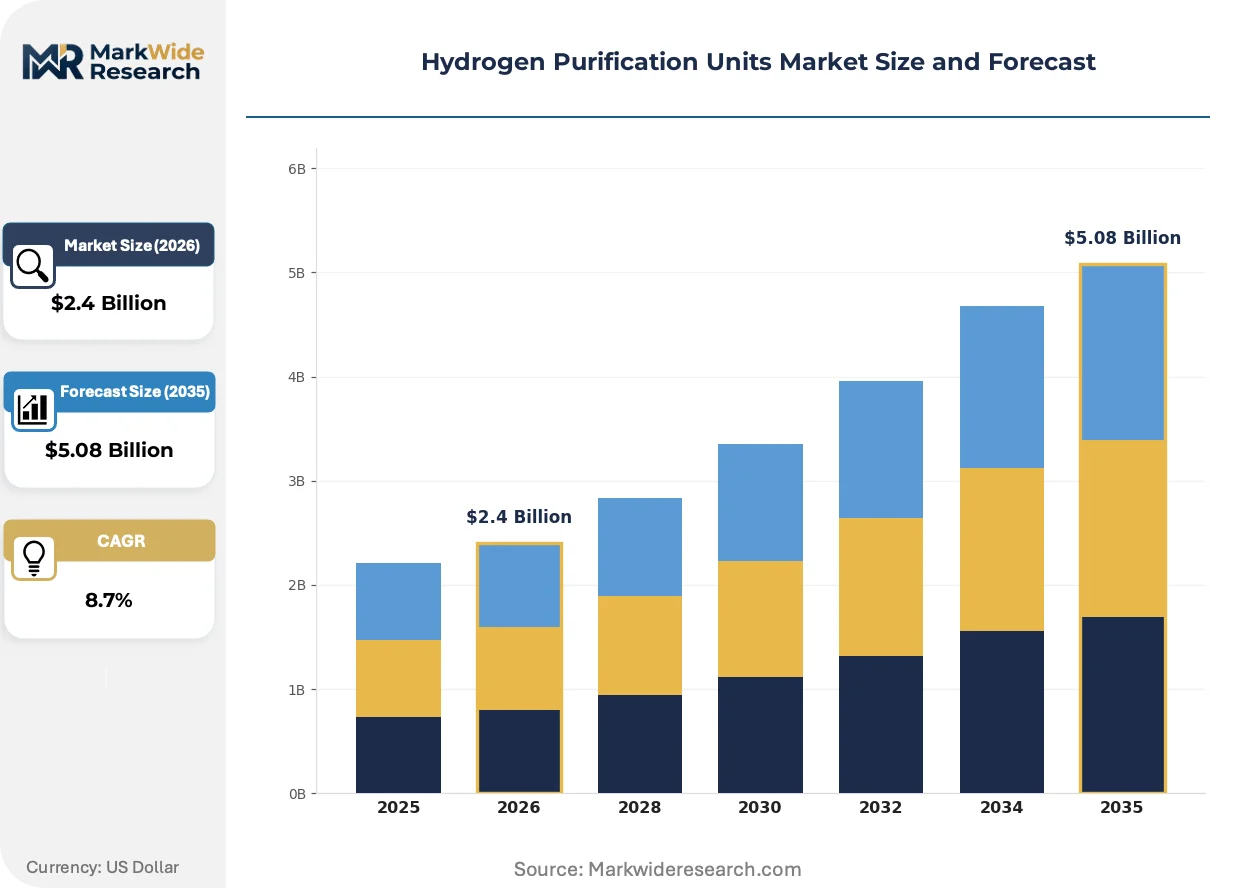
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pressure Swing Adsorption, Membrane Separation, Cryogenic Distillation, Electrochemical Separation Application: Refinery, Chemical Production, Fuel Cell Power Generation, Electronics End User: Industrial Gas Suppliers, Oil & Gas Companies, Power Generation Plants, Chemical Manufacturers Installation: On-site, Modular, Centralized, Portable |
| Companies Covered | Linde, Air Liquide, Air Products, Nel Hydrogen, Siemens Energy, McPhy, Chart Industries, Proton OnSite, HyGear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Purification Units Market Trends and Innovations
Automation and sensor integration are compressing the operational envelope for purification systems, while regulatory pressure on fluorinated compounds accelerates technology substitution. The competitive frontier is shifting toward predictive maintenance capabilities and modular architectures that reduce site-specific engineering.
Electrochemical hydrogen pumps are automating impurity rejection through proton-exchange membrane stacks that operate at ambient temperature without moving parts. Semiconductor fabs in South Korea and Taiwan are piloting these systems for sub-ppb moisture control. The technology is automating what previously required cryogenic distillation, compressing capital deployment timelines from months to weeks.
Europe's F-Gas Regulation is forcing refrigerant substitution in cryogenic hydrogen liquefaction loops, with ECHA guidance accelerating hydrofluorocarbon phaseout timelines. Industrial gas suppliers are redesigning cold-box architectures around helium or nitrogen Brayton cycles. The regulation is reshaping supplier R&D allocation, with membrane and adsorption alternatives capturing share in mid-purity applications previously served by distillation.
Refinery operators are unbundling purification from hydrogen production, contracting standalone PSA or membrane units as service-based rather than capex purchases. This procurement recalibration shifts technical risk to equipment vendors and compresses payback period requirements. The model is most visible on the US Gulf Coast, where merchant hydrogen suppliers are absorbing purification assets to guarantee offtake purity.
Hydrogen Purification Units Market Segmentation
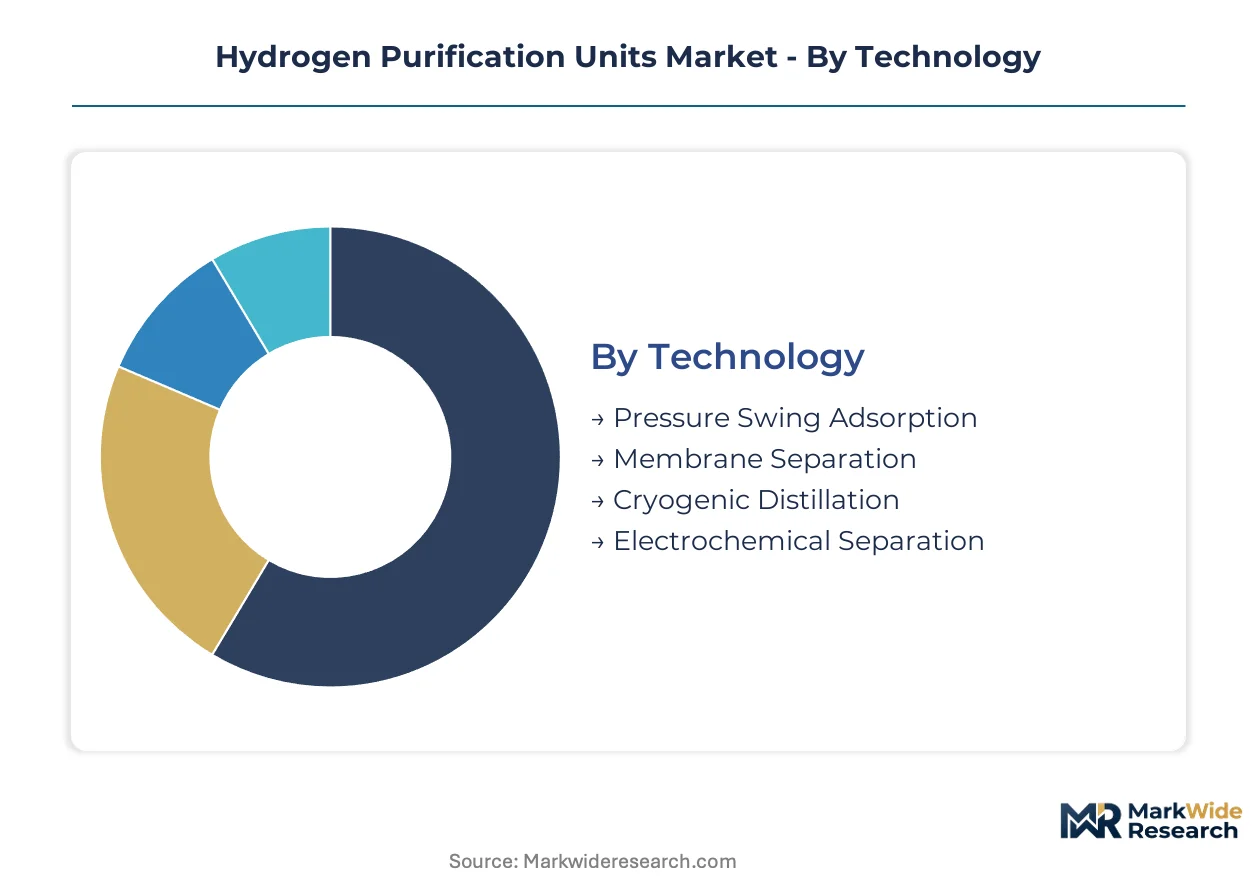
Technology selection in hydrogen purification hinges on purity thresholds, energy costs, and integration complexity. Each segment occupies distinct positions along the standalone-to-embedded spectrum, with implications for capital deployment and operational flexibility.
Technology:
Pressure swing adsorption and cryogenic distillation dominate standalone installations at refinery and electronics scales, while membrane and electrochemical systems embed directly into electrolysis skids and fuel cell power plants.
- Pressure Swing Adsorption:Zeolite-packed vessels cycle between adsorption and regeneration phases to strip CO2, CO, and nitrogen from reformer off-gas. Demand concentrates in German steel decarbonization clusters where ammonia loop purge gas recovery feeds electrolytic hydrogen blending. The technology's decades of operational validation support rapid deployment timelines for industrial gas suppliers.
- Membrane Separation:Palladium-alloy or polymer membranes selectively permeate hydrogen under pressure differentials, achieving 99.9% purity without thermal cycling. Middle East refinery operators favor compact membrane skids for hydrocracker hydrogen recovery where footprint constraints override marginal efficiency losses versus cryogenic alternatives.
- Cryogenic Distillation:Ultra-low-temperature fractionation separates hydrogen from helium and neon in electronics-grade production. South Korean semiconductor fabs sustain demand despite energy intensity penalties.
- Electrochemical Separation:Proton-exchange membrane stacks pump hydrogen ions against impurity gradients at ambient temperature. Nel Hydrogen integrates these units into containerized electrolysis systems for Dutch chemical cluster deployments.
Pressure swing adsorption leads volumes today; electrochemical separation is gaining share fastest.
Application:
Refinery and chemical production anchor current procurement, while fuel cell and electronics applications command premium pricing tiers based on contamination sensitivity.
- Refinery:Hydrocracker and hydrotreater operations consume hydrogen at scale, with purification units recovering unreacted hydrogen from purge streams. Gulf Coast operators unbundle purification as service-based contracts to merchant hydrogen suppliers.
- Chemical Production:Ammonia synthesis and methanol production require nitrogen-free hydrogen feedstock. Indian PLI scheme incentives accelerate green ammonia project development with integrated PSA-membrane hybrids.
- Fuel Cell Power Generation:Stationary and mobility fuel cells demand 99.97% purity with sub-ppm CO contamination. EPA Clean Air Act enforcement shapes procurement specifications for US vehicle deployment.
- Electronics:Semiconductor fabrication requires parts-per-billion moisture and oxygen control. Taiwan and South Korean fabs sustain cryogenic distillation demand despite F-Gas Regulation compliance burdens.
Refinery applications dominate current installed base; fuel cell power generation shows steepest expansion trajectory.
End User:
Industrial gas suppliers and oil & gas companies drive large-scale centralized investments, while chemical manufacturers and power generation plants favor modular or on-site architectures.
- Industrial Gas Suppliers:Linde and Air Products operate merchant hydrogen networks with embedded purification assets. These firms absorb technical risk through service-based pricing models on the US Gulf Coast.
- Oil & Gas Companies:Integrated majors processing heavier crude slates in Saudi Arabia and Kuwait expand hydrogen purification capacity to maintain hydrocracker performance.
- Power Generation Plants:Utility-scale electrolysis projects in Germany and the Netherlands integrate purification for grid injection compliance.
- Chemical Manufacturers:BASF and Dow Chemical specifications for ammonia and methanol feedstocks pull high-purity system demand into Rotterdam and Antwerp industrial clusters.
Industrial gas suppliers lead procurement volumes; chemical manufacturers are expanding fastest.
Installation:
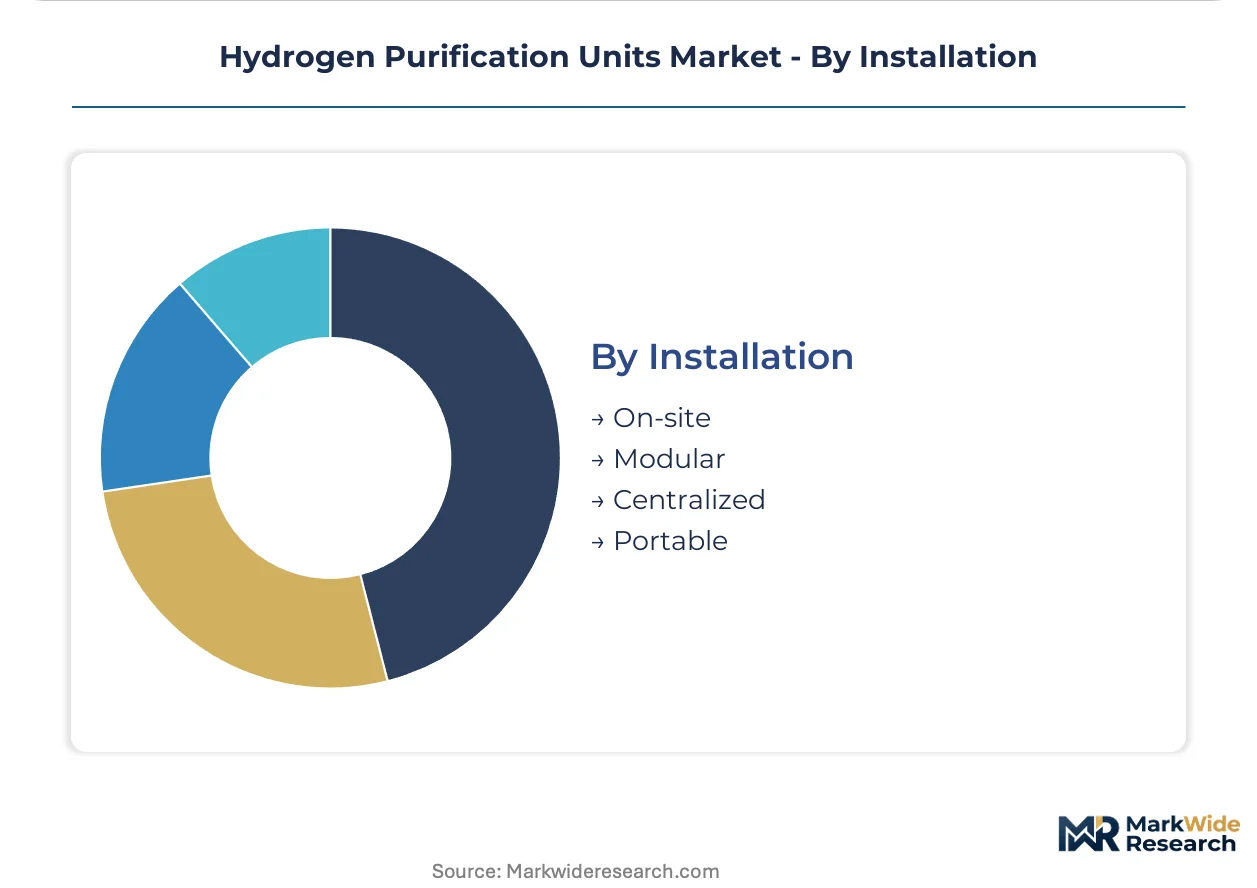
Centralized and on-site configurations reflect legacy industrial gas infrastructure, while modular and portable systems enable distributed hydrogen production models.
- On-site:Dedicated purification trains serve single-facility hydrogen demand with customized engineering. Large German steel mills deploy on-site PSA units for direct reduction iron production.
- Modular:Containerized skids with standardized interfaces reduce site-specific engineering and compress deployment timelines. Nel Hydrogen dominates this architecture for electrolysis-to-purification workflows.
- Centralized:Hub-and-spoke merchant hydrogen networks with cryogenic distribution serve multiple offtakers. Linde operates centralized purification at Gulf Coast hydrogen production complexes.
- Portable:Trailer-mounted units support temporary refinery maintenance turnarounds and emergency hydrogen supply. Limited current deployment concentrates in North American maintenance services.
Centralized installations anchor current capacity; modular systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryogenic technicians cluster in legacy industrial gas regions, constraining deployment velocity in emerging hydrogen hubs across the Middle East and Asia-Pacific.
Germany
Ruhr Valley steel mills and Rotterdam-Antwerp chemical corridors drive demand for ammonia loop purge gas recovery systems. The EU Green Deal mandates binding electrolytic hydrogen targets for industrial feedstocks. BASF and ThyssenKrupp operations in North Rhine-Westphalia integrate PSA-membrane hybrid units for direct reduction iron production.
United States
Gulf Coast refineries unbundle purification as service-based contracts to merchant hydrogen suppliers. EPA Clean Air Act enforcement shapes fuel cell vehicle purity specifications. Linde operates centralized cryogenic assets at Texas and Louisiana hydrogen production complexes serving multiple offtakers.
Saudi Arabia
Aramco and SABIC process heavier crude slates requiring expanded hydrocracker hydrogen recovery capacity. The country's national energy regulator aligns with Vision 2030 hydrogen export targets. Jubail Industrial City hosts membrane skid deployments where footprint constraints override cryogenic efficiency advantages.
South Korea
Semiconductor fabs in Gyeonggi Province sustain cryogenic distillation demand for parts-per-billion moisture control. MFDS pharmaceutical-grade gas standards fragment certification requirements for export markets. Hyundai Steel and POSCO operations anchor fuel cell purity tier procurement for mobility applications.
India
Green ammonia project developers under the PLI scheme accelerate packaged PSA-membrane hybrid system deployment. The Bureau of Indian Standards develops hydrogen quality specifications for grid injection. Reliance Industries and Adani Group operations in Gujarat integrate electrolysis-to-purification workflows for export-oriented production.
Hydrogen Purification Units Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base stratifies between industrial gas incumbents with cryogenic heritage and modular equipment disruptors. Three archetypes dominate: legacy gas majors leveraging distribution infrastructure, electrolysis-integrated purifiers, and membrane technology specialists. Capacity absorption through service-based contracting and geographic expansion into Middle East hydrogen export hubs represent the dominant competitive moves.
Within the legacy gas major tier, Linde and Air Liquide occupy positions anchored by decades of cryogenic distillation operational validation. Air Products exemplifies the electrolysis-integrated pathway through proton-exchange membrane system architectures. Nel Hydrogen sits within the modular disruptor archetype, representing compact containerized designs that compress deployment timelines for distributed production models.
| Leading Market Players |
|---|
| Linde |
| Air Liquide |
| Air Products |
| Nel Hydrogen |
| Siemens Energy |
| McPhy |
| Chart Industries |
| Proton OnSite |
| HyGear |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's renewable hydrogen mandates gate qualified supply and premium-tier pricing access, as only vendors with verified low-carbon purification pathways secure contracts in German steel and Dutch chemical clusters. Buyers without green certification credentials face exclusion from public procurement frameworks and industrial offtake agreements.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the hydrogen purification landscape. Equipment vendors increasingly absorb technical risk through service-based contracts on the US Gulf Coast, compressing upfront capital requirements while extending revenue recognition timelines. Price differentiation rests on purity certification tiers and after-sales service bundling, with fuel cell-grade systems commanding substantial premiums over refinery-grade alternatives. Cost compression in membrane-based modular systems is intensifying because palladium price volatility squeezes fabrication margins. Merchant hydrogen suppliers exhibit the lowest price sensitivity due to guaranteed offtake structures, while independent chemical manufacturers negotiate aggressively on per-unit economics.
Supply Chain Analysis
Freight costs for cryogenic cold-box components concentrate supply chain leverage in Germany, the United States, and Japan where specialized fabrication facilities cluster. Palladium sourcing draws from South Africa and Russia, while advanced zeolite adsorbents feed from Chinese and US chemical manufacturing. Single-source vulnerability in helium refrigeration cycles exposes European suppliers to F-Gas Regulation compliance disruptions. Distribution runs through industrial gas majors with embedded merchant hydrogen networks, though modular equipment vendors are building direct channel relationships with electrolysis project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen purification market functions as a stable compounder anchored by binding decarbonization mandates that institutionalize demand across industrial feedstock applications. Regulatory certainty in the EU and Asia-Pacific sustains procurement visibility regardless of near-term hydrogen price volatility.
For Market Incumbents: Anticipate membrane technology substitution threats by securing palladium supply agreements and accelerating electrochemical separation R&D. Linde and Air Liquide should deepen backward integration into electrolysis equipment to defend merchant hydrogen network control. Certification investment in EU Green Deal compliance frameworks preserves access to premium-tier German steel and chemical procurement.
For New Entrants and Emerging Players: Industrial gas distributors represent the critical channel partner type for market penetration without captive infrastructure. White-space opportunities concentrate in Indian green ammonia projects under the PLI scheme and Middle East refinery hydrogen recovery retrofits. The most penetrable segment is modular PSA-membrane hybrid systems for distributed electrolysis workflows. A go-to-market angle anchored by containerized deployment speed and predictive maintenance software differentiation bypasses incumbents' cryogenic heritage advantages.
For Investors and Strategic Acquirers: Roll-up economics work for regional membrane technology specialists because certification fragmentation across EPA, EU CSRD, and Japan METI standards prevents rapid organic geographic expansion. Long-term viability over a five-to-ten-year horizon hinges on electrochemical separation platform development and carbon capture coupling capabilities. The acquisition target archetype is pure-play modular equipment vendors with established electrolysis integration workflows. The signal to watch is F-Gas Regulation enforcement intensity reshaping cryogenic versus membrane technology share trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | German steel clusters expand PSA-membrane hybrid deployments for direct reduction iron production. |
| Backward Integration | Industrial gas majors acquire electrolysis technology to control hydrogen-to-purification value chains. |
| Green Certification Program | EU Green Deal compliance frameworks gate access to Rotterdam-Antwerp chemical procurement. |
| Long-term Supply Agreement | Gulf Coast refineries unbundle purification as service contracts to merchant hydrogen suppliers. |
| Technology Licensing | Membrane specialists license palladium-alloy fabrication to regional equipment assemblers in India. |
Research Methodology
Coverage spans Germany, the United States, Saudi Arabia, South Korea, and India, with primary inputs from each regional hydrogen hub. The analysis combines primary interviews with plant engineers at refinery and chemical facilities, procurement leads at industrial gas suppliers, electrolysis project developers, and aftermarket service technicians with secondary validation. Secondary sources include EPA Clean Air Act enforcement records, EU ECHA F-Gas Regulation guidance documents, Japan METI hydrogen roadmap publications, and Bureau of Indian Standards draft specifications. Bottom-up unit deployment tallies triangulate against top-down industrial hydrogen demand forecasts.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon. The analytical framework models technology selection, application purity requirements, end-user procurement models, and installation architecture as core segmentation dimensions, with regional regulatory framework as an industry-specific overlay. CAGRs derive from electrolysis capacity buildout trajectories, refinery crude slate heavification trends, and fuel cell vehicle deployment pipelines across modeled geographies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palladium price volatility, cryogenic technician availability constraints, and regulatory divergence between pipeline hydrogen and fuel cell purity tiers. The analysis reflects assumptions about technology cost reduction curves and policy continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Hydrogen Gas Generator Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Hydrogen Storage Tank Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market