
 Adhesive Tester Market | 2026-2036
Adhesive Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Tester Market Analysis
REACH compliance in the European Union is shifting the cost-of-entry calculus for adhesive tester suppliers entering the European market. Shimadzu Corporation leverages its electromechanical platform specialization to dominate high-precision segments across Japanese and Southeast Asian manufacturing bases. Labthink anchors its competitive position through backward integration into load cell production, insulating margin pools from component volatility. ZwickRoell sustains technology leadership in universal testing configurations for automotive OEM certification programs.
An adhesive tester measures bond strength, peel resistance, shear force, and tensile properties of adhesives across substrates, typically operating at force ranges from millinewtons to kilonewtons depending on application scale. Digital testers with integrated software analytics now command premium positioning as manufacturers seek real-time SPC integration and automated pass-fail documentation. Portable testers represent the fastest-growing product configuration, driven by on-site quality audits in construction and wind energy installation markets where laboratory access remains impractical. Electromechanical technology leads the technology dimension for precision and energy efficiency, while hydraulic systems retain share in high-force construction and aerospace composite testing above fifty kilonewtons.
The U.S. EPA and OSHA frameworks govern workplace exposure and volatile organic compound limits in adhesive formulation, indirectly mandating verification of alternative bonding chemistries through validated test protocols. The EU Green Deal and F-Gas Regulation accelerate demand for solvent-free adhesive systems that require new rheological and cure-characterization capabilities from testing equipment. Stakeholders must monitor evolving automotive electrification standards that redefine substrate combinations and thermal cycling requirements for battery module assembly.
Market Dynamics
Electromechanical testing platforms are compressing calibration cycles and displacing hydraulic systems across European automotive certification labs, forcing suppliers to retool service architectures around predictive maintenance and remote diagnostics capabilities.
Growth Catalysts
- Automotive Electrification Mandates:Battery module assembly protocols under EU Green Deal guidelines require thermal cycling validation for new substrate combinations, pulling demand for multi-axis testers capable of simulating charge-discharge stress profiles.
- REACH Compliance:ECHA substance restrictions on solvent-based adhesives compel manufacturers to verify alternative bonding chemistries through documented peel and shear protocols, expanding tester utilization rates at formulation labs.
- Wind Energy Installation:On-site blade repair audits in offshore parks drive portable tester deployment where laboratory access remains impractical, creating field-service revenue pools for equipment lessors.
Market Restraints
- Load Cell Input Volatility:Strain gauge and force transducer supply concentrates among Japanese and German component specialists, exposing margins to semiconductor foundry allocation cycles and rare earth magnet price swings.
- High-Force Hydraulic Lock-In:Aerospace composite testing above fifty kilonewtons retains hydraulic system dominance due to electromechanical torque limitations, fragmenting R&D budgets across incompatible platform architectures.
- CE Marking Friction:Machinery Directive conformity assessment timelines for software-integrated testers extend certification cycles by four to eight months, delaying product launches in safety-critical automotive segments.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for electronics manufacturing and automotive component localization create first-mover advantage for testers supporting BIS-certified adhesive validation at new semiconductor packaging facilities.
- Real-Time SPC Convergence:Integration of edge computing modules with electromechanical frames enables automated pass-fail documentation, opening subscription revenue streams from quality managers seeking MES connectivity.
- Solvent-Free Formulation Surge:F-Gas Regulation acceleration of UV-cure and hot-melt systems requires rheological characterization capabilities absent from legacy peel-test configurations, creating upgrade cycles among contract laboratories.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-functional engineers capable of calibrating force measurement chains while debugging Python-based analytics software command premium compensation, constraining service expansion at mid-tier distributors.
- Legacy MES Integration Complexity:Digital testers with native OPC-UA outputs face protocol translation delays when interfacing with 1990s-era manufacturing execution systems prevalent at tier-two automotive suppliers.
- ISO 17025 Audit Compression:Accelerated laboratory accreditation renewal cycles strain metrology departments already managing multiple adhesive test method certifications under ASTM and EN norms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Tester Market |
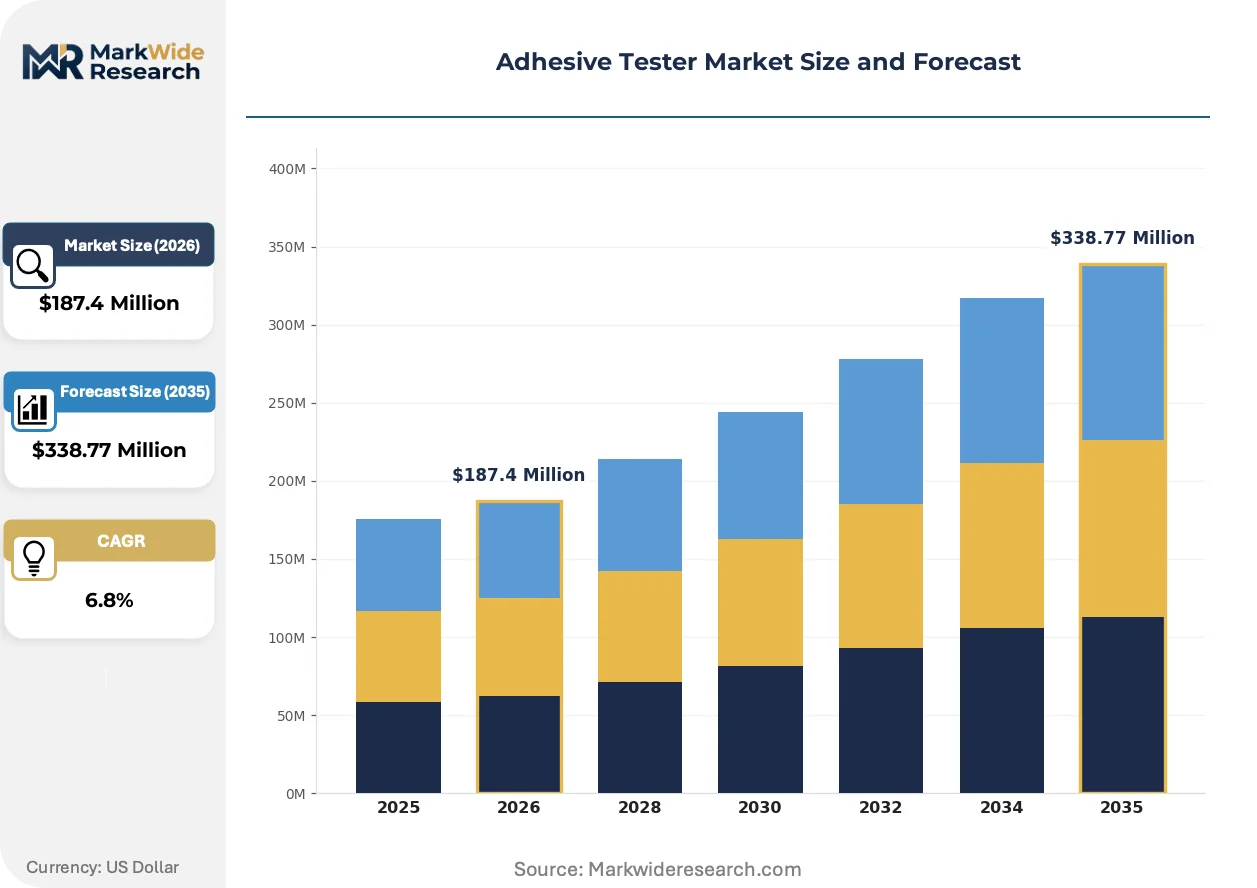
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Tester, Mechanical Tester, Universal Tester, Portable Tester Technology: Load Cells, Hydraulic, Pneumatic, Electromechanical End User: Manufacturers, Research Institutions, Quality Control Labs, Composite Fabricators Application: Packaging, Automotive, Electronics, Construction |
| Companies Covered | Shimadzu Corporation, Labthink, AMETEK, Instron, ZwickRoell, MTS Systems, ADMET, Thwing-Albert Instrument, Universal Testing Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Tester Market Emerging Trajectories
Software-defined measurement architectures are displacing hardware-centric control systems, compressing the boundary between raw force acquisition and actionable quality intelligence across adhesive testing workflows.
Digital twin technology is integrating physics-based deformation models with live sensor feeds from electromechanical frames. Automotive OEM certification programs in Germany and Japan adopt these configurations to predict bond failure modes before physical prototyping. The technology is integrating predictive simulation directly into supplier qualification protocols, reducing iterative test cycles by compressing design-of-experiments timelines.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are forcing adhesive formulators to validate replacement chemistries under accelerated aging protocols. Industrial consequence includes expanded demand for environmental chambers coupled to peel and shear fixtures. Battery module suppliers in Stuttgart and Wolfsburg respond by specifying testers with integrated thermal cycling capabilities that document performance degradation across temperature-humidity profiles.
Equipment-as-a-service contracting is displacing capital purchase models among mid-volume composite fabricators. Third-party lessors now bundle calibration, software updates, and metrological traceability into per-test pricing. This shift concentrates most visibly in North American wind energy construction markets where project-based quality audits require intermittent access to portable configurations without long-term asset ownership.
Adhesive Tester Market Segmentation
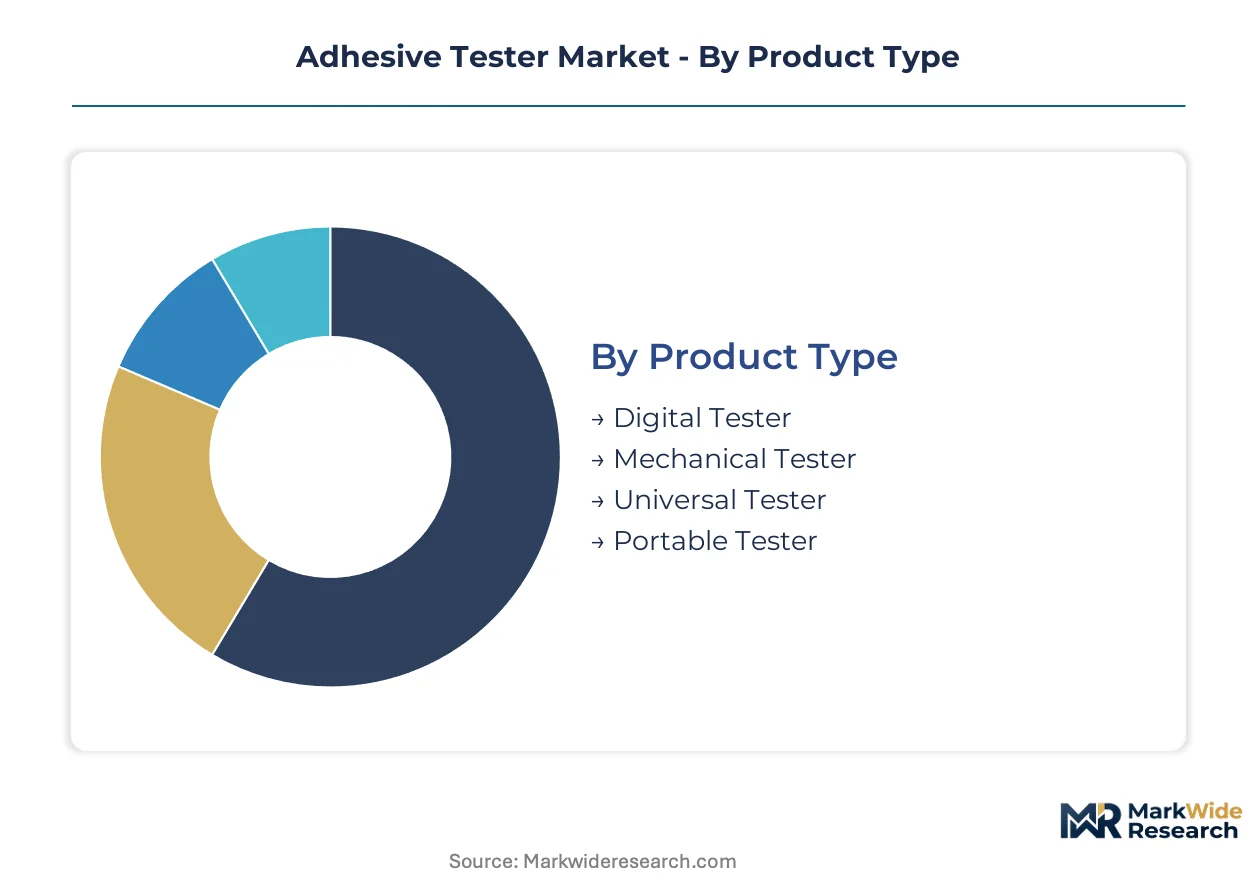
Adhesive tester procurement patterns diverge sharply by operational context. Capital allocation priorities differ between high-throughput manufacturing floors and intermittent R&D validation cycles. Equipment specification sheets must align force-range requirements with substrate portfolio complexity.
Product Type:
Capital intensity escalates with software integration depth and calibration automation. Digital configurations demand substantial upfront investment in sensor arrays and embedded analytics modules.
- Digital Tester:Integrated software platforms deliver real-time SPC connectivity and automated documentation for automotive OEM certification programs. Stuttgart-area battery module suppliers specify these units to satisfy EU Green Deal thermal cycling validation protocols.
- Portable Tester:Compact electromechanical frames with battery power enable on-site quality audits where laboratory access proves impractical. Offshore wind blade repair contractors in the North Sea deploy these configurations for intermittent bond verification without permanent facility investment.
- Mechanical Tester:Hand-operated dial gauges serve entry-level quality checks at small-scale packaging converters.
- Universal Tester:Modular load frame architectures accommodate interchangeable fixtures for peel, shear, and tensile sequences.
Digital testers absorb the bulk of installed capacity in automotive supplier parks; portable configurations are expanding most quickly in renewable energy field services.
Technology:
Force generation methodology determines precision thresholds, energy consumption profiles, and maintenance cadences. Electromechanical platforms command premium positioning against legacy hydraulic alternatives.
- Electromechanical:Servo motor-driven ball screw mechanisms deliver sub-micron displacement resolution with minimal energy draw. German automotive certification labs under KBA oversight specify these systems for bond-performance documentation meeting stricter EU type-approval standards.
- Load Cells:Strain gauge-based force transducers constitute the measurement core across platform architectures. Japanese and German component specialists concentrate supply, exposing procurement timelines to semiconductor foundry allocation cycles.
- Hydraulic:High-pressure fluid systems retain dominance above fifty kilonewtons for aerospace composite qualification.
- Pneumatic:Compressed air actuation serves rapid-cycle packaging line checks where absolute precision matters less than throughput speed.
Electromechanical platforms claim the dominant share of new installations; pneumatic systems maintain niche presence in high-speed packaging corridors.
End User:
Volume scale and test-frequency requirements shape equipment specification decisions. Continuous production environments prioritize uptime guarantees over capital expenditure minimization.
- Quality Control Labs:ISO 17025-accredited facilities require traceable calibration chains and multi-method certification coverage. Contract laboratories serving automotive tier-one suppliers face compressed audit renewal cycles under simultaneous ASTM and EN norm compliance.
- Composite Fabricators:Specialized operations bond dissimilar substrates for electric vehicle battery enclosures and wind turbine blades. Stuttgart and Wolfsburg manufacturing clusters specify testers with integrated environmental chambers for thermal cycling documentation.
- Manufacturers:In-house validation departments at adhesive producers verify formulation batches against customer specification sheets.
- Research Institutions:University materials science departments prioritize reconfigurable fixtures for exploratory substrate combinations.
Quality control labs concentrate the highest equipment density per facility; composite fabricators are climbing the fastest as automotive electrification accelerates substrate validation requirements.
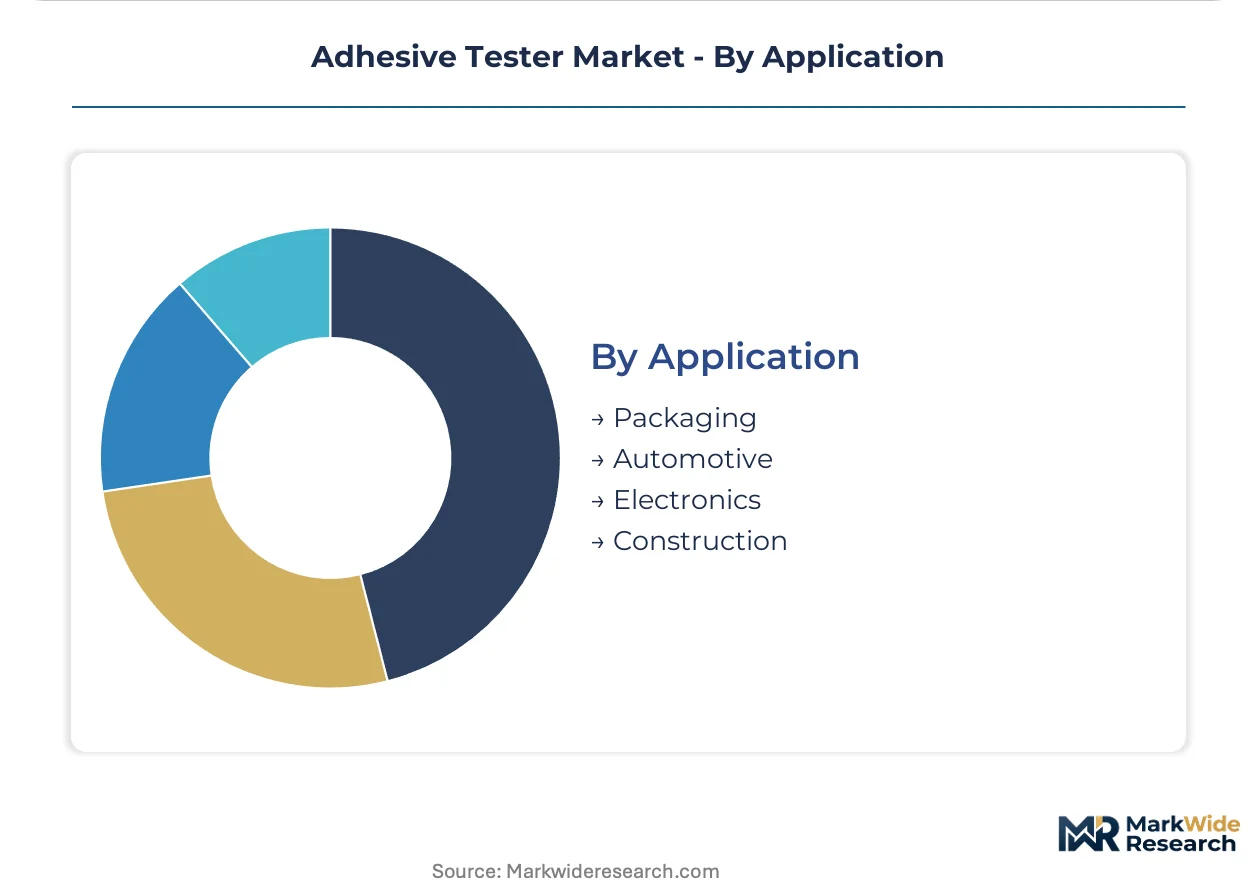
Application:
Substrate portfolio diversity and bond failure consequence severity determine tester specification rigor. Safety-critical applications mandate redundant measurement chains.
- Automotive:Battery module assembly protocols under EU Green Deal guidelines require multi-axis testers simulating charge-discharge stress profiles. Stuttgart-area suppliers specify equipment with thermal cycling capabilities to document performance degradation across temperature-humidity envelopes.
- Electronics:Miniaturized component bonding demands millinewton-resolution force measurement for semiconductor packaging validation. India's PLI scheme for electronics manufacturing pulls demand for BIS-certified adhesive testing at new fabrication facilities.
- Packaging:Corrugated board and flexible film converters prioritize rapid peel and seal strength verification.
- Construction:Structural glazing and cladding installations require on-site bond verification where laboratory access remains impractical.
Automotive applications anchor the largest installed base; electronics testing shows the steepest expansion trajectory as semiconductor packaging localizes under production-linked incentive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive supplier clusters concentrate the highest density of adhesive tester installations, while Asian electronics manufacturing corridors and North American renewable energy construction zones generate divergent equipment specifications.
Germany
KBA type-approval standards mandate bond-performance documentation for battery module assemblies. EU Green Deal thermal cycling protocols compel Stuttgart and Wolfsburg suppliers to specify multi-axis testers with integrated environmental chambers. Electromechanical platforms displace hydraulic systems across certification labs serving automotive OEM electrification programs.
United States
OSHA workplace exposure frameworks indirectly require verification of alternative bonding chemistries through validated test protocols. EPA volatile organic compound limits push adhesive formulators toward solvent-free systems demanding new rheological characterization capabilities. Wind energy construction contractors in the Great Plains and Texas deploy portable testers for intermittent on-site blade repair audits.
Japan
METI industrial standards govern precision requirements for semiconductor packaging validation at millinewton resolution. JIS certification protocols anchor quality control specifications for electronics manufacturers. Tokyo and Osaka manufacturing bases sustain demand for electromechanical platforms with sub-micron displacement accuracy.
China
MIIT standards for electric vehicle battery enclosures mandate substrate validation protocols. Dual carbon goals accelerate solvent-free adhesive adoption requiring upgraded cure-characterization capabilities. Yangtze River Delta and Pearl River Delta electronics corridors localize semiconductor packaging facilities under import-substitution programs.
India
PLI scheme production-linked incentives for electronics manufacturing and automotive component localization create first-mover opportunities. BIS certification requirements for adhesive validation pull demand at new semiconductor packaging facilities. Maharashtra and Karnataka industrial corridors concentrate contract laboratory expansion serving multinational OEM supplier qualification programs.
Adhesive Tester Market Vendor Landscape
German producers anchor the precision-tier segment; Japanese specialists hold dominant positions in electromechanical platform supply. The vendor base concentrates among universal testing machine manufacturers with adjacent adhesive fixture capabilities and dedicated adhesive testing specialists with application-specific expertise. Two strategic archetypes prevail: diversified materials testing conglomerates leveraging cross-selling from metals and composites portfolios, and focused adhesive testing specialists defending margin pools through backward integration into load cell production. Geographic expansion into Asian electronics manufacturing corridors and technology licensing for software-defined measurement architectures constitute the dominant competitive moves.
Among diversified instrumentation conglomerates, Shimadzu Corporation and AMETEK occupy positions spanning electromechanical platforms and multi-physics testing portfolios. ZwickRoell exemplifies the precision-focused archetype anchored in German automotive certification ecosystems. Labthink represents the specialist tier with captive supply chain integration into force transducer manufacturing.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Labthink |
| AMETEK |
| Instron |
| ZwickRoell |
| MTS Systems |
| ADMET |
| Thwing-Albert Instrument |
| Universal Testing Machines |
| Others |
Supply Flow & Price Mechanics
Backward integration into load cell production anchors competitive positioning for adhesive tester specialists, insulating margin pools from semiconductor foundry allocation cycles while enabling pricing power against distributors dependent on Japanese and German component specialists. Labthink's captive supply chain demonstrates how upstream control over strain gauge force transducers converts input volatility defense into premium-tier pricing authority across Asian manufacturing bases.
Pricing Analysis
Volume concentration in automotive OEM certification programs splits the market into premium electromechanical configurations and economy-tier mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels separates digital testers with integrated SPC software from portable field-service units and hand-operated dial gauges. Cost compression in the standard tier intensifies because European CE marking timelines extend certification cycles by four to eight months, delaying revenue recognition. Small-scale packaging converters exhibit highest price sensitivity, while Stuttgart-area battery module suppliers prioritize thermal cycling capabilities over capital expenditure minimization.
Supply Chain Analysis
Strain gauge and force transducer supply rests on Japanese and German component specialists, exposing procurement timelines to semiconductor foundry allocation cycles and rare earth magnet price swings. Electromechanical servo motors, ball screw mechanisms, and environmental chamber subsystems draw from China, Japan, and Germany manufacturing clusters. Single-source vulnerability concentrates in high-precision load cells above fifty kilonewtons, where aerospace qualification standards limit approved suppliers. Distribution runs through authorized distributor networks serving ISO 17025-accredited laboratories, with direct OEM relationships dominating automotive certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adhesive tester market functions as a cost-of-compliance arena where REACH substance restrictions and EU Green Deal thermal cycling protocols erect barrier-to-entry moats for testers with validated certification documentation. ECHA regulatory enforcement creates structural advantage for incumbents with established KBA and CE marking track records.
For Market Incumbents: Hedge against electromechanical platform commoditization by deepening software-defined measurement architectures with predictive maintenance subscriptions. Consolidate service architectures around remote diagnostics capabilities as European automotive labs displace hydraulic systems. Defend margin pools through backward integration into force transducer manufacturing, replicating Labthink's captive supply chain model. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for BIS-certified adhesive validation equipment at new semiconductor packaging facilities in Maharashtra and Karnataka. Target portable tester deployment for offshore wind blade repair audits in the North Sea where laboratory access remains impractical. Pursue equipment-as-a-service contracting models to bypass capital purchase barriers among mid-volume composite fabricators. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified materials testing conglomerates seeking electromechanical platform capabilities. Long-term viability favors specialists with captive load cell production and software analytics integration. Watch for inflection signals in automotive electrification standards redefining substrate combinations and thermal cycling requirements for battery module assembly.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Captive supply of strain gauge force transducers insulates margins from Japanese component specialist allocation cycles. |
| Software-Defined Measurement Architecture Development | Integrated edge computing modules enable automated SPC connectivity for Stuttgart-area automotive certification programs. |
| Equipment-as-a-Service Contracting Model | Per-test pricing with bundled calibration opens field-service revenue pools in North American wind energy construction markets. |
| CE Marking and KBA Certification Investment | Machinery Directive conformity accelerates access to EU automotive supplier parks under stricter bond-performance standards. |
| Portable Electromechanical Platform Miniaturization | Battery-powered configurations capture on-site quality audit demand where laboratory access remains impractical. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this adhesive tester market analysis. Primary interviews with quality control lab managers, automotive tier-one supplier procurement leads, electromechanical platform engineers, and aftermarket service heads combined with bottom-up and top-down triangulation. Secondary validation drew from KBA type-approval documentation, ECHA REACH substance restriction filings, EU Green Deal implementation reports, and BIS certification records for Indian electronics manufacturing facilities.
Granularity-level modeling disaggregated volume and value outputs across product type, technology, end user, application, and regional production cluster dimensions. Electromechanical versus hydraulic technology splits, ISO 17025 accreditation status, and automotive OEM certification program participation anchored industry-specific forecast inputs. CAGRs were derived through segment-level growth rate reconciliation against macroeconomic drivers and regulatory compliance timelines across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for hydraulic system retention in aerospace composite testing above fifty kilonewtons would alter the outlook. Forecasts reflect assumptions about REACH compliance timelines, PLI scheme implementation pace in India, and wind energy installation growth trajectories. A small set of triggers—automotive electrification standard revisions, semiconductor foundry allocation shocks, and CE marking directive amendments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Paint Tester Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Materials Testing Equipment Market