
 Chemical Testing Services Market | 2026-2036
Chemical Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Testing Services Market Analysis
Buyer concentration among pharmaceutical multinationals is recalibrating contract structures across the testing services landscape. SGS SA leverages its pan-European laboratory network to sustain long-term relationships with agrochemical registrants. Eurofins Scientific anchors its position through specialized chromatography capabilities for food safety verification. Bureau Veritas competes on geographic breadth, operating accredited facilities across multiple regulatory jurisdictions.
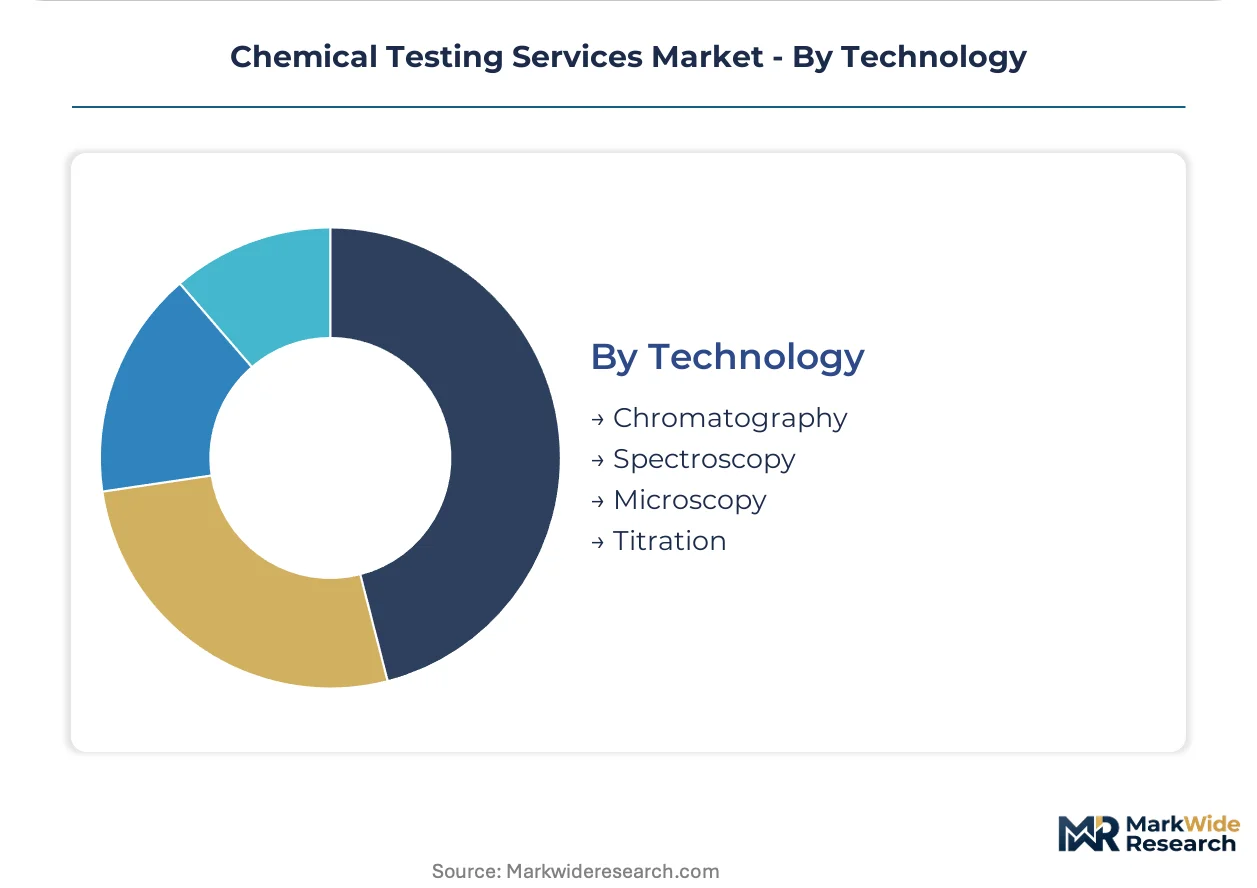
Chemical testing services encompass the analytical verification of substance composition, purity, stability, and safety profile using instrumental methods such as high-performance liquid chromatography with mass spectrometry detection limits reaching parts per billion. These services ensure regulatory compliance, quality assurance, and risk mitigation across industrial supply chains. Analytical testing dominates service revenue due to its ubiquity in pharmaceutical batch release and environmental monitoring programs. Compliance testing is expanding fastest as REACH deadlines and F-Gas Regulation phase-downs multiply registration and verification obligations. Chromatography leads technology deployment for separations-intensive applications, while spectroscopy commands premium pricing in materials identification and contaminant screening workflows.
EPA mandates under the Toxic Substances Control Act and ECHA's REACH authorization requirements directly expand mandatory testing volumes for industrial chemical producers. FDA cGMP guidelines and EMA GMP Annex 19 standards enforce analytical method validation, driving recurring demand from pharmaceutical quality control departments. ISO/IEC 17025 accreditation has become a non-negotiable market access criterion, filtering out undercapitalized regional laboratories. Stakeholders must monitor regulatory divergence between EU and US hazard classification frameworks, as testing protocols developed for one jurisdiction often require costly adaptation for the other.
Market Dynamics
Pharmaceutical outsourcing of analytical validation is compressing contract timelines while expanding testing volumes, forcing laboratories to reconfigure capacity allocation models around batch-release urgency rather than scheduled campaigns.
Growth Catalysts
- REACH Authorization Deadlines:ECHA's substance evaluation schedule multiplies registration dossier requirements for industrial chemical producers, generating recurring compliance testing mandates across the EU27.
- Biologics Manufacturing Expansion:Cell and gene therapy facilities require specialized stability and purity verification protocols that exceed in-house analytical capabilities.
- Germany's Chemical Corridor:Concentrated industrial demand around Leverkusen and Ludwigshafen sustains dedicated testing clusters serving export-oriented agrochemical and specialty chemical registrants.
Market Restraints
- Reference Standard Cost Volatility:Certified pharmaceutical reference materials face supply constraints from limited qualified manufacturers, inflating per-test input costs.
- Accreditation Concentration:ISO/IEC 17025 certification bodies cluster in Western Europe and North America, creating geographic bottlenecks for laboratories seeking market access credentials.
- Mass Spectrometry Platform Lock-in:Capital-intensive instrumentation from dominant equipment vendors creates switching costs that limit competitive price pressure on testing rates.
Strategic Opportunities
- India's CDMO Testing Gap:Contract development and manufacturing organizations near Hyderabad and Mumbai lack sufficient accredited analytical partners for export-bound pharmaceutical batches.
- PFAS Regulatory Expansion:Emerging EPA drinking water standards and state-level prohibitions are creating new contaminant screening demand across environmental and industrial matrices.
- Digital Laboratory Integration:Laboratory information management systems are converging with electronic batch record platforms, enabling real-time data exchange with sponsor quality systems.
Industry Challenges
- Mass Spectrometry Specialist Scarcity:Method development and troubleshooting for complex separations requires years of platform-specific experience that training pipelines fail to replenish.
- Multi-Jurisdictional Method Adaptation:Analytical protocols validated for FDA submission require expensive re-optimization for EMA or PMDA acceptance, fragmenting project economics.
- Legacy Equipment Integration:Chromatography data systems from 1990s-era installations resist seamless connection to modern cloud-based quality management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Testing Services Market |
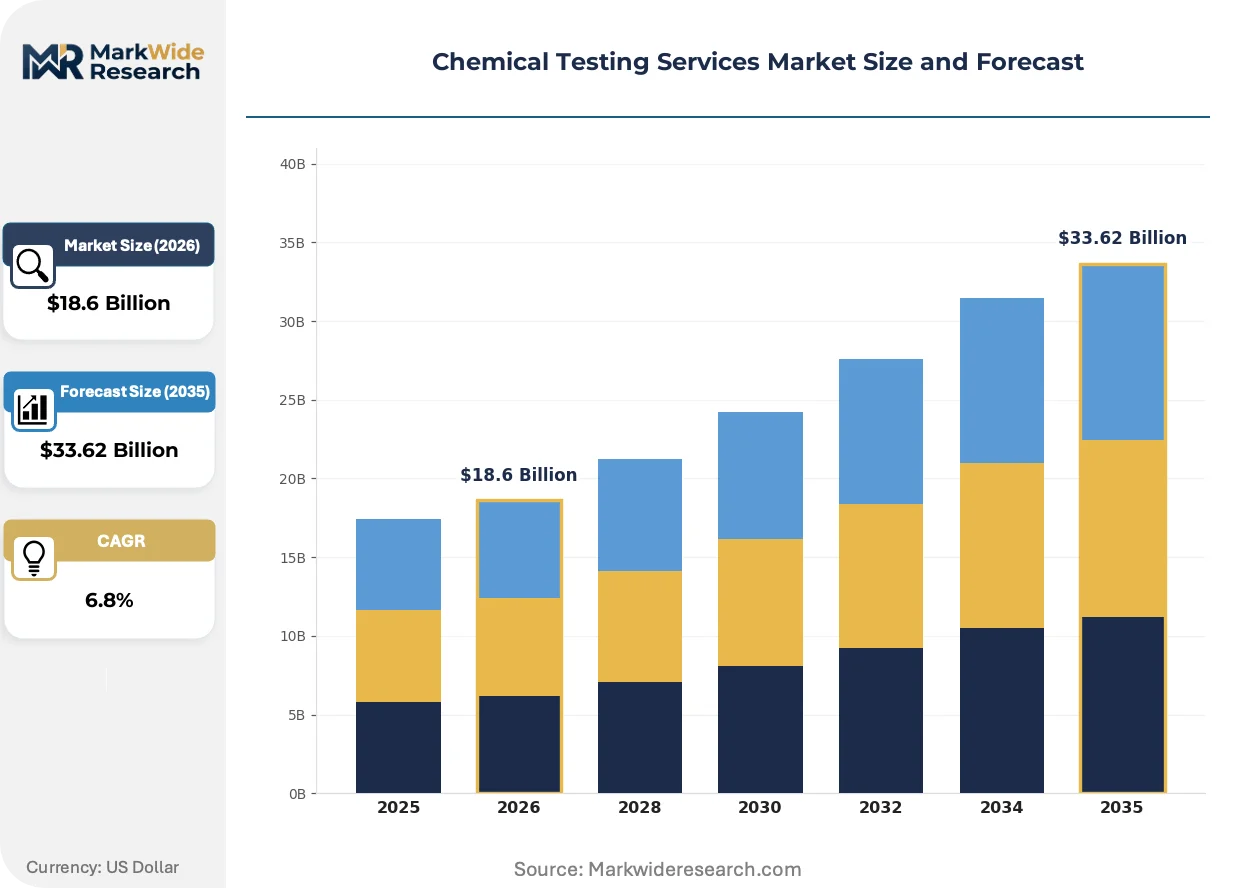
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Analytical Testing, Environmental Testing, Physical Testing, Compliance Testing Application: Pharmaceuticals, Food & Beverage, Agriculture, Paints End User: Manufacturers, Research Labs, Regulatory Agencies, Quality Control Technology: Chromatography, Spectroscopy, Microscopy, Titration |
| Companies Covered | SGS SA, Eurofins Scientific, Thermo Fisher Scientific, Bureau Veritas, Intertek Group, TÜV SÜD, Charles River Laboratories, ALS Limited, TÜV Rheinland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Testing Services Market Emerging Trajectories
Automation and artificial intelligence are compressing analytical turnaround times while regulatory data integrity requirements are tightening instrument qualification protocols. These forces are reshaping laboratory capital deployment and talent models simultaneously.
High-resolution mass spectrometry is converging with automated sample preparation robotics to enable unattended screening workflows for pharmaceutical impurity profiling. Large molecule manufacturers are adopting these integrated platforms to meet accelerated stability study timelines. The technology is converging with cloud-based data analytics to reduce method development cycles from weeks to days.
EPA's expanded testing mandates under the Toxic Substances Control Act are compelling industrial chemical producers to submit new substance notifications with exhaustive analytical characterization. This regulatory expansion is forcing testing providers to maintain dual capability in both mammalian toxicology and analytical chemistry. Specialty chemical manufacturers serving US export markets are responding by pre-positioning validation studies to avoid registration delays.
Consolidated procurement functions at pharmaceutical multinationals are unbundling analytical services from full-service contract research arrangements. Quality departments now issue separate purchase orders for method validation, batch release, and stability testing rather than accepting bundled CRO packages. This pattern is most visible among top-20 pharmaceutical companies with centralized vendor management functions in Switzerland and the United States.
Chemical Testing Services Market Segmentation
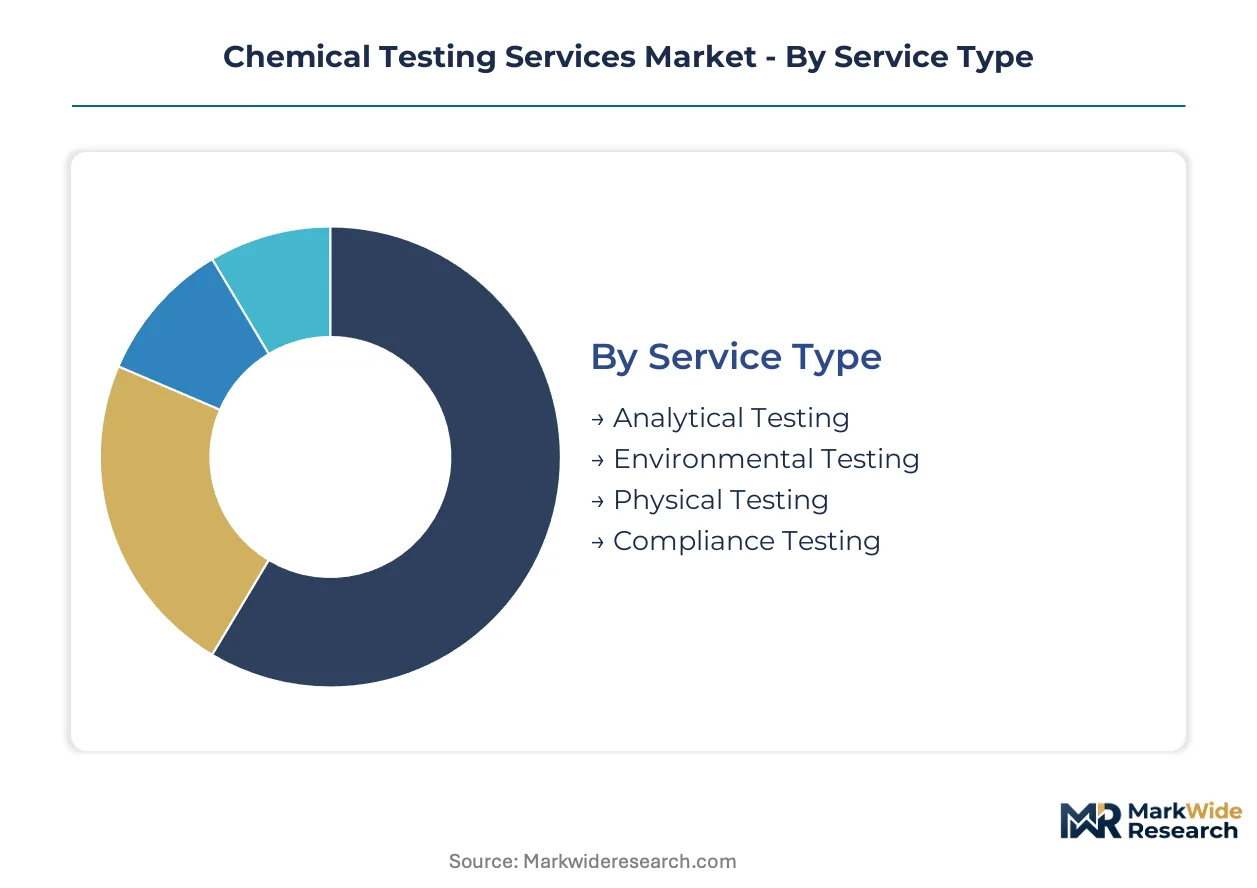
Chemical testing services fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct capability requirements, pricing structures, and competitive dynamics that shape laboratory investment priorities.
Service Type:
Standalone analytical services operate as discrete purchase orders from sponsor quality departments, while embedded compliance programs integrate directly into product registration lifecycles.
- Analytical Testing:High-performance liquid chromatography and mass spectrometry protocols verify substance composition, purity profiles, and stability characteristics for pharmaceutical batch release. Demand concentrates among CDMOs in Germany's chemical corridor, where export-bound batches require dual US-EU method validation. EPA drinking water mandates and EMA GMP Annex 19 standards drive recurring volume.
- Compliance Testing:REACH dossier preparation, F-Gas Regulation verification, and TSCA notification support dominate this segment. Industrial chemical producers in Leverkusen and Ludwigshafen sustain dedicated laboratory clusters for agrochemical and specialty chemical registrants facing ECHA authorization deadlines.
- Environmental Testing:Soil, water, and air matrix analysis for contaminant screening and remediation verification.
- Physical Testing:Viscosity, density, and mechanical property measurement for materials characterization and quality control.
Analytical Testing leads volumes today; Compliance Testing is gaining share fastest.
Application:
Cost-tier differentiation separates high-margin pharmaceutical validation from commodity food safety screening, with agrochemical testing occupying a mid-tier position.
- Pharmaceuticals:Cell and gene therapy manufacturers require specialized stability protocols for large molecule impurity profiling. Biologics facilities near Basel and Boston outsource method development for accelerated release timelines. High-resolution mass spectrometry platforms command premium pricing for unattended screening workflows.
- Food & Beverage:Chromatography-based contaminant detection for pesticide residues and mycotoxin verification. Eurofins Scientific anchors market position through specialized capabilities in this segment.
- Agriculture:Agrochemical residue testing and seed quality verification for export certification.
- Paints:VOC content analysis and heavy metal screening for RoHS and CE marking compliance.
Pharmaceutical applications command the highest pricing tier; Food & Beverage testing shows the steepest volume expansion trajectory.
End User:
Customer-type concentration shapes contract structures, with consolidated procurement functions at pharmaceutical multinationals unbundling services from full-service CRO arrangements.
- Manufacturers:Chemical producers and pharmaceutical companies requiring batch release, stability, and registration support. Quality departments now issue separate purchase orders for method validation rather than accepting bundled packages.
- Research Labs:Academic and government institutions conducting exploratory analytical work with grant-funded budgets.
- Regulatory Agencies:ECHA, EPA, and national enforcement bodies conducting surveillance testing and reference material certification.
- Quality Control:In-house and third-party verification of incoming raw materials and finished goods.
Manufacturers dominate current demand; Research Labs are expanding most quickly as academic-industry collaboration intensifies.
Technology:
Platform maturity determines automation potential and specialist scarcity, with mass spectrometry facing acute talent shortages while titration remains commoditized.
- Chromatography:HPLC and GC systems enable separations-intensive applications across pharmaceutical impurity profiling and environmental contaminant detection. Automated sample preparation robotics are compressing turnaround times for stability studies.
- Spectroscopy:FTIR and Raman techniques command premium pricing in materials identification workflows. SGS SA leverages pan-European laboratory networks to sustain relationships with agrochemical registrants requiring rapid contaminant screening.
- Microscopy:Particle characterization and materials structure analysis for specialty chemical and pharmaceutical applications.
- Titration:Classical wet chemistry methods for routine quality control and basic compositional analysis.
Chromatography leads technology deployment today; Spectroscopy is climbing the fastest as materials identification demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical corridor generates denser testing demand per square kilometer than any comparable US industrial region, while India's pharmaceutical manufacturing zones present steeper accreditation gaps relative to their production scale.
United States
EPA mandates under the Toxic Substances Control Act and emerging PFAS drinking water standards are multiplying analytical characterization requirements for industrial chemical producers. FDA cGMP guidelines enforce method validation protocols that drive recurring demand from pharmaceutical quality control departments. The Greater Boston biologics cluster and New Jersey's pharmaceutical corridor sustain specialized laboratory networks serving accelerated stability study timelines.
Germany
Leverkusen and Ludwigshafen anchor Europe's most concentrated industrial chemical testing demand, serving export-oriented agrochemical and specialty chemical registrants. REACH authorization deadlines from ECHA generate recurring compliance testing mandates across the EU27. The Rhine-Neckar metropolitan region hosts dedicated laboratory clusters that process registration dossiers for both domestic producers and international clients seeking EU market access.
Switzerland
Basel's cell and gene therapy manufacturing facilities require specialized stability and purity verification protocols that exceed in-house analytical capabilities. Swissmedic standards enforce rigorous batch release requirements for biologics export. The city's pharmaceutical quality departments now unbundle analytical services from full-service contract research arrangements, issuing separate purchase orders for method validation and stability testing.
India
Contract development and manufacturing organizations near Hyderabad and Mumbai lack sufficient accredited analytical partners for export-bound pharmaceutical batches. CDSCO compliance requirements and US FDA pre-approval inspection standards create dual validation burdens. The Maharashtra-Gujarat pharmaceutical belt is attracting laboratory investment to close the gap between manufacturing capacity and accredited testing infrastructure.
China
NMPA's evolving GMP standards and export registration requirements for active pharmaceutical ingredients are intensifying method validation demand. The Yangtze River Delta pharmaceutical manufacturing zone concentrates production facilities requiring batch release and stability testing. Shanghai's quality control departments are adopting international accreditation standards to meet dual domestic and export market requirements.
Chemical Testing Services Market Vendor Landscape
European producers anchor one tier through pan-regional laboratory networks and REACH specialization; North American specialists hold another through biologics capabilities and FDA relationship depth. The structure consolidates around three to five integrated groups with full accreditation portfolios, while mid-tier regional laboratories compete on turnaround speed for commodity testing. Strategic archetypes include pan-European compliance specialists, North American biologics-focused networks, and Asia-Pacific emerging market entrants. Dominant competitive moves involve geographic expansion through accreditation acquisition and technology platform diversification into high-resolution mass spectrometry.
Within the pan-European compliance tier, SGS SA and Bureau Veritas occupy positions defined by geographic breadth across multiple regulatory jurisdictions. Eurofins Scientific exemplifies the specialized chromatography archetype through its food safety verification capabilities. These three entities represent distinct strategic positions: one anchored in multi-jurisdiction accreditation coverage, another in separations-intensive technology deployment, and the third in pan-European relationship networks with agrochemical registrants.
| Leading Market Players |
|---|
| SGS SA |
| Eurofins Scientific |
| Thermo Fisher Scientific |
| Bureau Veritas |
| Intertek Group |
| TÜV SÜD |
| Charles River Laboratories |
| ALS Limited |
| TÜV Rheinland |
| Others |
Supply Flow & Price Mechanics
Certified pharmaceutical reference material indices cascade through contract laboratory pricing structures, compressing margins for routine analytical services while sustaining premium tiers for complex stability protocols. REACH registration deadlines and EPA notification requirements amplify demand volatility, forcing tiered capacity allocation that separates urgent batch-release pricing from scheduled campaign rates.
Pricing Analysis
Capacity additions in India's Maharashtra-Gujarat pharmaceutical belt are reshaping price floors for export-bound batch release testing. Three-tier pricing structure across premium, standard, and economy levels segments by ISO/IEC 17025 accreditation tier and dual-jurisdiction validation capability. Cost compression in routine chromatography is intensifying because automated sample preparation platforms reduce labor intensity. CDMO procurement functions show highest price sensitivity; biologics manufacturers with accelerated stability timelines exhibit lowest.
Supply Chain Analysis
Direct-to-sponsor channels handle multinational pharmaceutical quality department demand, while referral networks from contract research organizations feed mid-tier laboratories. Instrumentation supply concentrates in Germany, Switzerland, and the United States, with mass spectrometry platforms drawing from limited qualified vendors. Reference standard production rests on certified manufacturers in Western Europe and North America. Single-source vulnerability runs through high-resolution mass spectrometry equipment vendors, creating switching cost barriers that limit competitive price pressure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in chemical testing services hinges on automation-driven labor cost reduction and the premium-tier shift toward biologics stability protocols. Laboratories capturing unattended screening workflows for cell and gene therapy manufacturers command sustainable pricing power.
For Market Incumbents: Hedge against reference standard cost volatility through long-term supply agreements with certified manufacturers in Germany and Switzerland. Defend margin position by deepening automation integration for routine HPLC workflows, reducing per-test labor hours. Accreditation concentration in Western Europe creates geographic bottlenecks; preemptive certification investment in India's CDMO corridors blocks emerging competitor access.
For New Entrants and Emerging Players: Enter via India's accredited analytical partner gap near Hyderabad and Mumbai, where export-bound pharmaceutical batches face dual CDSCO and FDA validation burdens. Target biologics-focused CDMOs requiring specialized stability protocols that exceed in-house capabilities. Lead with high-resolution mass spectrometry platform differentiation to bypass commodity chromatography price competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional laboratories possessing ISO/IEC 17025 accreditation in underserved manufacturing corridors. Long-term viability centers on facilities positioned at the intersection of REACH compliance expansion and biologics manufacturing growth. Watch ECHA substance evaluation schedule acceleration as the inflection signal for compliance testing volume spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Expansion | ISO/IEC 17025 certification in India's pharmaceutical manufacturing zones closes infrastructure gaps for export-bound batches. |
| Automation Platform Deployment | Robotic sample preparation integration compresses stability study turnaround times for Basel biologics manufacturers. |
| Dual-Jurisdiction Method Validation | Simultaneous FDA-EMA protocol optimization reduces re-optimization costs for Leverkusen chemical corridor exporters. |
| Reference Standard Backward Integration | In-house certified material production insulates against supply constraints from limited qualified manufacturers. |
| Digital Laboratory Integration | Laboratory information management system convergence with electronic batch records enables real-time sponsor data exchange. |
Methodological Framework
Coverage spans Germany, the United States, Switzerland, India, and China, with primary inputs from each market's pharmaceutical quality control directors, CDMO procurement leads, contract laboratory operations managers, and regulatory affairs specialists. Secondary validation draws from ECHA registration dossier databases, FDA cGMP inspection records, SEC 10-K filings from listed testing providers, and customs trade data for analytical instrumentation imports. Bottom-up and top-down triangulation cross-validates facility-level capacity estimates against macro-level regulatory filing volumes.
Granularity-level modeling disaggregates revenue across service type, application, technology platform, and end-user archetype, with additional dimensioning by regional regulatory cluster and accreditation tier. CAGRs derive from regression analysis of historical regulatory filing trends and instrument installation base expansion. Forecast inputs incorporate REACH authorization deadline schedules, biologics manufacturing capacity pipelines, and PFAS regulatory expansion trajectories across the analysis window.
The model holds under steady regulatory enforcement intensity and reference standard supply continuity; deviation in ECHA evaluation acceleration or mass spectrometry equipment delivery delays would shift volume and pricing assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
HPLC Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Sample Preparation Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Paint Tester Market
Testing Equipment
Abrasion Tester Market