
 Hydrogen Recirculation Blower for Fuel Cell Market | 2026-2036
Hydrogen Recirculation Blower for Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Recirculation Blower for Fuel Cell Market Insights
Carbon-fiber-reinforced polymer is repositioning impeller economics in hydrogen recirculation blowers, trimming rotational mass while preserving fatigue resistance under proton-exchange-membrane operating pressures. Bosch leverages captive motor-inverter integration to anchor its supply position across European fuel-cell platforms. Rheinmetall sustains defense-aerospace crossover expertise that extends into high-reliability blower architectures for heavy transport.
A hydrogen recirculation blower is a precision gas-management device that maintains anode-circuit hydrogen circulation at differential pressures typically spanning 50 to 300 mbar, preventing nitrogen accumulation and optimizing fuel utilization in electrochemical stacks. Positive displacement blowers dominate current automotive volumes where pulsation tolerance and low-speed torque density matter most, while centrifugal designs are capturing stationary power-generation installations that prioritize acoustic suppression and maintenance intervals. Electrochemical technology integration across the product line is concentrating margin pools in sensor-augmented blower-motor assemblies that enable real-time humidity and pressure feedback.
The EU Green Deal and F-Gas Regulation are tightening emissions-accounting standards that directly condition fuel-cell system certification and blower efficiency benchmarks in European markets. EPA and NHTSA tailpipe rules in the United States are accelerating zero-emission powertrain qualification timelines that pull hydrogen recirculation components into commercial-vehicle development cycles. Stakeholders must monitor how converging efficiency mandates across these jurisdictions reshape blower specification sheets and supplier qualification protocols.
Market Dynamics
Carbon-fiber-reinforced polymer impellers are compressing rotational mass benchmarks while EU Green Deal mandates force fuel-cell system certification timelines that pull blower specifications into tighter efficiency corridors.
Growth Catalysts
- EU Green Deal fleet mandates:Heavy-duty trucking operators across Germany, Netherlands, and Denmark face binding zero-emission deployment targets that require anode-circuit hydrogen recirculation systems at scale.
- Sensor-augmented motor assemblies:Real-time humidity and pressure feedback integration is capturing margin pools previously dispersed across discrete component suppliers.
- South Korean manufacturing concentration:Dedicated hydrogen component clusters around Ulsan and Incheon are achieving process yields that lower unit economics for export markets.
Market Restraints
- Platinum-group metal input volatility:Electrocatalyst loading requirements in proton-exchange-membrane stacks create direct cost exposure to rhodium and iridium spot markets.
- German supply concentration:Precision machining capacity for high-speed impeller bearings concentrates in Baden-Württemberg supplier networks, creating single-point vulnerability.
- F-Gas Regulation compliance friction:Sealing material specifications for hydrogen compatibility conflict with existing fluorinated compound phase-out schedules.
Strategic Opportunities
- India heavy-transport corridors:National hydrogen mission frameworks and Delhi-Mumbai freight routes present untapped demand for positive-displacement blower architectures.
- Electrochemical-concentrator convergence:Integration of hydrogen recirculation with onboard water electrolysis modules creates packaged system opportunities.
- Japan METI hydrogen roadmap incentives:Subsidized fuel-cell bus procurement in Tokyo and Osaka metropolitan areas accelerates qualification pathways for qualified suppliers.
Industry Challenges
- High-speed bearing tribology expertise:Specialized lubrication engineering for 80,000+ RPM operation in hydrogen atmospheres faces acute talent scarcity in European mechanical engineering programs.
- Multi-jurisdiction certification timelines:Simultaneous KBA, EPA, and MFDS validation protocols extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Recirculation Blower for Fuel Cell Market |
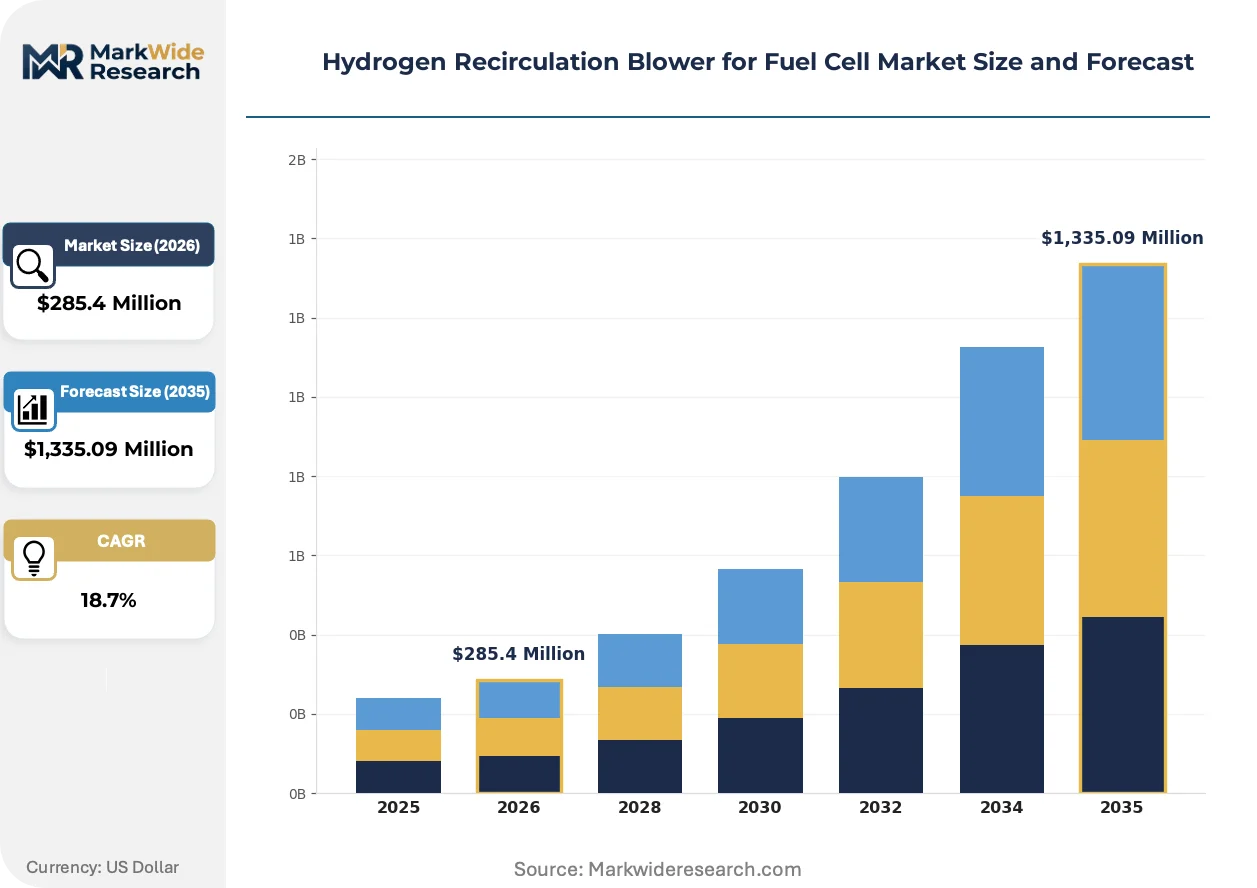
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Centrifugal, Diaphragm, Linear End User: Automotive, Aerospace, Industrial, Power Generation Installation: Onboard, Stationary, Portable, Hybrid Technology: Electrochemical, Thermal, Magnetic, Others |
| Companies Covered | Rheinmetall, Ogura, Bosch, Busch Vacuum Solutions, Eberspächer Group, ebm-papst, AVL List GmbH, Eaton, Barber-Nichols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Recirculation Blower for Fuel Cell Market Trends and Innovations
Active magnetic bearing systems are displacing conventional mechanical supports in high-reliability transport applications, while regulatory pressure on nitrogen accumulation limits forces real-time sensor density upgrades across anode-circuit architectures.
Carbon-fiber-reinforced polymer is consolidating impeller manufacturing economics by enabling 40% mass reduction against aluminum alternatives without fatigue degradation under 300 mbar differential pressures. Automotive fuel-cell platforms in Germany and South Korea are adopting these rotors for 2026-2028 model year heavy-duty trucks. The technology is consolidating supplier margins into integrated motor-inverter-blower assemblies that eliminate discrete component sourcing.
EPA and NHTSA tailpipe rules are compressing zero-emission powertrain qualification timelines for commercial vehicles above 8,500 pounds gross vehicle weight. California Air Resources Board certifications now require documented anode-circuit nitrogen purge rates that directly specify blower flow precision. Heavy-duty fleet operators in the US Southwest are responding by pre-qualifying dual-source blower suppliers before 2027 model year commitments.
Service-contract unbundling is fragmenting traditional OEM captive maintenance models for stationary power installations. Independent service providers in Texas and Alberta oil-field hydrogen pilot projects now procure blower modules separately from stack integrators, forcing component suppliers to carry direct warranty obligations. This pattern is most visible in North American distributed generation deployments where uptime guarantees drive preference for field-replaceable motor-inverter units.
Hydrogen Recirculation Blower for Fuel Cell Market Segmentation
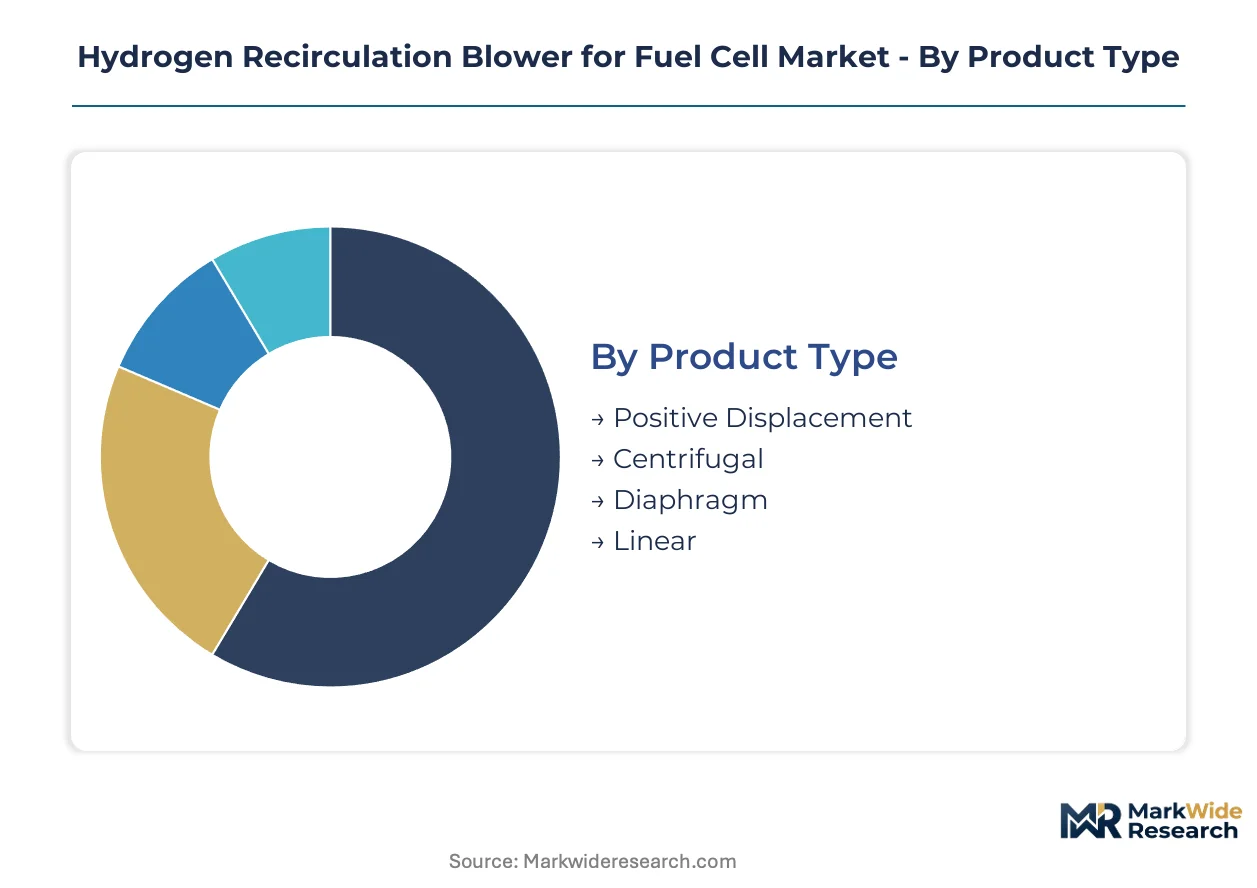
Hydrogen recirculation blower configurations diverge sharply between integrated fuel-cell stacks and standalone auxiliary systems. Product architecture choices cascade through bearing specifications, motor sizing, and sensor integration density.
Product Type:
Standalone blower modules dominate aftermarket and retrofit applications, while embedded designs anchor OEM fuel-cell platform strategies.
- Positive Displacement:Roots and claw-type mechanisms deliver pulsation-tolerant flow at low rotational speeds. Heavy-duty trucking fleets in Germany specify these architectures for anode-circuit reliability under variable hydrogen quality conditions.
- Centrifugal:Impeller-based designs achieve acoustic suppression targets that stationary power installations demand. South Korean manufacturing clusters around Ulsan prioritize these units for export to distributed generation projects.
- Diaphragm:Hermetic sealing eliminates lubricant contamination risks in proton-exchange-membrane environments. Aerospace qualification programs favor this architecture.
- Linear:Oscillating piston mechanisms serve portable fuel-cell systems where compact form factors override efficiency optimization.
Positive Displacement leads volumes today; Centrifugal is gaining share fastest.
End User:
Cost tier stratification separates premium-certified aerospace demand from price-sensitive industrial deployments.
- Automotive:Integration with 700-bar hydrogen storage systems requires blowers rated for continuous duty cycles. European Green Deal fleet mandates pull specification sheets toward 50,000-hour bearing life targets.
- Power Generation:Stationary fuel-cell installations prioritize maintenance interval extension over weight reduction. Texas and Alberta oil-field pilots specify field-replaceable motor-inverter modules.
- Aerospace:Defense-aerospace crossover expertise from Rheinmetall and similar suppliers anchors high-reliability architectures for unmanned aerial vehicle programs.
- Industrial:Forklift and material-handling equipment in South Korean logistics hubs drive volume for lower-cost positive-displacement variants.
Automotive commands the largest revenue pool; Power Generation shows the steepest expansion trajectory.
Installation:
Application context determines packaging constraints from thermal management to vibration isolation.
- Onboard:Vehicle-integrated blowers face severe space and weight budgets. German heavy-duty truck platforms specify carbon-fiber-reinforced polymer impellers to trim rotational mass.
- Stationary:Fixed installations accommodate larger acoustic enclosures and redundant bearing systems. Japanese METI-subsidized bus depots in Tokyo deploy these configurations.
- Portable:Battery-fuel-cell hybrid generators for emergency response require rapid-start blower subsystems. Netherlands civil defense procurement drives specification development.
- Hybrid:Dual-mode architectures switch between onboard vehicle supply and stationary grid injection. Danish ferry operators pilot these for maritime applications.
Onboard installations dominate current shipments; Hybrid configurations are climbing the fastest.
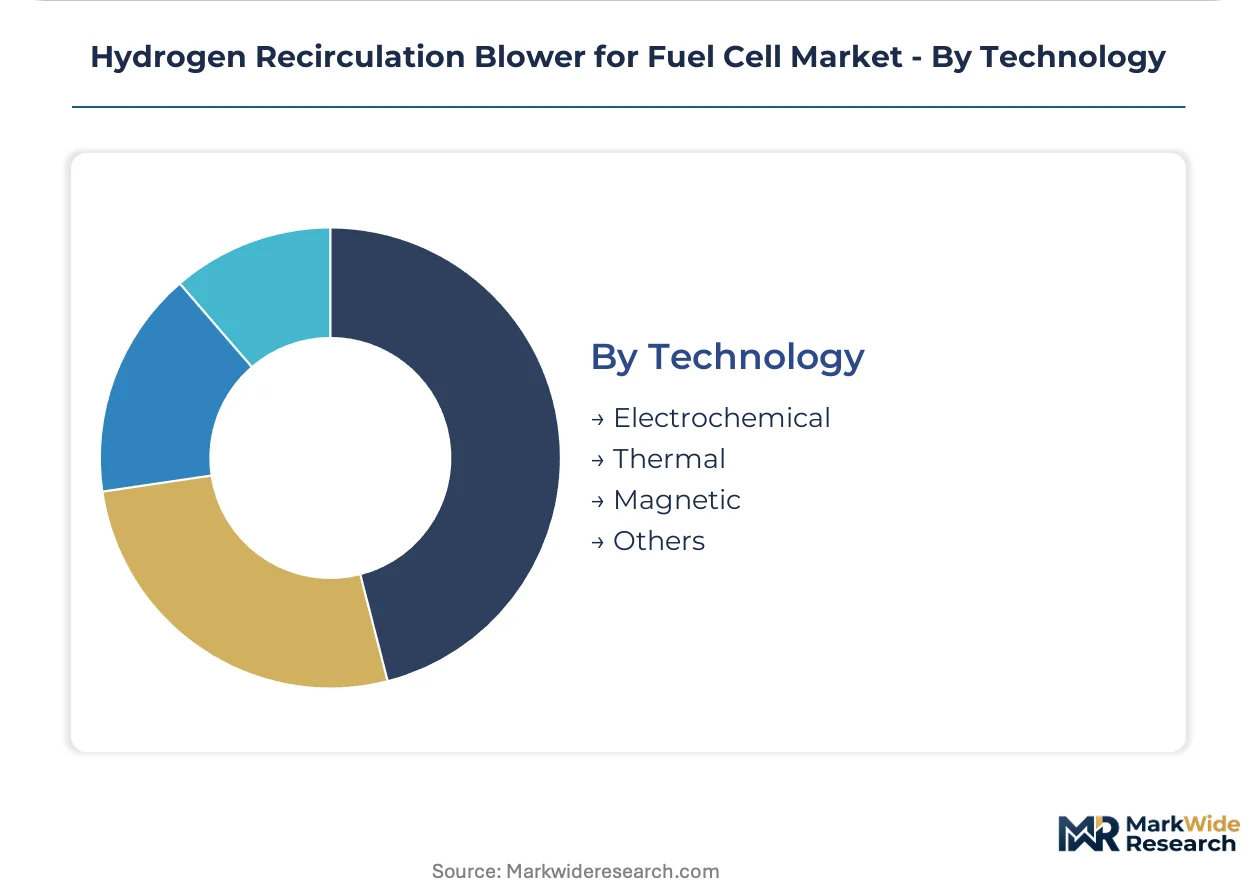
Technology:
Margin concentration tracks sensor-augmented feedback integration rather than base blower mechanisms alone.
- Electrochemical:Integrated humidity and pressure sensors enable real-time anode-circuit optimization. This technology captures premium pricing in European fuel-cell bus platforms.
- Magnetic:Active magnetic bearing systems displace mechanical supports for 80,000+ RPM operation. Talent scarcity in European tribology programs constrains supplier expansion.
- Thermal:Waste-heat recovery integration improves system-level efficiency in stationary cogeneration installations. South Korean district heating pilots validate these designs.
- Others:Emerging piezoelectric and acoustic drive mechanisms remain pre-commercial for hydrogen service.
Electrochemical technology leads adoption today; Magnetic systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision machining networks anchor European hydrogen blower manufacturing, with supplier ecosystems concentrated around Stuttgart and Karlsruhe feeding fuel-cell platform development across the continent.
Germany
Heavy-duty trucking fleets under EU Green Deal mandates drive anode-circuit system procurement. KBA certification protocols enforce nitrogen purge rate documentation for commercial vehicle fuel-cell stacks. Stuttgart-based supplier networks specialize in high-speed bearing tribology for 80,000 RPM blower operation.
South Korea
Busan-Ulsan manufacturing clusters achieve process yield improvements that lower unit economics for export markets. MFDS validation requirements compress product launch timelines for hydrogen component suppliers. Incheon dedicated hydrogen component facilities supply centrifugal blower architectures to distributed generation projects.
United States
Texas and Alberta oil-field hydrogen pilots fragment traditional OEM captive maintenance models. EPA and NHTSA tailpipe rules accelerate zero-emission powertrain qualification above 8,500 pounds gross vehicle weight. California Air Resources Board certifications now mandate documented anode-circuit nitrogen purge specifications.
Japan
Tokyo and Osaka metropolitan bus procurement subsidies accelerate qualification pathways for fuel-cell component suppliers. METI hydrogen roadmap incentives concentrate demand in public transit electrification. Nagoya-Chubu region industrial bases support precision manufacturing for aerospace-crossover blower architectures.
Netherlands
Amsterdam-Rotterdam freight corridor operators face binding zero-emission deployment targets for heavy-duty fleets. EU F-Gas Regulation creates compliance friction for sealing material specifications in hydrogen service. Eindhoven region technical universities feed specialized lubrication engineering talent into European blower development programs.
Hydrogen Recirculation Blower for Fuel Cell Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers position for 2026-2028 heavy-duty truck platform launches. The vendor base concentrates around integrated motor-inverter-blower assemblies that capture margin pools previously dispersed across discrete component sourcing. Three archetypes define positioning: diversified industrial conglomerates with captive fuel-cell divisions, precision machining specialists with defense-aerospace crossover expertise, and dedicated electromechanical component fabricators. Geographic expansion into South Korean manufacturing clusters and strategic partnerships for sensor-augmented feedback integration represent the dominant competitive moves.
Among German-based industrial groups, Bosch and Rheinmetall occupy distinct archetype positions. Bosch exemplifies the diversified conglomerate model with captive motor-inverter integration capabilities. Rheinmetall represents defense-aerospace crossover expertise extending into high-reliability transport architectures. Busch Vacuum Solutions anchors the precision vacuum and gas-handling specialist tier with established hydrogen service credentials.
| Leading Market Players |
|---|
| Rheinmetall |
| Ogura |
| Bosch |
| Busch Vacuum Solutions |
| Eberspächer Group |
| ebm-papst |
| AVL List GmbH |
| Eaton |
| Barber-Nichols |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal fleet mandates for heavy-duty trucking operators are compressing specification tolerances for anode-circuit hydrogen recirculation systems, forcing suppliers to absorb certification costs while maintaining throughput commitments across German and South Korean manufacturing networks.
Pricing Analysis
Platinum-group metal volatility in proton-exchange-membrane electrocatalysts feeds directly into blower motor-inverter assembly costs. Pricing stratifies across premium, standard, and economy tiers based on bearing life certification and real-time sensor integration density. Cost compression in economy-tier positive-displacement units is intensifying as South Korean process yields improve. Power generation operators show least price sensitivity due to uptime guarantee structures, while industrial forklift fleets in logistics hubs exhibit highest sensitivity to unit economics.
Supply Chain Analysis
Specialized lubrication engineering talent scarcity in Baden-Württemberg and Eindhoven technical programs constrains expansion of 80,000 RPM bearing production capacity. Manufacturing concentrates in Germany, South Korea, and Japan, drawing from carbon-fiber-reinforced polymer feedstocks, precision-machined bearing races, and rare-earth magnetic materials. Single-source vulnerability sits with Baden-Württemberg high-speed impeller bearing networks. Distribution runs through Tier 1 fuel-cell stack integrators and emerging independent service providers in North American distributed generation pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-fiber-reinforced polymer mass reduction is capturing premium positioning while sensor-augmented motor assemblies consolidate margin pools previously dispersed across discrete component suppliers.
For Market Incumbents: Cement captive motor-inverter integration advantages by locking long-term supply agreements with Baden-Württemberg precision machining networks before talent scarcity worsens. Expand carbon-fiber-reinforced polymer impeller capacity in Stuttgart-Karlsruhe corridors to anchor 2026-2028 heavy-duty truck platform launches. Defense-aerospace crossover expertise from Rheinmetall-type suppliers represents a replicable moat against emerging electromechanical component fabricators. For New Entrants and Emerging Players: The 40-60% price-point gap between premium electrochemical-sensor-augmented assemblies and economy positive-displacement units offers entry space for mid-tier sensor-integration specialists. Target Indian heavy-transport corridors around Delhi-Mumbai freight routes where national hydrogen mission frameworks lack established supplier relationships. Pursue qualification partnerships with Japanese METI-subsidized bus procurement programs to bypass 18-24 month multi-jurisdiction certification bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with precision machining specialists possessing defense-aerospace crossover expertise that extends into high-reliability transport architectures. Long-term viability hinges on backward integration into carbon-fiber-reinforced polymer impeller manufacturing and captive sensor-augmented feedback integration. Watch for KBA, EPA, and MFDS certification timeline convergence as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Fiber Impeller Manufacturing Scale-Up | Captures 40% mass reduction economics for German heavy-duty truck platforms. |
| Sensor-Augmented Motor-Inverter Integration | Consolidates margin pools from discrete component suppliers into unified assemblies. |
| Defense-Aerospace Crossover Qualification | Leverages Rheinmetall-type high-reliability expertise for unmanned aerial vehicle programs. |
| South Korean Manufacturing Cluster Expansion | Exploits Busan-Ulsan process yield improvements for export market penetration. |
| Independent Service Provider Channel Development | Captures warranty obligations fragmenting from OEM captive maintenance models in Texas-Alberta pilots. |
Research Methodology
Bottom-up fuel-cell platform modeling reconciled against top-down hydrogen component manufacturing tracking forms the analytical core of this study. Primary interviews with fuel-cell stack integrators, Tier 1 automotive procurement officers, precision machining plant managers, and aftermarket service heads in Texas and Alberta oil-field pilots combined with secondary validation from KBA certification databases, MFDS validation protocols, EPA tailpipe rule filings, and EU Green Deal implementation trackers. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map blower unit shipments against fuel-cell stack deployment trajectories across the projection horizon. Segmentation dimensions include product architecture, end-use application, installation context, and technology integration level. CAGRs derive from fitted adoption curves calibrated to regulatory mandate timelines and fleet operator procurement commitments. Industry-specific forecast inputs incorporate platinum-group metal spot market trajectories and carbon-fiber-reinforced polymer supply elasticity.
Caveats apply where platinum-group metal price spikes, KBA-MFDS-EPA certification timeline divergence, or F-Gas Regulation sealing material compliance friction could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market