
 Protonic Ceramic Fuel Cell (PCFC) Market | 2026-2036
Protonic Ceramic Fuel Cell (PCFC) Market Size, Share, and Industry Trends Forecast 2026-2036
Protonic Ceramic Fuel Cell (PCFC) Market Analytics
ISO 14687 hydrogen fuel quality standards is reorganizing which developers can secure offtake contracts with European industrial buyers. Ballard Power Systems anchors North American electrolyte stack development through captive ceramic processing partnerships. Toshiba leverages its solid oxide heritage to compete in intermediate-temperature system architectures. FuelCell Energy sustains technology leadership in high-temperature stationary configurations.
Protonic ceramic fuel cells operate through proton-conducting ceramic electrolytes, typically barium zirconate or cerate compositions sintered above 1600°C, generating electricity via hydrogen oxidation at 400-700°C for distributed power and transport applications. Intermediate-temperature fuel cells command the dominant product position because they balance ionic conductivity against thermal cycling durability better than high-temperature alternatives. Electrolyte framework technology attracts the fastest R&D allocation as yttrium-doped barium zirconate formulations achieve conductivity thresholds previously limited to more brittle chemistries. Stationary power generation absorbs the deepest margin pools through long-term utility procurement contracts.
The US Department of Energy and Japan's METI both enforce hydrogen purity benchmarks that directly determine which ceramic electrolyte designs qualify for public demonstration funding. REACH substance restrictions in Europe constrain cerium and nickel precursor sourcing for cathode material production, pushing developers toward alternative dopant systems. Stakeholders must monitor which national hydrogen bank structures recognize PCFC-specific efficiency advantages when allocating production subsidies.
Market Dynamics
Electrolyte material qualification timelines are compressing as national hydrogen roadmaps tighten purity benchmarks, forcing developers to accelerate yttrium-doped barium zirconate validation cycles ahead of sintering scale-up.
Growth Catalysts
- Japan's METI hydrogen roadmap:Public demonstration funding now requires proton-conducting ceramic electrolytes meeting 99.97% hydrogen purity thresholds, pulling forward commercial deployment timelines for intermediate-temperature systems.
- Stationary utility procurement:Long-term power purchase agreements in Germany are absorbing PCFC output at fixed capacity payments, de-risking manufacturing scale-up for electrolyte stack producers.
- Yttrium-doped barium zirconate conductivity breakthroughs:Sintering protocols above 1600°C now achieve ionic conductivity metrics previously limited to cerate compositions, expanding addressable temperature windows.
Market Restraints
- Cerium precursor sourcing constraints:REACH substance restrictions in Europe limit cerium oxide availability for cathode production, forcing reformulation toward praseodymium-doped alternatives with unproven degradation profiles.
- Nickel supply concentration:Cathode cermet production depends on Russian and Indonesian nickel sulfate refining capacity, exposing cost volatility from export licensing disruptions.
- High-temperature thermal cycling brittleness:Barium zirconate electrolytes exhibit microcracking after 500+ rapid thermal cycles, constraining transport applications where cold-start responsiveness is mandatory.
Strategic Opportunities
- China's dual carbon goals:Provincial hydrogen industrial parks in Shandong and Guangdong are offering land and grid connection subsidies for PCFC manufacturing facilities serving steel decarbonization clusters.
- Maritime propulsion auxiliary power:Classification societies in Norway and Japan are developing fuel cell safety notations for coastal vessels, opening a 400-600°C operating niche between diesel generators and full battery-electric systems.
- Data center combined heat and power:Hyperscale operators in Northern Virginia and Frankfurt are piloting protonic ceramic systems for baseload power with waste heat recovery for cooling loops.
Industry Challenges
- Solid-state electrochemist talent scarcity:The specialized workforce for ceramic electrolyte fabrication and thin-film deposition is concentrated at national laboratories in Germany, Japan, and the US, constraining production expansion.
- KBA transport certification timelines:German vehicle type approval for fuel cell integration requires 18-24 month validation cycles for protonic ceramic stacks, delaying revenue recognition against competing solid oxide architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protonic Ceramic Fuel Cell (PCFC) Market |
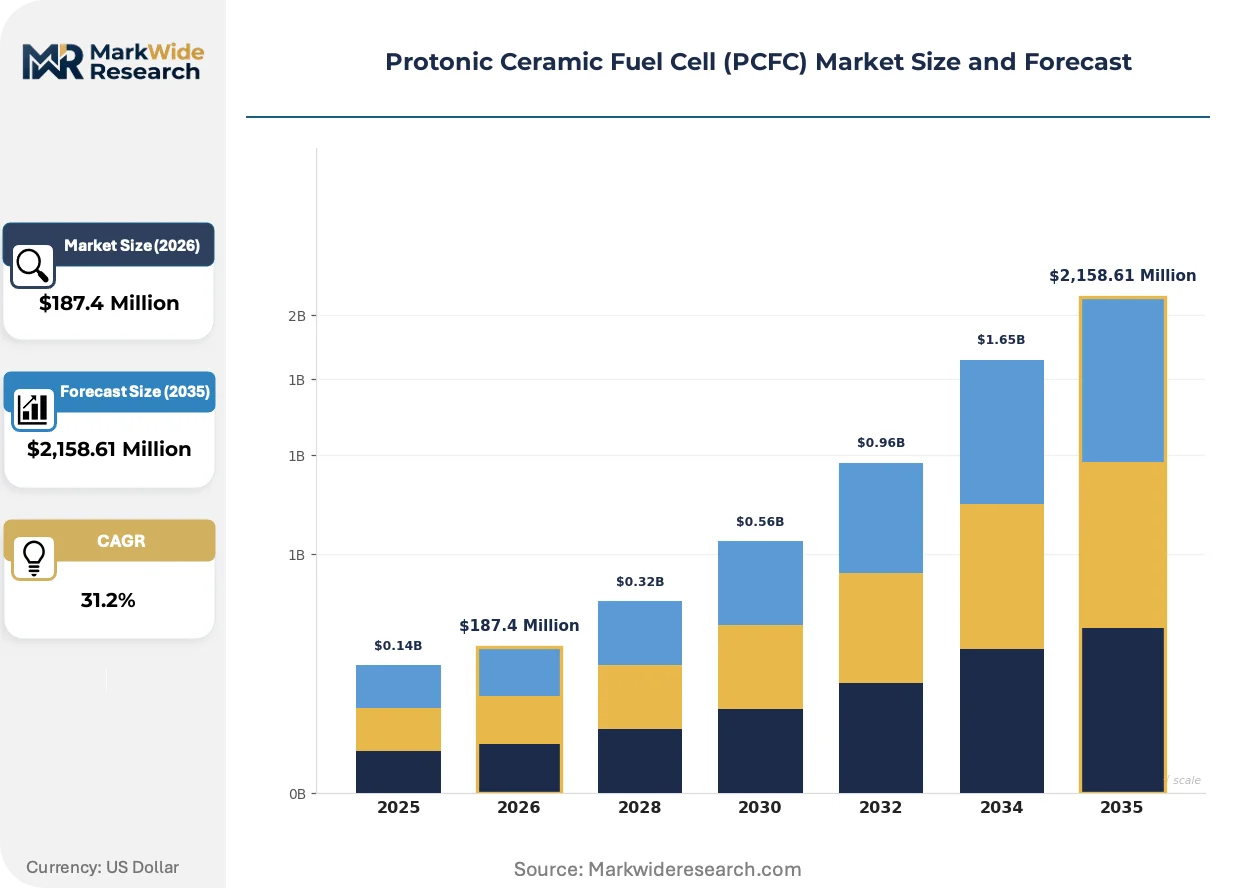
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,158.61 Million |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Temperature Fuel Cells, Low-Temperature Fuel Cells, Intermediate-Temperature Fuel Cells, Solid Oxide Fuel Cells Technology: Electrolyte Framework, Catalyst Layer, Anode Material, Cathode Material Application: Stationary Power Generation, Portable Power, Transportation, Backup Power End User: Industrial Users, Residential Users, Commercial Users, Educational Institutions |
| Companies Covered | FuelCell Energy, Hydrogenics, Ballard Power Systems, Horizon Fuel Cell Technologies, Nedstack, Toshiba, Sunrise Power Solutions, Intelligent Energy, PLUG POWER INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protonic Ceramic Fuel Cell (PCFC) Market Evolving Landscape
Protonic ceramic fuel cell development is pivoting toward intermediate-temperature architectures that trade peak efficiency for manufacturing repeatability, while regulatory hydrogen purity standards are hardening faster than electrolyte reformulation cycles can adapt.
Thin-film electrolyte deposition is miniaturizing. Yttrium-doped barium zirconate layers below 10 micrometers now achieve equivalent proton conductivity to 50-micrometer conventional sintered plates. Stationary power developers in Germany and Japan are adopting these architectures for sub-megawatt distributed generation units. The technology is miniaturizing system footprints by 60% while maintaining 400-700°C operating windows, compressing balance-of-plant costs and enabling containerized deployment models.
ISO 14687 hydrogen fuel quality standards are reorganizing offtake eligibility. The 99.97% purity specification for sulfur and halogen contaminants now determines which ceramic electrolyte designs qualify for European industrial hydrogen procurement. Electrolyte developers using cerate-based compositions face higher sulfur poisoning susceptibility, pushing reformulation toward zirconate chemistries. German industrial buyers are enforcing these specifications through tender clauses that exclude non-compliant stack suppliers.
Utility procurement departments are unbundling long-term service contracts from equipment supply. European and North American power purchasers now separate stack replacement obligations from initial capital expenditure, forcing manufacturers to price degradation risk explicitly. This shift is most visible in Germany, where KBA-certified transport integrators and stationary operators alike are negotiating power-by-the-hour arrangements that transfer operational risk to fuel cell providers.
Protonic Ceramic Fuel Cell (PCFC) Market Segmentation
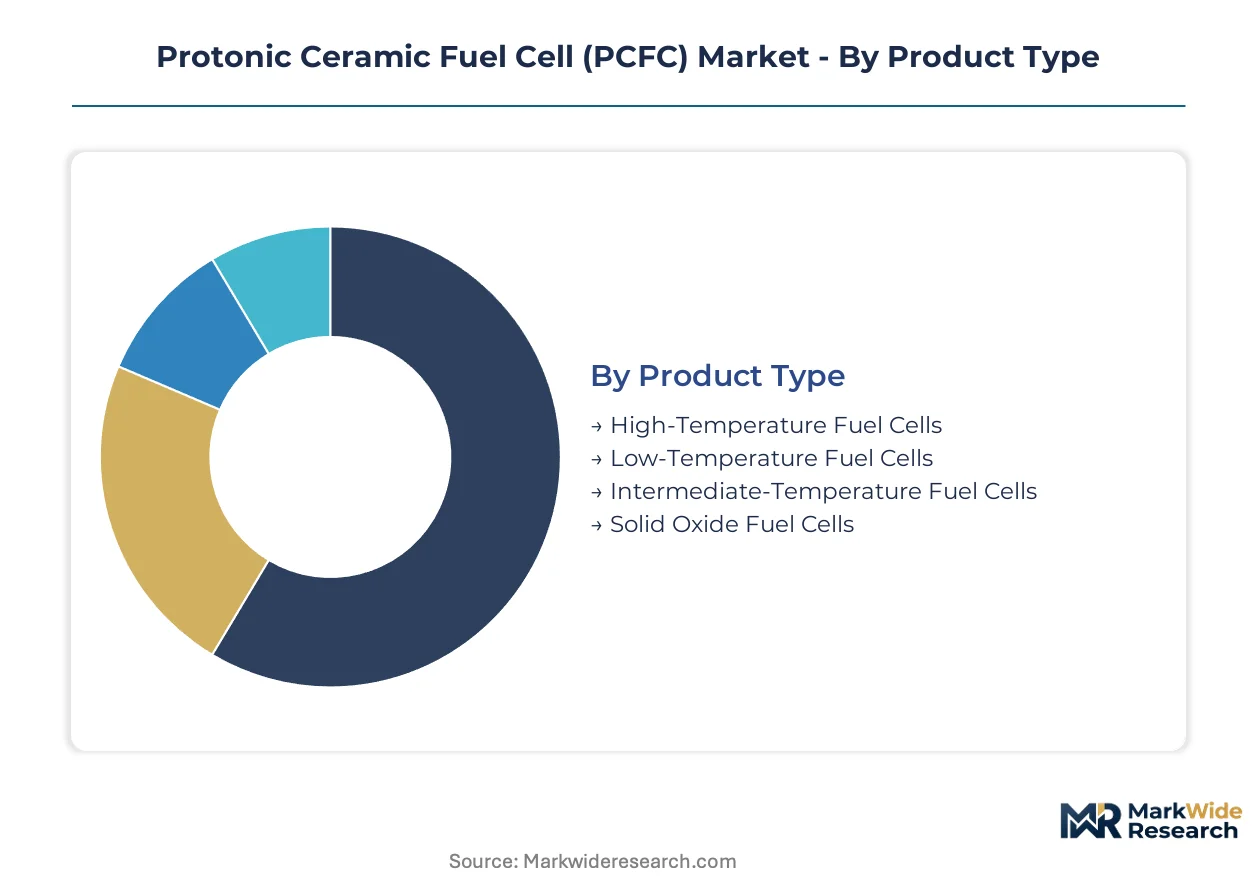
PCFC market segmentation reveals distinct procurement patterns across temperature regimes and end-use sectors. German utility buyers prioritize intermediate-temperature architectures for baseload contracts, while Japanese transport integrators demand rapid thermal cycling performance. Material qualification timelines diverge sharply between stationary and mobility applications.
Product Type:
German and Japanese buyers dominate procurement for high-temperature and intermediate-temperature systems, while low-temperature architectures serve export markets with less stringent purity requirements.
- Intermediate-Temperature Fuel Cells:Yttrium-doped barium zirconate electrolytes operating at 400-700°C balance ionic conductivity against thermal cycling durability. German utility procurement contracts in North Rhine-Westphalia absorb the deepest margin pools through 15-year power purchase agreements with fixed capacity payments.
- High-Temperature Fuel Cells:Barium cerate compositions above 700°C achieve peak proton conductivity but suffer microcracking degradation. Japanese METI demonstration funding now requires these systems for industrial hydrogen clusters in Osaka and Yokohama, pulling forward commercial deployment timelines.
- Low-Temperature Fuel Cells:Sub-400°C architectures target portable and backup applications with simplified balance-of-plant requirements.
- Solid Oxide Fuel Cells:Oxygen-ion conducting alternatives compete directly with protonic ceramics in overlapping temperature windows.
Intermediate-temperature systems command the established base. The steepest expansion runs through high-temperature configurations for industrial decarbonization clusters.
Technology:
Cost tiers separate electrolyte framework investments from catalyst layer expenditures, with anode and cathode materials absorbing divergent R&D allocations.
- Electrolyte Framework:Sintering protocols above 1600°C for barium zirconate plates now achieve conductivity thresholds previously limited to cerate chemistries. China's Shandong provincial hydrogen industrial parks are offering land subsidies for domestic electrolyte manufacturing facilities serving steel decarbonization demand.
- Cathode Material:Nickel-cermet compositions face REACH substance restrictions in Europe that constrain cerium oxide precursor sourcing, forcing reformulation toward praseodymium-doped alternatives with unproven degradation profiles.
- Anode Material:Porous nickel-zirconia cermets provide hydrogen oxidation sites at reduced overpotential.
- Catalyst Layer:Thin-film deposition below 10 micrometers miniaturizes system footprints by 60% while maintaining operating windows.
Electrolyte frameworks absorb the dominant R&D share. Catalyst layer miniaturization is gaining share fastest through sub-megawatt distributed generation adoption.
Application:
Customer type determines contract structure, with utilities unbundling long-term service obligations from equipment supply while transport integrators accept bundled procurement.
- Stationary Power Generation:Combined heat and power configurations in Northern Virginia and Frankfurt data centers recover waste heat for cooling loops. Hyperscale operators are piloting protonic ceramic baseload systems with explicit degradation risk pricing in power-by-the-hour arrangements.
- Transportation:KBA certification protocols in Germany require 18-24 month validation cycles for fuel cell integration, delaying revenue recognition against competing solid oxide architectures. Maritime classification societies in Norway are developing safety notations for 400-600°C auxiliary power in coastal vessels.
- Portable Power:Containerized deployment models target remote industrial sites without grid connection.
- Backup Power:Critical infrastructure operators prioritize rapid start capability over efficiency optimization.
Stationary power generation holds the dominant revenue position. Maritime propulsion auxiliary power is expanding most quickly through emerging classification notations.
End User:
Maturity levels separate industrial procurement with established hydrogen supply chains from residential and educational pilots requiring infrastructure buildout.
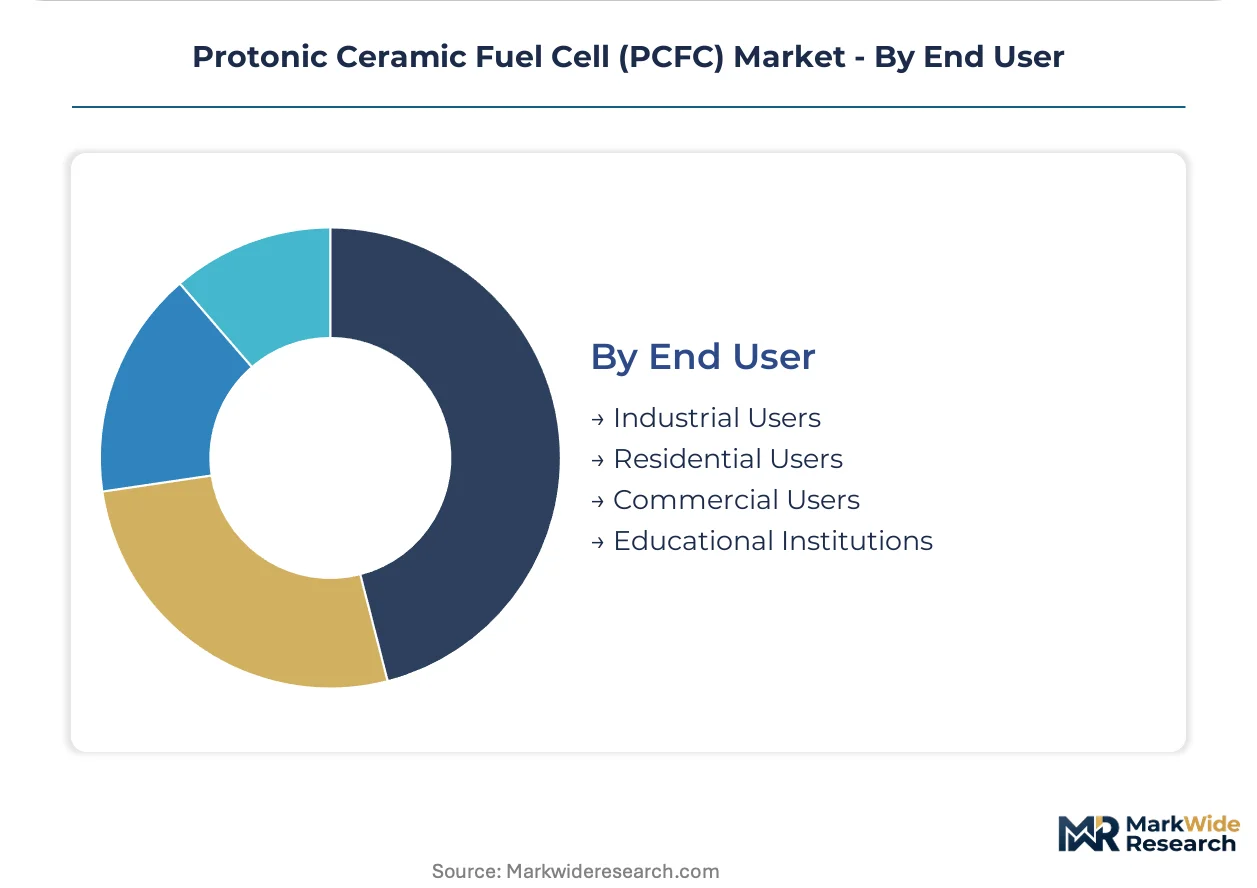
- Industrial Users:Steel and chemical producers in Germany's Ruhr region and Japan's Keihin industrial belt qualify for public hydrogen bank subsidies recognizing PCFC-specific efficiency advantages. ISO 14687 purity specifications determine offtake eligibility through tender clauses excluding non-compliant stack suppliers.
- Commercial Users:Data center and retail chains pilot distributed generation with waste heat recovery.
- Residential Users:Single-family and multi-unit buildings in Japan's ENE-FARM program test micro-cogeneration configurations.
- Educational Institutions:University demonstration projects in Germany and the US validate degradation models for emerging electrolyte chemistries.
Industrial users anchor the current installed base. Commercial deployment is climbing the fastest through hyperscale operator pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI hydrogen roadmap and Germany's KBA certification protocols are compressing electrolyte qualification timelines, while China's dual carbon goals accelerate provincial manufacturing subsidies. National hydrogen bank structures increasingly recognize PCFC-specific efficiency advantages when allocating production subsidies.
Germany
Ruhr region steel decarbonization clusters absorb the deepest stationary power margins through 15-year utility procurement contracts. KBA vehicle type approval mandates 18-24 month validation cycles for protonic ceramic stack integration. North Rhine-Westphalia hosts the densest concentration of electrolyte framework R&D facilities serving EMEA industrial buyers.
Japan
Keihin and Osaka industrial belts qualify for METI demonstration funding requiring 99.97% hydrogen purity thresholds. The national hydrogen roadmap pulls forward commercial deployment timelines for intermediate-temperature systems. Yokohama harbors classification society development of maritime fuel cell safety notations for coastal vessel auxiliary power.
China
Shandong and Guangdong provincial hydrogen industrial parks offer land and grid connection subsidies for PCFC manufacturing facilities. Dual carbon goals accelerate electrolyte material qualification timelines ahead of sintering scale-up. Steel decarbonization clusters in Hebei and Jiangsu provinces anchor domestic demand for high-temperature stationary configurations.
United States
Department of Energy hydrogen purity benchmarks determine which ceramic electrolyte designs qualify for public demonstration funding. Northern Virginia hyperscale data centers pilot protonic ceramic baseload systems with waste heat recovery for cooling loops. Department of Energy programs in the Mountain West support yttrium-doped barium zirconate conductivity validation cycles.
Norway
Maritime classification societies develop fuel cell safety notations for 400-600°C auxiliary power in coastal vessels. Fjord-crossing ferry routes create demand niches between diesel generators and full battery-electric systems. Stavanger and Bergen harbor districts concentrate pilot installations for offshore supply vessel propulsion hybridization.
Protonic Ceramic Fuel Cell (PCFC) Market Competitive Landscape
Player mix skews toward integrated fuel cell specialists with captive ceramic processing capabilities. The competitive set organizes around three archetypes: solid oxide heritage players pivoting to proton-conducting architectures, pure-play electrolyte developers securing sintering scale-up partnerships, and utility-facing project developers unbundling long-term service contracts from equipment supply. Dominant competitive moves include backward integration into yttrium-doped barium zirconate precursor refining and strategic partnerships with German KBA-certified transport integrators.
Within the solid oxide heritage tier, Toshiba occupies a position exemplifying intermediate-temperature system architecture transitions. Ballard Power Systems anchors North American electrolyte stack development through captive ceramic processing partnerships. FuelCell Energy represents the utility-facing project developer archetype sustaining technology leadership in high-temperature stationary configurations.
| Leading Market Players |
|---|
| FuelCell Energy |
| Hydrogenics |
| Ballard Power Systems |
| Horizon Fuel Cell Technologies |
| Nedstack |
| Toshiba |
| Sunrise Power Solutions |
| Intelligent Energy |
| PLUG POWER INC. |
| Others |
Value Network & Pricing Analysis
Praseodymium-doped cathode reformulation displacing cerium-dependent compositions is redrawing precursor sourcing maps and compressing margin structures for European stack producers facing REACH substance restrictions. This substitution dynamic simultaneously elevates Indonesian and Russian nickel sulfate refining premiums while forcing German buyers to absorb qualification cost premiums for unproven degradation profiles.
Pricing Analysis
Certification level (ISO 14687-grade) creates the primary spread between German utility procurement premiums and export-tier commodity pricing. Three-tier pricing structure across KBA-certified, METI-compliant, and uncertified equipment tiers separates long-term power purchase arrangements from spot market transactions. Cost compression in intermediate-temperature stacks is intensifying because yttrium-doped barium zirconate sintering scale-up is outpacing cathode material qualification. Transport integrators in Germany exhibit the sharpest price sensitivity due to 18-24 month validation cycle burdens, while Japanese industrial clusters accept bundled service premiums for purity-guaranteed hydrogen supply.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion are elevating yttrium precursor inventory carrying costs for electrolyte framework producers. Supply concentrates in China for barium zirconate sintering infrastructure, Germany for KBA-certified transport integration, and Japan for METI-compliant demonstration systems. Raw material dependencies span Indonesian nickel sulfate, Chinese rare earth yttrium oxides, and European REACH-compliant praseodymium sources. Single-source vulnerability in Russian nickel refining capacity exposes cost volatility from export licensing disruptions. Distribution runs through captive ceramic processing partnerships for stack producers and direct utility procurement for stationary deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PCFC market sits at an early-cycle expansion phase where METI hydrogen roadmap funding and German utility procurement contracts are validating commercial viability ahead of manufacturing scale-up. This adoption tailwind favors stakeholders with captive electrolyte processing capabilities and established regulatory certification pathways.
For Market Incumbents: Shield technology leadership by deepening backward integration into yttrium-doped barium zirconate precursor refining in Shandong and Guangdong provincial hydrogen industrial parks. Accelerate KBA certification pipeline investments to defend against solid oxide heritage competitors with faster validation cycles. Prioritize long-term service contract unbundling to capture degradation risk premiums from German utility buyers. For New Entrants and Emerging Players: METI demonstration funding fast-tracks offer the most penetrable entry channel for intermediate-temperature system developers lacking German KBA validation histories. Target maritime classification society notations in Norway and Japan for auxiliary power applications with reduced thermal cycling requirements versus transport mandates. Pursue power-by-the-hour arrangements with Northern Virginia and Frankfurt hyperscale data centers as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated electrolyte specialists over pure-play catalyst layer developers. Long-term viability hinges on sintering scale-up execution and cathode material qualification timelines rather than near-term order book depth. Acquisition target archetype: captive ceramic processing facilities with established 1600°C sintering protocols and METI or KBA certification relationships. Watch for inflection in provincial Chinese hydrogen bank subsidy recognition of PCFC-specific efficiency advantages versus competing alkaline electrolyzer deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yttrium Precursor Refining | Captive supply of doped barium zirconate inputs reduces REACH exposure and stabilizes sintering cost structures. |
| KBA Certification Fast-Track Investment | German transport integration approval compresses revenue recognition timelines against solid oxide competitors. |
| Maritime Classification Society Partnership | Norwegian and Japanese safety notations open 400-600°C auxiliary power niches in coastal vessel propulsion. |
| Long-Term Service Contract Unbundling | Power-by-the-hour arrangements with German utilities transfer operational risk and capture degradation premiums. |
| Provincial Chinese Manufacturing Subsidy Capture | Shandong and Guangdong land and grid connection subsidies de-risk electrolyte stack production scale-up. |
Research Methodology
Cross-validation between primary interviews with electrolyte material scientists, utility procurement officers, and maritime classification society engineers anchors the qualitative findings against secondary validation from METI hydrogen roadmap disclosures, KBA certification protocols, and ECHA REACH substance restriction updates. Bottom-up triangulation across sintering facility capacity announcements and top-down reconciliation with national hydrogen bank subsidy allocations ensures segmentation integrity.
Sensitivity analysis across electrolyte conductivity breakthrough scenarios and cathode material qualification delays shapes the analytical framework. Segmentation dimensions modeled span temperature regime, application category, end-user maturity tier, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and new capacity absorption rates across the projection horizon. Industry-specific forecast inputs include yttrium-doped barium zirconate sintering yield improvements and ISO 14687 hydrogen purity enforcement timelines.
Underlying assumptions cover METI funding continuity, KBA certification protocol stability, and Chinese provincial subsidy program persistence, with deviation risk concentrated in nickel sulfate supply disruptions and REACH substance restriction expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Fuel Cell Market