
 Europe Refined Petroleum Products Market | 2026-2036
Europe Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refined Petroleum Products Market Foresight
The EU Green Deal is broadening the strategic imperative for European refiners to reconfigure product slates toward lower-carbon outputs. Shell leverages its integrated refining-chemicals footprint across the Netherlands and Germany to sustain naphtha and middle distillate supply chains. TotalEnergies anchors its position through biofuel co-processing investments at French and Belgian sites. Neste differentiates via renewable diesel capacity expansion, competing with conventional refiners for transport fuel market share.
Refined petroleum products encompass hydrocarbon streams separated and upgraded through atmospheric and vacuum distillation, catalytic cracking, hydrotreating, and reforming processes, yielding fuels and feedstocks with specified sulfur content, cetane index, or octane ratings for combustion engines, heating systems, and industrial furnaces. Gasoline retains mature volume leadership across European retail networks, though margin compression intensifies as electric vehicle penetration rises. Diesel commands structural importance in commercial freight and industrial power generation, where demand proves more resilient than light-duty transport. Jet fuel represents the fastest-growing product category as aviation recovery outpaces other transport modes, particularly at hub airports serving long-haul routes.
The European Union's F-Gas Regulation and ETS framework compel refiners to quantify and reduce process emissions, while REACH governs chemical substance registration in blended products. Germany's KBA enforces vehicle emission standards that directly constrain diesel sulfur specifications and gasoline benzene limits. France's DGEC implements national biofuel blending mandates that alter refinery product economics. Stakeholders must monitor carbon border adjustment mechanisms and renewable fuel obligation trajectories to time capacity reinvestment decisions.
Market Dynamics
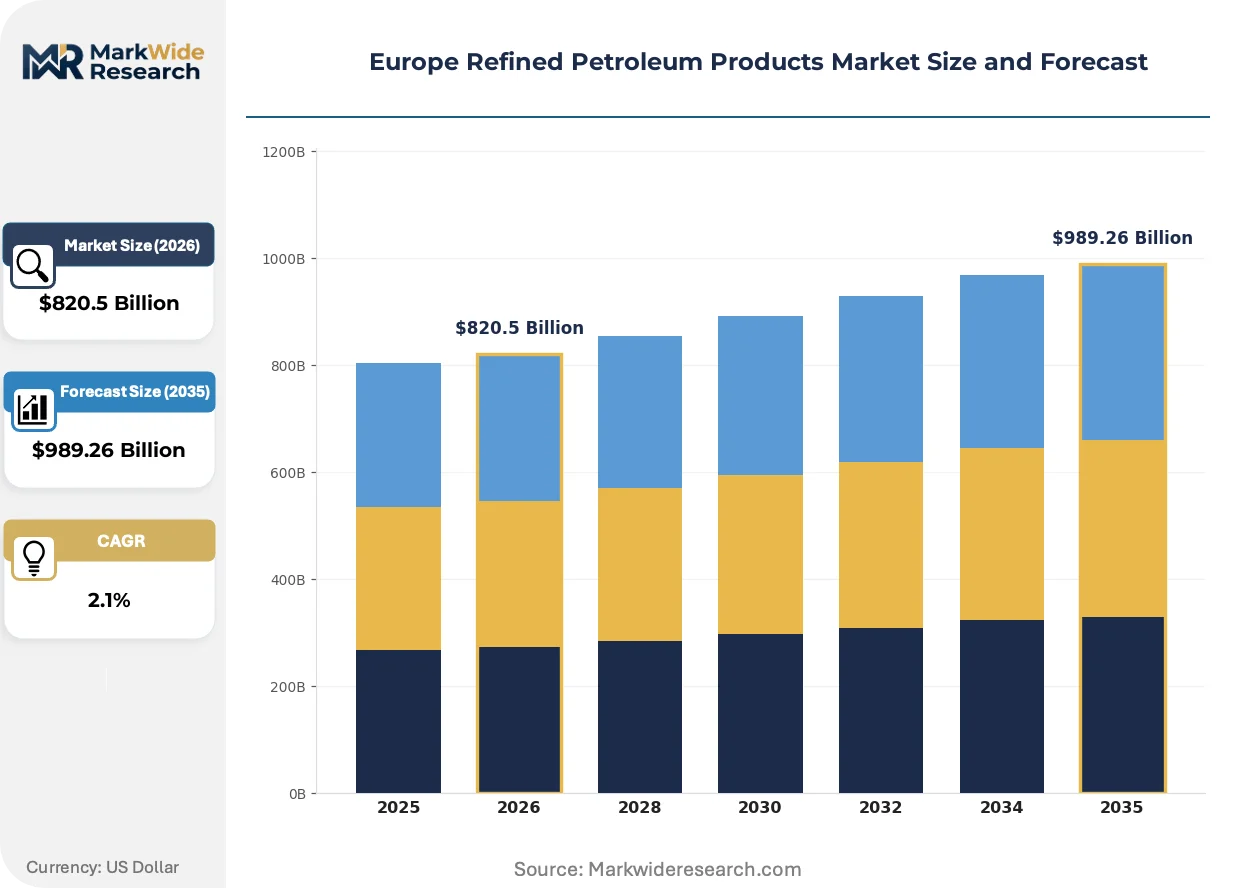
The EU Green Deal is forcing European refiners to reconfigure product slates toward lower-carbon outputs, compressing margins on conventional fuels while rewarding biofuel co-processing investments. Rotterdam's storage hub attracts marine fuel upgrading activity, concentrating capital deployment in the Netherlands.
Growth Catalysts
- EU ETS carbon pricing:The Emissions Trading System incentivizes refinery decarbonization investments, directing capital toward hydrogen and carbon capture retrofits at German and Belgian sites.
- Aviation recovery:Long-haul route expansion at Amsterdam Schiphol and Frankfurt airports drives jet fuel demand faster than other transport categories.
- Biofuel blending mandates:France's DGEC and Germany's BImSchV enforcement accelerate renewable diesel offtake, creating new revenue streams for hydrotreating capacity.
Market Restraints
- Crude supply concentration:European refiners remain dependent on seaborne crude from OPEC+ and Russian-origin alternatives, exposing margin volatility to freight and sanctions dynamics.
- Electric vehicle penetration:Battery electric vehicle sales in Germany and France erode gasoline demand at rates faster than refinery run cuts can offset.
- REACH compliance costs:Chemical substance registration requirements for blended fuel additives impose fixed-cost burdens that disadvantage smaller independent refiners.
Strategic Opportunities
- Poland's underpenetrated retail network:Limited premium fuel branding and convenience retail integration create whitespace for integrated marketers to capture motorway corridor demand.
- Sustainable aviation fuel mandates:The EU ReFuelEU Aviation regulation creates guaranteed offtake pools for hydrotreated esters and fatty acids production.
- Marine fuel 0.5% sulfur compliance:IMO 2020 enforcement continues to reward very low sulfur fuel oil blending capability at Rotterdam and Antwerp storage terminals.
Industry Challenges
- Process control engineering talent:Refinery digitalization and advanced process control implementation require automation specialists that European labor markets undersupply.
- Hydrocracker catalyst replacement cycles:Extended turnaround intervals for high-pressure units strain maintenance planning and working capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refined Petroleum Products Market |
| Market Size in 2026 | $820.5 Billion |
| Market Size in 2035 | $989.26 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Heating Oil End User: Transportation, Residential, Industrial, Commercial Distribution Channel: Retail, Wholesale, Direct Supply, E-commerce Application: Power Generation, Vehicle Fuel, Heating, Aviation |
| Companies Covered | Shell, TotalEnergies, BP, Eni, Equinor, OMV Petrom, Galp Energia, Hellenic Petroleum, Neste, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refined Petroleum Products Market Shifts & Advancements
Refinery configuration decisions now pivot on carbon intensity metrics rather than crude flexibility alone, compressing the planning horizon for major capital projects. Technology vendors and process licensors are repositioning around biofuel integration packages.
Co-processing technology is consolidating refinery competitive positions across Europe. Units that can simultaneously hydrotreat renewable feedstocks and conventional distillates command premium utilization rates. Shell and TotalEnergies have prioritized these retrofits at their Pernis and Antwerp complexes respectively. The technology is consolidating supply chains around dual-feed flexibility, marginalizing single-purpose fossil units.
REACH enforcement is tightening chemical disclosure requirements for fuel additives and blending components. ECHA's authorization list expansion forces reformulators to substitute legacy substances with registered alternatives. The F-Gas Regulation's phase-down schedule most affects refinery cooling and refrigeration systems, pushing operators toward ammonia and CO2-based alternatives in German and Dutch facilities.
Buyer concentration among large fleet operators is compressing contract structures toward index-linked pricing with sustainability certification requirements. Road transport and marine fuel procurement teams now mandate ISCC-EU or RSB chain-of-custody documentation. This shift is most visible in German commercial freight, where DB Schenker and DHL Supply Chain have centralized fuel purchasing with carbon accounting clauses.
Europe Refined Petroleum Products Market Segmentation
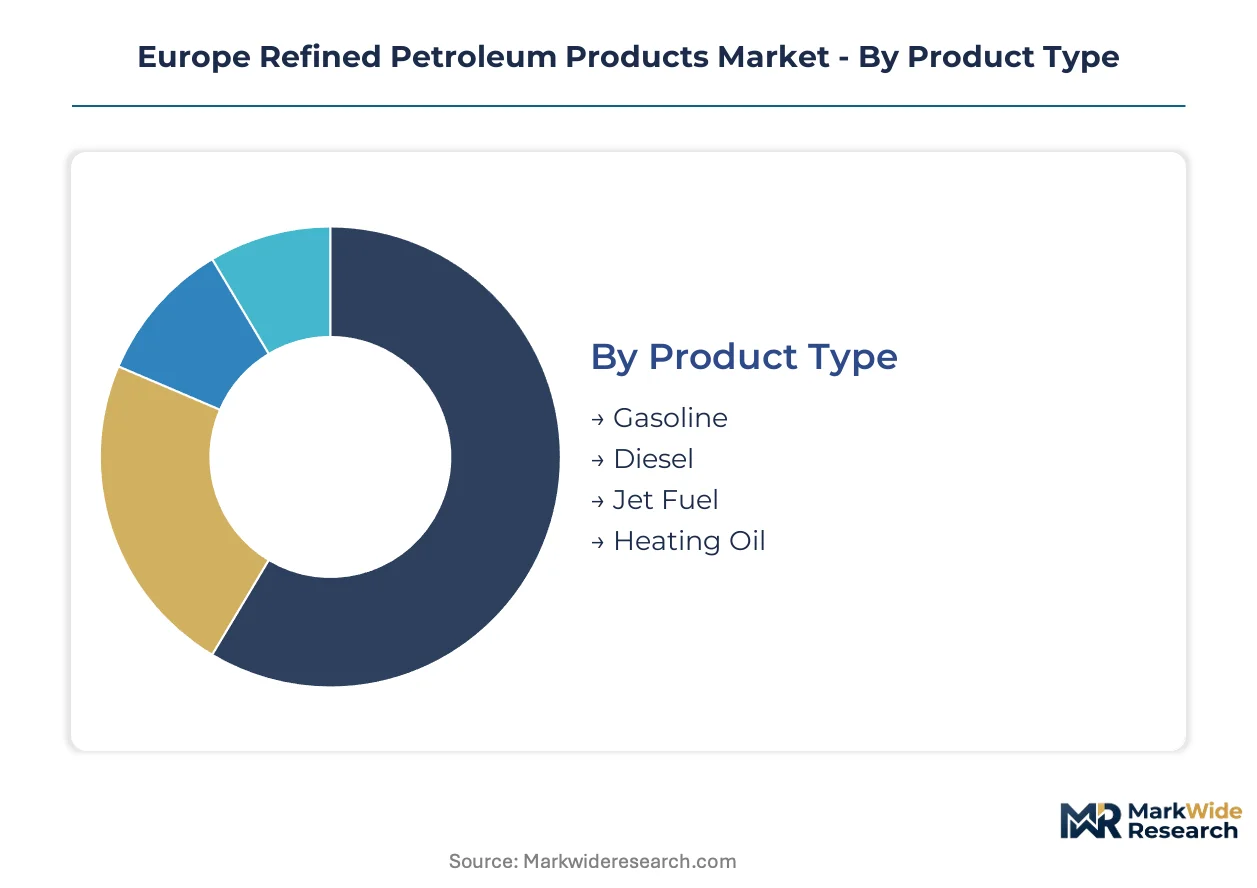
European refiners configure product slates around carbon intensity metrics and end-use specifications rather than crude flexibility alone. Segment boundaries blur as co-processing technology enables single units to serve multiple product categories with renewable feedstock blends.
Product Type:
Buyers prioritize cetane index, sulfur content, and renewable blending compatibility when selecting refined products for fleet operations.
- Gasoline:Light distillate with 95 RON octane ratings dominates European retail networks. German and French passenger vehicle fleets sustain volume leadership despite battery electric erosion in urban commuting corridors.
- Diesel:Middle distillate with 51+ cetane index commands structural importance in commercial freight and industrial power generation. Demand concentrates in German logistics corridors where long-haul trucking and rail freight resist electrification.
- Jet Fuel:Kerosene-range distillate meeting Jet A-1 specifications for turbine combustion. Aviation recovery at Amsterdam Schiphol and Frankfurt hubs drives offtake acceleration.
- Heating Oil:Residual fuel oil and gasoil blends for residential and commercial boiler systems. German and Polish building stock sustains seasonal demand peaks.
Volume sits with diesel; growth tilts toward jet fuel.
End User:
Carbon accounting requirements and fuel procurement centralization reshape how refiners segment their customer base.
- Transportation:Fleet operators and logistics providers purchasing road, rail, and marine fuels. DB Schenker and DHL Supply Chain in Germany mandate ISCC-EU chain-of-custody documentation with carbon intensity clauses.
- Residential:Household consumers procuring heating oil and LPG for space conditioning. Polish and German rural building stock outside district heating networks sustains this segment.
- Industrial:Manufacturing facilities burning fuel oil and naphtha for process heat and feedstock. German chemical parks and Rotterdam refinery complexes anchor demand concentration.
- Commercial:Retail fuel stations, airports, and marine bunkering terminals serving downstream consumers. Rotterdam's storage hub attracts marine fuel upgrading activity from this buyer class.
Transportation commands revenue concentration; commercial buyers drive margin expansion through sustainability certification premiums.
Distribution Channel:
Supply chain configuration determines working capital intensity and price discovery mechanisms for each channel.
- Retail:Branded service stations and motorway corridor outlets selling packaged fuels to consumers. Poland's underpenetrated premium fuel branding creates whitespace for integrated marketers.
- Wholesale:Bulk terminals and distributors supplying independent retailers and commercial accounts. Rotterdam and Antwerp storage terminals concentrate wholesale liquidity.
- Direct Supply:Refinery-to-consumer contracts for large industrial and aviation offtakers. Long-term index-linked structures with carbon clauses dominate this channel.
- E-commerce:Digital platforms for fuel card management and fleet procurement optimization. German commercial freight operators pilot centralized purchasing through these interfaces.
Wholesale handles volume throughput; direct supply captures value through term contracting.
Application:
End-use specifications dictate refinery configuration investments and product quality differentiation.
- Power Generation:Fuel oil and diesel combustion in industrial boilers and backup generators. German industrial parks and Polish manufacturing zones sustain demand.
- Vehicle Fuel:Gasoline and diesel for internal combustion engines across light-duty and heavy-duty categories. KBA emission standards constrain sulfur specifications and benzene limits.
- Heating:Residential and commercial space conditioning through oil-fired boilers. Seasonal demand peaks align with Central European winter severity.
- Aviation:Turbine fuel for commercial and cargo aircraft operations. EU ReFuelEU Aviation regulation mandates sustainable aviation fuel blending quotas.
Vehicle fuel retains volume dominance; aviation applications expand most quickly through regulatory mandate support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's storage and blending hub concentrates marine fuel upgrading activity, drawing capital deployment from refiners reconfiguring for lower-carbon product slates. The Netherlands anchors European refined product flows through this port complex.
Germany
German chemical parks sustain high-purity naphtha offtake for petrochemical derivatives. The KBA enforces vehicle emission standards that constrain diesel sulfur specifications and gasoline benzene limits. The Rhine-Ruhr corridor hosts refinery complexes integrating hydrogen retrofit investments.
Netherlands
Rotterdam's terminal infrastructure handles very low sulfur fuel oil blending for IMO 2020 compliance. The EU ETS carbon pricing framework directs capital toward carbon capture retrofits at Dutch refining sites. The Port of Rotterdam anchors marine fuel upgrading capacity serving North Sea shipping lanes.
France
French aviation hubs drive jet fuel demand acceleration as long-haul route expansion outpaces other transport modes. The DGEC implements national biofuel blending mandates that alter refinery product economics. The Le Havre-Paris corridor concentrates refining capacity serving domestic and export markets.
Belgium
Antwerp's storage terminals concentrate wholesale liquidity for middle distillate distribution. REACH compliance requirements govern chemical substance registration in blended fuel additives processed through Belgian facilities. The Antwerp-Rotterdam pipeline corridor enables integrated product flows between refining centers.
Poland
Limited premium fuel branding and convenience retail integration create whitespace for integrated marketers. Polish manufacturing zones sustain seasonal heating oil demand peaks outside district heating networks. The Warsaw-Łódź corridor presents motorway corridor opportunities for retail network expansion.
Europe Refined Petroleum Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across biofuel co-processing capability and carbon intensity certification. The European refining sector consolidates around integrated majors with chemicals integration and standalone renewable specialists with hydrotreating expertise. Three archetypes dominate: integrated oil majors with downstream-chemicals footprints, pure-play renewable fuel specialists, and national oil companies with regional supply mandates. Capacity reinvestment and strategic partnerships constitute the dominant competitive vectors as players position for EU Green Deal compliance.
Within the integrated major tier, Shell and TotalEnergies exemplify the refining-chemicals integration archetype, leveraging coastal complex positions to sustain naphtha and middle distillate supply chains. Neste occupies a distinct position as the renewable specialist archetype, competing through hydrotreated renewable diesel capacity expansion rather than conventional crude processing. These three anchors represent the strategic positioning spectrum from fossil-integrated to biofuel-pure competitive models.
| Leading Market Players |
|---|
| Shell |
| TotalEnergies |
| BP |
| Eni |
| Equinor |
| OMV Petrom |
| Galp Energia |
| Hellenic Petroleum |
| Neste |
| Others |
Supply & Pricing Matrix
Co-processing technology retrofits at Dutch and German refineries simultaneously compress unit operating costs and concentrate supply leverage among integrated majors capable of dual-feed hydrotreating. This production-method transition rewards facilities with renewable feedstock access while marginalizing single-purpose fossil units unable to blend conventional and bio-derived streams.
Pricing Analysis
Carbon intensity certification anchors value-based pricing structures across European refined product markets. Three-tier pricing structure across ISCC-EU certified renewable, conventional low-sulfur, and economy-grade residual products separates premium tiers from commodity grades. Cost compression in gasoline is intensifying because battery electric vehicle penetration erodes light-duty transport demand faster than refinery run cuts offset. Fleet operators purchasing through direct supply contracts exhibit lowest price sensitivity due to sustainability mandate compliance requirements, while independent retailers in wholesale channels face highest margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with seaborne crude feedstock dependence from OPEC+ origins and Russian-alternative suppliers. European refining capacity draws from crude imports originating in Norway, the United Kingdom, and West African basins, with intermediate feedstocks sourced from Middle Eastern and US Gulf Coast exporters. Tariff exposure on catalyst and specialty chemical imports strains working capital for hydrotreater maintenance cycles. Distribution runs through Rotterdam and Antwerp storage terminals concentrating wholesale liquidity before rail and barge dispersal to inland markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European refined petroleum product markets operate under supply-constrained conditions where hydrotreater co-processing capacity limits renewable diesel and sustainable aviation fuel output, propping margin structures for qualified producers.
For Market Incumbents: Hedge conventional fuel margin erosion by accelerating biofuel co-processing retrofits at Pernis and Antwerp-scale complexes before EU ETS carbon pricing deepens cost disadvantages for fossil-only units. Prioritize backward integration into renewable feedstock aggregation networks securing ISCC-EU certified supply chains. Defend position against pure-play renewable specialists through chemicals integration sustaining naphtha derivative offtake. For New Entrants and Emerging Players: Enter via Poland's underpenetrated premium fuel retail corridor where limited convenience retail integration creates whitespace for branded motorway network expansion. Target sustainable aviation fuel production leveraging guaranteed offtake pools under ReFuelEU Aviation mandates. Pursue tolling arrangements with existing hydrotreating capacity rather than greenfield construction given capital intensity barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated majors seeking co-processing capability and renewable certification expertise. Long-term viability favors assets with coastal complex positions enabling marine fuel blending and carbon capture retrofit potential. Watch EU carbon border adjustment mechanism implementation timing as inflection indicator for conventional refinery stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Co-processing Retrofit | Enables Shell and TotalEnergies facilities to simultaneously process renewable feedstocks and conventional distillates. |
| Renewable Feedstock Supply Agreement | Secures ISCC-EU certified waste oil and fat streams for Neste-scale renewable diesel production. |
| Carbon Capture Installation | Positions Dutch refineries for EU ETS compliance cost reduction through Port of Rotterdam cluster infrastructure. |
| Sustainable Aviation Fuel Capacity Buildout | Captures ReFuelEU Aviation mandated blending quotas at Frankfurt and Amsterdam Schiphol hub airports. |
| Retail Network Expansion | Exploits whitespace in Poland's motorway corridor fuel stations lacking premium branding integration. |
Research Methodology
Independent corroboration across refinery operations executives, marine fuel procurement managers, and biofuel trading specialists underwrites the qualitative findings, validated against EU ETS registry data, customs import records, and SEC filings from integrated majors. Bottom-up capacity utilization assessments triangulate with top-down demand modeling across transportation, industrial, and residential segments.
Comparable-period anchoring to historical refinery run rates and product slate configurations establishes baseline trajectory assumptions across the analysis window. Segmentation dimensions include product type, end-use application, distribution channel, and renewable content tier, with CAGRs derived from elasticity-adjusted demand projections and capacity expansion schedules. Forecast inputs incorporate EU Green Deal regulatory trajectory and aviation recovery patterns at hub airports.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crude supply disruption scenarios or accelerated electric vehicle penetration in German passenger vehicle markets. Forecasts reflect documented assumptions regarding carbon pricing trajectory and biofuel mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Oil Shale Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Naphtha Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Global Petroleum Coke Market