
 CHPTAC Market | 2026-2036
CHPTAC Market Size, Share, and Industry Trends Forecast 2026-2036
CHPTAC Market Intelligence
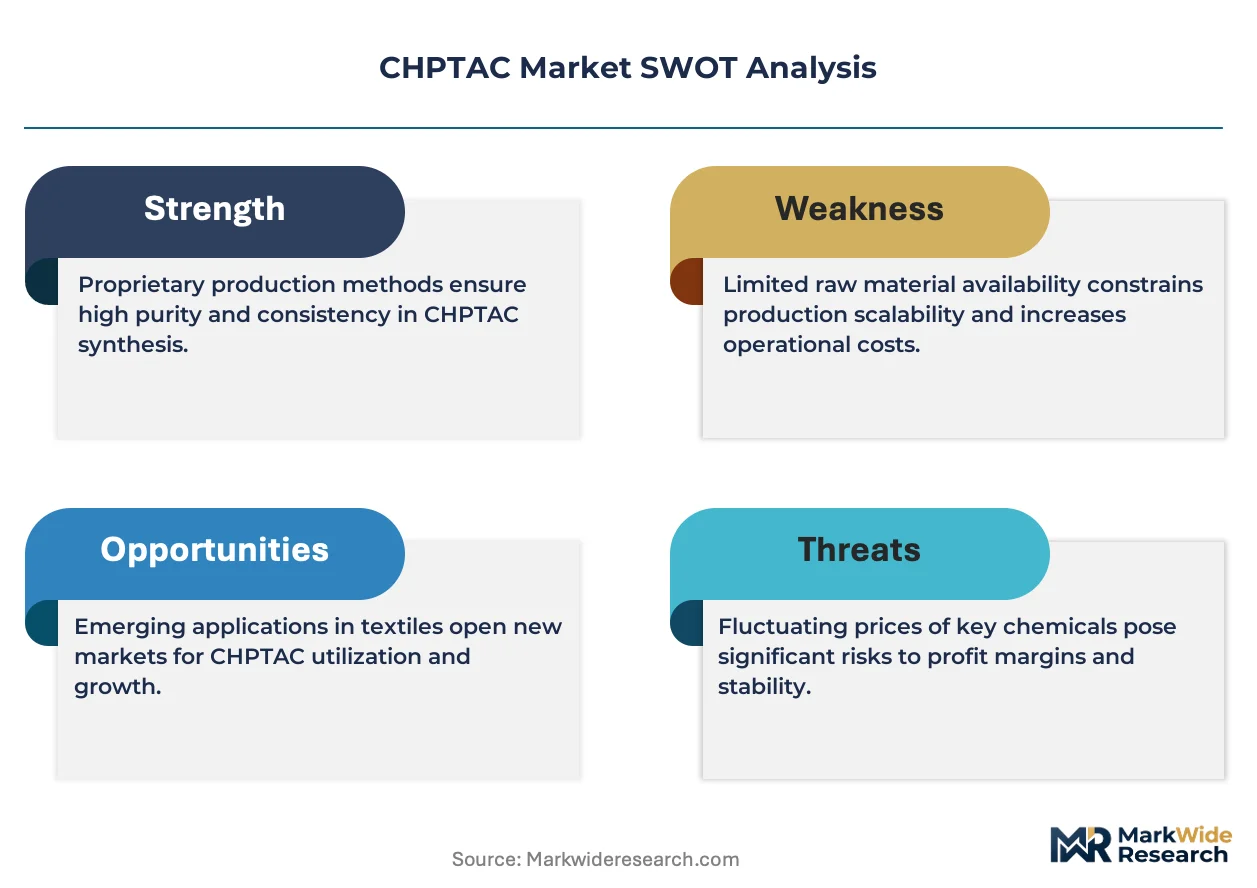
Specialty paper mills and coating industries is reorganizing procurement priorities around higher-purity cationic starch modifiers. Dow anchors North American supply through captive epichlorohydrin integration and dedicated quaternary ammonium production lines. Shandong Tiancheng Wanfeng Chemical dominates Shandong province output, leveraging coastal logistics to serve Korean and Japanese paper chemical distributors. Merck KGaA differentiates in reagent-grade segments where pharmaceutical and analytical laboratories require batch-certified material.
CHPTAC (3-chloro-2-hydroxypropyltrimethylammonium chloride) functions as a quaternary ammonium cationization agent, typically supplied as an aqueous solution with active content ranging from sixty to sixty-five percent by weight, reacting with hydroxyl or amino groups to impart permanent cationic charge. Paper manufacturing consumes the largest volume share as mills substitute cationic starch for synthetic retention aids under freshwater discharge constraints. Water treatment represents the fastest-expanding application as municipal plants deploy cationic polyelectrolytes for sludge dewatering. High-purity CHPTAC commands premium positioning in cosmetics formulation where residual epichlorohydrin limits must meet personal care safety standards.
EPA effluent guidelines and OSHA process safety management requirements govern US manufacturing and downstream handling protocols. REACH registration and the EU Green Deal chemical sustainability criteria constrain European import sourcing and favor domestic producers with full substance dossiers. China's MEE emission standards and GB chemical safety codes shape plant operating permits in Shandong and Jiangsu provinces. Stakeholders must track regulatory divergence between jurisdictions where purity specifications and byproduct thresholds are tightening at uneven speeds.
Market Dynamics
Freshwater discharge constraints at paper mills are accelerating substitution toward cationic starch systems, tightening purity specifications for quaternizing agents across North American and European supply chains.
Growth Catalysts
- EPA effluent guidelines:United States paper manufacturers face mandated reductions in synthetic retention aid discharge, driving volume demand for cationic starch modifiers that rely on CHPTAC quaternization chemistry.
- Sludge dewatering expansion:Municipal water treatment utilities across Asia are scaling cationic polyelectrolyte programs to meet tightening biosolids management requirements.
- Shandong chemical corridor concentration:Integrated producers in eastern China's coastal manufacturing belt achieve cost efficiencies through captive epichlorohydrin supply and direct port access to Korean and Japanese distributors.
Market Restraints
- Epichlorohydrin cost volatility:Feedstock price swings tied to propylene and chlorine markets compress margin stability for non-integrated quaternary ammonium producers.
- REACH registration barriers:European importers lacking full substance dossiers face exclusion from industrial-grade supply contracts as ECHA enforcement tightens.
- Residual impurity limits:Personal care formulators reject standard-grade material due to stringent residual epichlorohydrin thresholds, fragmenting addressable volume pools.
Strategic Opportunities
- High-purity cosmetics grade:Batch-certified reagent segments command premium positioning where pharmaceutical and analytical laboratories require documented impurity profiles.
- EU Green Deal chemical sustainability criteria:Domestic European producers with verified low-carbon process credentials gain preferential procurement status from sustainability-mandated buyers.
- Direct mill supply contracts:Specialty paper manufacturers are bypassing chemical distributors to secure dedicated quaternizing agent supply with customized active content specifications.
Industry Challenges
- Process safety management compliance:OSHA requirements for handling reactive quaternization chemistry demand specialized engineering controls and documented hazard analysis protocols.
- Quality certification timelines:Pharmaceutical-grade batch certification requires extended analytical validation cycles that strain working capital for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CHPTAC Market |
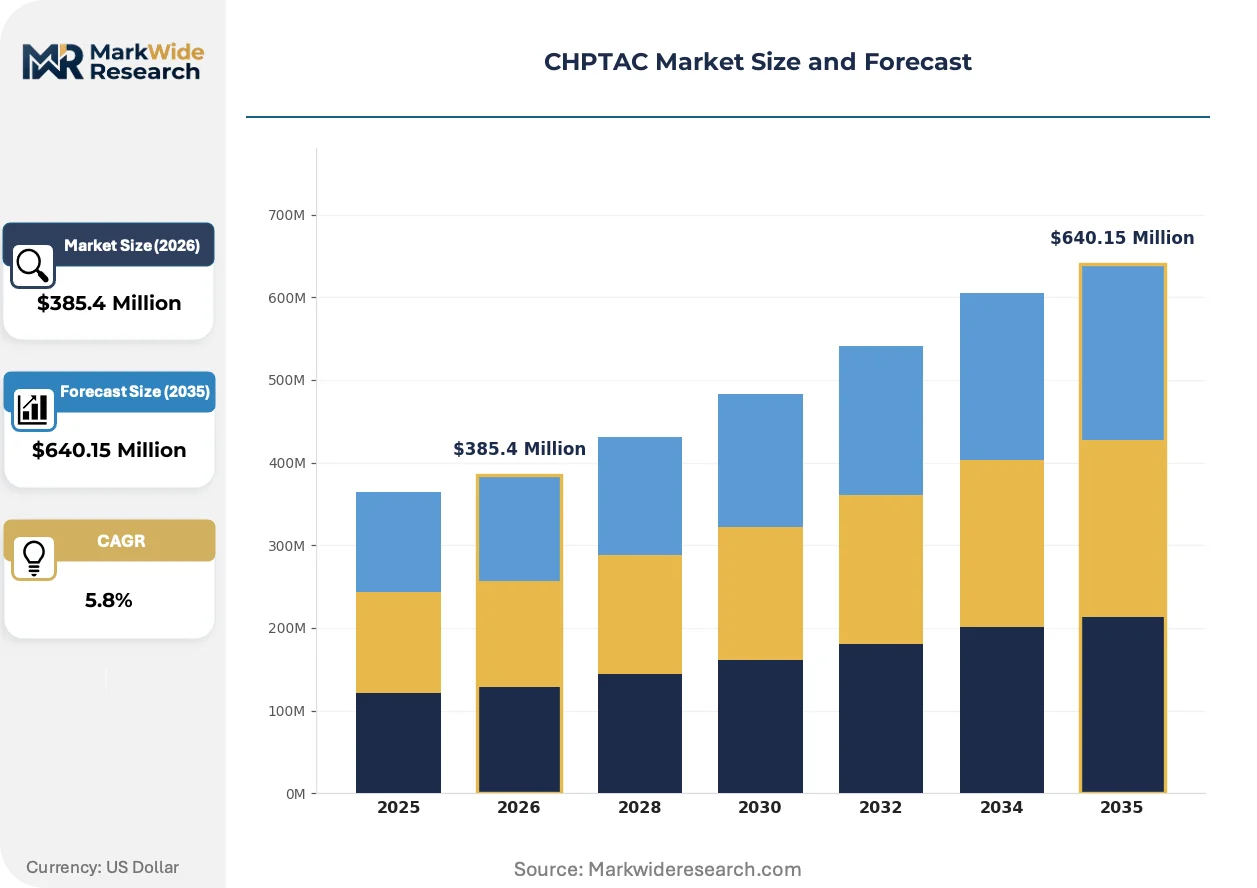
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity CHPTAC, Reagent Grade, Technical Grade, Stabilized Form, Anhydrous Form Application: Water Treatment, Textile Finishing, Paper Manufacturing, Adhesive Production, Cosmetics Formulation End User Industry: Chemical Manufacturers, Textile Producers, Paper Mills, Personal Care Companies, Coating Industries Packaging Type: Drums, Bulk Bags, Intermediate Bulk Containers, Bottles, Carboys |
| Companies Covered | Dow, Shanghai Baijin Chemical Group Co., Ltd., Merck KGaA, Shandong Tiancheng Wanfeng Chemical Co., Ltd., Dongying J&M Chemical Co., Ltd, Arkema Group, Parchem Fine & Specialty Chemicals, Jiangsu Jinshan Chemical Co. Ltd., Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CHPTAC Market Strategic Shifts & Innovations
Continuous-flow reactor technology is reshaping production economics while regulatory divergence between jurisdictions is fragmenting specification standards across end-use segments.
Membrane-based purification systems for aqueous CHPTAC solutions are decomposing the traditional distillation-dominated cost structure for high-purity grades. European reagent suppliers are adopting these systems fastest to meet REACH-registered purity dossiers. The technology is decomposing capital barriers that previously locked premium segments to established incumbents with legacy thermal separation assets.
China's MEE emission standards are tightening volatile organic compound thresholds for Shandong and Jiangsu province chemical plants. Facilities must retrofit scrubber systems and upgrade wastewater treatment to maintain operating permits. Integrated producers with captive utilities are absorbing compliance costs more readily than toll manufacturers, accelerating consolidation in coastal manufacturing corridors.
Specification-driven procurement is compressing supplier qualification cycles as paper mills consolidate chemical vendor lists under centralized procurement functions. Distributors serving mid-size coating operations are losing share to direct mill contracts and integrated producer channels. This pattern is most pronounced in North American specialty paper segments where freshwater discharge constraints have elevated cationic starch to critical process chemistry status.
CHPTAC Market Segmentation
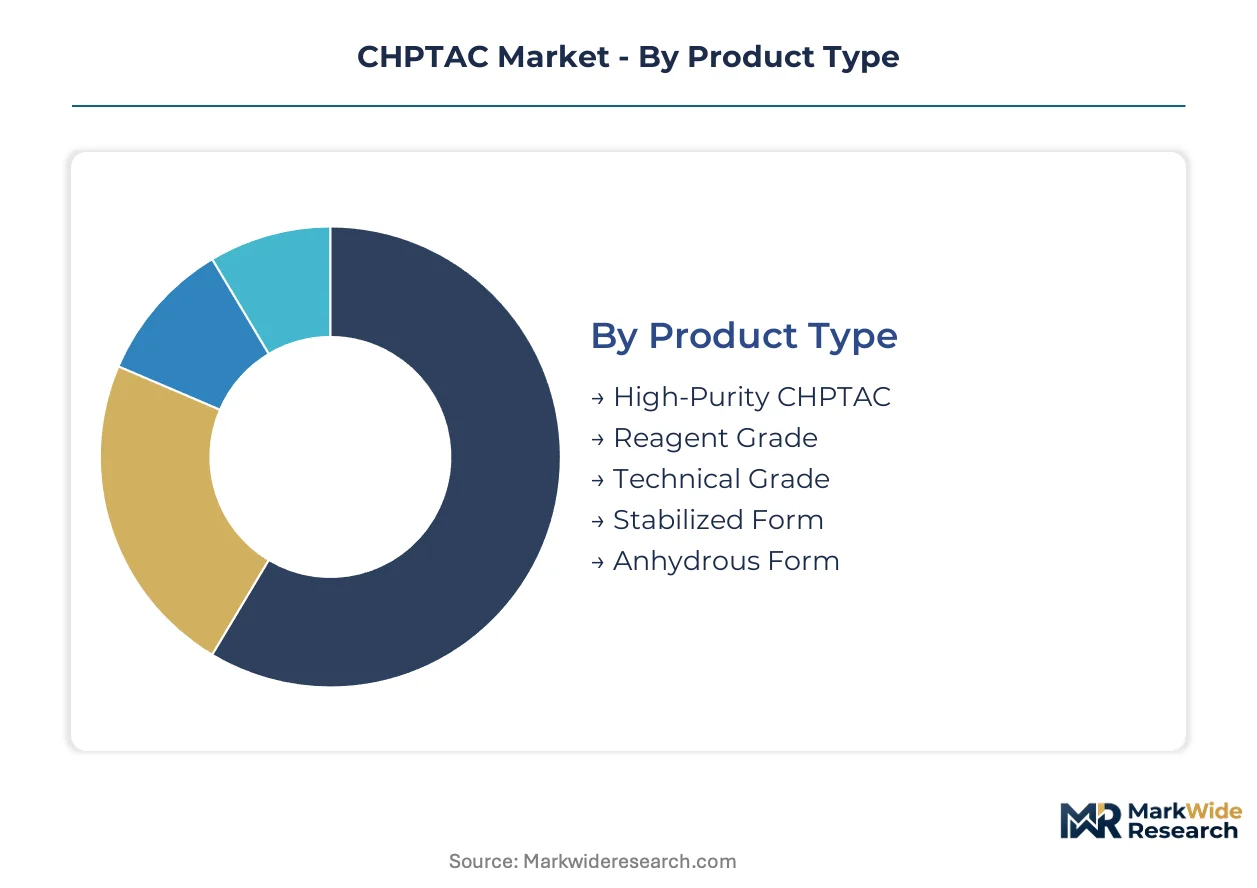
CHPTAC specification tiers fragment procurement channels across industrial and specialty segments. Purity gradients determine whether material flows through distributor networks or direct mill contracts.
Product Type:
High-purity grades command dedicated logistics channels with batch documentation, while technical grades move through commodity chemical distributors serving multiple end-uses.
- High-Purity CHPTAC:Aqueous solutions with active content exceeding sixty-five percent and residual epichlorohydrin below pharmaceutical thresholds. Paper mills in the United States and Germany source this grade through direct contracts to meet EPA and ECHA discharge documentation requirements.
- Reagent Grade:Batch-certified material with full impurity profiling for analytical and pharmaceutical laboratory applications. European reagent suppliers deploy membrane purification systems to satisfy REACH-registered dossier demands from Merck KGaA and comparable distributors.
- Technical Grade:Standard sixty percent active content solutions for industrial cationization. Chinese coastal producers supply Korean and Japanese paper chemical distributors through Shandong port logistics.
- Stabilized Form:Additive-enhanced formulations extending shelf life for tropical climate distribution. Southeast Asian textile finishers favor this grade where storage infrastructure limits temperature control.
- Anhydrous Form:Concentrated solid-phase material reducing transport costs for remote water treatment installations. Municipal utilities in western China specify this packaging where aqueous freight economics prove prohibitive.
By volume, Technical Grade leads. By growth pace, High-Purity CHPTAC is expanding most quickly.
Application:
Application mix determines active content specifications and residual impurity limits that suppliers must certify.
- Water Treatment:Cationic polyelectrolyte production for municipal sludge dewatering. Asian utilities in China and South Korea scale programs under tightening biosolids regulations from MEE and MFDS.
- Textile Finishing:Cotton cationization for reactive dye fixation. Eastern China's manufacturing corridor consumes volume through integrated chemical producers supplying domestic fabric processors.
- Paper Manufacturing:Cationic starch modification replacing synthetic retention aids. North American specialty mills drive specification tightening as freshwater discharge constraints elevate process chemistry criticality.
- Adhesive Production:Pressure-sensitive and packaging adhesive cationization. European formulators face EU Green Deal chemical sustainability criteria favoring low-carbon process credentials.
- Cosmetics Formulation:Hair conditioning and personal care applications with stringent residual epichlorohydrin limits. Personal care companies reject standard-grade material, fragmenting addressable volume pools.
Paper Manufacturing dominates current offtake. Water Treatment climbs fastest on municipal infrastructure expansion.
End User Industry:
Customer scale and technical capability determine whether procurement flows through distributors or direct producer relationships.
- Chemical Manufacturers:Intermediate producers integrating CHPTAC into formulated cationic polymers. Shandong Tiancheng Wanfeng Chemical anchors supply to downstream paper chemical distributors.
- Textile Producers:Fabric finishers operating batch cationization processes. Chinese and Indian mills source through regional distributors with technical service support.
- Paper Mills:Integrated producers and specialty manufacturers with centralized procurement functions. North American mills consolidate vendor lists under freshwater discharge compliance pressures.
- Personal Care Companies:Formulators requiring documented impurity profiles and batch certification. Pharmaceutical-grade validation cycles strain working capital for smaller suppliers serving this segment.
- Coating Industries:Surface treatment and functional coating applications. Mid-size coating operations lose share to direct mill contracts as specification-driven procurement compresses supplier qualification cycles.
Paper Mills absorb the largest volume share. Personal Care Companies pay the steepest premium for certification compliance.
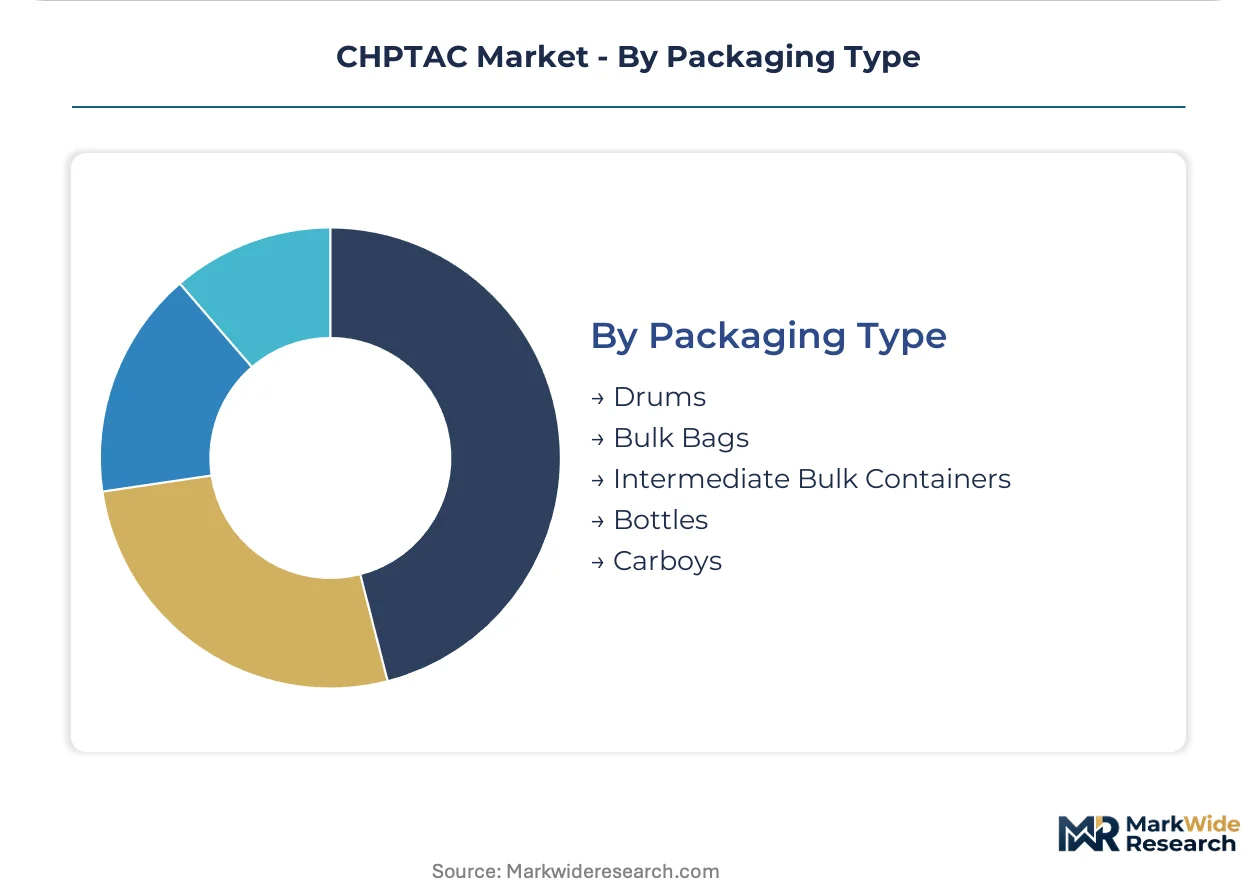
Packaging Type:
Packaging economics align with shipment scale and handling infrastructure at destination facilities.
- Drums:Standard two-hundred-liter steel and polyethylene containers for multi-ton industrial orders. Paper mills with bulk storage capacity receive drum shipments through established chemical distributors.
- Bulk Bags:Flexible intermediate bulk containers for anhydrous solid grades. Remote water treatment utilities in western China favor this format where aqueous freight costs escalate.
- Intermediate Bulk Containers:One-thousand-liter totes for medium-scale cationic polymer producers. Chemical manufacturers in eastern China's coastal corridor deploy IBCs for just-in-time inventory management.
- Bottles:Laboratory-scale packaging for reagent grade validation and sampling. European analytical laboratories require this format for initial batch certification before drum-scale commitment.
- Carboys:Pressurized and vented containers for stabilized formulations. Southeast Asian textile finishers specify carboys where tropical climate storage demands enhanced containment.
Drums move the highest tonnage. Intermediate Bulk Containers gain share fastest on just-in-time adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex underwrites China's dominance in CHPTAC export logistics, handling bulk chemical shipments to Korean and Japanese paper chemical distributors with direct vessel access from Shandong manufacturing clusters.
United States
Specialty paper mills in Wisconsin and Maine drive cationic starch substitution programs under EPA effluent guidelines. OSHA process safety management requirements govern reactive quaternization handling protocols at Gulf Coast production facilities. Integrated producers with captive epichlorohydrin supply anchor supply security for domestic retention aid manufacturers.
Germany
REACH-registered purity dossiers constrain import sourcing for industrial-grade CHPTAC contracts. EU Green Deal chemical sustainability criteria favor domestic producers with verified low-carbon process credentials. Merck KGaA anchors reagent-grade supply from Darmstadt facilities serving pharmaceutical and analytical laboratory segments.
China
Shandong province chemical manufacturing corridor concentrates integrated output with coastal logistics to Asian paper chemical markets. MEE emission standards tighten volatile organic compound thresholds for Jiangsu and Shandong facilities. Shandong Tiancheng Wanfeng Chemical leverages direct port access to supply Korean and Japanese distributors.
South Korea
Municipal water treatment utilities scale cationic polyelectrolyte programs under MFDS biosolids management requirements. Paper manufacturers in Gyeonggi-do province import high-purity grades for retention aid substitution. Busan-Ulsan chemical processing belt hosts downstream cationic polymer formulation for textile and coating applications.
Japan
Textile finishers in Osaka prefecture consume stabilized CHPTAC formulations for cotton cationization processes. METI chemical safety codes govern handling protocols at Kansai region polymer production facilities. Tokyo-based paper chemical distributors qualify Chinese suppliers against JIS purity specifications for specialty coating applications.
CHPTAC Market Key Industry Players
Listed leaders compete with private specialists across integrated feedstock control, with public chemical conglomerates facing off against family-held manufacturers in coastal China. The vendor base separates into three tiers: multinational diversified chemicals with captive epichlorohydrin, Chinese provincial specialists with port logistics advantages, and reagent-grade purveyors serving pharmaceutical certification segments. Strategic moves concentrate on backward integration into epichlorohydrin supply and membrane purification technology licensing for high-purity grade expansion.
Within the multinational tier, Dow exemplifies integrated supply chain control through North American epichlorohydrin assets. Shandong Tiancheng Wanfeng Chemical occupies a position among Chinese coastal specialists leveraging Qingdao port access. Merck KGaA anchors the reagent-grade vector where batch-certified material commands pharmaceutical and analytical laboratory positioning.
| Leading Market Players |
|---|
| Dow |
| Shanghai Baijin Chemical Group Co., Ltd. |
| Merck KGaA |
| Shandong Tiancheng Wanfeng Chemical Co., Ltd. |
| Dongying J&M Chemical Co., Ltd |
| Arkema Group |
| Parchem Fine & Specialty Chemicals |
| Jiangsu Jinshan Chemical Co. Ltd. |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day order-to-delivery cycles for high-purity CHPTAC shipments from Shandong province to European paper mills concentrate pricing power with integrated producers possessing captive epichlorohydrin assets and direct port access. This lead-time band compresses margin flexibility for non-integrated toll manufacturers while rewarding backward-integrated coastal Chinese specialists with volume-discount leverage over Korean and Japanese distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates CHPTAC procurement, with high-purity grades certified for pharmaceutical applications commanding substantial premia over technical-grade material. Price differentiation hinges on residual epichlorohydrin thresholds and batch documentation depth, while cost compression in standard industrial grades intensifies as Shandong producers expand membrane purification capacity. Paper mills with centralized procurement functions exhibit lowest price sensitivity; mid-size coating operations face highest margin pressure.
Supply Chain Analysis
Qingdao port congestion and vessel scheduling constraints constitute the primary logistics chokepoint governing CHPTAC export flows to Korean and Japanese paper chemical distributors. Supply concentrates in China, Germany, and the United States, with production drawing from captive epichlorohydrin supply or merchant propylene-chlorine feedstock markets. Tariff exposure on Chinese-origin material into European Union markets fragments sourcing strategies. Distribution runs through direct mill contracts for high-volume North American and European buyers, while Asian markets retain distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American specialty paper mills consolidating vendor lists under EPA freshwater discharge compliance pressures, shifting procurement leverage toward direct producer relationships and away from chemical distributors.
For Market Incumbents: Shield margin position by securing captive epichlorohydrin supply through backward integration or long-term offtake agreements with propylene-chlorine producers. Invest in membrane purification technology licensing to defend high-purity grade positioning against emerging Chinese competitors with lower-cost process credentials. For New Entrants and Emerging Players: Differentiate on reagent-grade batch certification capabilities serving pharmaceutical and analytical laboratory segments where Merck KGaA and comparable incumbents face capacity constraints. Target Southeast Asian textile finishers with stabilized formulation packaging suited to tropical climate storage limitations, deploying carboy-format distribution through regional chemical distributors with technical service infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because membrane purification technology decomposes capital barriers previously locking premium segments to legacy thermal separation asset owners, creating acquisition opportunities among European reagent suppliers with REACH-registered dossiers but constrained working capital. Watch for inflection when MEE emission standard enforcement accelerates Shandong province facility consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Captive feedstock supply anchors margin stability against propylene-chlorine volatility for Dow and comparable integrated producers. |
| Membrane Purification Technology Licensing | European reagent suppliers deploy these systems to satisfy ECHA REACH-registered purity dossier requirements fastest. |
| Direct Mill Supply Contracting | Specialty paper manufacturers bypass distributors to secure dedicated quaternizing agent supply with customized active content specifications. |
| Stabilized Formulation Development | Southeast Asian textile finishers favor additive-enhanced grades where tropical climate storage infrastructure limits temperature control. |
| Green Manufacturing Certification | Domestic European producers with verified low-carbon process credentials gain preferential procurement status under EU Green Deal criteria. |
Research Approach
Cross-validation between primary interviews with plant managers at Shandong and Jiangsu province chemical facilities, procurement leads at North American specialty paper mills, and technical R&D directors at European reagent suppliers anchors the qualitative findings. Secondary validation draws from customs and trade data, American Chemistry Council and Cefic industry reports, and SEC 10-K filings from listed chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Sensitivity analysis across grade tier, end-use industry, packaging format, and regional production hub dimensions tests forecast robustness throughout the projection horizon. CAGRs derive from segmented growth rate aggregation and cross-referencing with downstream cationic starch and polyelectrolyte demand trajectories. Key inputs include EPA effluent guideline implementation timelines, MEE emission standard enforcement intensity, and membrane purification technology adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained freshwater discharge constraint tightening or epichlorohydrin feedstock price stability would require recalibration. Practitioners should keep alternative scenarios live as REACH dossier enforcement rigor and EU Green Deal chemical sustainability criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethanolamine Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Canada Methanol Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Hydrazine Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
1-Methylimidazole Market
Chemicals
Aluminium Chloride Market
Chemicals
China Inorganic Iodide Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Europe Tertiary Amines Market