
 Triethanolamine Market | 2026-2036
Triethanolamine Market Size, Share, and Industry Trends Forecast 2026-2036
Triethanolamine Market Analytics
Buyer concentration in personal care and cosmetics is recalibrating procurement dynamics across the triethanolamine value chain. BASF SE leverages its integrated ethylene oxide derivatives platform to sustain cost-advantaged supply positions in European cosmetic-grade markets. Dow Chemical Company anchors North American supply through its Gulf Coast ethylene chain infrastructure, while INEOS Group Limited competes on volume scale across industrial-grade segments in Atlantic markets.
Triethanolamine is a viscous organic compound produced via ethoxylation of ammonia with ethylene oxide, yielding a tertiary amine with three hydroxyethyl groups and a typical purity threshold of 99% for pharmaceutical and cosmetic applications. It functions primarily as a pH adjuster, emulsifier, and neutralizing agent across formulated chemical systems. Surfactants and emulsifiers represent the deepest margin pools given their technical specification intensity and customer stickiness, while agricultural chemicals and textile applications compete on volume throughput with thinner spreads. Cosmetic-grade material commands premium positioning over industrial-grade supply due to certification burdens and lot-traceability requirements.
EPA oversight of ethylene oxide emissions shapes facility siting and capital allocation for North American producers, while REACH registration obligations in Europe constrain import pathways for non-compliant Asian supply. FDA purity standards for pharmaceutical-grade triethanolamine create a bifurcated quality landscape that rewards certified manufacturers with durable customer lock-in. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where compliance costs will reshape competitive cost curves and sourcing patterns.
Market Dynamics
Ethylene oxide feedstock volatility and tightening emissions controls at production facilities are compressing operating margins and forcing capacity consolidation among merchant suppliers. REACH registration deadlines and EPA ethylene oxide emission limits are synchronizing to reshape facility economics.
Growth Catalysts
- Cosmetic formulation intensity:Personal care manufacturers are expanding triethanolamine procurement for emulsification in premium skincare lines, with pH balancing specifications tightening across EU and US cosmetic directives.
- REACH compliance deadlines:European chemical registration obligations are filtering non-compliant Asian supply from import channels, securing market position for registered producers.
- Agrochemical processing expansion:Domestic textile and crop protection chemical output in China is concentrating demand for industrial-grade material.
Market Restraints
- Ethylene oxide cost volatility:Feedstock price swings tied to naphtha-cracker economics transmit directly to triethanolamine production costs, squeezing margin stability for non-integrated producers.
- Supply concentration risk:Gulf Coast ethylene oxide infrastructure concentration exposes North American supply to hurricane-related disruption and EPA facility action.
- Monoethanolamine substitution:Alternative ethanolamines compete in select surfactant applications where lower pH adjustment intensity permits formulation flexibility.
Strategic Opportunities
- Pharmaceutical-grade certification:FDA purity standards for pharmaceutical applications create defensible premium positioning for manufacturers achieving lot-traceability compliance.
- Biobased ethylene oxide pathways:Ethanol-to-ethylene oxide technology convergence offers carbon-intensity reduction for sustainability-positioned cosmetic supply chains.
- Direct-to-formulator distribution:Bypassing traditional chemical distributor networks enables margin capture and technical service relationships with mid-sized personal care compounders.
Industry Challenges
- Specialized chemical engineering talent:Ethoxylation process expertise and regulatory compliance knowledge are concentrating at integrated majors, constraining operational expansion for independent producers.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and cosmetic GMP compliance creates 18-24 month product qualification cycles for new supply entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triethanolamine Market |
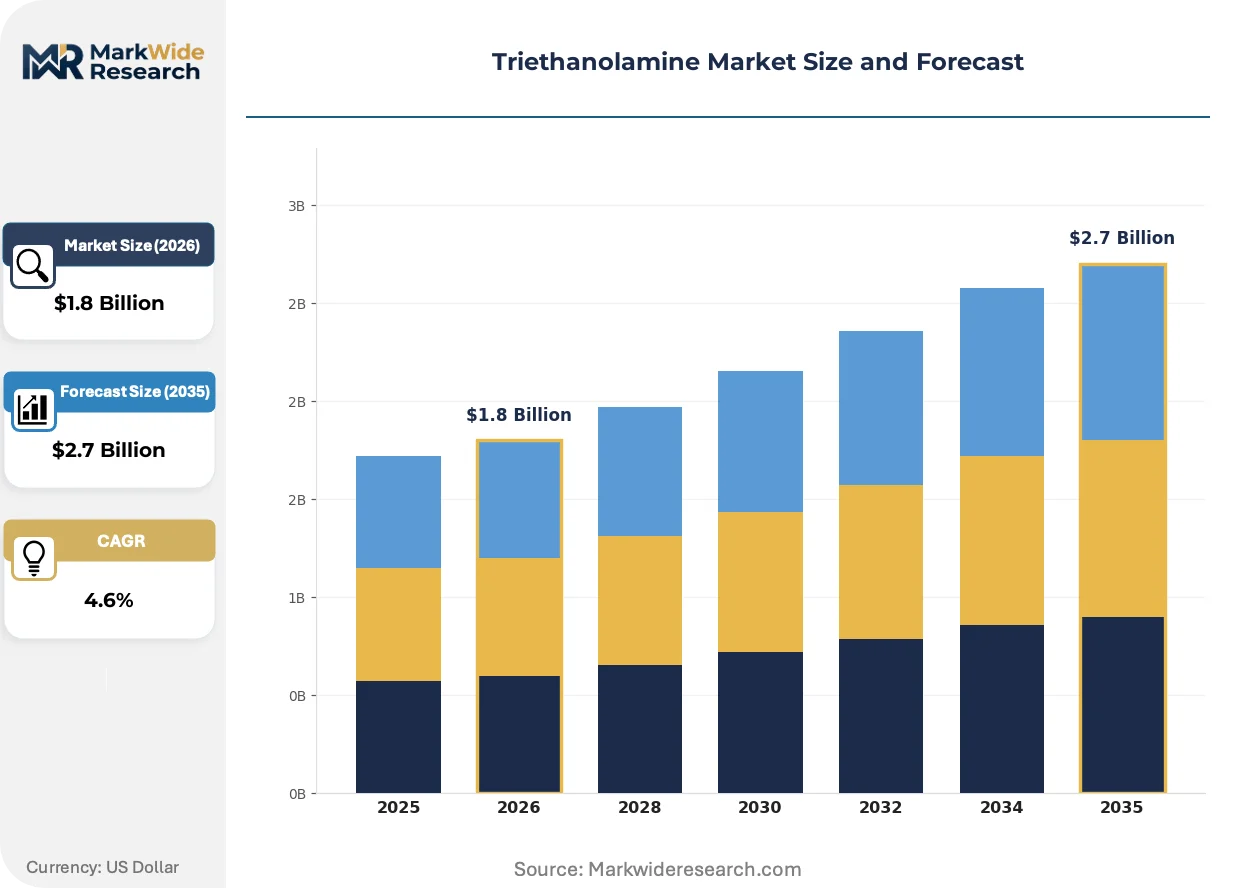
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Ingredients, Agricultural Chemicals, Pharmaceutical Intermediates, Surfactants Application: Personal Care, Agrochemicals, Textile, Emulsifiers End Use Industry: Cosmetics, Agriculture, Pharmaceuticals, Paints Grade: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Food Grade |
| Companies Covered | The Dow Chemical Company, BASF SE, INEOS Group Limited, Huntsman Corporation, Eastman Chemical Company, Akzo Nobel N.V., Nouryon, SABIC, TPC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triethanolamine Market Evolving Landscape
Process intensification and regulatory data transparency are converging to reshape how triethanolamine producers compete on specification breadth and supply assurance.
Continuous ethoxylation reactor technology is integrating into new capacity installations, replacing batchwise production with steady-state operation that tightens purity distribution and reduces ethylene oxide inventory exposure. Cosmetic-grade manufacturers in Germany and the United States are adopting these systems fastest. The technology is integrating quality assurance directly into production flow, compressing batch-release testing timelines.
REACH Article 33 supply chain communication obligations are mandating downstream disclosure of Substances of Very High Concern content, forcing triethanolamine distributors to maintain granular lot-level documentation. Formulators in personal care and pharmaceuticals now audit supplier data systems before contract award. European cosmetic compounders are responding by consolidating procurement to registered producers with established SCIP database compliance.
Specification-driven procurement is displacing spot-market purchasing for surfactant-grade material, with personal care formulators locking annual contracts to secure lot-traceability and audit rights. Traditional chemical distributors are losing volume to direct manufacturer relationships in premium segments. This pattern is most visible in France and California, where cosmetic GMP enforcement is strictest.
Triethanolamine Market Segmentation
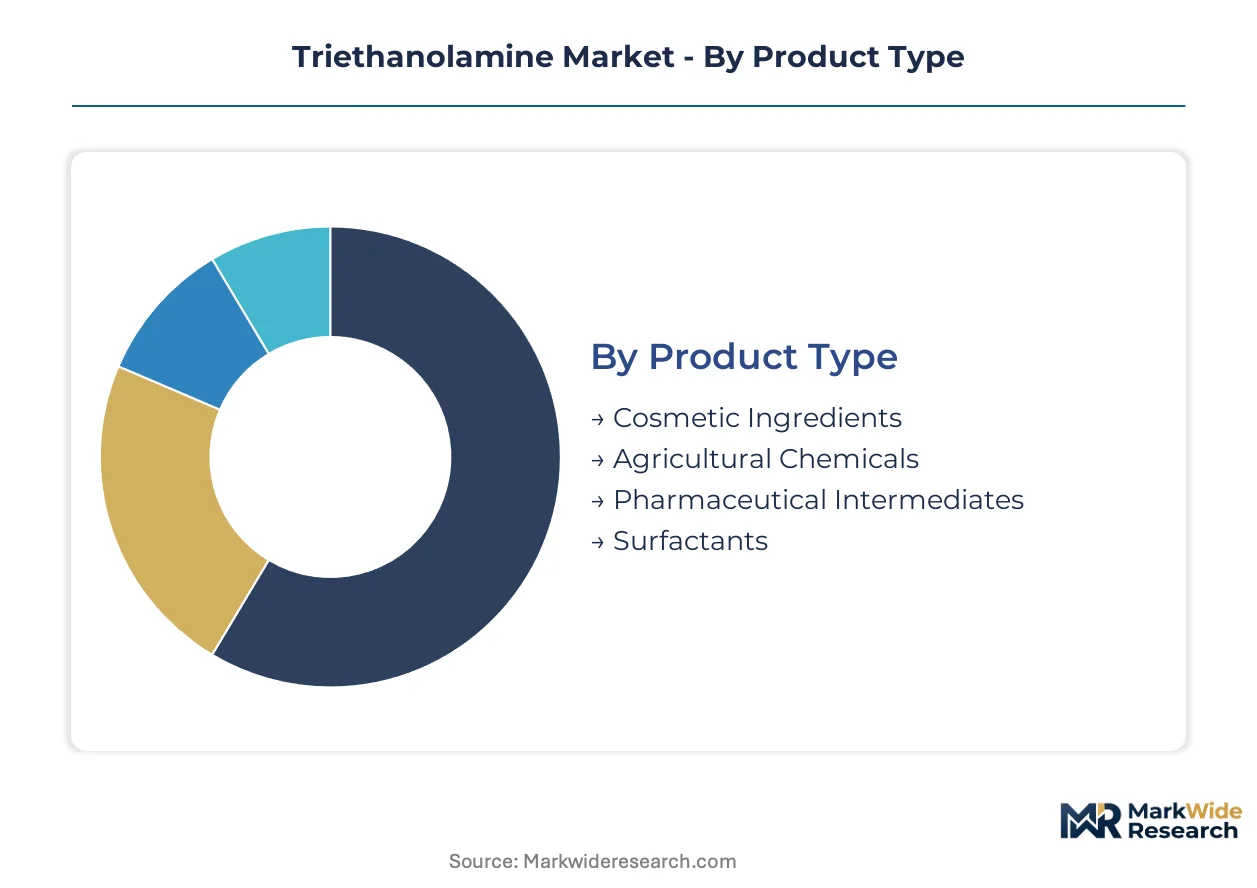
Triethanolamine procurement patterns diverge sharply across certification tiers, with FDA, REACH, and cosmetic GMP requirements creating distinct margin pools. Understanding these segmentation boundaries reveals where specification intensity translates into pricing power and customer lock-in.
Product Type:
FDA pharmaceutical standards and REACH cosmetic registration obligations split procurement channels across these four categories, with certification burden determining distributor eligibility.
- Cosmetic Ingredients:REACH-registered material commands premium positioning in EU personal care supply chains. pH balancing specifications for premium skincare lines in France and Germany concentrate demand here, with lot-traceability requirements filtering non-compliant Asian supply.
- Surfactants:Emulsification chemistry for formulated cleaning systems requires 99% purity thresholds. Industrial detergent compounders in the United States source through Gulf Coast ethylene oxide infrastructure, exposing procurement to hurricane disruption risk.
- Agricultural Chemicals:Crop protection formulation in China absorbs volume throughput at thinner spreads.
- Pharmaceutical Intermediates:FDA lot-release documentation creates 18-24 month qualification cycles for new suppliers.
Cosmetic Ingredients sits at the top of the volume ranking, with Surfactants climbing the fastest.
Application:
End-use formulators select triethanolamine based on pH adjustment intensity and emulsion stability requirements, with cost tier separating premium from commodity procurement.
- Personal Care:Premium skincare and haircare formulations require REACH-compliant material with SCIP database documentation. EU cosmetic directive enforcement in France and Germany has consolidated procurement to registered producers with established audit systems.
- Emulsifiers:Technical specification intensity peaks here, with continuous ethoxylation reactor technology tightening purity distribution. German and U.S. cosmetic-grade manufacturers adopted steady-state production fastest, compressing batch-release timelines.
- Agrochemicals:Volume-scale procurement in China concentrates on industrial-grade material for glyphosate and other crop protection chemistry.
- Textile:Fabric softener and dye leveling applications compete on throughput with thinner margin structures.
Emulsifiers captures the steepest expansion trajectory as specification-driven procurement displaces spot-market purchasing.
End Use Industry:
Customer type determines contract structure, with direct manufacturer relationships displacing traditional chemical distributors in premium segments.
- Cosmetics:Mid-sized personal care compounders in California and France now audit supplier data systems before contract award. Direct-to-formulator distribution enables margin capture and technical service relationships that distributors cannot match.
- Pharmaceuticals:FDA purity standards create durable customer lock-in for certified manufacturers. Lot-traceability requirements and pharmaceutical GMP compliance secure multi-year supply agreements.
- Agriculture:Domestic crop protection chemical output in China drives volume concentration at cost-competitive pricing.
- Paints:pH adjustment and pigment dispersion applications operate at industrial-grade specifications with commodity procurement patterns.
Cosmetics leads volume concentration, with Pharmaceuticals expanding most quickly on certification-driven contract migration.
Grade:
Margin structure stratifies across purity thresholds, with pharmaceutical and cosmetic grades commanding substantial premiums over industrial supply.
- Cosmetic Grade:REACH registration and EU cosmetic directive compliance create defensible market position. SCIP database obligations and Article 33 supply chain communication requirements force granular lot-level documentation that non-registered producers cannot supply.
- Pharmaceutical Grade:FDA certification and lot-traceability standards create the deepest margin pool. 99% purity thresholds and pharmaceutical GMP compliance secure multi-year agreements with compounders.
- Industrial Grade:Agrochemical and textile applications absorb volume at commodity pricing with thinner spreads.
- Food Grade:Limited application scope constrains segment scale relative to other certified grades.
Industrial Grade dominates volume throughput, with Pharmaceutical Grade gaining share fastest on certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs industrial-grade volumes at commodity spreads while the United States commands premium positioning through FDA-certified pharmaceutical supply chains. Germany anchors European cosmetic-grade procurement under REACH registration requirements. Each geography concentrates demand around distinct certification tiers and end-use applications.
United States
Gulf Coast ethylene oxide infrastructure supplies surfactant and personal care formulators across Texas and Louisiana. EPA emission limits at production facilities constrain merchant supply availability and compress operating margins for non-integrated producers. Houston-area chemical clusters concentrate pharmaceutical-grade certification capacity serving domestic compounders.
Germany
REACH-registered producers in the Rhine-Ruhr industrial region dominate EU cosmetic-grade supply chains. Continuous ethoxylation reactor technology adoption tightens purity distribution for premium skincare formulators in Frankfurt and Düsseldorf. ECHA compliance deadlines filter non-registered Asian imports from European procurement channels.
China
Domestic agrochemical and textile processing output in Jiangsu and Zhejiang provinces concentrates demand for industrial-grade material. MIIT industrial standards govern quality thresholds for crop protection chemical manufacturing. Yangtze River Delta chemical parks scale ethoxylation capacity to serve glyphosate and fabric softener compounders.
France
Cosmetic GMP enforcement in Paris and Lyon metropolitan areas consolidates procurement to registered producers with SCIP database compliance. ANSM oversight of pharmaceutical-grade material creates durable supplier lock-in for compounders serving EU markets. Premium skincare manufacturers in Île-de-France audit supplier data systems before contract award.
India
Domestic personal care manufacturing expansion in Maharashtra and Gujarat drives cosmetic-grade import demand. CDSCO pharmaceutical standards constrain local production qualification timelines for international suppliers. Mumbai-Pune chemical corridors absorb surfactant-grade volumes for detergent and cleaning product formulators.
Triethanolamine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market segments. The structure concentrates around integrated ethylene oxide derivatives platforms and merchant ethoxylation specialists. Three archetypes dominate: integrated petrochemical majors with captive feedstock, regional chemical distributors with formulation technical service, and pharmaceutical-grade certification specialists. Capacity consolidation and direct-to-formulator distribution represent the dominant competitive moves reshaping channel economics.
Among integrated petrochemical majors, BASF SE and The Dow Chemical Company exemplify archetype leaders with ethylene chain control. INEOS Group Limited occupies a position within the volume-scale industrial-grade tier. These three anchors represent how feedstock integration, geographic production positioning, and certification breadth stratify competitive standing across personal care, pharmaceutical, and agrochemical end-use segments.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| BASF SE |
| INEOS Group Limited |
| Huntsman Corporation |
| Eastman Chemical Company |
| Akzo Nobel N.V. |
| Nouryon |
| SABIC |
| TPC Group |
| Others |
Value Network & Pricing Analysis
Ethoxylation process engineers in the Rhine-Ruhr industrial corridor command wage premiums that compress margin spreads between cosmetic-grade and industrial-grade triethanolamine tiers. Labor-cost differentials between German continuous-reactor facilities and Chinese batch operations amplify pricing stratification across certification levels, with REACH compliance burdens adding fixed overhead that non-registered producers avoid.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for industrial-grade material, intensifying competition in agrochemical feedstock supply. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial levels reflects certification burden and lot-traceability requirements, with FDA-grade material commanding substantial premiums over commodity supply. Cost compression in surfactant-grade tiers stems from ethylene oxide feedstock volatility transmitted from naphtha-cracker economics. Agrochemical formulators in China exhibit highest price sensitivity, while pharmaceutical compounders in Houston and Frankfurt prioritize supply assurance over unit cost.
Supply Chain Analysis
China's MIIT domestic-content standards for crop protection chemicals are reshaping sourcing patterns toward local ethoxylation capacity. Production gravity centers on China, the United States, and Germany, with Yangtze River Delta chemical parks, Gulf Coast ethylene oxide infrastructure, and Rhine-Ruhr derivatives platforms anchoring regional supply. Raw material flows draw from ethylene oxide, ammonia, and catalytic ethoxylation systems, with feedstock integration determining cost position. Single-source vulnerability runs through Gulf Coast hurricane exposure and EPA facility actions. Distribution feeds from direct manufacturer relationships in premium cosmetic and pharmaceutical tiers, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Triethanolamine functions as a stable compounder anchored by regulatory certification stickiness that locks formulators into qualified supplier relationships. Personal care and pharmaceutical procurement patterns favor incumbents with established compliance infrastructure.
For Market Incumbents: Acquire continuous ethoxylation reactor assets to tighten purity distribution and compress batch-release timelines for cosmetic-grade supply. Integrate backward into ethylene oxide production to insulate margin stability from naphtha-cracker volatility, while expanding REACH registration coverage to filter Asian import competition from European procurement channels. For New Entrants and Emerging Players: Specialty chemical distributors with formulation technical service capabilities represent the most accessible channel partnership for bypassing established manufacturer-direct relationships. Target Indian personal care manufacturing expansion in Maharashtra and Gujarat, where CDSCO pharmaceutical standards constrain local production and create import demand for certified supply. Lead with SCIP database compliance and audit-ready documentation systems to differentiate from commodity traders. For Investors and Strategic Acquirers: Valuations sit cheapest among merchant ethoxylation specialists lacking feedstock integration, presenting consolidation targets for diversified chemical conglomerates. Long-term viability hinges on certification breadth across FDA, REACH, and cosmetic GMP tiers, with durable cash flows from multi-year pharmaceutical supply agreements. Watch EPA ethylene oxide emission enforcement actions as inflection indicator for North American capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates margin stability from naphtha-cracker volatility at Gulf Coast and Rotterdam crackers. |
| Continuous Ethoxylation Reactor Deployment | Steady-state operation tightens purity distribution for REACH-registered cosmetic-grade material in German facilities. |
| Pharmaceutical-Grade Certification Investment | FDA lot-traceability compliance secures multi-year agreements with Houston and New Jersey compounders. |
| Direct-to-Formulator Distribution Expansion | Bypassing chemical distributors captures margin and enables technical service relationships with mid-sized personal care manufacturers. |
| SCIP Database Compliance Infrastructure | Granular lot-level documentation satisfies REACH Article 33 obligations for EU cosmetic and pharmaceutical procurement. |
Research Methodology
Direct dialogue with plant managers at ethoxylation facilities, procurement leads at personal care OEMs, distribution channel partners, and technical R&D directors anchored qualitative assessment. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Segmentation-grade projections across pharmaceutical, cosmetic, and industrial tiers, end-use industry splits, and regional production hub clusters populated the analytical framework. CAGRs were derived from ethylene oxide feedstock cost trajectories, REACH registration penetration curves, and personal care formulation intensity trends across the projection horizon. Ethoxylation capacity utilization rates and cosmetic GMP enforcement patterns served as industry-specific calibration inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA ethylene oxide emission rulemaking, REACH authorization list expansions, and biobased ethylene oxide technology convergence. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and feedstock cost transmission. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global E Series Glycol Ether Market
Chemicals
Cummene Derivatives Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Hydrogen Chloride Market
Chemicals
Betaine Market
Chemicals
Sulfur Chemicals Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Allyl Chloride Market
Chemicals
Inorganic Chemicals Market
Chemicals
Roofing Chemical Market
Chemicals
Fluorochemicals Market
Chemicals
Superplasticizer Market
Chemicals
South America Construction Chemicals Market
Chemicals
Maleic Acid Market
Chemicals
Ferric Oxide Market