
 Superplasticizer Market | 2026-2036
Superplasticizer Market Size, Share, and Industry Trends Forecast 2026-2036
Superplasticizer Market Analytics
Capital-intensity divergence between integrated resin producers and formulation-only suppliers is redrawing competitive boundaries in the superplasticizer sector. Sika AG leverages captive polycarboxylate ether production to sustain margin control across European infrastructure bids. BASF SE anchors its position through backward integration into ethylene oxide derivatives, while Mapei SpA competes via specialized distribution networks in Mediterranean pre-cast markets.
Superplasticizers are high-range water reducers that enable concrete placement at water-cement ratios below 0.30 while maintaining workability, with polycarboxylate ether variants achieving slump retention exceeding two hours through steric hindrance mechanisms. Polycarboxylate ether formulations command premium positioning due to superior dispersion stability and compatibility with supplementary cementitious materials. Ready-mix suppliers represent the most structurally concentrated demand pool, while dry-mix applications exhibit faster specification migration from naphthalene sulfonate toward modified polycarboxylate systems.
REACH compliance in Europe and China's GB 8076-2008 concrete admixture standards constrain product entry, with ECHA substance evaluation protocols forcing reformulation of certain sulfonated melamine derivatives. The US EPA's emerging scrutiny of construction chemical VOC profiles adds another compliance layer for North American suppliers. Stakeholders must monitor polymer architecture patents and regional carbon-border adjustments to anticipate where formulation premiums will hold.
Market Dynamics
China's GB 8076-2008 concrete admixture standards and tightening dual carbon goals are forcing polycarboxylate ether reformulation across Asia-Pacific supply chains, compressing margins for sulfonated melamine derivative producers while rewarding backward-integrated resin manufacturers.
Growth Catalysts
- Urban rail infrastructure:Metro expansion in China's Yangtze River Delta and India's western corridor drives specification upgrades toward high-performance concrete with extended slump retention.
- REACH substance evaluation:ECHA protocols in Europe force replacement of legacy sulfonated melamine systems, opening substitution windows for polycarboxylate ether formulations.
- Smart city mandates:National programs in India and Southeast Asian markets accelerate dry-mix system adoption, displacing naphthalene sulfonate in pre-cast applications.
Market Restraints
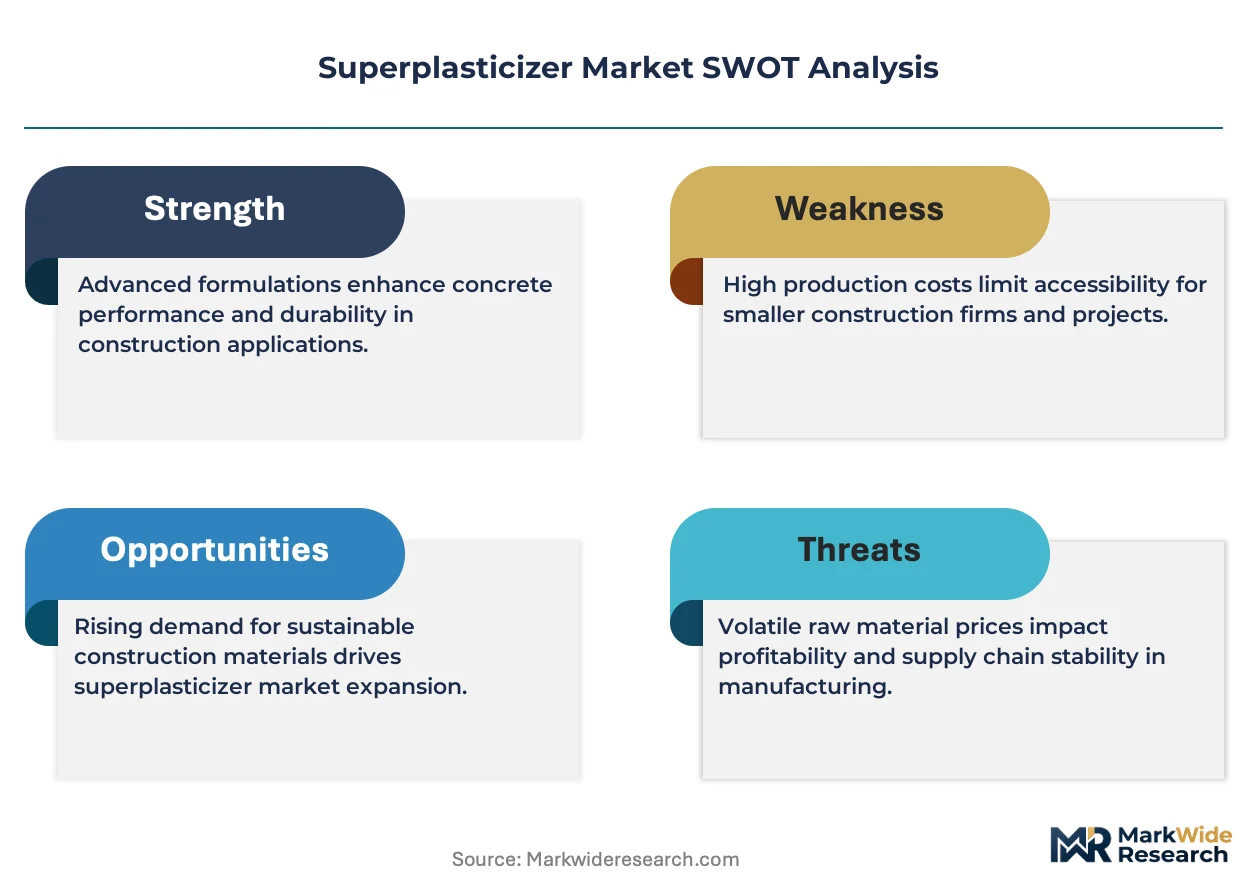
- Ethylene oxide derivative volatility:Captive production of polyethylene glycol backbones requires substantial capital commitment, disadvantaging formulation-only suppliers.
- Resin supply concentration:Integrated polycarboxylate ether producers in East Asia control critical polymer architecture patents, limiting new entrant formulation flexibility.
- VOC scrutiny expansion:US EPA construction chemical emission profiles add compliance layers for North American admixture suppliers without captive testing infrastructure.
Strategic Opportunities
- Carbon-border adjustment preparation:EU CBAM implementation creates first-mover advantage for suppliers with verified low-carbon resin production and lifecycle documentation.
- Supplementary cementitious material compatibility:Polycarboxylate ether variants optimized for fly ash and slag blends capture specification share in low-clinker concrete formulations.
- Direct-to-contractor digital channels:Bypassing traditional ready-mix distributor networks enables margin recovery and specification influence in mid-scale commercial projects.
Industry Challenges
- Polymer architecture patent navigation:Dense intellectual property thickets around comb-structure polycarboxylate ethers complicate independent formulation development.
- Cross-regional certification timelines:Divergent ECHA, EPA, and MEE approval protocols delay product launch synchronization across major demand markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superplasticizer Market |
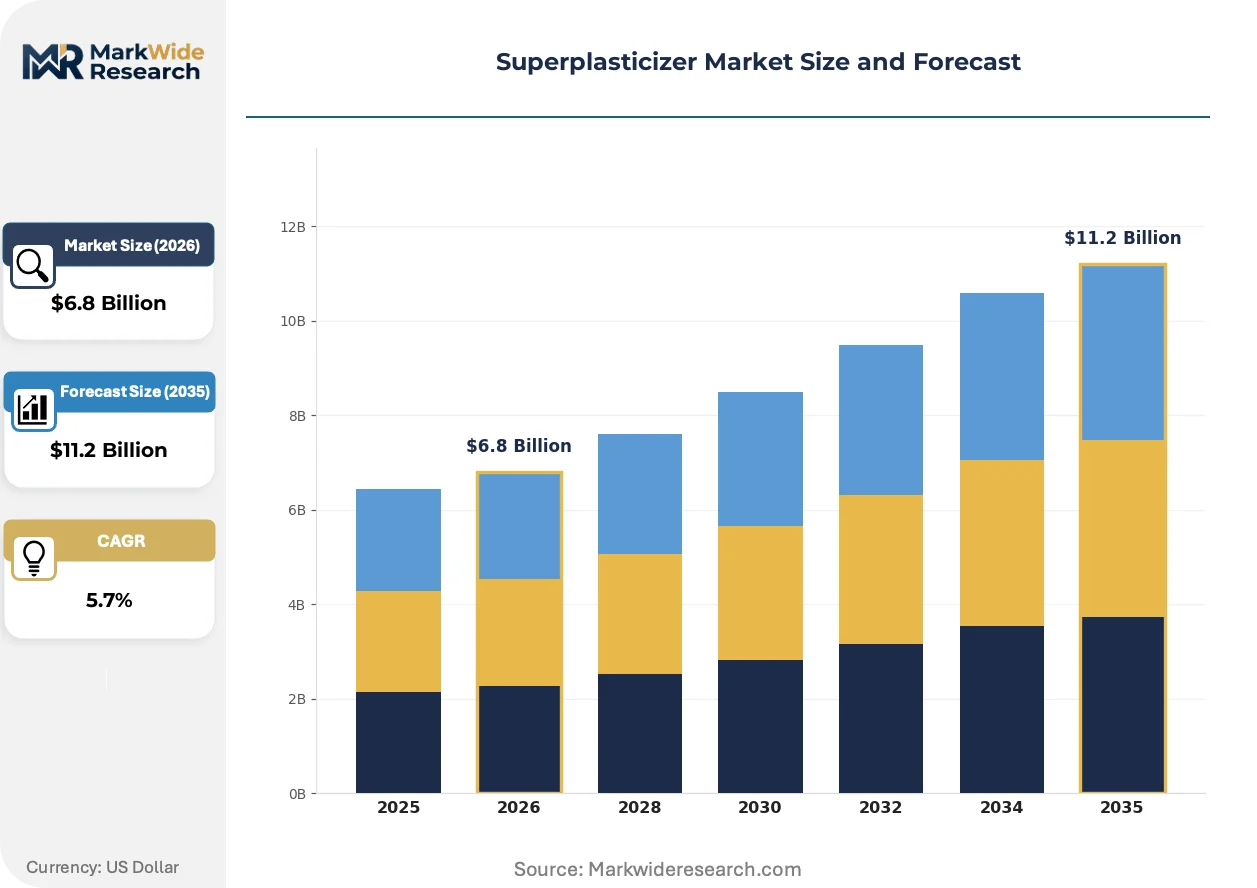
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarboxylate Ether, Lignosulfonate, Napthalene Sulfonate, Others Application: Concrete, Mortar, Dry Mix, Grouts End User: Construction, Infrastructure, Pre-cast Manufacturers, Ready-mix Suppliers Form: Liquid, Powder, Granules, Tablets |
| Companies Covered | Sika AG, BASF SE, Mapei SpA, Arkema, MBCC Group, GCP Applied Technologies Inc., Kao Corporation, Fosroc Inc., Chryso S.A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superplasticizer Market Evolving Landscape
Formulation science and compliance architecture are diverging sharply between premium polycarboxylate systems and legacy chemistries, with polymer architecture patents and carbon accounting becoming decisive competitive variables.
Modified polycarboxylate ether technology is bifurcating the admixture landscape. These steric hindrance-based systems enable water-cement ratios below 0.30 with slump retention exceeding two hours. Ready-mix concrete suppliers in high-specification infrastructure bids are adopting them aggressively. The technology is bifurcating competitive position between backward-integrated resin producers and formulation-dependent suppliers.
REACH substance evaluation protocols are accelerating sulfonated melamine derivative phase-outs across European construction chemical markets. ECHA's systematic assessment of persistent organic pollutant characteristics forces reformulation investments. Mediterranean pre-cast manufacturers face compressed compliance timelines and raw material qualification burdens.
Specification authority is migrating from distributor networks toward engineering-consultant channels. Large infrastructure developers now retain independent concrete technology advisors who mandate polymer-grade certifications. This pattern concentrates most visibly in German and Swiss commercial building markets where performance-based contracting dominates procurement.
Superplasticizer Market Segmentation
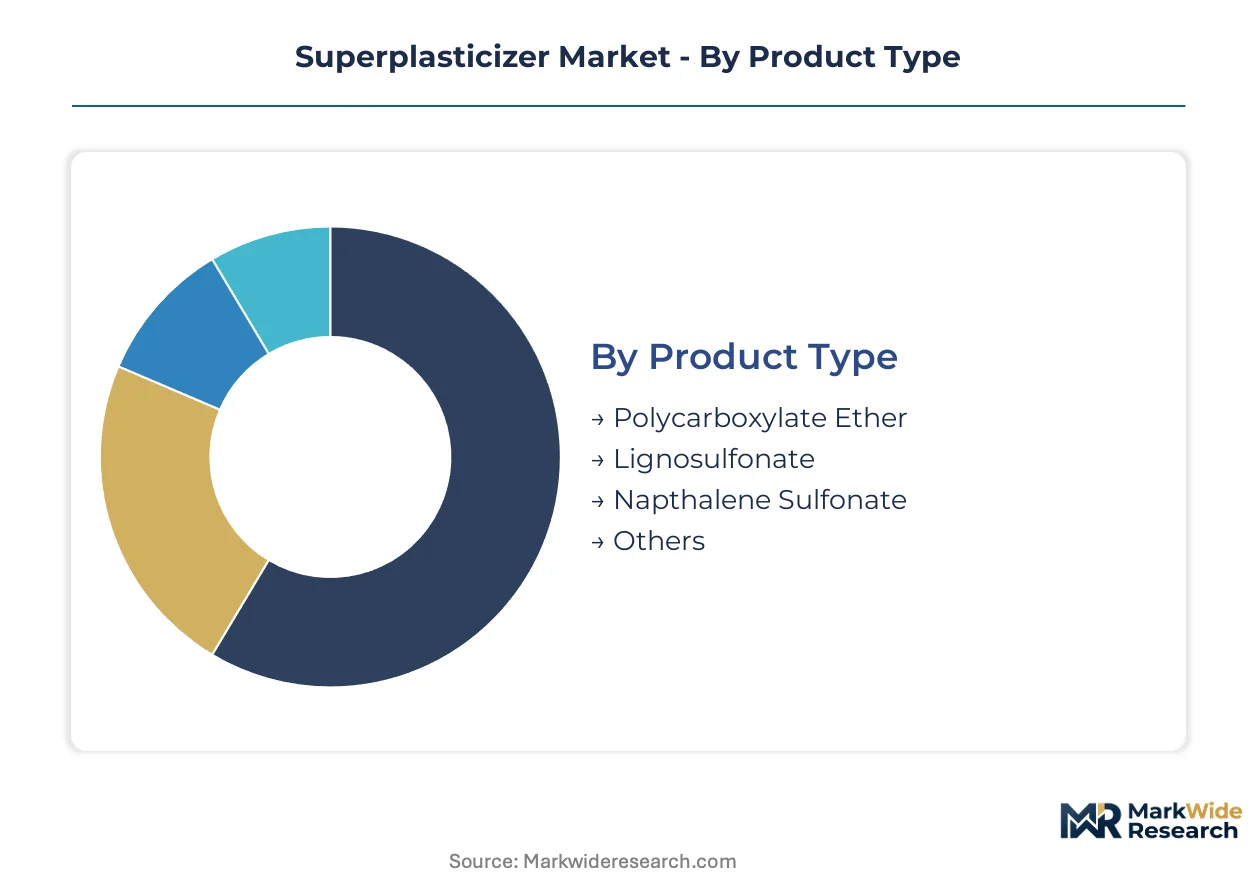
Superplasticizer segmentation reveals how substitution pressures from polycarboxylate ether technology are compressing legacy chemistry margins while reshaping procurement patterns across formulation types and delivery formats. Product architecture and application requirements drive specification divergence between high-performance infrastructure bids and commodity construction supply.
Product Type:
Polycarboxylate ether formulations exert intense substitution pressure on sulfonated and lignin-based chemistries as REACH protocols and China's GB standards tighten performance benchmarks.
- Polycarboxylate Ether:Comb-structure polymers achieve water-cement ratios below 0.30 through steric hindrance mechanisms, with slump retention exceeding two hours. Demand concentrates in China's Yangtze River Delta metro expansion and India's western corridor smart city projects where extended workability specifications dominate procurement.
- Lignosulfonate:Derived from wood pulp sulfite liquor, these cost-advantaged formulations retain footholds in low-specification commercial concrete where water reduction requirements remain modest. European pre-cast manufacturers facing compressed margins deploy lignosulfonate in non-structural applications as ECHA evaluation timelines create temporary chemistry windows.
- Napthalene Sulfonate:Condensation polymers from naphthalene and formaldehyde face accelerating displacement as slump retention demands intensify; residual demand persists in emerging market dry-mix systems where specification migration lags.
- Others:Melamine sulfonate and amino-sulfonate variants occupy niche high-early-strength applications in pre-stressed concrete segments.
Polycarboxylate ether retains volume leadership; lignosulfonate holds the steepest contraction trajectory as regulatory thresholds harden.
Application:
Cost tier stratification separates premium infrastructure specifications from commodity construction chemistry procurement.
- Concrete:Ready-mix and site-mixed concrete consume the majority of superplasticizer volume, with polycarboxylate ether penetration deepest in high-rise and heavy infrastructure segments requiring extended slump life.
- Mortar:Masonry and rendering applications favor powder and liquid lignosulfonate formulations where water retention rather than water reduction drives specification.
- Dry Mix:Factory-blended systems for pre-cast and tilt-up construction are migrating fastest from naphthalene sulfonate to modified polycarboxylate powders as automated batching enables precise dosing control.
- Grouts:Precision injection and anchoring applications demand ultra-low viscosity polycarboxylate systems with controlled bleed characteristics.
Concrete commands absolute volume share; dry mix is gaining share fastest on pre-cast automation trends.
End User:
Customer type determines specification authority, with engineering-consultant channels displacing traditional distributor influence in large-project procurement.
- Construction:Commercial and residential building contractors represent fragmented, price-sensitive demand where formulation switching costs remain low and distributor relationships govern supply.
- Infrastructure:Mega-project developers in German and Swiss markets retain independent concrete technology advisors who mandate polymer-grade certifications and performance-based contracting terms.
- Pre-cast Manufacturers:Mediterranean and Southeast Asian factory producers drive dry-mix specification migration as automated production lines require consistent admixture dispersion.
- Ready-mix Suppliers:Structurally concentrated demand pools in China's Yangtze River Delta and India's western corridor enforce backward integration requirements on admixture vendors.
Ready-mix suppliers anchor procurement volume; infrastructure holds the steepest expansion curve on mega-project pipelines.
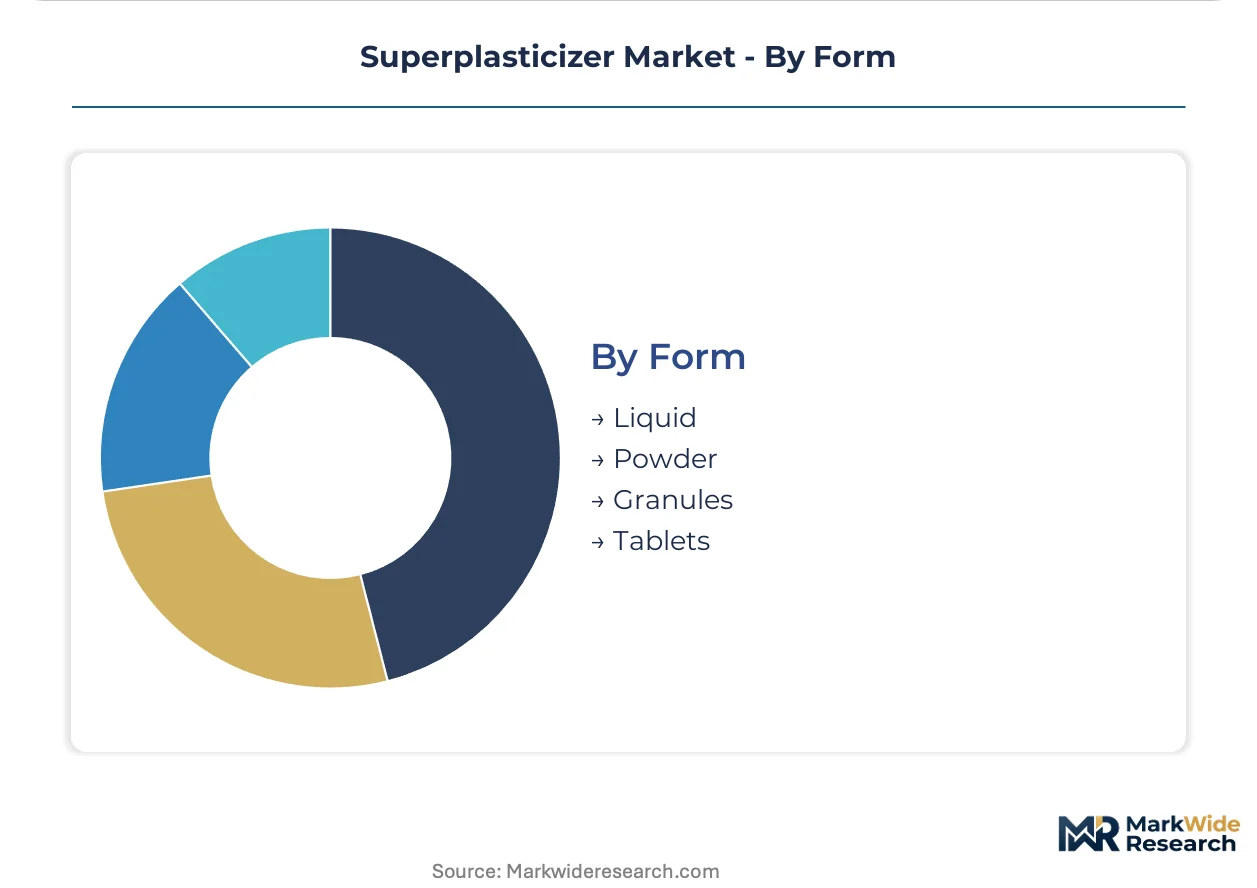
Form:
Supply concentration in liquid production favors integrated resin manufacturers while powder and granule formats enable regional formulation flexibility.
- Liquid:Bulk polycarboxylate ether solutions dominate ready-mix concrete integration, requiring refrigerated transport and storage infrastructure that disadvantages smaller regional blenders.
- Powder:Spray-dried polycarboxylate and lignosulfonate formulations serve dry-mix and pre-cast segments where extended shelf stability and freight efficiency offset premium conversion costs.
- Granules:Intermediate moisture-resistant formats occupy logistics-constrained emerging markets lacking liquid handling infrastructure.
- Tablets:Precision-dosed solid formats address small-batch repair and specialty grouting applications where volumetric accuracy outweighs unit cost premiums.
Liquid retains volume leadership; powder holds the steepest expansion curve on dry-mix automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. China's Yangtze River Delta deploys polycarboxylate ether for extended-slump metro concrete, while European pre-cast manufacturers face compressed reformulation timelines under ECHA protocols. India's western corridor drives dry-mix specification migration from legacy naphthalene systems.
China
Metro expansion in Shanghai, Nanjing, and Hangzhou anchors polycarboxylate ether demand for high-performance concrete with two-hour slump retention. GB 8076-2008 concrete admixture standards and dual carbon goals force reformulation away from sulfonated melamine derivatives. Yangtze River Delta ready-mix suppliers enforce backward integration requirements on admixture vendors.
India
Smart city investments in Mumbai, Pune, and Ahmedabad accelerate dry-mix system adoption for automated pre-cast production. Bureau of Indian Standards certification timelines for construction chemicals compress product launch windows. Western corridor infrastructure bids specify polycarboxylate ether compatibility with fly ash blends.
Germany
Performance-based contracting in commercial building markets concentrates specification authority with independent concrete technology advisors. REACH substance evaluation protocols systematically assess persistent organic pollutant characteristics in legacy admixtures. Rhine-Ruhr and Bavarian construction clusters drive premium polycarboxylate penetration in high-rise segments.
United States
EPA emerging scrutiny of construction chemical VOC profiles adds compliance layers for admixture suppliers without captive testing infrastructure. Texas and California infrastructure bids emphasize extended workability specifications for mass concrete placements. Southeast commercial construction maintains price-sensitive demand for lignosulfonate formulations.
Saudi Arabia
NEOM and Red Sea Project mega-developments specify ultra-low viscosity polycarboxylate systems for precision grouting and high-early-strength applications. The country's national building code authority tightens admixture performance benchmarks for desert climate durability. Riyadh and Eastern Province construction clusters import resin backbones from East Asian integrated producers.
Superplasticizer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the superplasticizer sector. Captive polycarboxylate ether production distinguishes resin manufacturers from formulation-dependent competitors. Three archetypes dominate: backward-integrated chemical conglomerates with ethylene oxide derivative control, regional formulation specialists serving dry-mix pre-cast segments, and construction chemical distributors with specification influence in fragmented commercial markets. Competitive moves center on polymer architecture patent licensing and carbon-border adjustment documentation.
Within the integrated chemical tier, Sika AG and BASF SE exemplify archetypes of captive resin production and ethylene oxide derivative control respectively. Mapei SpA occupies a position representing specialized distribution network competition in Mediterranean pre-cast markets. These three anchors illustrate how geographic concentration and supply chain configuration determine margin sustainability across European infrastructure bids.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Mapei SpA |
| Arkema |
| MBCC Group |
| GCP Applied Technologies Inc. |
| Kao Corporation |
| Fosroc Inc. |
| Chryso S.A.S. |
| Others |
Value Network & Pricing Analysis
Ninety-day resin inventory cycles at East Asian integrated producers translate directly into pricing power over formulation-only suppliers in European infrastructure bids. Polycarboxylate ether backbones from captive ethylene oxide derivative operations command premium positioning against spot-market-dependent blenders facing compressed margins under REACH compliance timelines.
Pricing Analysis
Project-based long-term offtake contracts dominate mega-infrastructure procurement in China's Yangtze River Delta and India's western corridor, while spot transactions govern fragmented commercial construction. Three-tier pricing structure across premium polycarboxylate ether, standard naphthalene sulfonate, and economy lignosulfonate levels reflects certification grade and volume scale differentiation. Pricing pressure stems from ethylene oxide derivative volatility disadvantaging non-integrated suppliers. Ready-mix concrete suppliers exhibit lowest price sensitivity due to backward integration requirements, while small-scale pre-cast manufacturers face acute margin compression.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo and Singapore-Rotterdam trade lanes elevates inbound logistics costs for European formulation houses sourcing spray-dried polycarboxylate powders. Supply concentrates in China, South Korea, and Germany, with polyethylene glycol backbone production drawing from ethylene oxide derivatives and acrylic acid feedstocks. Single-source vulnerability around comb-structure polymer architecture patents in East Asia creates supply chain risk. Distribution runs through ready-mix supplier networks in concentrated demand clusters and specialized construction chemical distributors in fragmented commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive resin production capabilities separate margin-sustainable leaders from formulation-dependent competitors facing raw material volatility. Engineering-consultant specification authority and carbon-border documentation requirements now determine competitive viability more than distributor relationships.
For Market Incumbents: Secure backward integration into ethylene oxide derivatives or captive polycarboxylate ether resin production to defend against margin compression from spot-market polyethylene glycol volatility. Deepen certification investments for EU CBAM lifecycle documentation and GB 8076-2008 compliance to maintain specification access in China's Yangtze River Delta metro expansion. For New Entrants and Emerging Players: Digital direct-to-contractor channels in mid-scale commercial projects represent underserved white space where traditional distributor networks lack specification influence. Target dry-mix pre-cast segments in India's western corridor smart city investments where automated batching enables precise dosing control without legacy distributor entrenchment. Pursue regional formulation licensing from East Asian patent holders rather than independent polymer architecture development. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because formulation-only suppliers face structural disadvantage against integrated resin producers as regulatory compliance costs rise. Acquisition targets should exhibit captive polyethylene glycol production or established engineering-consultant specification relationships. Monitor ECHA substance evaluation timelines for sulfonated melamine derivatives as inflection signal for polycarboxylate ether substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Derivatives | Captive polyethylene glycol production insulates margin from raw material volatility in European infrastructure bids. |
| EU CBAM Lifecycle Documentation Investment | Verified low-carbon resin certification secures specification advantage in German performance-based contracting markets. |
| Direct-to-Contractor Digital Channel Development | Bypassing traditional ready-mix distributors recovers margin in mid-scale commercial projects with consultant-led procurement. |
| Regional Formulation Licensing Agreement | Patent access from East Asian integrated producers accelerates market entry without independent R&D timelines. |
| Supplementary Cementitious Material Compatibility Program | Fly ash and slag-optimized polycarboxylate variants capture share in low-clinker concrete formulations under China's dual carbon goals. |
Research Methodology
Desk research of customs/trade data, SEC 10-K filings, and Cefic construction chemical reports preceded structured interviews with ready-mix procurement directors, pre-cast plant managers, and admixture R&D technical leads. Primary fieldwork with engineering consultants specifying concrete technology for German and Swiss infrastructure projects combined with secondary validation from ECHA substance evaluation databases and China's GB standards documentation. Bottom-up volume modeling across product types, applications, and end-user segments triangulated against top-down construction chemical market assessments.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension including product chemistry tier, delivery format, regional production hub, and specification authority channel. CAGRs derive from modeled year-over-year progression incorporating ethylene oxide derivative cost trajectories and regulatory compliance timeline assumptions. Industry-specific inputs include metro infrastructure bid pipelines in China's Yangtze River Delta and ECHA persistent organic pollutant evaluation schedules for legacy admixtures.
Forecasts assume regulatory continuity in REACH substance evaluation protocols and China's GB 8076-2008 admixture standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
United Kingdom Methanol Market
Chemicals
Guaiazulene Market
Chemicals
Betaine Market
Chemicals
Cummene Derivatives Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Household Insecticides Market
Chemicals
Glycerol Carbonate Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Hexachloroethane Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Cupric Chloride Market