
 Die Casting Machinery Market | 2026-2036
Die Casting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Die Casting Machinery Market Outlook
Aftermarket service revenue is reconfiguring margin distribution across the die casting machinery value chain. Bühler AG leverages its global spare parts network to capture recurring service income. UBE Machinery anchors its position through deep technical support for aluminum structural component producers. Italpresse Gauss specializes in integrated cell solutions that bind customers to long-term maintenance contracts.
Die casting machinery comprises high-pressure injection systems that force molten non-ferrous metals—typically aluminum, magnesium, or zinc—into hardened steel dies at clamping forces exceeding 4,000 metric tons, producing near-net-shape components for mass production. Cold chamber systems dominate automotive structural applications where aluminum alloys require separate melting and transfer to avoid iron contamination. Automated technology lines command premium positioning as OEMs mandate traceability and repeatability for safety-critical chassis castings. Contract manufacturers represent a fast-growing end user segment as tier suppliers outsource capital-intensive die casting cell investments.
EPA emissions standards tighten energy efficiency requirements for foundry operations across the United States. China's MIIT enforces GB standards on industrial equipment energy consumption, accelerating replacement cycles for outdated hot chamber units. REACH compliance in Europe restricts certain die lubricant chemistries, pushing machinery suppliers toward closed-loop spray systems. Stakeholders must weigh capital deployment timing between incremental automation upgrades and full greenfield cell investments as regulatory thresholds diverge across manufacturing jurisdictions.
Market Dynamics
Automotive OEMs in Germany and China are forcing a wholesale replacement cycle for legacy hot chamber equipment as electric vehicle structural battery housings demand clamping forces above 4,000 metric tons with traceability systems embedded.
Growth Catalysts
- EPA Emissions Standards:Foundries across the United States face tightening energy efficiency mandates that accelerate retirement of energy-intensive legacy equipment and drive capital deployment toward automated cold chamber systems.
- Aluminum Structural Components:Electric vehicle manufacturers require near-net-shape chassis castings that only high-pressure die casting cells can produce at automotive production volumes.
- Guangdong Province Concentration:Tier suppliers cluster around Shenzhen and Dongguan to access technical support infrastructure for complex magnesium alloy injection systems.
Market Restraints
- Copper and Hardened Steel Input Volatility:Die casting machinery manufacturers face margin compression from fluctuating specialty alloy prices for injection system components.
- REACH Compliance Friction:European foundries encounter restricted die lubricant chemistries that complicate spray system specifications and extend equipment qualification timelines.
- Mechanical Substitution by Stamping:High-strength steel stamping advances threaten aluminum die casting in non-structural automotive applications where weight reduction targets moderate.
Strategic Opportunities
- India PLI Scheme for Auto Components:Domestic machinery suppliers can capture capacity expansion as OEMs localize electric vehicle supply chains under production-linked incentive frameworks.
- Closed-Loop Spray System Convergence:Integration of real-time viscosity monitoring with automated die lubrication creates premium positioning for machinery vendors serving European REACH-compliant foundries.
- Contract Manufacturer Channel:Tier suppliers outsource capital-intensive cell investments to specialized die casting service providers, opening recurring revenue streams for equipment-as-a-service models.
Industry Challenges
- Multi-Axis CNC Programming Talent Gap:Automated die casting cells require operators fluent in CAM software for complex core pull sequences, creating recruitment bottlenecks in Stuttgart and Shanghai manufacturing corridors.
- Legacy PLC Integration Complexity:Brownfield foundries struggle to retrofit traceability systems onto 1990s-era machine controls without complete cell replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Casting Machinery Market |
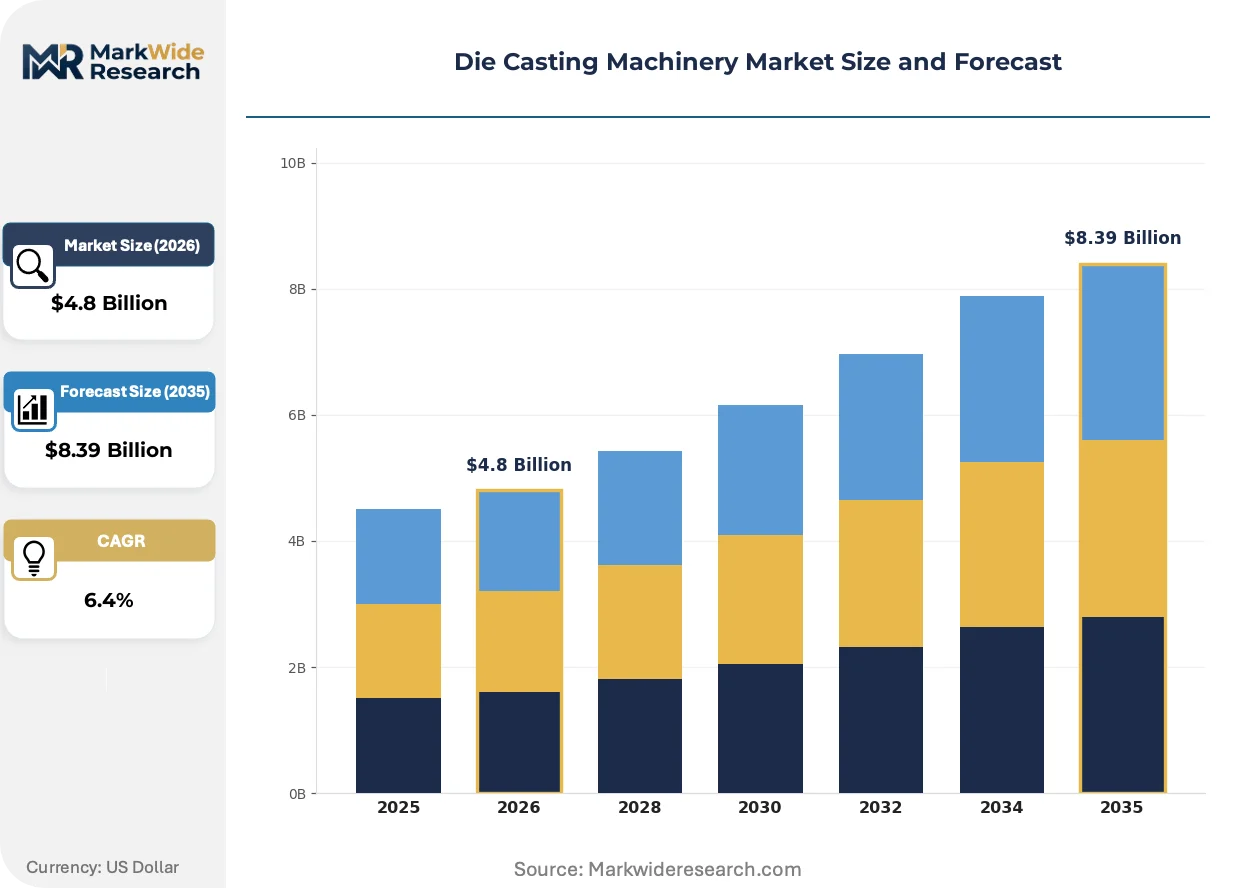
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Chamber, Hot Chamber, CNC Machining, Die Sets Technology: Automated, Manual, Semi-Automated, Hybrid Application: Automotive Components, Aerospace Parts, Consumer Goods, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Contract Manufacturers |
| Companies Covered | UBE Machinery, Italpresse Gauss, Bühler AG, Haitian Die Casting, L.K. Technology Holdings Limited, Shibaura Machine, Toyo Machinery & Metal, Yizumi Holdings, Oskar Frech GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Casting Machinery Market Strategic Shifts
Real-time thermal monitoring and predictive maintenance algorithms are compressing the acceptable downtime windows for high-volume automotive contracts.
Integrated sensor arrays embedded in die casting platens now track cavity temperature gradients with millisecond resolution. Tier one automotive suppliers in Germany and China mandate these systems for structural component qualification. Conventional manual thermocouple placement is rendering obsolete across safety-critical casting applications.
China's MIIT enforces GB standards on industrial equipment energy consumption that disqualify hot chamber units from new factory approvals. Foundries in Guangdong Province accelerate replacement cycles to avoid production quota penalties. Cold chamber system vendors capture displaced demand through turnkey energy audit documentation.
Automotive procurement teams now unbundle after-sales service contracts from initial equipment purchases. Contract manufacturers in the Stuttgart corridor negotiate performance-based maintenance agreements tied to uptime guarantees. Machinery suppliers respond with remote diagnostic platforms that preempt field service dispatch.
Die Casting Machinery Market Segmentation
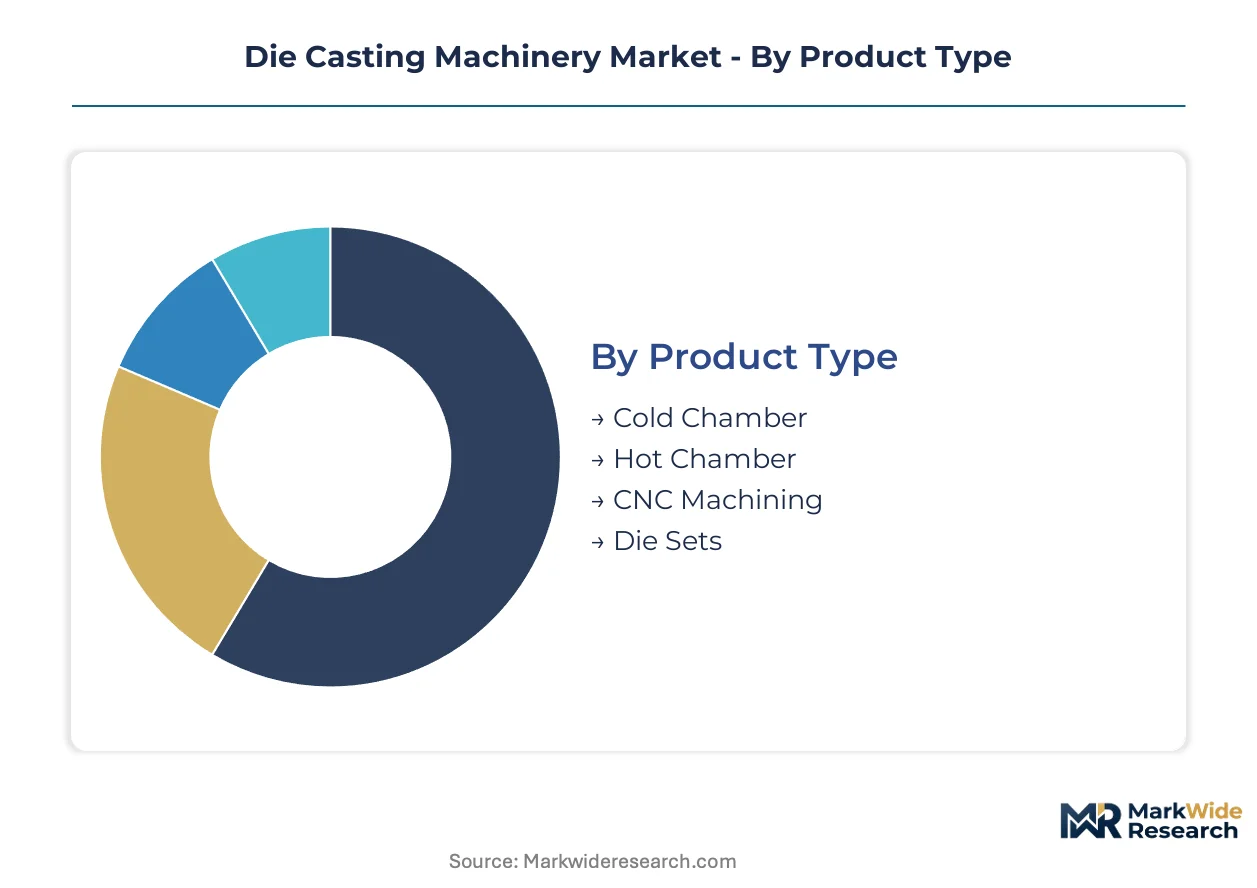
Die casting machinery segmentation reveals divergent technology paths across automotive electrification and traditional manufacturing. Equipment specifications vary dramatically between structural battery housing production and legacy component casting.
Product Type:
Cold chamber systems dominate aluminum-intensive applications where melt quality demands separation from injection mechanisms.
- Cold Chamber:Separate melting and transfer systems prevent iron contamination in aluminum alloys. Automotive OEMs in Germany specify these units for EV structural battery housings requiring clamping forces above 4,000 metric tons with embedded traceability.
- Hot Chamber:Integrated melting pots suit zinc and magnesium alloys with lower melting points. China's MIIT energy consumption standards are accelerating replacement cycles for these units in Guangdong Province foundries.
- CNC Machining:Post-cast finishing cells integrate with die casting lines for near-net-shape component refinement.
- Die Sets:Hardened steel tooling systems determine cavity precision and thermal management for specific component geometries.
Established volume favors cold chamber systems; emerging adoption favors integrated die set solutions with predictive thermal monitoring.
Technology:
Automation intensity separates premium positioning from commodity equipment tiers based on traceability mandates.
- Automated:Real-time sensor arrays and predictive maintenance algorithms compress downtime windows for high-volume automotive contracts. Tier one suppliers in Stuttgart mandate these systems for safety-critical chassis casting qualification.
- Manual:Conventional operator-dependent controls persist in low-volume specialty applications and developing market foundries with limited capital deployment capacity.
- Semi-Automated:Hybrid configurations balance labor costs with quality consistency for mid-tier component producers.
- Hybrid:Modular retrofit packages allow brownfield foundries to upgrade legacy PLC systems without complete cell replacement.
Procurement patterns concentrate in automated systems for new capacity; semi-automated configurations capture brownfield upgrade demand.
Application:
End-use specifications drive divergent clamping force and thermal management requirements across industrial sectors.
- Automotive Components:Structural battery housings and chassis castings demand the highest clamping forces and cavity temperature gradient monitoring. OEMs unbundle after-sales service contracts from initial equipment purchases in this segment.
- Aerospace Parts:Magnesium alloy thin-wall castings for cabin interiors require precision injection control and vacuum-assisted systems.
- Consumer Goods:Zinc alloy decorative hardware and appliance components utilize smaller hot chamber units with shorter cycle times.
- Industrial Equipment:Pump housings and valve bodies tolerate broader dimensional tolerances than automotive safety-critical applications.
Capital deployment tilts toward automotive; margin stability characterizes industrial equipment applications.
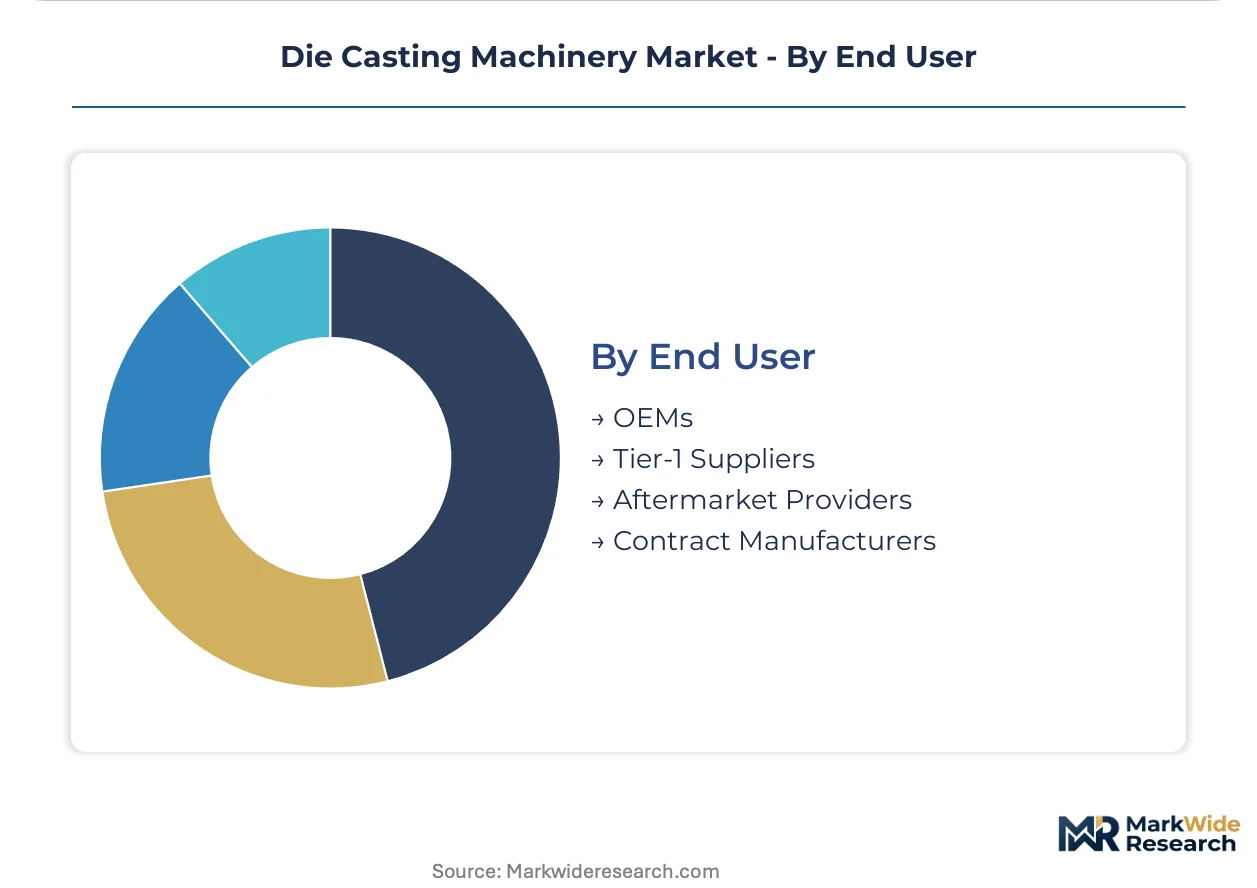
End User:
Customer type determines financing structures and service contract negotiation leverage across the value chain.
- OEMs:Direct automotive manufacturer procurement mandates traceability systems and performance-based uptime guarantees. Contract manufacturers in the Stuttgart corridor negotiate service agreements tied to production continuity.
- Tier-1 Suppliers:Intermediate component specialists balance capital constraints against OEM qualification requirements.
- Aftermarket Providers:Spare parts and refurbishment specialists capture recurring revenue from installed base maintenance.
- Contract Manufacturers:Outsourced die casting service providers open equipment-as-a-service models for machinery vendors seeking recurring revenue streams.
Direct OEM relationships anchor premium pricing; contract manufacturer channels are expanding most quickly as tier suppliers outsource capital-intensive cell investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Guangdong Province show the highest price elasticity as tier suppliers compete on thin margins, while German automotive OEMs demonstrate the lowest sensitivity given qualification requirements and uptime guarantees.
China
Guangdong Province foundries in Shenzhen and Dongguan drive demand for magnesium alloy injection systems as electric vehicle supply chains localize. MIIT enforces GB standards on industrial equipment energy consumption that disqualify hot chamber units from new factory approvals. Tier suppliers cluster around the Pearl River Delta to access technical support infrastructure for complex structural component production.
Germany
Automotive OEMs in the Stuttgart manufacturing corridor mandate clamping forces above 4,000 metric tons with embedded traceability for EV battery housings. REACH compliance restricts certain die lubricant chemistries, pushing foundries toward closed-loop spray system investments. Contract manufacturers negotiate performance-based maintenance agreements tied to production continuity guarantees.
United States
EPA emissions standards tighten energy efficiency requirements for foundry operations, accelerating retirement of legacy hot chamber equipment. Tier suppliers in the Midwest automotive belt deploy automated cold chamber systems to meet OEM traceability mandates. Brownfield foundries struggle with PLC integration complexity when retrofitting 1990s-era machine controls.
India
The PLI scheme for auto components attracts domestic machinery suppliers as OEMs localize electric vehicle supply chains. Tier suppliers in Maharashtra and Gujarat outsource capital-intensive die casting cell investments to contract manufacturers. Foundries face recruitment bottlenecks for operators fluent in CAM software for complex core pull sequences.
Japan
Precision magnesium alloy thin-wall casting for aerospace cabin interiors sustains demand for vacuum-assisted injection control systems. METI industrial efficiency guidelines pressure foundries to replace energy-intensive legacy equipment. Manufacturers in the Nagoya manufacturing belt specialize in integrated sensor arrays for real-time cavity temperature monitoring.
Die Casting Machinery Market Competitive Environment
Integrated solution providers and component specialists split the market based on customer preference for turnkey cells versus modular upgrades. The vendor base concentrates among Swiss-German precision engineering houses, Japanese automation conglomerates, and Chinese scale manufacturers. Two strategic archetypes dominate: full-service providers capturing long-term maintenance contracts, and equipment-focused suppliers competing on initial capital cost. Competitive moves center on geographic expansion into India's PLI-driven auto component corridor and technology licensing partnerships for predictive maintenance algorithms.
Within the full-service tier, Bühler AG and Italpresse Gauss exemplify providers that anchor customer relationships through aftermarket service revenue. UBE Machinery occupies a position among Japanese conglomerates that leverage deep technical support for aluminum structural component producers. These three represent the archetype of vendors unbundling after-sales contracts from initial equipment purchases to capture recurring income streams.
| Leading Market Players |
|---|
| UBE Machinery |
| Italpresse Gauss |
| Bühler AG |
| Haitian Die Casting |
| L.K. Technology Holdings Limited |
| Shibaura Machine |
| Toyo Machinery & Metal |
| Yizumi Holdings |
| Oskar Frech GmbH |
| Others |
Value Chain & Pricing Dynamics
Copper and hardened steel input volatility compresses margin buffers across machinery tiers while simultaneously forcing tier suppliers toward contract manufacturers with captive sourcing arrangements. This commodity exposure widens spreads between premium automated cold chamber systems and economy-grade hot chamber units, concentrating procurement leverage among buyers with volume scale in Guangdong Province and the Stuttgart corridor.
Pricing Analysis
After-sales service revenue tiers anchor lifetime value calculations for machinery vendors competing on total cost of ownership rather than initial capital outlay. Three-tier pricing structure across premium, standard, and economy levels separates automated cells with embedded traceability from semi-automated configurations and legacy manual systems. Price differentiation hinges on certification grade for automotive OEM qualification and geographic delivery cost for remote technical support infrastructure. Cost compression in economy-tier hot chamber equipment is intensifying because China's MIIT energy standards disqualify these units from new factory approvals. Contract manufacturers in India demonstrate highest price sensitivity as they outsource capital-intensive cell investments, while German automotive OEMs show lowest sensitivity given uptime guarantee requirements and REACH compliance qualification timelines.
Supply Chain Analysis
Upstream feedstock channels for injection system components draw from specialty alloy producers in Germany, Japan, and China where hardened steel and copper supply concentrates. Raw material dependencies center on high-grade tool steel for die sets, copper alloys for platen heating elements, and precision-machined hydraulic components. Single-source vulnerability threatens European foundries dependent on Chinese rare earth elements for permanent magnet servo motors in automated cells. Distribution runs through direct OEM procurement teams for large-scale capacity investments and specialized die casting service providers for outsourced production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die casting machinery fragmentation creates acquisition targets as electric vehicle supply chain localization splinters demand across regional technical support clusters. Contract manufacturer proliferation generates niche opportunities for vendors unbundling equipment-as-a-service models from traditional capital sales.
For Market Incumbents: Build aftermarket service moats through predictive maintenance platforms that preempt field service dispatch and lock in recurring revenue streams. Incumbents should anchor customer relationships via performance-based uptime guarantees tied to remote diagnostic capabilities, while adding capacity for aluminum structural component production in India's PLI-driven auto component corridor to offset margin pressure from Chinese scale manufacturers. For New Entrants and Emerging Players: Mid-tier automated cell retrofits for brownfield foundries with 1990s-era PLC systems represent the most penetrable entry point given legacy integration complexity that incumbents neglect. New entrants should target contract manufacturers in Maharashtra and Gujarat seeking equipment-as-a-service financing to avoid capital-intensive cell ownership, while positioning through CAM software training partnerships that address the multi-axis CNC programming talent gap constraining tier supplier expansion. For Investors and Strategic Acquirers: REACH compliance deadlines reshaping the acquisition landscape favor targets with closed-loop spray system IP and energy audit documentation capabilities. Long-term viability over the coming decade rests on vendors capturing displaced hot chamber demand through turnkey cold chamber transitions. Acquisition focus should center on mid-cap specialists with integrated sensor array technology for real-time cavity temperature monitoring. The signal to watch is MIIT enforcement intensity accelerating replacement cycles in Guangdong Province foundries.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Remote diagnostic capabilities preempt field service dispatch for Stuttgart corridor contract manufacturers. |
| Backward Integration into Die Set Manufacturing | In-house production of hardened steel tooling secures thermal management precision for automotive structural applications. |
| Closed-Loop Spray System Development | Real-time viscosity monitoring satisfies REACH compliance for European foundries restricted on die lubricant chemistries. |
| Equipment-as-a-Service Model Launch | Performance-based contracts capture tier suppliers outsourcing capital-intensive cell investments in India. |
| Geographic Expansion into India PLI Corridor | Localized technical support infrastructure addresses Maharashtra and Gujarat contract manufacturer demand. |
Study Parameters
Initial hypotheses were tested against primary input from die casting plant managers, OEM procurement specialists, aftermarket service directors, and technical R&D leads at machinery manufacturers and refined through secondary validation. Foundry engineering trade publications, MIIT energy consumption standard filings, EPA emissions compliance documentation, and SEC filings from listed industrial equipment manufacturers provided triangulation anchors. Bottom-up capacity deployment tracking across Guangdong Province and Stuttgart manufacturing clusters converged with top-down automotive production volume projections.
Demand-supply balance modeling across the analysis window segmented projections by product type, automation intensity, end-use application, and customer archetype. CAGRs were derived from installed base replacement cycles intersecting with regulatory compliance deadlines and electric vehicle platform ramp schedules. Forecast inputs incorporated aluminum alloy price trajectories, clamping force specification evolution for structural battery housings, and regional technical support infrastructure density metrics.
Practitioners should monitor MIIT enforcement patterns, EPA emissions standard tightening timelines, and high-strength steel stamping substitution rates for early signals requiring forecast revision. Cross-checking against automotive OEM platform engineering disclosures and foundry capital expenditure announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Metalworking Machinery Market