
 Global Metal Embossing Machine Market | 2026-2036
Global Metal Embossing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Embossing Machine Market Intelligence
The buyer base for metal embossing equipment is broadening beyond traditional sheet metal fabricators as packaging manufacturers and electronics producers enter the market with specialized surface-texturing requirements. The Bradbury Co., Inc. anchors North American demand through its roll-forming and embossing integration capabilities. Anhui LIFU Machinery Technology leverages domestic supply chain density to compete on delivery timelines for Asian customers. Alliance Machine & Engraving, LLC specializes in custom-engineered solutions that differentiate its portfolio from standardized equipment vendors.
Metal embossing machines apply controlled pressure through hardened dies or rollers to create raised or recessed patterns on sheet metal, strip, or coil stock, typically operating at pressures from 50 to 500 tons depending on material thickness and pattern complexity. These systems serve primarily to enhance structural rigidity, improve aesthetic surfaces, or embed functional textures for grip and airflow in industrial components. CNC-controlled electric embossing systems command expanding margin pools as end users prioritize programmable pattern libraries and energy efficiency over conventional hydraulic architectures. Roll embossing technology dominates high-volume coil processing for automotive and packaging applications, while laser engraving carves out a premium niche in electronics housings requiring micron-level precision without mechanical contact.
The EPA enforces emissions and energy-efficiency standards that shape electric and servo-driven machine demand in the United States, while the EU Green Deal and REACH frameworks push European fabricators toward cleaner production technologies with reduced hydraulic fluid dependency. China's MIIT implements GB standards for industrial equipment efficiency that directly influence domestic manufacturer design priorities and export competitiveness. Stakeholders must monitor how dual carbon compliance timelines in China and carbon border adjustments in Europe recalibrate total cost of ownership calculations for machine procurement across major manufacturing hubs.
Market Dynamics
Servo-electric architectures are compressing the installed base of hydraulic embossing systems as automotive lightweighting mandates in Germany, China, and the United States force fabricators toward programmable, energy-efficient equipment with pattern libraries.
Growth Catalysts
- EU Green Deal:REACH frameworks push European fabricators toward cleaner production technologies with reduced hydraulic fluid dependency, accelerating electric machine adoption.
- Automotive stamping:Lightweighting mandates intensify equipment procurement as OEMs seek structural rigidity without weight penalties in body-in-white components.
- CNC control integration:Programmable pattern libraries enable rapid changeover for packaging manufacturers entering with specialized surface-texturing requirements.
Market Restraints
- Input cost volatility:Hardened die and roller materials face price pressure from specialty steel supply concentration in select metallurgical clusters.
- Technical limitation:Laser engraving systems remain throughput-constrained for high-volume coil processing despite micron-level precision advantages.
- Substitution threat:Additive surface texturing methods challenge mechanical embossing for low-volume electronics housings requiring extreme customization.
Strategic Opportunities
- Underpenetrated geography:India's packaging sector offers white space as domestic food and beverage brands upgrade from manual to automated embossing.
- Technology convergence:Roll-forming integration with in-line embossing creates bundled equipment sales for construction and appliance manufacturers.
- Regulatory tailwind:China's dual carbon goals under MIIT GB standards recalibrate total cost of ownership calculations toward electric architectures.
Industry Challenges
- Skill gap in servo programming:Machine shops lack technicians trained in CNC pattern development and electric press parameter optimization.
- Integration complexity:Legacy hydraulic lines require complete infrastructure replacement rather than retrofit when upgrading to electric systems.
- Certification timeline:CE marking and EPA emissions compliance extend delivery schedules for customized equipment configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Embossing Machine Market |
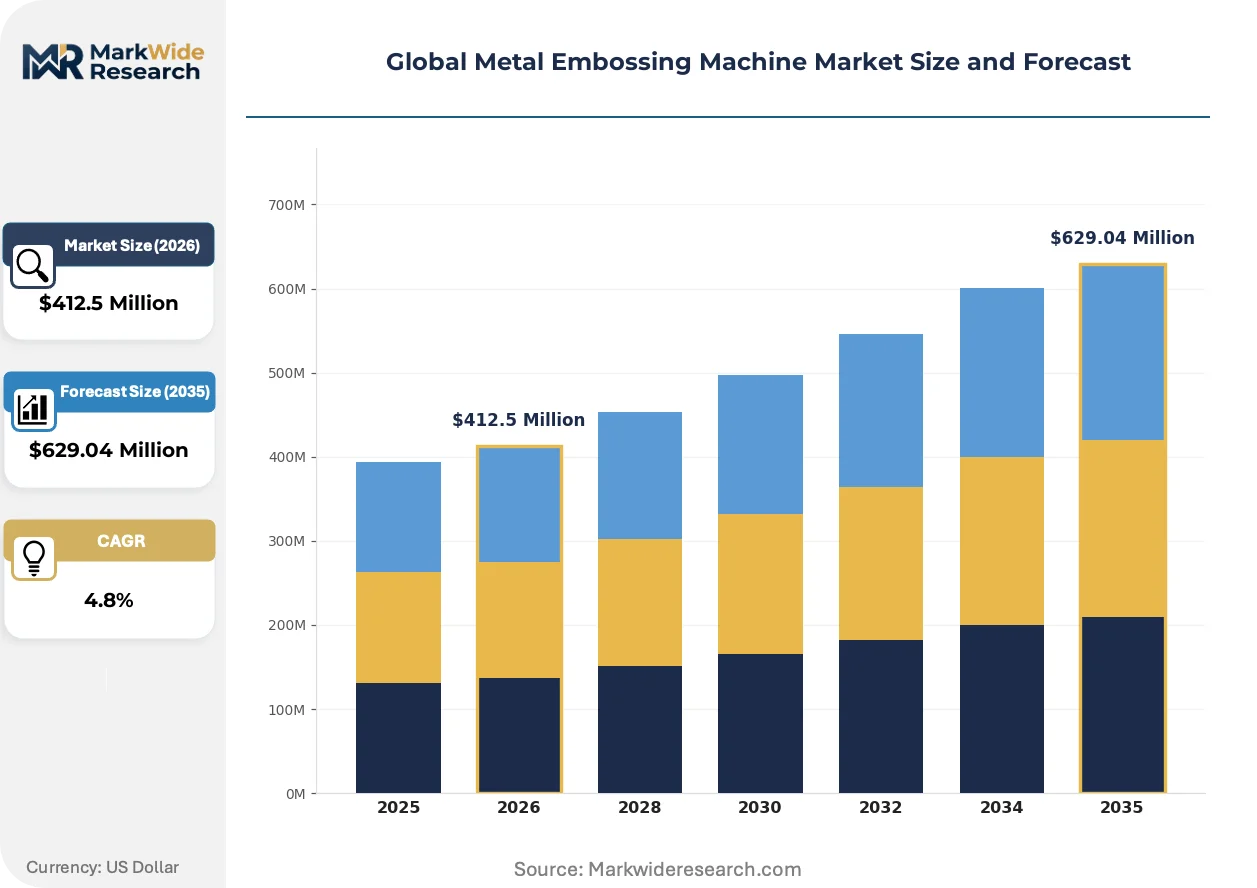
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Mechanical, Pneumatic, Electric, CNC Technology: Roll Embossing, Press Embossing, Roller Die, Magnetic Embossing, Laser Engraving Application: Automotive Components, Decorative Panels, Packaging Materials, Electronics Housings, Architectural Facades End User: Sheet Metal Fabricators, Packaging Manufacturers, Electronics Producers, Construction Firms, Furniture Makers |
| Companies Covered | Alliance Machine & Engraving, LLC, Anhui LIFU Machinery Technology, Jawo Sheng Precise Machinery Works Co., Ltd., The Bradbury Co., Inc., Pannier Corporation, Nanjing Harsle Machine Tool Co Ltd., Zhengzhou Ellsen Machinery Equipment Co Ltd., Big City Manufacturing Inc., Botou Yangcheng Cold Forming Machine Co Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Embossing Machine Market Strategic Shifts & Innovations
Digital control layers and energy-efficiency mandates are reconfiguring equipment specifications across automotive, packaging, and electronics verticals, compressing the competitive window for mechanical-only suppliers.
Servo-electric press technology is electrifying the medium-tonnage segment previously dominated by hydraulic systems. Automotive stampers in Germany and the United States are adopting these architectures for body panel production. The shift is compressing maintenance intervals and energy consumption while expanding programmable pattern capabilities.
REACH and the EU Green Deal are forcing hydraulic fluid elimination from production floors. European fabricators face compliance deadlines that favor dry electric systems. Packaging manufacturers in Germany and France are responding fastest, prioritizing equipment with reduced environmental liability.
After-sales service unbundling is fragmenting traditional vendor-customer relationships. End users in China and the United States now source spare dies and control modules through independent channels rather than captive service contracts. Electronics producers with specialized texture requirements are driving this behavior most aggressively.
Global Metal Embossing Machine Market Segmentation
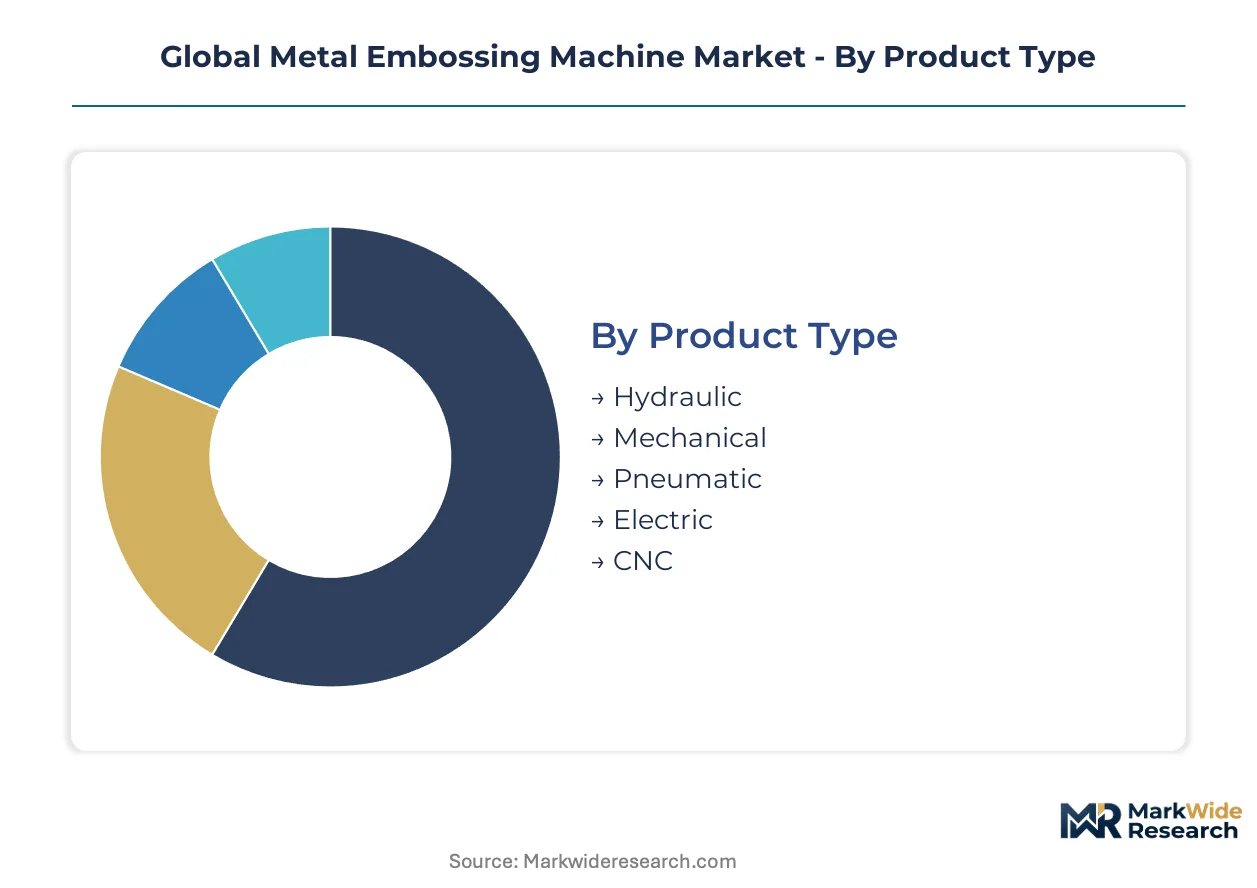
Metal embossing equipment segments diverge sharply by integration depth and automation sophistication. Standalone hydraulic presses dominate legacy installed bases, while servo-electric CNC systems embed into continuous coil processing lines for automotive and packaging throughput.
Product Type:
Standalone hydraulic and mechanical units serve job shops with batch production requirements, whereas electric and CNC architectures embed into automated manufacturing cells for OEM-tier suppliers.
- Hydraulic:These systems deploy fluid-powered actuation delivering 200-500 ton pressure ranges for thick-gauge structural components. German automotive stampers retain substantial hydraulic fleets for body-in-white production, though replacement cycles favor electric alternatives under EU Green Deal fluid-handling restrictions.
- Electric:Servo-driven architectures eliminate hydraulic infrastructure while cutting energy consumption through regenerative braking and programmable force curves. Packaging manufacturers in France and electronics producers in South Korea specify these systems for clean-room compliance and rapid pattern changeover.
- Mechanical:Crank-driven presses offer lowest capital outlay for simple repetitive patterns in standard gauges.
- Pneumatic:Compressed-air systems occupy niche applications requiring lower tonnage with minimal maintenance overhead.
- CNC:Computer-numerical control layers enable stored pattern libraries and real-time parameter adjustment for complex geometries.
Volume placements concentrate in Hydraulic; the faster expansion belongs to Electric.
Technology:
Cost tier separation distinguishes high-throughput mechanical contact methods from premium non-contact precision systems serving electronics and medical device specifications.
- Roll Embossing:Continuous rotary dies process metal coil at speeds exceeding 100 meters per minute for automotive heat shields and appliance panels. Chinese packaging converters deploy these systems at scale for food-grade container production, prioritizing throughput over pattern complexity.
- Laser Engraving:Fiber and CO2 laser sources ablate surface material without mechanical contact, achieving micron-level feature resolution for smartphone housings and semiconductor enclosures. Japanese electronics assemblers in Osaka and Nagoya clusters specify these systems for traceability marking and aesthetic texturing on aluminum alloys.
- Press Embossing:Single-stroke or progressive die configurations handle discrete blanks for structural reinforcement patterns.
- Roller Die:Custom-engraved cylindrical tools create longitudinal patterns on strip or coil feedstock.
- Magnetic Embossing:Electromagnetic force application enables rapid tooling change without mechanical die sets.
Standard-economy procurement favors Roll Embossing; premium positioning accrues to Laser Engraving.
Application:
Customer type maturity varies substantially across end-use verticals, with automotive and packaging commanding established specification standards while architectural applications remain specification-fragmented.
- Automotive Components:Embossed patterns enhance structural rigidity in floor pans, door panels, and heat shields while supporting lightweighting mandates. OEM stamping operations in Detroit, Stuttgart, and Shanghai specify equipment with automated die change and statistical process control integration.
- Electronics Housings:Surface texturing improves grip, heat dissipation, and electromagnetic shielding for consumer devices and industrial controls. Taiwanese and South Korean contract manufacturers drive demand for hybrid mechanical-laser systems combining throughput with precision.
- Decorative Panels:Aesthetic patterns serve appliance fronts, elevator interiors, and furniture surfaces.
- Packaging Materials:Food and beverage containers utilize embossed textures for brand differentiation and structural integrity.
- Architectural Facades:Building cladding applications require weather-resistant pattern durability and large-format processing capability.
Established demand centers on Automotive Components; Electronics Housings is climbing the fastest.
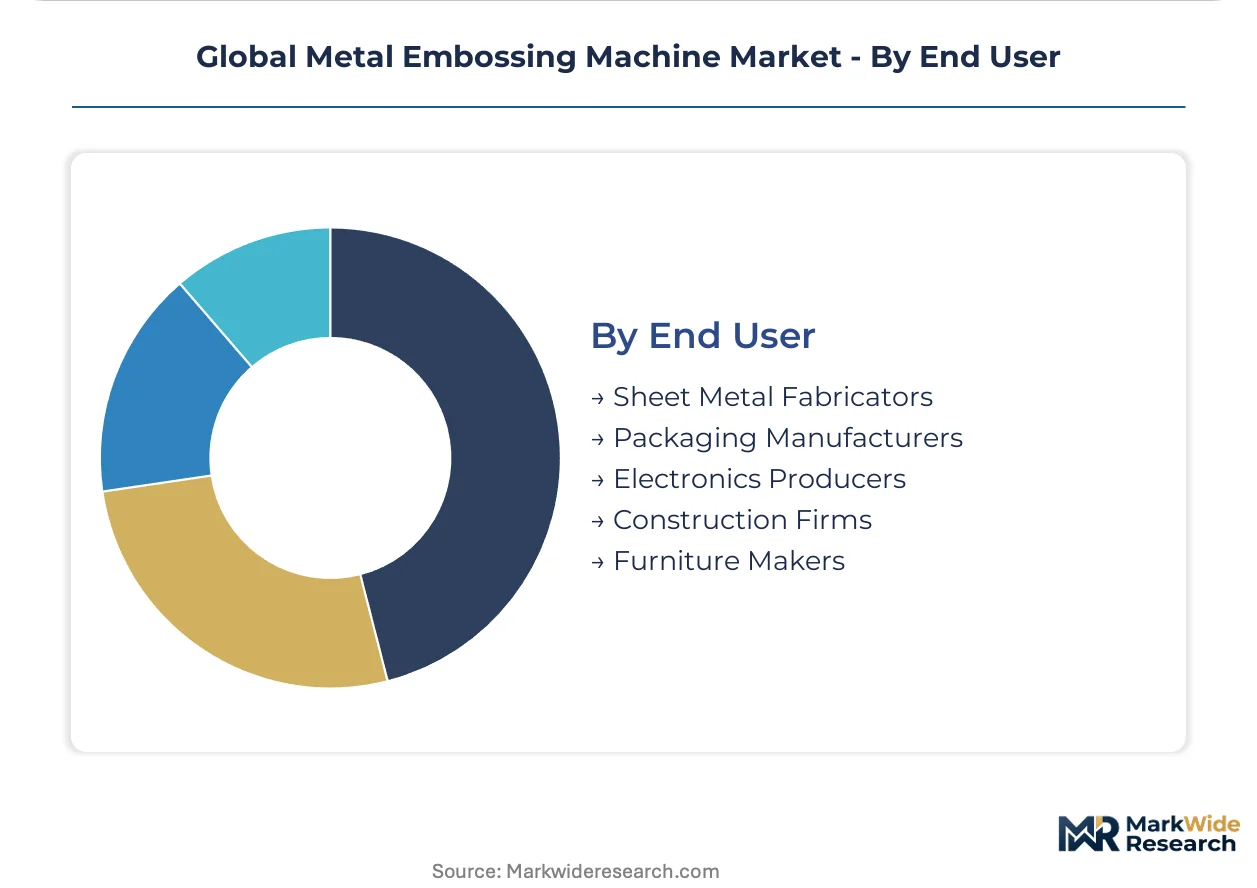
End User:
Geographic supply concentration shapes procurement patterns, with precision metalworking clusters in Germany, Japan, and the United States driving premium equipment specifications while emerging manufacturing bases prioritize cost-optimized configurations.
- Sheet Metal Fabricators:General-purpose job shops process diverse customer requirements across gauges and materials, requiring flexible equipment with quick-change tooling. Fabricators in the American Midwest and Germany's Baden-Württemberg region maintain the densest installed bases of mid-tonnage hydraulic and mechanical systems.
- Electronics Producers:Consumer device and semiconductor equipment manufacturers specify micron-precision surface texturing for aluminum, magnesium, and stainless enclosures. South Korean and Japanese electronics conglomerates drive specification standards for clean-room-compatible electric systems with vibration isolation and particulate containment.
- Packaging Manufacturers:Food, beverage, and cosmetics container producers utilize embossing for structural reinforcement and shelf differentiation.
- Construction Firms:Building material suppliers process metal roofing, siding, and interior panel systems.
- Furniture Makers:Decorative metal components for office and residential furnishings require aesthetic pattern consistency.
Procurement volume aggregates at Sheet Metal Fabricators; Electronics Producers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, China, and the United States concentrate equipment procurement for precision metalworking, with automotive stamping operations and electronics packaging driving specification standards across three continents.
United States
Automotive OEMs in Detroit and appliance manufacturers in the Midwest anchor hydraulic fleet replacement cycles. EPA emissions standards enforce energy-efficiency thresholds that favor servo-electric architectures over fluid-powered systems. Precision metalworking clusters in Ohio and Michigan specify equipment with automated die change capabilities.
Germany
REACH frameworks and the EU Green Deal mandate hydraulic fluid elimination from production floors by compliance deadlines. Stuttgart stamping operations and Baden-Württemberg fabricators lead electric machine adoption for body-in-white components. Bavarian packaging converters prioritize clean-room-compatible systems with reduced environmental liability.
China
MIIT GB standards for industrial equipment efficiency reshape domestic manufacturer design priorities and export competitiveness. Shanghai automotive clusters and Yangtze River Delta packaging producers drive volume demand for roll embossing systems. Dual carbon compliance timelines recalibrate total cost of ownership calculations toward electric architectures.
Japan
Electronics assemblers in Osaka and Nagoya clusters specify laser engraving systems for micron-level precision on smartphone housings. METI industrial efficiency guidelines push adoption of programmable pattern libraries. Kanto region contract manufacturers combine hybrid mechanical-laser systems for throughput and precision.
South Korea
Consumer device manufacturers in Seoul and Gyeonggi Province drive clean-room-compatible electric system specifications. MFDS-aligned production standards influence equipment selection for medical device enclosures. Busan-Ulsan industrial corridors anchor coil processing demand for automotive heat shield applications.
Global Metal Embossing Machine Market Key Industry Players
German and Japanese producers anchor one tier; Chinese specialists hold volume positioning through domestic supply chain density. The vendor base stratifies across integrated roll-forming suppliers, CNC control specialists, and regional job-shop equipment fabricators. Three archetypes dominate: precision-engineering houses serving electronics specifications, scale-oriented manufacturers supplying packaging converters, and diversified metalworking equipment conglomerates. Competitive moves center on technology licensing agreements and backward integration into hardened die production.
Within the precision-engineering tier, Alliance Machine & Engraving, LLC and The Bradbury Co., Inc. represent North American custom-solution capabilities. Anhui LIFU Machinery Technology occupies a position among Asia-based fabricators leveraging proximity to dense component supply networks. These three exemplify how geographic clustering shapes competitive positioning without requiring uniform technology portfolios.
| Leading Market Players |
|---|
| Alliance Machine & Engraving, LLC |
| Anhui LIFU Machinery Technology |
| Jawo Sheng Precise Machinery Works Co., Ltd. |
| The Bradbury Co., Inc. |
| Pannier Corporation |
| Nanjing Harsle Machine Tool Co Ltd. |
| Zhengzhou Ellsen Machinery Equipment Co Ltd. |
| Big City Manufacturing Inc. |
| Botou Yangcheng Cold Forming Machine Co Ltd. |
| Others |
Cost & Logistics Intelligence
Specialty steel for hardened dies and rollers flows from concentrated metallurgical clusters through three distinct pricing tiers before reaching end users. German automotive stampers absorb premium pricing for CE-certified electric architectures with programmable pattern libraries, while Chinese packaging converters prioritize economy-tier hydraulic units sourced through dense domestic supply networks.
Pricing Analysis
Volume placements concentrate in economy-tier hydraulic systems, while margin pools accrue to premium electric architectures with CNC control layers. Price differentiation hinges on certification grade—CE marking and EPA emissions compliance command substantial premiums—and after-sales service bundling versus unbundled spare-part sourcing. Pricing pressure stems from input cost volatility in specialty steel alloys as metallurgical supply concentrates in select geographies. Packaging manufacturers exhibit highest price sensitivity, prioritizing throughput-per-dollar over precision specifications, whereas electronics producers accept substantial premiums for micron-level laser engraving capability.
Supply Chain Analysis
Single-source vulnerability sits with hardened die and roller production concentrated in Germany, Japan, and select Chinese metallurgical zones. Raw material dependencies encompass specialty tool steels, tungsten carbide composites, and precision-ground bearing assemblies. Supply chain risk centers on tariff exposure as carbon border adjustments in Europe and dual carbon compliance timelines in China recalibrate cross-border equipment flows. Distribution runs through OEM-direct channels for large automotive stampers, regional equipment distributors serving job shops, and independent aftermarket channels for spare dies and control modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-electric architectures are displacing hydraulic installed bases across automotive and packaging verticals, compressing the competitive window for mechanical-only suppliers. This technology-transition phase demands differentiated positioning strategies across incumbent, entrant, and investor archetypes.
For Market Incumbents: Deploy backward integration into hardened die production to defend margin pools against independent aftermarket channels. Anchor capacity in Baden-Württemberg and Shanghai precision metalworking clusters to capture replacement-cycle demand as REACH and EPA deadlines force hydraulic fluid elimination. Counter additive surface texturing threats by expanding programmable pattern libraries and rapid-changeover capabilities. For New Entrants and Emerging Players: India's domestic food and beverage brands offer white space as packaging converters upgrade from manual to automated embossing. Target hybrid mechanical-laser system specifications for Taiwanese and South Korean electronics contract manufacturers seeking throughput-plus-precision combinations. Pursue technology licensing agreements with established CNC control specialists to bypass R&D capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-engineering houses with captive die-production capability in Germany and Japan. Long-term viability hinges on electric architecture transition completion and clean-room certification depth. Watch for inflection signals in MIIT GB standard enforcement timelines and EU carbon border adjustment implementation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die Production | Captive supply of hardened tooling insulates margins from specialty steel volatility and aftermarket fragmentation. |
| CNC Control Layer Licensing | Programmable pattern libraries accelerate electric architecture adoption among packaging manufacturers seeking rapid changeover. |
| Clean-Room Certification Investment | EPA and REACH compliance positions equipment for electronics and medical device enclosure specifications. |
| Roll-Forming Integration Partnership | Bundled equipment sales penetrate construction and appliance manufacturers with combined forming-texturing workflows. |
| India Market Development Program | Localized service presence captures packaging sector upgrade cycles from manual to automated embossing systems. |
Research Approach
Independent corroboration across plant engineers at automotive stamping operations, procurement leads at electronics contract manufacturers, and aftermarket service heads at regional distributors underwrites the qualitative findings. Primary interviews with OEM platform engineers, maintenance directors at packaging converters, and technical R&D directors at metallurgical suppliers combined with secondary validation from SEC 10-K filings, customs and trade data, and MIIT GB standard documentation. Bottom-up equipment shipment tallies and top-down manufacturing value-added estimates triangulate market sizing.
Rate-of-change decomposition across product type, technology architecture, application vertical, and end-user category structures the analytical framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Industry-specific forecast inputs encompass automotive lightweighting mandate compliance timelines and electronics packaging surface-texturing specification evolution.
Revisions become necessary when dual carbon compliance deadlines accelerate, carbon border adjustment mechanisms expand geographic coverage, or additive surface texturing technologies achieve cost parity for low-volume electronics applications. Forecasts reflect documented assumptions about regulatory enforcement pace and technology substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market