
 Lattice Cranes Market | 2026-2036
Lattice Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Lattice Cranes Market Foresight
A shift from single-source to multi-source procurement of high-capacity boom sections is restructuring supply economics for lattice crane builders. Liebherr sustains captive production of welded chord segments at its Swiss and German plants. Manitowoc competes through modular boom kits that slash field assembly hours on wind turbine sites. Zoomlion dominates domestic sourcing networks for structural steel across central China.
Lattice cranes are truss-framed lifting machines built from welded tubular or angular chord members with diagonal lacing, engineered to deliver extreme load-to-weight ratios at radii exceeding 100 meters. Their primary purpose centers on erecting heavy infrastructure where boom deflection limits and tip height requirements exclude telescopic alternatives. Mobile configurations lead volume shipments due to transportability between dispersed wind and petrochemical sites, while ultra high capacity units command concentrated margin pools tied to offshore installation vessels. Electric and hybrid technology segments attract engineering hours as port authorities and energy developers impose emissions protocols on construction fleets.
The EU Machinery Directive and China's GB/T crane standards govern structural design margins, fatigue testing protocols, and operator cab ergonomics that determine market access across the world's two largest demand basins. OSHA crane regulations in the United States mandate third-party inspection and assembly documentation that lengthen procurement cycles but elevate barriers for uncertified entrants. Stakeholders must track how carbon border adjustments and local-content rules for renewable energy infrastructure redirect manufacturing investment and aftermarket service footprints.
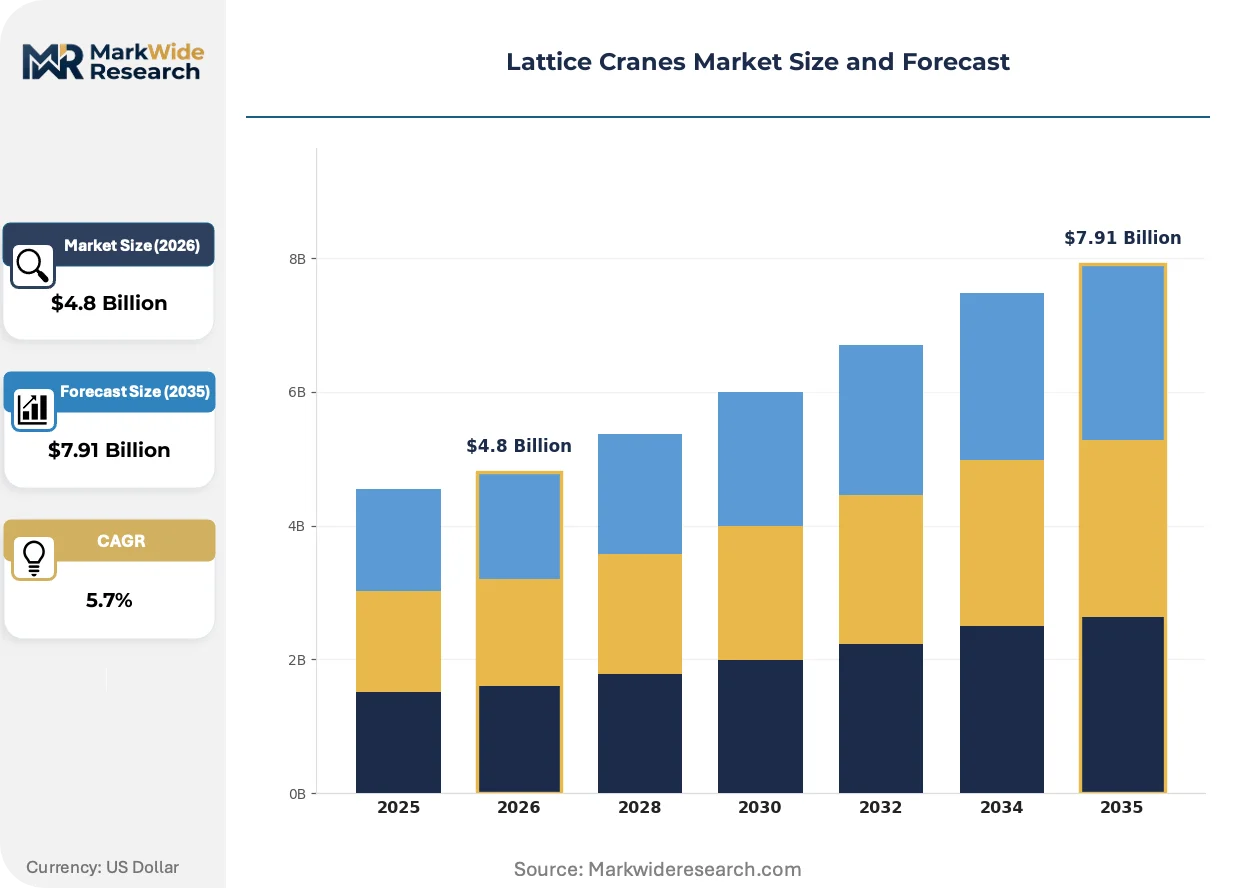
Market Dynamics
Offshore wind farm construction is compressing assembly timelines and forcing lattice crane builders to reconfigure boom logistics for turbine components exceeding 15 tons at 140-meter radii.
Growth Catalysts
- EU Green Deal offshore targets:Germany's North Sea expansion mandates 30 GW of floating wind capacity by 2035, requiring specialized heavy-lift vessels equipped with lattice boom systems.
- Steel recycling mandates:China's GB/T standards now incentivize high-strength low-alloy chord fabrication from scrap-fed electric arc furnaces, lowering embodied carbon in boom sections.
- Modular field assembly:Pin-connected lattice modules slash transport costs for inland wind sites in the United States where road width restrictions exclude telescopic alternatives.
Market Restraints
- Specialized weldment supply:Tubular chord segments require submerged-arc welding of quenched-and-tempered steel plate, with qualified fabricators concentrated in Lower Saxony and Jiangsu provinces.
- OSHA assembly documentation:Third-party inspection protocols for boom reconfiguration add 6-12 weeks to procurement cycles for US petrochemical turnarounds.
- Telescopic crawler encroachment:800-tonne class telescopic booms with luffing jibs now handle 70% of refinery maintenance lifts previously reserved for lattice configurations.
Strategic Opportunities
- Floating offshore wind in Portugal:Pre-assembly of turbine components at portside yards creates demand for land-based lattice systems with 180-meter tip heights.
- Carbon border adjustment mechanisms:EU CBAM phase-in from 2026 favors European-sourced boom sections with documented Scope 3 emissions, disadvantaging imported kits.
- Hybrid-electric powerpacks:Integration of battery-buffered diesel-electric drives allows port authorities in Rotterdam and Hamburg to meet zero-emission berth requirements.
Industry Challenges
- Welder certification pipelines:EN ISO 9606-1 qualification for high-strength steel chord fabrication faces 18-month backlogs at German technical institutes.
- Legacy fleet interoperability:Mixed-vendor boom sections from 1990s-era cranes lack pin-spacing standardization, complicating rental pool optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lattice Cranes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed, Mobile, Transportable, Self-Erecting End User: Construction, Mining, Shipbuilding, Infrastructure Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Technology: Hydraulic, Electric, Pneumatic, Hybrid |
| Companies Covered | Liebherr, Manitowoc, Tadano, Kobelco Cranes, Link-Belt Cranes, SANY, XCMG, Zoomlion, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lattice Cranes Market Shifts & Advancements
Digital twin integration and alternative material architectures are compressing design-validation cycles while emissions protocols reshape powertrain specifications across rental fleets.
High-strength composite lacing members are rewriting deflection limits for ultra-long boom configurations. Vestas and Siemens Gamesa specify carbon-fiber-reinforced polymer diagonals for turbine installation vessels operating in the Baltic Sea. The technology is rewriting the 100-meter boom threshold that previously separated lattice from telescopic competitiveness.
China's GB/T 3811-2021 crane design standard mandates fatigue testing protocols for welded joints under spectrum loading conditions. The regulation forces domestic manufacturers to adopt ultrasonic peening treatments previously reserved for European export models. Offshore installation contractors in the Bohai Bay region now require third-party fatigue certification for boom sections exceeding 20 years service life.
Consolidated procurement through equipment lessors is displacing direct OEM relationships for wind farm developers. United Rentals and Lampson International now specify boom interchangeability standards that force component commonality across manufacturer lines. The shift concentrates specification-setting power with fleet managers in Texas and Iowa rather than project engineers at construction sites.
Lattice Cranes Market Segmentation
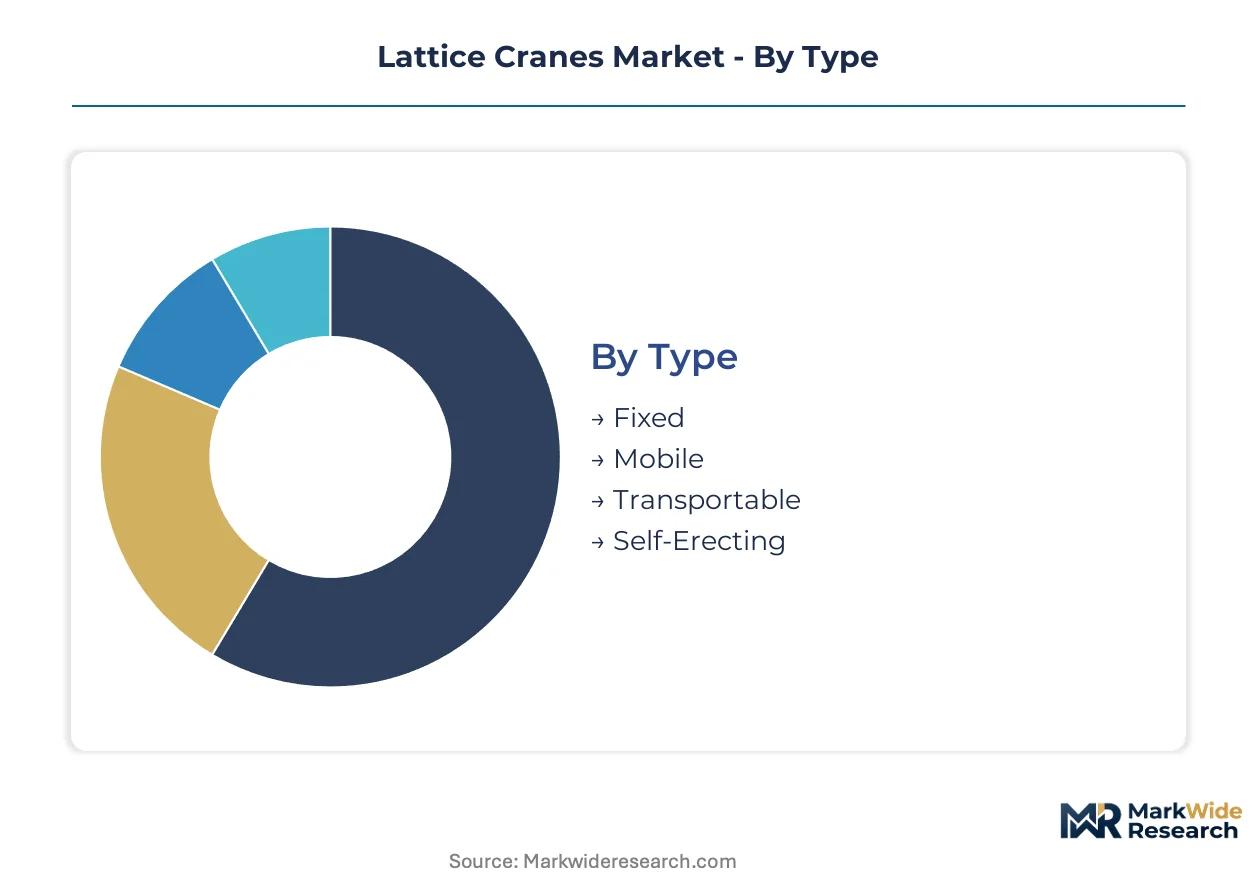
Segmentation in lattice cranes reveals how equipment specifications align with project economics across wind energy, petrochemical, and infrastructure verticals. Upgrade cycles and replacement demand vary dramatically by crane type, capacity class, and powertrain technology, reshaping procurement patterns for fleet operators and project developers.
Type:
Replacement cycles for fixed installations run 25-30 years, while mobile units face compressed 12-15 year refresh timelines driven by transport fatigue and boom inspection protocols.
- Fixed:Permanent foundation-mounted systems dominate offshore wind installation vessels and major petrochemical complexes. Demand concentrates in the North Sea and Bohai Bay where floating turbine pre-assembly requires 180-meter tip heights with minimal deflection.
- Mobile:Crawler-mounted configurations with modular pin-connected booms lead onshore wind and refinery turnaround markets. Fleet operators in Texas and Iowa prioritize rapid site-to-site relocation over maximum capacity.
- Transportable:Trailer-mounted lattice systems serve bridge construction and infrastructure projects requiring highway-legal dimensions without boom disassembly.
- Self-Erecting:Automated tower systems with integrated climbing mechanisms target urban construction sites in Germany and Japan where crane setup labor costs exceed equipment rental rates.
Mobile configurations sit at the top of the volume ranking, with self-erecting systems climbing the fastest as urban labor shortages intensify.
End User:
Cost tier segmentation separates project owners with captive fleets from rental-dependent contractors facing margin pressure on lump-sum contracts.
- Construction:Commercial and residential building applications favor transportable and self-erecting types for mid-rise concrete structures. German general contractors now specify electric powertrains to comply with municipal zero-emission zones in Hamburg and Munich.
- Mining:Open-pit extraction operations in Western Australia and Chile's Atacama deploy ultra high capacity fixed installations for dragline maintenance and crusher relocation. Dust ingress protection and extended duty cycles dominate specification requirements.
- Shipbuilding:Korean and Chinese shipyards utilize heavy-lift mobile configurations for hull block assembly and engine installation. Portside emissions regulations in Rotterdam and Singapore now disqualify diesel-only powertrains from long-term charter contracts.
- Infrastructure:Bridge and tunnel projects across the United States combine mobile lattice systems with specialized launching gantries. Federal highway width restrictions enforce modular boom transport configurations.
Construction commands the largest installed base, though infrastructure applications are expanding most quickly behind federal renewable energy and grid modernization appropriations.
Capacity:
Margin pools concentrate at capacity extremes, with low-capacity units competing on rental rate efficiency and ultra high capacity systems commanding project-specific engineering premiums.
- Low Capacity:Sub-100-tonne systems serve building construction and light infrastructure where telescopic alternatives compete aggressively. Chinese manufacturers dominate this tier through standardized chord fabrication and domestic steel sourcing.
- Medium Capacity:100-300-tonne configurations balance transportability with wind turbine nacelle handling. European rental fleets standardize on this class for multi-site renewable energy contracts.
- High Capacity:300-800-tonne mobile systems anchor onshore wind installation and refinery maintenance. Boom interchangeability standards from major lessors now force component commonality across OEM lines.
- Ultra High Capacity:800-tonne-plus fixed installations equip specialized offshore vessels and nuclear construction projects. Fatigue certification requirements under China's GB/T 3811-2021 and EU Machinery Directive extend procurement cycles to 18-24 months.
Medium capacity retains the deepest rental fleet penetration, while ultra high capacity shows the steepest expansion trajectory behind floating offshore wind targets.
Technology:
Customer type segmentation separates emission-regulated port authorities and municipal contractors from unregulated mining and remote infrastructure operators.
- Hydraulic:Conventional diesel-hydraulic powertrains retain dominance in mining and remote construction where electrical infrastructure is absent. OEMs now integrate exhaust aftertreatment to meet EU Stage V and US EPA Tier 4 Final standards.
- Electric:Grid-connected and battery-electric systems capture portside and urban construction demand. Rotterdam's zero-emission berth requirements and Hamburg's port authority mandates now specify electric or hybrid powertrains for terminal cranes.
- Pneumatic:Compressed-air systems serve specialized hazardous environment applications in chemical processing and underground mining where spark ignition risks exclude electrical alternatives.
- Hybrid:Diesel-electric architectures with battery buffering reduce fuel consumption and enable zero-emission operation in regulated zones. Siemens Gamesa and Vestas now require hybrid powertrains for turbine installation vessel charters in the Baltic Sea.
Hydraulic systems maintain the largest installed base, though hybrid configurations are gaining share fastest as emissions protocols expand beyond port authorities to inland waterway construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters around Rostock and Bremerhaven anchor lattice crane deployment for North Sea offshore wind pre-assembly. Port authorities in Hamburg enforce EU Green Deal emissions protocols that reshape powertrain specifications across European rental fleets.
Germany
Offshore wind turbine pre-assembly at Rostock and Bremerhaven ports drives demand for 180-meter tip height systems. The EU Machinery Directive mandates fatigue testing protocols for welded boom joints under spectrum loading. Lower Saxony hosts qualified submerged-arc welding fabricators facing 18-month EN ISO 9606-1 certification backlogs.
China
Floating wind targets in the Bohai Bay region require specialized heavy-lift vessels with lattice boom configurations. GB/T 3811-2021 crane design standards impose third-party fatigue certification for boom sections exceeding 20 years service life. Jiangsu province concentrates tubular chord segment fabricators serving domestic OEM supply networks.
United States
Onshore wind installation across Texas and Iowa relies on modular pin-connected booms for rapid site relocation. OSHA crane regulations mandate third-party inspection and assembly documentation that extends procurement cycles by 6-12 weeks. Federal highway width restrictions enforce transportable boom configurations for inland infrastructure projects.
Japan
Urban construction sites in Tokyo and Osaka deploy self-erecting automated tower systems to offset climbing labor costs. METI industrial standards govern structural design margins for high-strength steel chord fabrication. Nagoya-based shipyards utilize heavy-lift mobile configurations for hull block assembly and engine installation.
United Kingdom
North Sea floating wind expansion mandates specialized installation vessels equipped with lattice boom systems. HSE offshore safety regulations align with EU Machinery Directive fatigue testing requirements for welded joints. Scottish port clusters at Aberdeen and Dundee develop pre-assembly yards for 15-ton turbine components at 140-meter radii.
Lattice Cranes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric and hybrid powertrain integration for emission-regulated port authorities. The vendor base concentrates around three strategic archetypes: European specialists in offshore installation vessel systems, Chinese fabricators leveraging domestic steel sourcing networks, and diversified industrial equipment conglomerates with modular boom kit portfolios. Competitive positioning hinges on backward integration into welded chord segment production and strategic partnerships with floating wind developers for vessel charter specifications.
Among German-Swiss engineering groups, Liebherr exemplifies the captive production archetype through in-house welded chord manufacturing. Manitowoc occupies a position representing the modular assembly tier with field-optimized boom kits. Zoomlion anchors the domestic sourcing vector within Chinese central province steel networks. These three entities represent distinct competitive postures without implying specific market share or strategic action claims.
| Leading Market Players |
|---|
| Liebherr |
| Manitowoc |
| Tadano |
| Kobelco Cranes |
| Link-Belt Cranes |
| SANY |
| XCMG |
| Zoomlion |
| Terex Corporation |
| Others |
Supply & Pricing Matrix
Captive production of welded chord segments anchors supply positions and pricing power for lattice crane manufacturers serving offshore wind installation fleets. German and Swiss OEMs maintain in-house submerged-arc welding capacity that insulates margin structures from raw steel volatility, while Chinese fabricators leverage Jiangsu province scrap-fed electric arc furnace networks to undercut import parity on boom section kits.
Pricing Analysis
Quenched-and-tempered steel plate costs pass through directly to boom section pricing, with EN ISO 9606-1 certified fabricators commanding 15-20% premiums over uncertified alternatives. Three-tier pricing structure across premium certified, standard commercial, and economy import levels separates project-specific engineering from rental fleet commoditization. Cost compression in the economy tier intensifies because Chinese OEMs standardize chord fabrication for domestic wind farm deployment. Rental fleet operators in Texas and Iowa exhibit highest price sensitivity, while offshore vessel charterers prioritize fatigue certification over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle demand from specialized offshore installation vessel operators, while equipment lessors aggregate procurement across modular boom kit suppliers. Tubular chord fabrication concentrates in Germany's Lower Saxony, China's Jiangsu province, and Switzerland's alpine industrial zones. High-strength low-alloy steel plate, carbon-fiber-reinforced polymer lacing, and battery-buffered powerpacks constitute critical input dependencies. Single-source vulnerability runs through qualified submerged-arc welding capacity facing 18-month certification backlogs. Distribution runs through portside pre-assembly yards in Bremerhaven, Rostock, and Bohai Bay rather than traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lattice crane procurement operates as a geographic-arbitrage play between EU carbon border adjustment exposure and Chinese domestic steel cost advantages. The regulatory differential on embodied carbon documentation creates divergent landed cost structures for boom sections crossing into European portside yards.
For Market Incumbents: Extend captive welding certification capacity to capture floating offshore wind vessel charter specifications before EN ISO 9606-1 backlogs widen. Deepen backward integration into scrap-fed electric arc furnace partnerships to neutralize EU CBAM phase-in exposure on imported chord segments. For New Entrants and Emerging Players: Launch via portside equipment lessor partnerships targeting hybrid-electric powerpack retrofits for Rotterdam and Hamburg zero-emission berth compliance. White-space concentration sits with carbon-fiber-reinforced polymer diagonal lacing for Baltic Sea turbine installation vessels exceeding 100-meter boom thresholds. For Investors and Strategic Acquirers: Roll-up economics work for regional welding certification specialists because fragmented EN ISO 9606-1 qualification pipelines face structural capacity constraints. Five-to-ten-year viability hinges on boom interchangeability standard adoption by United Rentals and Lampson International. The inflection signal to watch is floating offshore wind capacity auction awards in Portugal and Scotland.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Welded Chord Production | Captive EN ISO 9606-1 certification capacity secures priority access to German North Sea vessel charters. |
| Hybrid-Electric Powerpack Development | Rotterdam port authority zero-emission mandates now disqualify diesel-only systems from long-term contracts. |
| Carbon-Fiber Lacing Partnership | Vestas and Siemens Gamesa specifications for Baltic Sea vessels rewrite 100-meter boom competitiveness thresholds. |
| Modular Boom Kit Standardization | United Rentals interchangeability requirements force component commonality across OEM product lines. |
| Portside Pre-Assembly Yard Expansion | Scottish clusters at Aberdeen and Dundee capture 15-ton turbine component handling demand at 140-meter radii. |
Research Methodology
Bottom-up wind farm and petrochemical project modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with offshore installation vessel operators, equipment lessor procurement directors, submerged-arc welding certification instructors, and port authority emissions compliance officers combined with secondary validation from EU Machinery Directive implementation reports, China's GB/T 3811-2021 certification databases, and OSHA crane regulation filings. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrices map crane capacity class, powertrain technology, and end-use vertical demand against regional project pipelines throughout the forecast period. Segmentation dimensions span fixed/mobile/transportable/self-erecting types, low/medium/high/ultra-high capacity tiers, and hydraulic/electric/pneumatic/hybrid technologies. CAGRs derive from project-based demand forecasting rather than extrapolated trend fitting. Offshore wind capacity targets and steel recycling mandate compliance curves constitute industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU carbon border adjustment enforcement intensity and Chinese domestic steel price volatility. Projections reflect assumptions on welder certification pipeline expansion and floating offshore wind vessel deployment schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market