
 Australia Construction Machinery Market | 2026-2036
Australia Construction Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Construction Machinery Market Analysis
Skilled heavy equipment operator availability is collapsing across Queensland and Western Australia, forcing contractors to prioritize machinery with telematics and assisted controls. Caterpillar leverages its integrated dealer network to sustain parts availability in remote mining territories. Komatsu anchors its position through autonomous haulage system deployment at Pilbara iron ore operations. JCB specializes in compact equipment lines that navigate tight urban construction sites in Sydney and Melbourne.
Australia construction machinery encompasses earth-moving, material-handling, and compaction equipment engineered to Australian Design Rules noise and emissions thresholds, typically powered by diesel engines rated above 19 kilowatts or battery-electric alternatives for underground applications. This equipment serves commercial building, civil infrastructure, and resource extraction by delivering rated breakout force, lift capacity, and cycle times calibrated to local material densities and climatic conditions. Hydraulic technology dominates installed base maintenance schedules while electric and autonomous systems attract replacement investment from mining companies seeking operational expenditure reduction. Small and medium size classes occupy the volume leadership in residential and commercial contracting, whereas extra-large excavators and dump trucks concentrate margin pools in Bowen Basin coal and Pilbara iron ore extraction.
The Department of Infrastructure enforces Australian Design Rules that dictate emissions compliance for imported machinery, while WorkSafe jurisdictions across states mandate operator certification and site-specific equipment inspection protocols. Standards Australia publishes AS 1418 crane and hoist standards that shape manufacturer product configurations for local market access. Stakeholders must monitor the interplay between state-level procurement preferences for local content and federal emissions harmonization pressures when positioning fleet investment and distribution strategies.
Market Dynamics
Fleet electrification pressures from Australian Design Rules emissions thresholds are compressing diesel equipment replacement cycles while forcing distributors to reconfigure service capabilities around battery-electric powertrains and high-voltage technician certification.
Growth Catalysts
- Western Australia mining fleet modernization:Iron ore operators in the Pilbara are replacing aging haul trucks and excavators to meet productivity targets and emissions benchmarks, sustaining import demand for extra-large equipment classes.
- Queensland infrastructure corridor expansion:State government priority projects linking Brisbane to the Sunshine Coast are accelerating civil contractor equipment procurement for earth-moving and compaction applications.
- Battery-electric underground equipment:Hard-rock mining operations are adopting zero-emission loaders and trucks to eliminate diesel particulate exposure and ventilation infrastructure costs.
Market Restraints
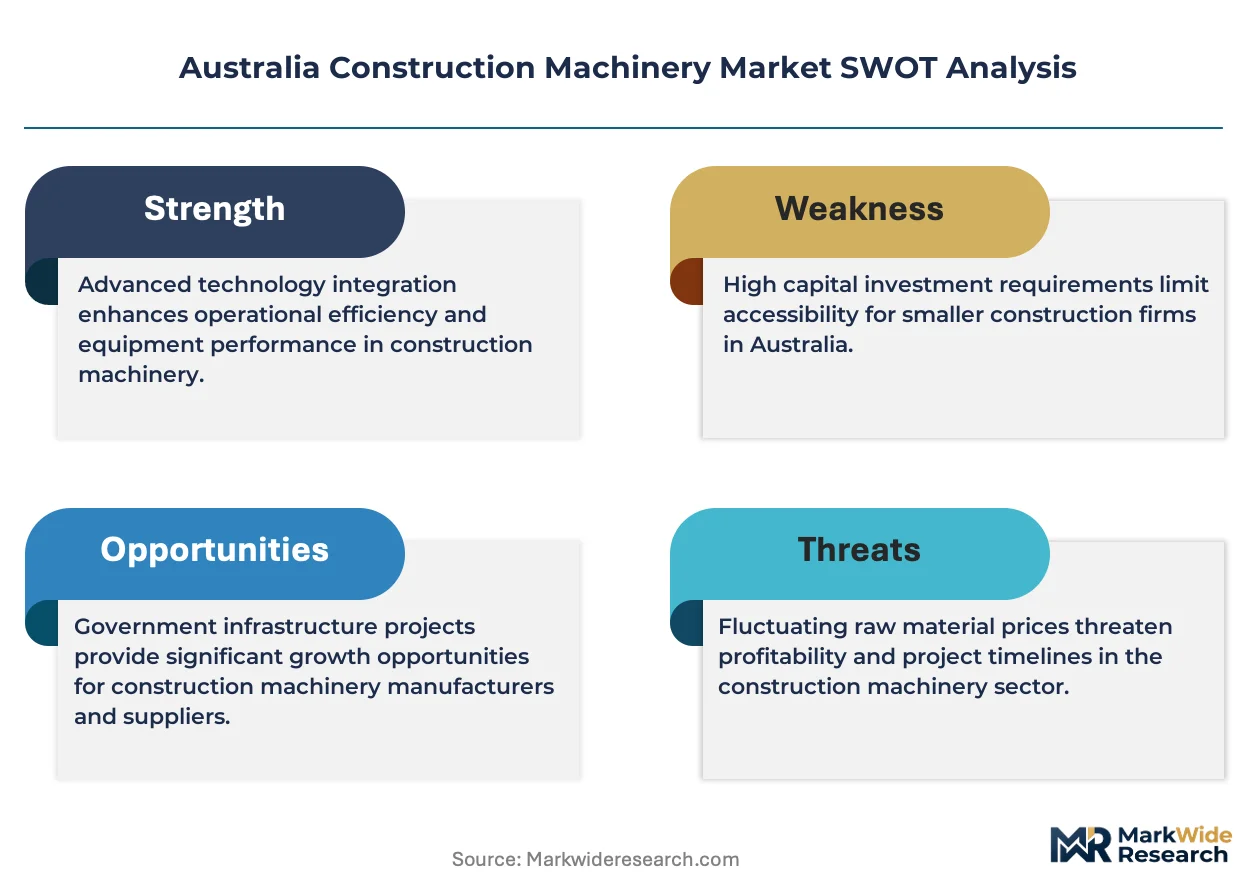
- Steel and hydraulic component cost volatility:Input price swings for high-grade steel and precision hydraulic systems compress manufacturer margins and destabilize contractor quoting confidence.
- Dealer network concentration in remote territories:Parts and service availability depends on a thin distribution layer across Western Australia's mining regions, creating downtime risk for isolated operations.
- Australian Design Rules compliance friction:Tightening emissions thresholds for imported machinery extend homologation timelines and limit model availability relative to other markets.
Strategic Opportunities
- Telematics-integrated rental models:Equipment rental channels are embedding usage-based billing and predictive maintenance to capture contractors avoiding outright purchase.
- Autonomous haulage retrofit kits:Technology convergence between machine vision and fleet management software enables partial automation upgrades for existing truck fleets without full replacement.
- Tasmania hydropower construction:Renewable energy storage projects create underpenetrated demand for specialized tunnelling and dam construction equipment.
Industry Challenges
- Heavy equipment operator certification backlog:WorkSafe jurisdictions face processing delays for high-risk licenses, constraining crew availability for Queensland and Western Australia projects.
- High-voltage technician skill scarcity:Battery-electric equipment maintenance requires qualifications that training institutions have not yet scaled to match fleet transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Construction Machinery Market |
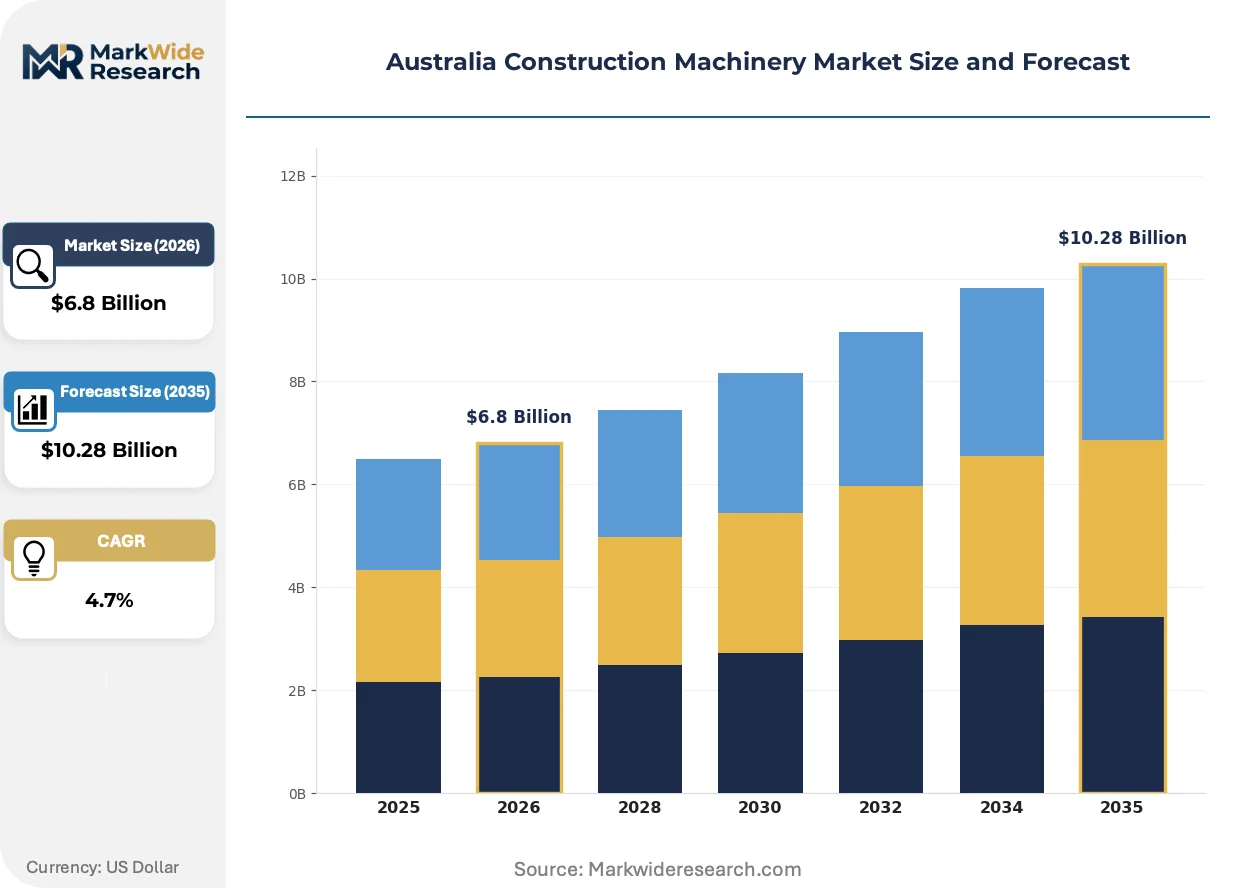
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Dump Trucks, Gradalls Technology: Hydraulic, Electric, Pneumatic, Autonomous End User: Contractors, Builders, Civil Engineers, Mining Companies Size: Small, Medium, Large, Extra Large |
| Companies Covered | Caterpillar, Komatsu, Volvo Construction Equipment, Hitachi Construction Machinery, Liebherr, XCMG, JCB, SANY, Kobelco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Construction Machinery Market Emerging Trajectories
Digital fleet management and powertrain electrification are restructuring how contractors acquire, operate, and maintain construction machinery across Australian states.
Telematics platforms that capture machine health data and operator behavior patterns are displacing scheduled maintenance contracts in mining and large civil fleets. Pilbara iron ore operators now mandate real-time payload and fuel consumption monitoring as a procurement condition. Equipment manufacturers are bundling connectivity hardware as standard to retain aftermarket service attachment.
The Department of Infrastructure's progressive tightening of Australian Design Rules emissions thresholds is compressing diesel engine certification timelines and accelerating battery-electric product development. Import homologation costs are rising for Tier 3 and Tier 4 interim engines that fail to meet forthcoming thresholds. Queensland contractors report extended delivery lead times for compliant excavators in the 20-35 tonne class.
Contractors are consolidating equipment procurement through national rental chains rather than fragmented local dealers, concentrating volume leverage and standardizing fleet specifications. This consolidation displaces independent dealer relationships that historically dominated regional markets. Sydney and Melbourne commercial construction sites show the strongest shift toward multi-year rental agreements with full maintenance inclusion.
Australia Construction Machinery Market Segmentation
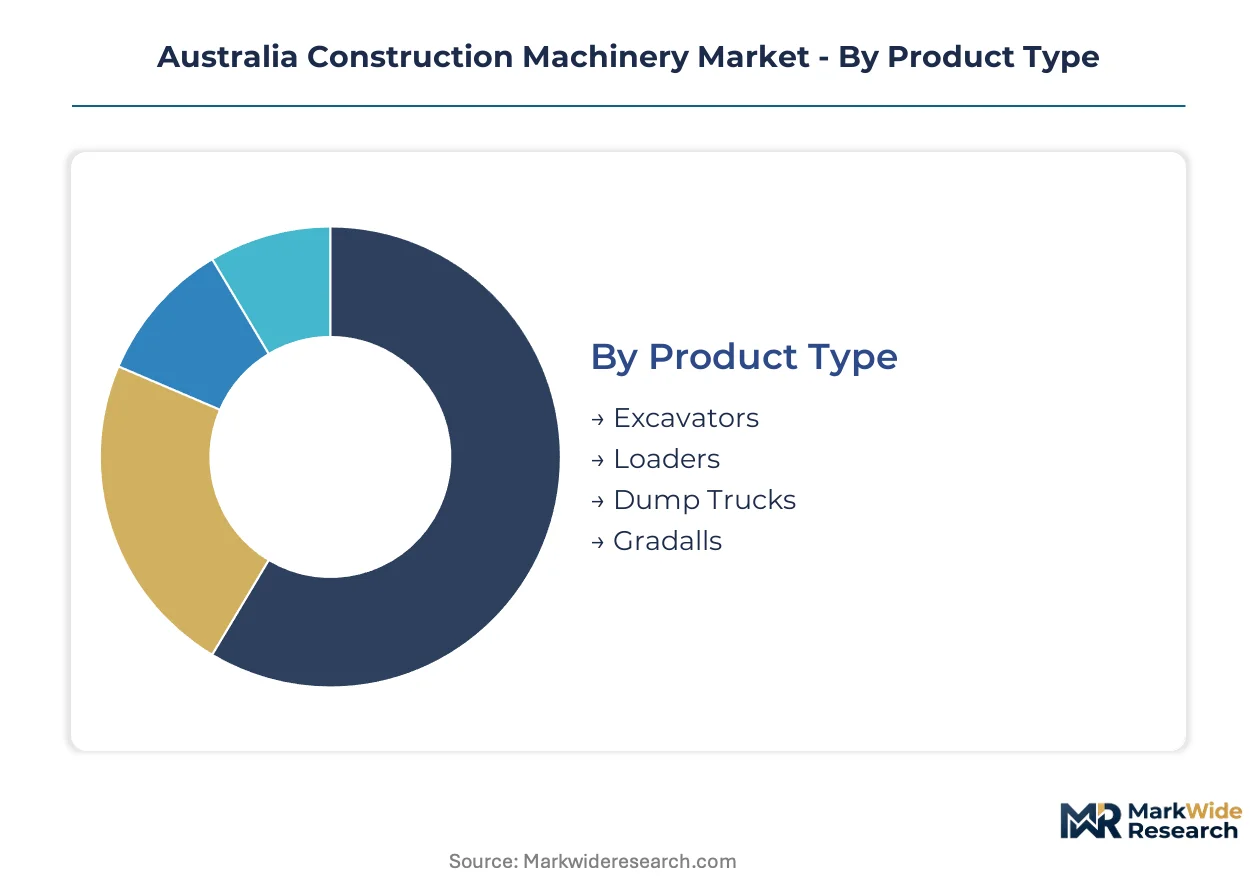
Equipment procurement patterns across Queensland and Western Australia diverge sharply by application intensity and regulatory exposure. Contractors align fleet composition with project duration, site access constraints, and Australian Design Rules compliance timelines.
Product Type:
Rental channels dominate small-class excavator and loader flows to urban contractors, while direct manufacturer relationships govern extra-large dump truck procurement by Pilbara mining operators.
- Excavators:Tracked and wheeled variants span 1.5 to 800 tonne operating weights with hydraulic boom configurations optimized for Australian material densities. Queensland civil contractors are concentrating procurement in the 20-35 tonne class for Brisbane-Sunshine Coast corridor earthworks, though Australian Design Rules compliance delays are extending delivery timelines.
- Loaders:Articulated wheel loaders deliver rated breakout force calibrated to Pilbara iron ore and Bowen Basin coal material specifications. Western Australia mining fleet modernization programs are accelerating replacement demand for large-class units with telematics-integrated payload systems.
- Dump Trucks:Rigid and articulated haulers serve surface mining and quarry operations with rated capacities from 25 to 400 tonnes.
- Gradalls:Wheeled excavators with telescoping booms navigate restricted-access urban infrastructure sites in Sydney and Melbourne.
By volume, excavators lead. By growth pace, dump trucks are expanding most quickly.
Technology:
Cost tier stratification separates mature hydraulic platforms from emerging electric and autonomous systems requiring high-voltage technician certification.
- Hydraulic:Dominant power transmission technology utilizing piston pumps and valve control systems rated to 350 bar operating pressure. Established service networks across Australia sustain aftermarket parts availability, though component cost volatility compresses fleet operator maintenance budgets.
- Electric:Battery-electric powertrains eliminate diesel particulate exposure in underground hard-rock mining applications. Queensland and Western Australia operations are adopting zero-emission loaders to reduce ventilation infrastructure capital expenditure.
- Pneumatic:Compressed-air systems serve specialized tunneling and confined-space applications with reduced ignition risk profiles.
- Autonomous:Machine vision and fleet management convergence enables partial automation retrofits for existing haul truck fleets without full replacement capital outlay.
By installed base, hydraulic systems dominate. By investment trajectory, autonomous technology is gaining share fastest.
End User:
Customer type determines procurement channel preference, with mining companies favoring direct manufacturer partnerships and residential contractors consolidating through national rental chains.
- Contractors:Small and medium earth-moving specialists serving residential and commercial construction across Sydney, Melbourne, and Brisbane metropolitan areas. Skilled operator shortages are forcing prioritization of machinery with assisted controls and telematics-based fleet management.
- Builders:Commercial construction firms executing multi-story developments and infrastructure foundations.
- Civil Engineers:State government priority project delivery organizations managing Queensland infrastructure corridor expansion.
- Mining Companies:Iron ore and coal operators in Western Australia's Pilbara and Queensland's Bowen Basin driving extra-large equipment replacement cycles.
By fleet value, mining companies command the largest share. By procurement volume acceleration, contractors are climbing the fastest.
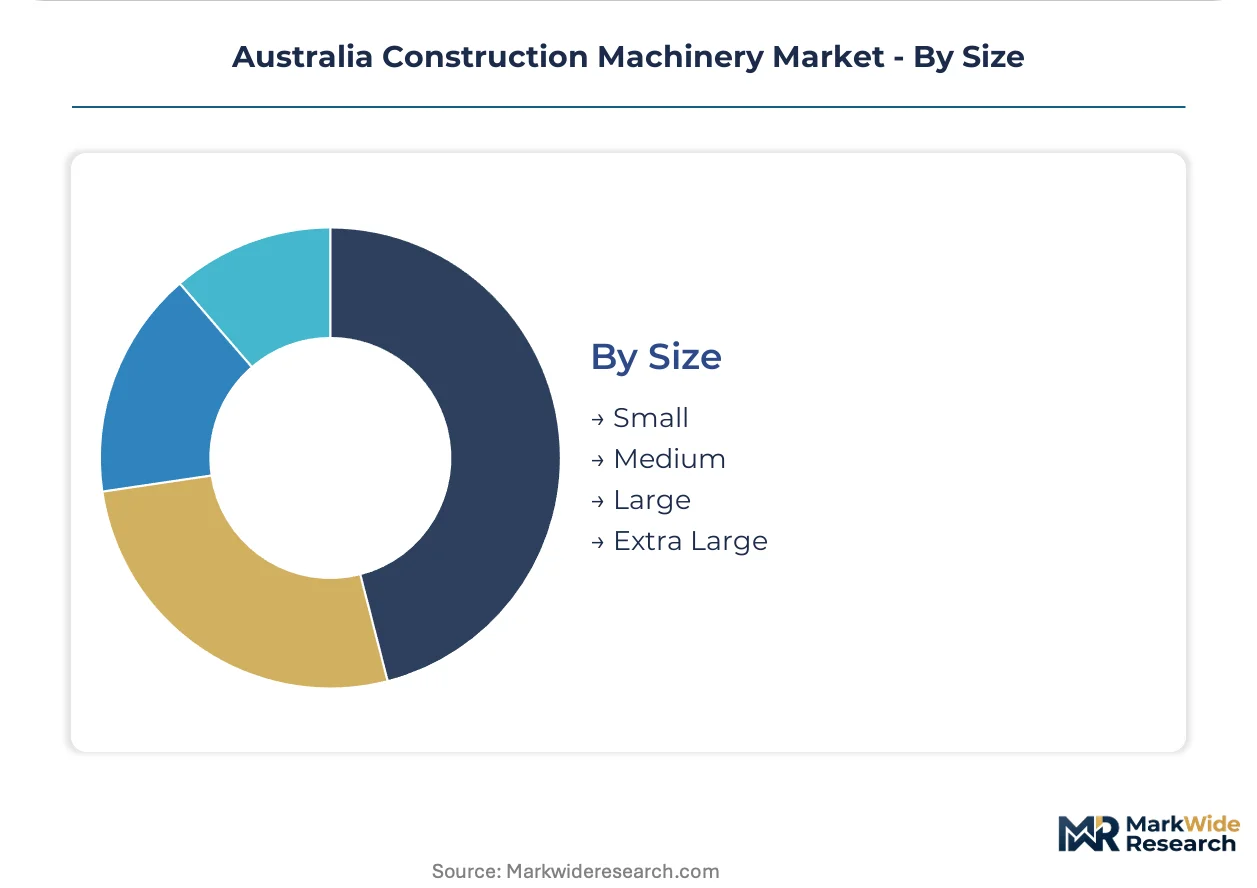
Size:
Application geography dictates size class distribution, with urban density favoring compact equipment and remote resource extraction demanding maximum payload capacity.
- Small:Equipment under 10 tonnes operating weight navigates tight urban construction sites and residential subdivision development. Sydney and Melbourne commercial contractors report strongest shift toward multi-year rental agreements with full maintenance inclusion for this class.
- Medium:10-45 tonne machines balance mobility and productivity for regional civil infrastructure projects.
- Large:45-100 tonne excavators and loaders serve quarry and surface mining operations with moderate production scale.
- Extra Large:Equipment exceeding 100 tonnes delivers rated breakout force and haul capacity calibrated to Pilbara iron ore material densities. Western Australia mining fleet modernization sustains import demand despite thin dealer network coverage creating downtime risk for isolated operations.
By unit shipments, small and medium classes lead. By margin concentration, extra large equipment is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Infrastructure administers Australian Design Rules that govern emissions compliance for imported construction machinery across all states and territories. These federal standards interact with state-level procurement preferences and WorkSafe jurisdiction requirements to create a complex regulatory environment for fleet operators.
Western Australia
Pilbara iron ore operators are driving extra-large equipment replacement cycles for haul trucks and excavators calibrated to local material densities. The state's Department of Mines, Industry Regulation and Safety enforces site-specific equipment inspection protocols for surface mining operations. Perth serves as the primary distribution hub, though thin dealer network coverage across remote mining regions creates downtime risk for isolated operations.
Queensland
Civil contractors are accelerating procurement of 20-35 tonne excavators for the Brisbane-Sunshine Coast infrastructure corridor expansion. WorkSafe Queensland mandates operator certification and high-risk license processing that currently faces significant backlogs. The Bowen Basin coal region concentrates demand for large-class articulated wheel loaders with telematics-integrated payload systems.
New South Wales
Sydney commercial construction sites show the strongest shift toward multi-year rental agreements with full maintenance inclusion for small and medium equipment classes. The state's Environmental Protection Authority enforces noise and emissions thresholds that align with Australian Design Rules compliance timelines. Greater Sydney's urban density favors compact equipment lines that navigate tight residential and commercial development sites.
Victoria
Melbourne metropolitan contractors are consolidating procurement through national rental chains rather than fragmented local dealers. WorkSafe Victoria administers operator certification requirements that interact with federal emissions standards for imported machinery. The city's commercial construction sector drives demand for wheeled excavators with telescoping booms that access restricted-access infrastructure locations.
Australia Construction Machinery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure in the Australian construction machinery market. The upper tier comprises full-line manufacturers with established dealer networks and aftermarket service capabilities, while the specialist tier includes regional players focused on specific equipment categories or geographic niches. Strategic archetypes include integrated technology providers pursuing autonomous and electric powertrain development, rental-focused distributors emphasizing fleet management services, and compact equipment specialists targeting urban construction density. Dominant competitive moves encompass dealership network consolidation in remote territories and portfolio diversification into battery-electric product lines to meet tightening emissions thresholds.
Within the integrated technology provider tier, Caterpillar and Komatsu anchor market presence through established distribution infrastructure and mining sector relationships. JCB occupies a position exemplifying the compact equipment specialist archetype, with its product configuration aligned to Australian Design Rules requirements for urban construction applications. Volvo Construction Equipment represents the European-origin diversified manufacturer archetype, competing across multiple equipment categories with emphasis on emissions-compliant powertrain development. These three companies illustrate the strategic positioning variations that define competitive interaction in this market.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Liebherr |
| XCMG |
| JCB |
| SANY |
| Kobelco |
| Others |
Supply Flow & Price Mechanics
Extended delivery timelines of 12-18 months for Australian Design Rules-compliant excavators concentrate pricing power with distributors holding confirmed import slots, while steel and hydraulic component volatility compresses margins for contractors locked into fixed-price project bids. This inventory scarcity dynamic rewards early-ordering mining operators and penalizes reactive procurement from civil contractors facing Queensland infrastructure corridor deadlines.
Pricing Analysis
Perth-to-Brisbane price spreads of 8-15% for identical equipment classes reflect Western Australia's thin dealer network coverage and higher logistics costs for remote Pilbara delivery. Three-tier pricing structure across premium OEM, mid-tier challenger, and economy import levels stratifies by after-sales service bundling and telematics integration depth. Cost compression in the 20-35 tonne excavator class is intensifying because Australian Design Rules compliance delays limit model availability and concentrate demand on certified inventory. Residential contractors exhibit highest price sensitivity due to thin project margins, whereas iron ore operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Inventory carry costs for high-grade steel castings and precision hydraulic valve blocks now extend 180-270 days for Australian distributors, forcing working capital reallocation toward confirmed manufacturer allocations. Component sourcing draws from Japan, South Korea, and Germany for Tier 4 final powertrains and autonomous control systems. Single-source vulnerability concentrates in precision hydraulic pump manufacturing, where two suppliers dominate global capacity. Distribution runs through Caterpillar and Komatsu integrated dealer networks in mining territories, while national rental chains consolidate urban contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia construction machinery market enters a cyclical recovery phase anchored to Western Australia mining fleet modernization programs and Queensland state government infrastructure commitments. Replacement demand from aging Pilbara haul fleets provides durable volume support despite near-term steel cost volatility.
For Market Incumbents: Secure aftermarket service attachment rates by embedding telematics hardware as standard equipment and pre-positioning high-voltage technician certification programs ahead of battery-electric fleet transitions. Threat substitution from autonomous haulage retrofit kits demands accelerated R&D investment in partial automation upgrades. Channel control through exclusive parts distribution agreements defends margin pools against emerging rental-chain consolidation. For New Entrants and Emerging Players: Anchor in Tasmania's underpenetrated hydropower construction sector, where specialized tunnelling equipment demand outpaces established OEM service coverage. Battery-electric underground loaders for hard-rock mining operations present the most penetrable segment, with ventilation cost reduction providing a compelling procurement rationale. Go-to-market execution should prioritize direct relationships with mine engineering departments rather than distributor intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming construction machinery divisions lacking Australian Design Rules certification capabilities. Long-term viability hinges on electrification transition execution and autonomous technology integration over the next decade. Acquisition candidates with captive high-voltage technician training pipelines command strategic premium. Watch for inflection when Australian Design Rules emissions threshold announcements accelerate diesel equipment pre-buying patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Retrofit Deployment | Machine vision integration with Pilbara fleet management systems extends asset life without full replacement capital. |
| Battery-Electric Product Line Expansion | Zero-emission underground equipment eliminates diesel particulate exposure and reduces ventilation infrastructure expenditure. |
| Telematics-Integrated Rental Model Scaling | Usage-based billing and predictive maintenance capture contractors avoiding outright purchase in Sydney and Melbourne. |
| High-Voltage Technician Certification Investment | Training pipeline development addresses skill scarcity constraining electric equipment maintenance capacity. |
| Tasmania Distribution Network Establishment | Specialized tunnelling and dam construction equipment demand from hydropower storage projects remains underserved. |
Methodological Framework
Operator-level perspectives from fleet managers at Pilbara iron ore operations, procurement leads at Queensland civil contractors, aftermarket service heads at integrated dealer networks, and WorkSafe licensing administrators anchored the qualitative base. Primary interview findings triangulated against Australian Bureau of Statistics import data, Department of Infrastructure Australian Design Rules certification registers, Standards Australia publication records, and mining company fleet disclosure statements. Bottom-up equipment unit forecasts reconciled with top-down state-level construction expenditure projections.
Sensitivity analysis tested volume and value outputs across alternative Australian Design Rules implementation timelines and steel price trajectory assumptions over the projection horizon. Segmentation modeling incorporated equipment type, powertrain technology, end-user category, and size class dimensions. CAGRs derived from historical replacement cycle analysis and projected fleet modernization intensity. Forecast inputs included mining production volume targets and state government infrastructure pipeline commitments.
Material uncertainties — regulatory acceleration of emissions thresholds, steel and hydraulic component cost volatility, skilled operator certification processing delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued federal-state regulatory harmonization and sustained mining capital expenditure commitment. Revision becomes warranted when Australian Design Rules compliance timelines compress beyond modeled boundaries or mining commodity price movements alter fleet replacement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market