
 Plastic Injection Molding Machines Market | 2026-2036
Plastic Injection Molding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Injection Molding Machines Market Analysis
All-electric injection molding technology is fragmenting traditional hydraulic dominance across precision manufacturing sectors. ENGEL leverages its Austrian engineering base to sustain premium positioning in medical and automotive applications. Haitian International Holdings Limited anchors volume leadership through manufacturing scale and cost-optimized electric platforms for Asian markets. Arburg GmbH differentiates via modular system architecture that permits rapid reconfiguration between thermoplastic and liquid silicone processing.
Plastic injection molding machines are clamping and injection systems that melt thermoplastic or thermoset polymers, inject them under high pressure into precision-tooled cavities, and cool them into finished shapes with tolerances often within 0.05 millimeters. These systems serve as foundational production equipment for mass-manufactured components across consumer, medical, automotive, and industrial sectors. Electric machines now lead technology substitution as manufacturers pursue energy reductions of 50-70% versus hydraulic equivalents, while hybrid systems retain share in thick-walled and high-tonnage applications where servo-electric drives face torque limitations. Packaging and automotive end users concentrate demand for high-cavitation, fast-cycle systems, whereas medical device applications drive premium pricing for cleanroom-compatible electric platforms with full process traceability.
FDA device manufacturing regulations and EU MDR traceability requirements shape medical segment equipment specifications, while EPA energy efficiency guidelines and REACH material compliance standards constrain polymer selection and machine design across North American and European installations. China's GB standards and MIIT industrial efficiency mandates accelerate domestic electric machine adoption while setting technical barriers for imported equipment. Stakeholders must weigh regional regulatory divergence against platform standardization economics when configuring global machine portfolios.
Market Dynamics
Electric drive technology is fragmenting hydraulic machine dominance as energy efficiency mandates from the EU Green Deal and China's MIIT accelerate capital replacement cycles across automotive and packaging sectors.
Growth Catalysts
- EU Green Deal emissions targets:German, French, and Italian automotive manufacturers are expanding all-electric machine procurement to meet binding carbon reduction deadlines.
- Medical device traceability mandates:FDA device manufacturing regulations and EU MDR requirements are driving premium demand for cleanroom-compatible electric platforms with full process documentation.
- China's Yangtze River Delta cluster:Concentrated packaging and consumer goods production in this manufacturing hub sustains high-cavitation, fast-cycle system demand.
Market Restraints
- High-tonnage torque limitations:Servo-electric drives face technical constraints in thick-walled applications above 1,000 tons, preserving hydraulic share in heavy industrial segments.
- Copper and rare earth magnet volatility:Electric machine motor cores depend on neodymium and copper supply chains concentrated in China and the Democratic Republic of Congo.
- REACH material compliance:European chemical registration requirements constrain polymer selection and complicate machine design for multinationals operating across regulatory zones.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for domestic component fabrication create white space for mid-tonnage electric machine deployment.
- Bioplastic processing convergence:Bio-based polymer injection requires modified screw geometries and temperature control systems that incumbent vendors are slow to commercialize.
- Indonesia's packaging demand surge:Southeast Asian consumer goods expansion outpaces local machine supply, opening channels for used equipment refurbishment and service bundling.
Industry Challenges
- Servoelectric maintenance skill scarcity:Hydraulic technicians require retraining in encoder calibration and drive programming, stretching OEM service networks.
- Retrofit integration complexity:Legacy hydraulic cells with proprietary PLCs resist seamless electric drive conversion, forcing parallel system installation.
- ISO 13485 medical certification timelines:Cleanroom validation and process traceability documentation extend machine qualification periods for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Injection Molding Machines Market |
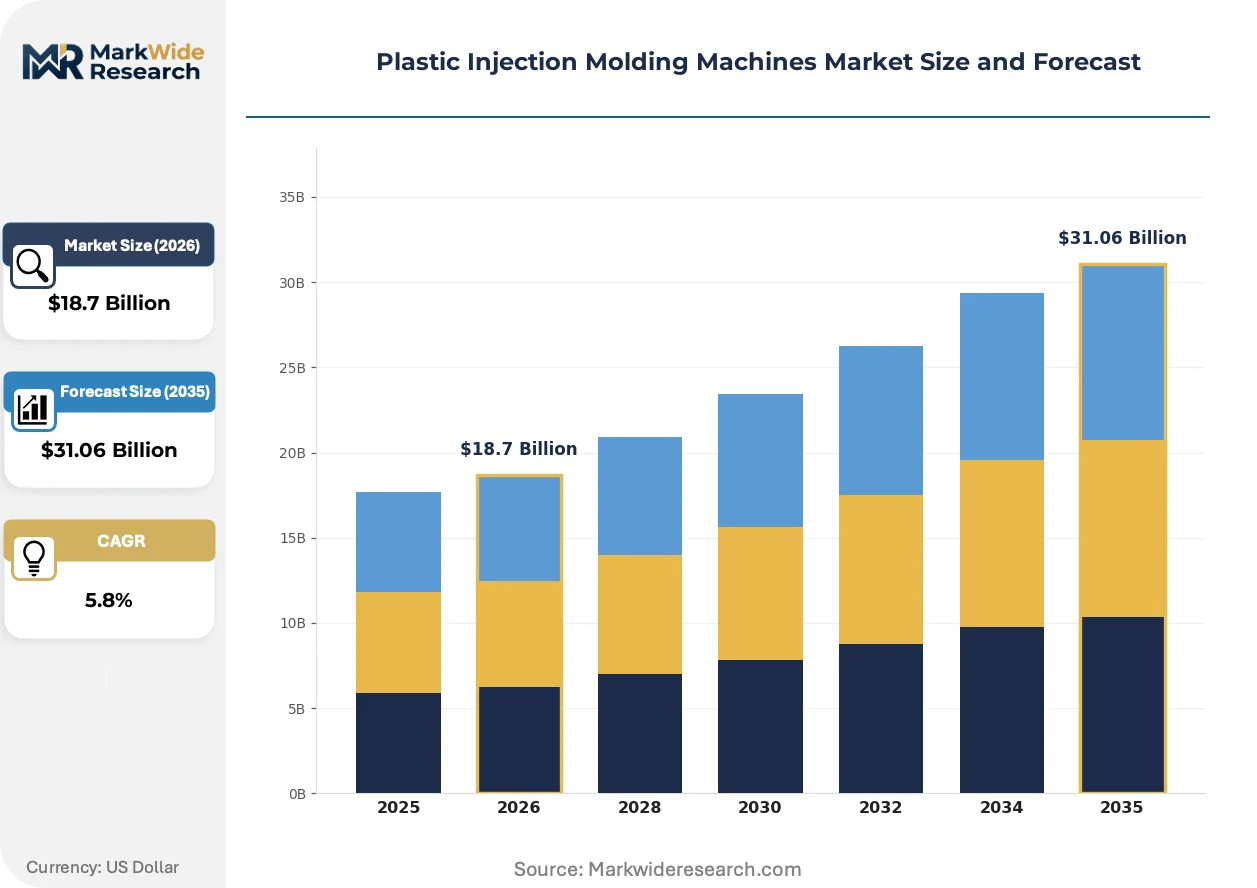
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
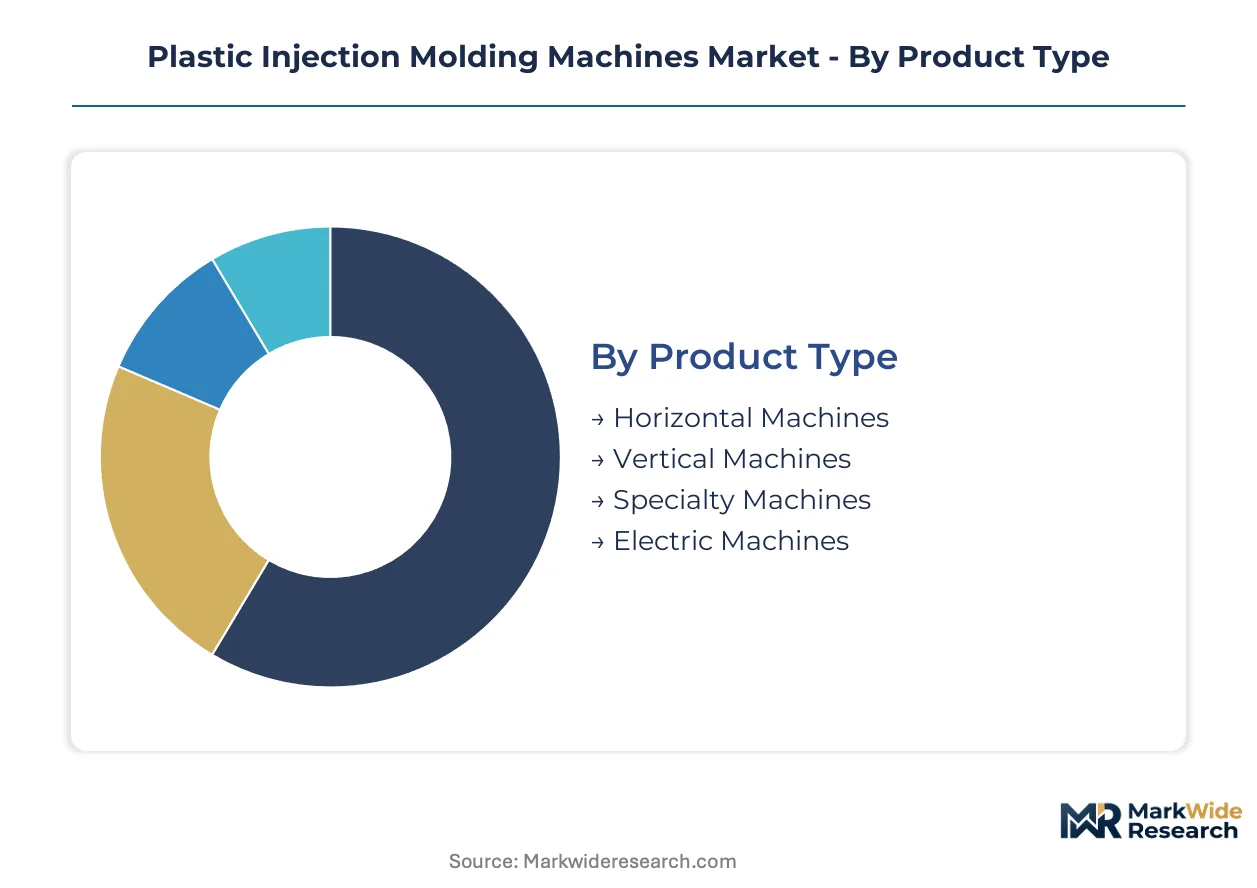
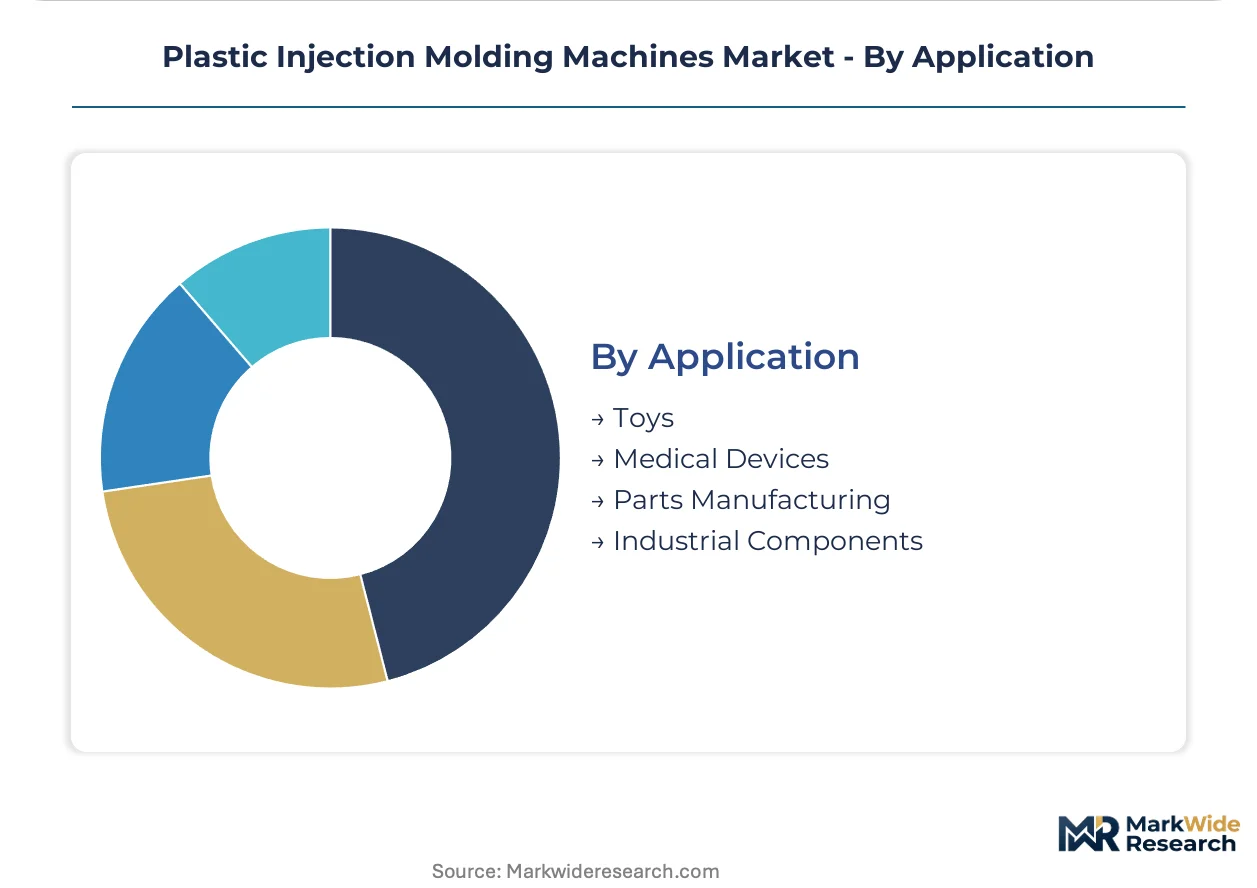
| Segmentation | Product Type: Horizontal Machines, Vertical Machines, Specialty Machines, Electric Machines End User: Automotive, Consumer Goods, Packaging, Electronics Technology: Hydraulic, Electric, Hybrid, Pneumatic Application: Toys, Medical Devices, Parts Manufacturing, Industrial Components |
| Companies Covered | Sumitomo Heavy Industries Limited, Arburg GmbH, ENGEL, Nissei Plastic Industrial Co., Ltd., Japan Steel Works Ltd., Haitian International Holdings Limited, Milacron, FANUC, Chen Hsong Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Injection Molding Machines Market Emerging Trajectories
Machine architecture is converging around modular platforms that permit rapid reconfiguration between polymer types, while digital thread integration and alternative material processing reshape competitive requirements.
Hybrid drive systems are hybridizing machine design by combining servo-electric precision for injection and clamping with hydraulic power for ejection and core pull functions. Automotive tier-one suppliers in Germany and Japan are adopting these platforms for interior trim and under-hood components. This architecture is hybridizing the traditional electric-versus-hydraulic purchase decision, compressing pure-play electric adoption timelines in the 500-800 ton range.
China's GB standards and MIIT industrial efficiency mandates are accelerating domestic electric machine adoption while erecting technical barriers for imported equipment. Domestic manufacturers must certify to revised energy consumption benchmarks that exceed most European and Japanese baseline specifications. Medical device and food packaging segments are responding by qualifying dual-certified platforms that satisfy both GB and FDA/EU MDR requirements.
Buyer preference is consolidating around total cost of ownership metrics rather than upfront capital expenditure, compressing traditional equipment financing models. Distributors in the United States and Western Europe are unbundling after-sales service from machine sales, offering predictive maintenance subscriptions as standalone contracts. This shift is most visible among automotive and medical device buyers in Michigan, Baden-Württemberg, and Osaka prefecture.
Plastic Injection Molding Machines Market Segmentation
Machine configuration and end-use specialization determine procurement patterns across automotive, medical, and packaging sectors. Technology substitution between hydraulic and electric platforms reshapes competitive positioning within each segment cluster.
Product Type:
Cost tier stratification separates volume manufacturers from precision specialists and premium electric platforms.
- Horizontal Machines:Clamping units arranged horizontally dominate high-volume automotive and packaging production. Tier-one suppliers in Germany and Japan specify these platforms for bumper fascia and interior trim with cycle times under 30 seconds.
- Electric Machines:Servo-motor driven systems eliminate hydraulic oil and reduce energy consumption. Medical device manufacturers in Baden-Württemberg and Osaka prefecture require these platforms for FDA and EU MDR compliance with full process traceability.
- Vertical Machines:Insert molding applications favor vertical clamping for overmolding metal components. Electronics manufacturers specify these for connector and sensor housings.
- Specialty Machines:Multi-component and liquid silicone configurations serve niche medical and automotive sealing applications. Arburg GmbH anchors this segment through modular rearchitecture capabilities.
Horizontal machines hold installed capacity. Electric machines are rotating up the share rankings.
End User:
Application intensity varies by sector energy mandates and precision requirements.
- Automotive:Interior trim, under-hood components, and electric vehicle battery housings drive demand for 500-1000 ton platforms. EU Green Deal emissions deadlines accelerate all-electric procurement at BMW, Volkswagen, and Toyota.
- Packaging:Thin-wall containers and caps require high-cavitation molds with sub-3-second cycle times. China's Yangtze River Delta cluster concentrates demand for Haitian International's fast-cycle systems.
- Consumer Goods:Appliance housings and furniture components utilize mid-tonnage hydraulic and hybrid machines. India's PLI scheme for manufacturing is expanding domestic sourcing requirements.
- Electronics:Precision connectors and miniaturized housings demand micro-molding capability with shot sizes below 1 gram. Cleanroom compatibility differentiates supplier selection.
Automotive maintains the largest installed base. Packaging is expanding most quickly on consumer goods demand in Southeast Asia.
Technology:
Maturity gradients separate legacy hydraulic dominance from electric substitution trajectories.
- Electric:Servo-driven precision controls injection velocity to 0.1 millimeter accuracy. Medical device and food packaging segments mandate these platforms for contamination prevention and energy efficiency compliance with China's MIIT benchmarks.
- Hybrid:Combines electric injection precision with hydraulic clamping force for thick-walled industrial components. Automotive tier-one suppliers adopt these for 500-800 ton applications where pure electric torque falls short.
- Hydraulic:Remains standard above 1,000 tons for automotive structural parts and industrial pallets. High maintenance costs and energy inefficiency accelerate replacement cycles in EU-regulated facilities.
- Pneumatic:Limited to low-pressure insert molding and specialty applications. Miniature component manufacturers specify these for cost-sensitive prototyping.
Hydraulic systems retain heavy-tonnage dominance. Electric platforms are gaining share fastest on regulatory pressure and total cost of ownership advantages.
Application:
Volume scale and certification requirements fragment demand across commodity and regulated segments.
- Parts Manufacturing:Automotive and industrial components constitute the highest volume segment. Standardized tooling and rapid changeover systems enable multi-shift production economics.
- Medical Devices:Syringes, inhalers, and surgical instruments require ISO 13485 certified cleanroom platforms. FDA device manufacturing regulations and EU MDR traceability mandates extend qualification timelines and sustain premium pricing.
- Industrial Components:Gears, housings, and functional assemblies utilize glass-filled polymers for structural performance. Material handling equipment and machinery builders drive demand in Germany and the United States.
- Toys:Safety-certified commodity production concentrates in China for export markets. EN 71 and ASTM F963 compliance requirements constrain supplier qualification.
Parts manufacturing commands the broadest installed base. Medical devices are climbing the fastest on regulatory premium capture and reshoring initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese machine builders export precision electric platforms to automotive manufacturers in the United States and EU member states, while Chinese fabricators supply cost-optimized systems across Southeast Asian packaging clusters.
United States
Automotive battery housing production and medical device reshoring drive electric machine procurement. EPA energy efficiency guidelines and OSHA workplace safety standards constrain hydraulic system installations. Michigan's automotive corridor and Minnesota's medical device cluster concentrate demand for 500-1000 ton all-electric platforms.
Germany
BMW, Volkswagen, and tier-one suppliers accelerate replacement of hydraulic cells ahead of EU Green Deal emissions deadlines. KBA vehicle certification requirements and REACH chemical compliance shape polymer selection. Baden-Württemberg's precision manufacturing belt anchors ENGEL and Arburg engineering operations.
China
Packaging and consumer goods producers in the Yangtze River Delta sustain high-cavitation system demand. MIIT industrial efficiency mandates and revised GB energy consumption standards accelerate domestic electric machine adoption. Haitian International and Chen Hsong anchor manufacturing capacity in Ningbo and Dongguan.
Japan
Automotive interior trim and electronics miniaturization sustain precision electric platform demand. METI energy conservation standards and JIS certification requirements filter equipment procurement. Osaka prefecture's machinery builders and Nagoya's automotive corridor concentrate technical buyer activity.
India
PLI scheme incentives for domestic component fabrication expand mid-tonnage electric machine deployment. BIS equipment safety standards and DGFT import regulations shape vendor qualification. Maharashtra's automotive belt and Gujarat's industrial corridors attract first-mover installation activity.
Plastic Injection Molding Machines Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct technology tiers. The market structures around consolidated premium engineering at the top, fragmented volume manufacturing in the middle band, and specialized niche configurations at the margins. Austrian and Japanese engineering specialists occupy premium positioning through precision platform development. Chinese scale manufacturers dominate volume economics through cost-optimized electric architectures. Strategic moves concentrate on modular system reconfiguration capabilities and predictive maintenance service bundling.
Within the premium engineering tier, ENGEL represents Austrian precision platform development for medical and automotive applications. Haitian International Holdings Limited anchors volume leadership through manufacturing scale and cost-optimized electric platforms. Arburg GmbH exemplifies modular system architecture that permits rapid reconfiguration between polymer processing modes.
| Leading Market Players |
|---|
| Sumitomo Heavy Industries Limited |
| Arburg GmbH |
| ENGEL |
| Nissei Plastic Industrial Co., Ltd. |
| Japan Steel Works Ltd. |
| Haitian International Holdings Limited |
| Milacron |
| FANUC |
| Chen Hsong Holdings Ltd. |
| Others |
Supply Flow & Price Mechanics
Neodymium and copper supply chains concentrated in China and the Democratic Republic of Congo anchor electric machine motor costs, compressing margin pools at mid-tier manufacturers while premium Austrian and Japanese engineering specialists capture value through cleanroom-certified platforms.
Pricing Analysis
Electric-to-hydraulic pricing gaps of 30-50% separate current-generation servo platforms from prior-generation hydraulic systems, with next-generation hybrid architectures compressing this spread in the 500-800 ton range. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in standard-tier electric machines is intensifying because Haitian International and Chen Hsong scale Ningbo production. Packaging buyers in China's Yangtze River Delta cluster exhibit highest price sensitivity, while medical device manufacturers in Baden-Württemberg prioritize FDA/EU MDR compliance over capital expenditure.
Supply Chain Analysis
Contract manufacturing concentration rests with Haitian International, Chen Hsong, and ENGEL production facilities in Ningbo, Dongguan, and Schwertberg. Geographic supply concentration centers on China, Austria, and Japan for complete machine fabrication, with Germany and Japan anchoring precision component sourcing. Raw material dependencies draw from neodymium rare earth magnets, copper motor windings, and specialty steel for clamping platens. Single-source vulnerability in Chinese rare earth processing creates supply chain risk. Distribution runs through OEM-direct sales for automotive tier-one suppliers and distributor networks for mid-market packaging producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and aftermarket service contracts are expanding faster than hardware sales, creating service-attach opportunities that reshape capital equipment economics across automotive and medical segments.
For Market Incumbents: Insulate premium positioning by deepening backward integration into servo drive manufacturing and expanding cleanroom certification capacity ahead of EU MDR enforcement. Anchor service revenue through predictive maintenance platforms that lock in multi-year contracts with automotive manufacturers facing EU Green Deal deadlines. Defend against Chinese scale manufacturers by modularizing platforms for rapid reconfiguration between polymer types. For New Entrants and Emerging Players: Pursue India's PLI scheme manufacturing incentives as the most penetrable geography, targeting mid-tonnage electric machine deployment in Maharashtra's automotive belt. Exploit bioplastic processing convergence by commercializing modified screw geometries and temperature control systems that incumbent vendors have delayed. Enter through service-bundled refurbishment models for Indonesia's packaging demand surge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision engineering specialists holding ISO 13485 medical certifications and established cleanroom validation protocols. Long-term viability centers on platforms capable of dual GB/FDA certification for China's domestic electric machine mandates. Watch for inflection in copper and rare earth magnet price volatility as signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | ENGEL and Arburg are unbundling service contracts to capture recurring revenue from Michigan automotive buyers. |
| Dual Certification Investment | Medical device platforms qualifying for both GB standards and FDA requirements access China's domestic procurement. |
| Backward Integration into Servo Drives | Japanese manufacturers are reducing Chinese rare earth dependency through in-house magnet processing partnerships. |
| Bioplastic Processing Module Development | Modified screw geometries for bio-based polymers create differentiation in European packaging segments facing REACH compliance. |
| Refurbishment and Service Bundling | Used equipment channels in Indonesia and Vietnam capture demand outpacing local machine supply. |
Methodological Framework
The analysis maps electric, hybrid, hydraulic, and pneumatic machine configurations, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with automotive tier-one supplier sourcing executives and medical device manufacturing engineers combined with secondary validation from MIIT efficiency filings, EU ETS carbon border documentation, customs trade data, and SEC equipment manufacturer disclosures. Bottom-up installation base modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Assumption sets held fixed regulatory enforcement timelines and commodity price baselines while varying electric technology adoption curves and regional manufacturing incentive intensity across the projection horizon. Segmentation dimensions modeled include technology type, end-use sector, tonnage capacity tier, and regional regulatory cluster. CAGRs derived from historical replacement cycle analysis and forward-looking capital expenditure surveys. Industry-specific forecast inputs incorporated EU Green Deal emissions deadline phasing and China's MIIT industrial efficiency mandate compliance thresholds.
Sensitivities concentrate around neodymium supply disruption, EU MDR traceability requirement enforcement delays, and electric machine torque limitation breakthroughs in high-tonnage applications. Forecasts reflect documented assumptions on technology substitution trajectories and regional incentive persistence. Quarterly review of rare earth export quotas, EU carbon border adjustment mechanism expansion, and automotive OEM electric platform procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
India Lathe Machines Market