
 Hyaluronic Acid Personal Care Products Market | 2026-2036
Hyaluronic Acid Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hyaluronic Acid Personal Care Products Market Intelligence
Buyer concentration among dermatology clinic chains and medical spa networks is hardening as these channels capture a growing share of professional-grade hyaluronic acid skincare. L'Oréal S.A. leverages its integrated dermatological research pipeline to supply both consumer retail and clinic-exclusive lines. Shiseido Company, Limited anchors its position through advanced fermentation-derived hyaluronic acid technologies developed in its Japanese laboratories. Allergan Aesthetics specializes in bridging injectable and topical applications, sustaining premium positioning across both segments.
Hyaluronic acid personal care products comprise topical formulations utilizing high-molecular-weight and low-molecular-weight hyaluronic acid polymers to enhance epidermal hydration through humectant action and barrier support, typically manufactured via microbial fermentation or extraction from rooster combs for cosmetic-grade applications. Serums command the strongest margin pools due to concentrated active formulations and premium price positioning, while moisturizers occupy the largest volume share across mass and prestige channels. The anti-aging application segment leads value generation, though hydration-focused products targeting men are expanding fastest as gender-specific marketing breaks from unisex positioning.
The EU's REACH framework and ECHA microplastic restrictions are reshaping formulation standards for rinse-off hyaluronic acid cleansers and masks, forcing suppliers to validate biodegradability claims. The U.S. FDA maintains active oversight of hyaluronic acid marketed with drug-like claims, creating compliance thresholds that filter smaller entrants from professional channels. Japan's Ministry of Health, Labour and Welfare through the Pharmaceuticals and Medical Devices Agency enforces strict quasi-drug classifications for whitening and anti-aging products containing hyaluronic acid. Stakeholders must monitor evolving cross-border ingredient disclosure requirements and decide whether to pursue multi-regulatory certification or geographic specialization.
Market Dynamics
Professional channel consolidation is compressing margin pools as dermatology clinic chains and medical spa networks demand volume pricing for clinical-grade hyaluronic acid formulations. This buyer concentration is forcing suppliers to choose between premium positioning in retail or scale economics in institutional supply.
Growth Catalysts
- EU Green Deal microplastic restrictions:Mandates for biodegradable delivery systems in rinse-off cosmetics are accelerating R&D investment in fermentation-derived polymer alternatives.
- Medical spa network expansion:These facilities now represent the fastest-expanding professional buyer segment for clinical-grade topical applications.
- Fermentation biotechnology advances:Microbial production methods are displacing animal-derived extraction, improving batch consistency and supply security.
Market Restraints
- Rooster comb supply concentration:Animal-derived raw material sourcing remains geographically concentrated, exposing cost volatility to avian disease outbreaks and trade restrictions.
- REACH compliance burden:ECHA biodegradability validation requirements for rinse-off formulations impose testing costs that filter smaller formulators from EU market access.
- Cross-linked polymer substitution:Advanced peptide and ceramide complexes are capturing share in premium anti-aging segments where immediate surface effect matters more than deep hydration.
Strategic Opportunities
- Men's hydration segment:Gender-specific marketing is breaking from unisex positioning, creating white space for dedicated product lines targeting male skincare routines.
- South Korean export hub leverage:Seoul-based beauty conglomerates dominate both ingredient innovation and finished-product distribution, offering partnership pathways for foreign suppliers.
- Injectable-topical bridge protocols:Convergence of aesthetic medicine and home care is opening channel opportunities for brands spanning both professional and retail environments.
Industry Challenges
- Quasi-drug classification timelines:Japan's PMDA review processes for whitening and anti-aging claims extend product launch cycles by 18-24 months.
- Multi-regulatory certification complexity:Divergent FDA, REACH, and PMDA evidentiary standards force parallel track development or geographic specialization.
- Fermentation scale-up capex requirements:Commercial microbial production facilities demand substantial capital investment for GMP compliance and yield optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyaluronic Acid Personal Care Products Market |
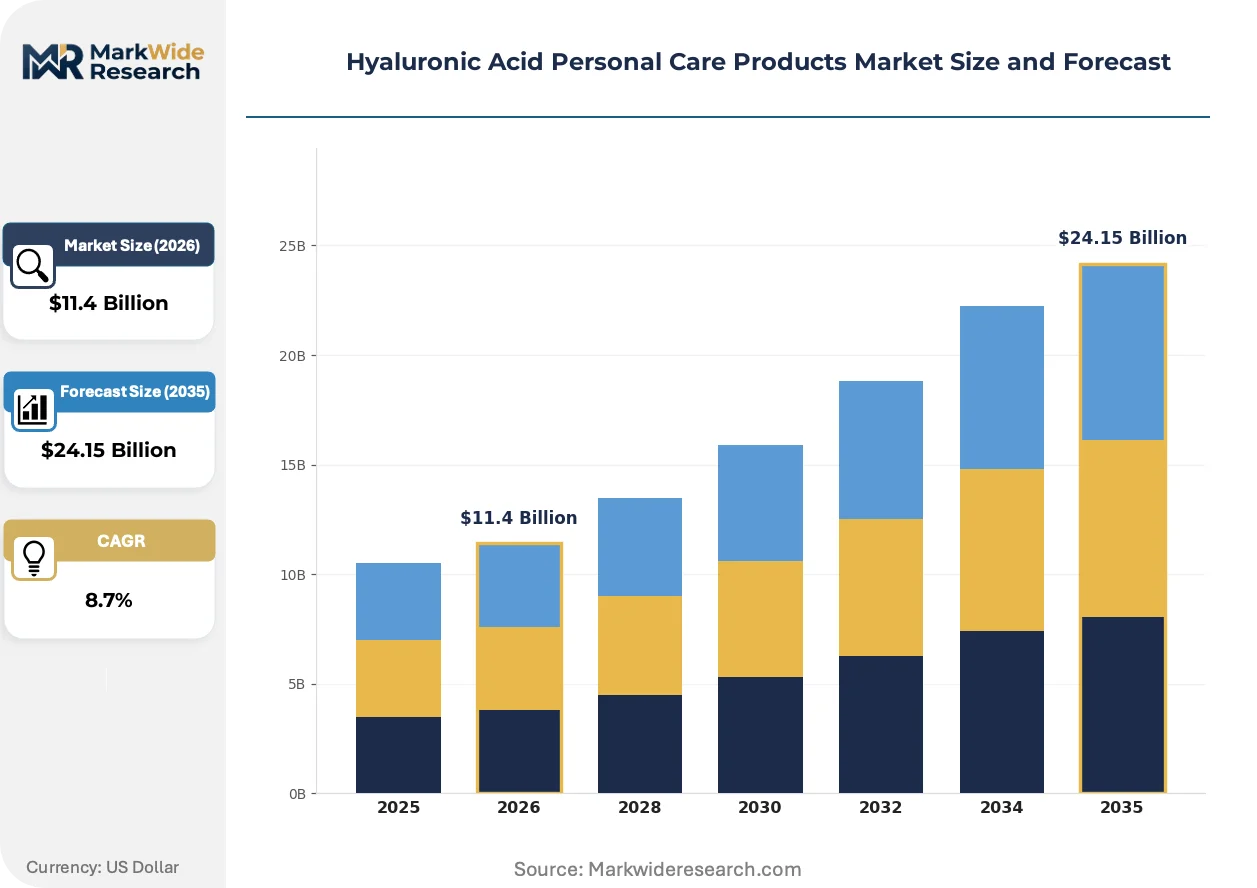
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Masks, Cleansers Application: Anti-Aging, Hydration, Skin Repair, Acne Treatment Target Audience: Women, Men, Teens, Seniors Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Shiseido Company, Limited, Allergan Aesthetics, L'Oréal S.A., LG Household & Health Care Ltd., SkinCeuticals, Procter & Gamble Company, Beiersdorf AG, Rohto Pharmaceutical, The Estée Lauder Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyaluronic Acid Personal Care Products Market Strategic Shifts & Innovations
Active ingredient delivery science is reshaping competitive differentiation as molecular weight engineering enables targeted epidermal penetration. Formulators now compete on polymer architecture rather than concentration claims alone.
Multi-molecular-weight complexing is electrifying serum formulation architecture. Low-molecular-weight fragments penetrate stratum corneum while high-weight polymers form surface films. Prestige brands and clinic-exclusive lines are adopting these complexes fastest. This technology is electrifying margin structures by justifying tiered pricing across penetration depth claims.
REACH microplastic restrictions are forcing cleanser and mask reformulation across European supply chains. ECHA biodegradability mandates now require validated degradation data for polymer-based delivery vehicles. Rinse-off hyaluronic acid products face the steepest compliance burden, pushing investment toward enzymatically cleavable polymer backbones.
Clinic-direct procurement is consolidating professional-grade supply relationships. Dermatology chains are bypassing traditional distribution to negotiate direct manufacturer contracts with volume guarantees and exclusive SKU development. South Korea and Japan exhibit the most advanced buyer concentration, with hospital-affiliated aesthetic centers driving standardization requirements.
Hyaluronic Acid Personal Care Products Market Segmentation
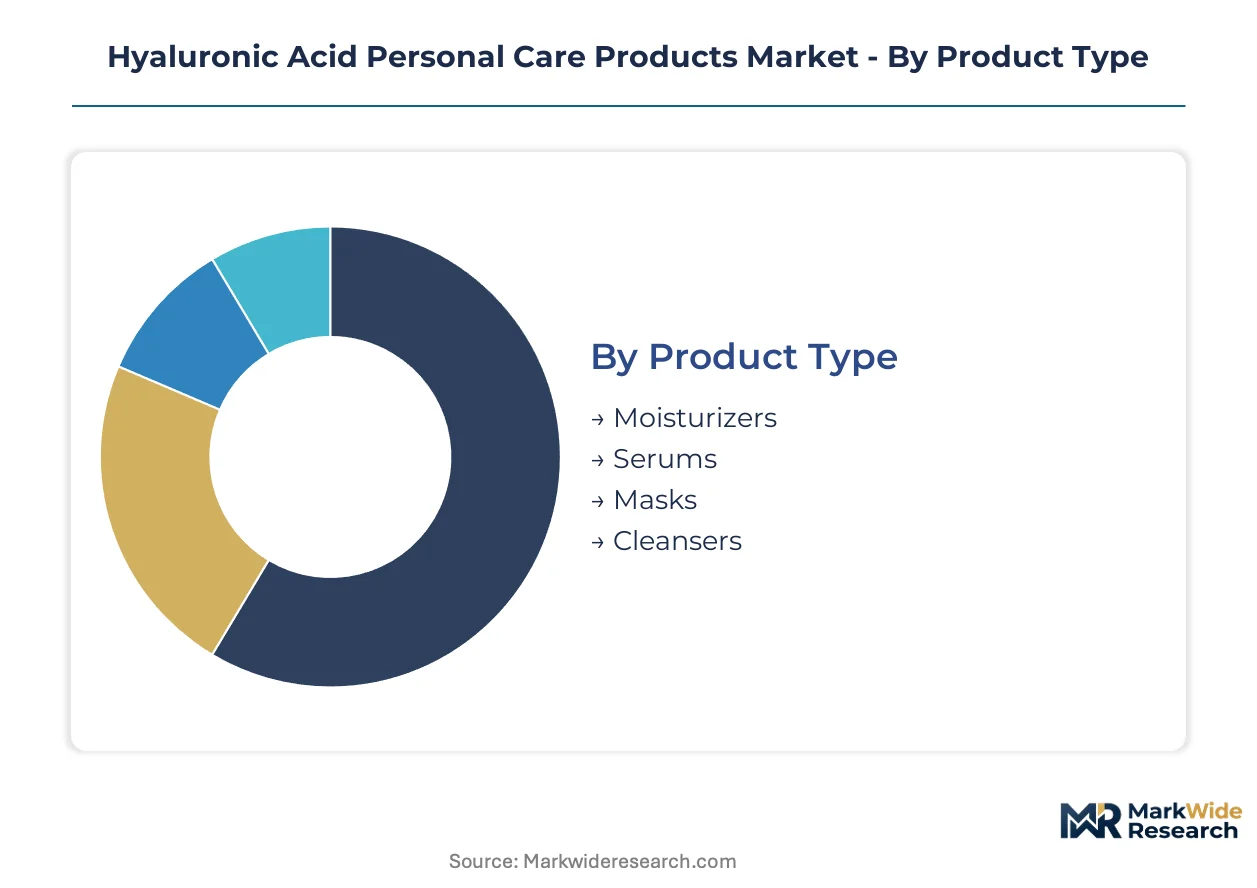
Hyaluronic acid personal care markets fragment across four critical dimensions. Each segmentation layer carries distinct regulatory burdens, margin profiles, and channel access requirements that determine competitive positioning.
Product Type:
Certification intensity varies sharply across product formats, with rinse-off formulations facing ECHA biodegradability mandates under REACH while leave-on products navigate quasi-drug pathways in Japan.
- Moisturizers:These emulsion-based formulations combine high-molecular-weight hyaluronic acid with occlusive agents to form surface hydration films. Demand concentrates in mass retail channels across Germany and France, where pharmacy distribution requires CE marking compliance and ingredient disclosure validation. Volume leadership here reflects the category's accessibility across price tiers.
- Serums:Concentrated aqueous solutions featuring multi-molecular-weight hyaluronic acid complexes for targeted penetration depth claims. Professional channel procurement in Seoul and Tokyo drives premium positioning, with clinic-exclusive lines demanding GMP certification and stability documentation. These formulations command the steepest price premiums due to active ingredient density.
- Masks:Sheet and rinse-off formats subject to EU microplastic restrictions requiring validated polymer backbone biodegradability.
- Cleansers:Rinse-off surfactant systems with hyaluronic acid conditioning agents facing the heaviest REACH compliance burden for polymer discharge validation.
Moisturizers sit at the top of the volume ranking, with serums climbing the fastest as professional channel consolidation accelerates.
Application:
Functional claim categories determine regulatory pathway complexity, with anti-aging and whitening assertions triggering extended review timelines in Japan's PMDA quasi-drug framework.
- Anti-Aging:Formulations targeting wrinkle reduction and elasticity improvement through collagen synthesis support and barrier function enhancement. Clinic networks in South Korea and medical spa chains in the United States concentrate procurement for professional-grade SKUs, driven by consumer willingness to pay for visible outcome documentation.
- Hydration:Core humectant applications emphasizing transepidermal water loss reduction through polymer film formation. Mass market penetration across online retail platforms in China and India expands volume, though price compression intensifies as commodity-grade suppliers proliferate.
- Skin Repair:Post-procedure and barrier-compromised skin applications requiring dermatological validation and sensitivity testing documentation.
- Acne Treatment:Combination formulations with salicylic acid or niacinamide facing drug-cosmetic boundary scrutiny from FDA.
Hydration captures the largest absolute volume, while skin repair gains share fastest as post-aesthetic procedure home care protocols standardize.
Target Audience:
Demographic specialization is reshaping product development cycles, with gender-specific formulation and marketing breaking from historical unisex positioning.
- Women:Historically dominant segment with established purchase patterns across prestige and masstige channels. Mature demand in Japan and South Korea sustains innovation investment in fermentation-derived molecular weight engineering.
- Men:Emerging segment with fastest trajectory as dedicated skincare routines normalize among male consumers in urban China and metropolitan United States markets. Formulation preferences favor lightweight textures and simplified regimens.
- Teens:Entry-level positioning through affordable serum formats and social media-driven discovery channels.
- Seniors:Age-specific hydration and repair claims targeting barrier function degradation with clinical validation requirements.
Women retain volume leadership, with men expanding most quickly as gendered marketing investments accelerate.
Distribution Channel:
Channel selection determines margin realization and regulatory exposure, with direct professional procurement bypassing traditional wholesale markups while imposing documentation burdens.
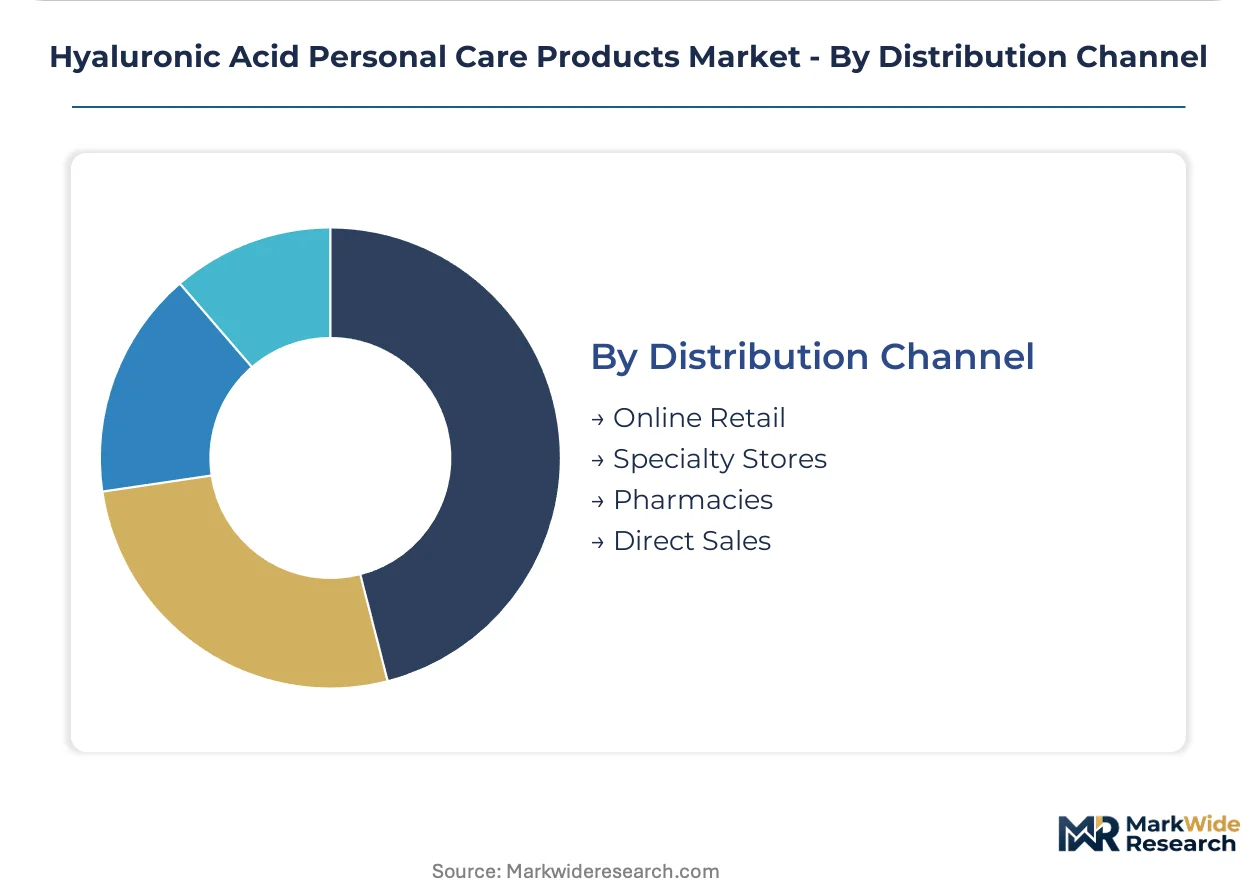
- Online Retail:E-commerce platforms and direct-to-consumer brands capturing share through algorithmic personalization and subscription mechanics. Cross-border fulfillment complexity demands multi-jurisdiction labeling compliance for sellers targeting European and Asian markets simultaneously.
- Specialty Stores:Prestige beauty retailers and clinic-adjacent retail spaces offering assisted selling and professional recommendation validation. High service intensity supports premium price realization.
- Pharmacies:Regulated channel requiring pharmacist involvement in France and Germany, with quasi-drug classification expanding accessible claims.
- Direct Sales:Network marketing and brand-owned retail with controlled education and demonstration protocols.
Online retail holds volume primacy, with specialty stores advancing fastest as clinic network expansion drives professional-adjacent purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's fermentation biotechnology workforce anchors the industry's innovation core, with South Korean conglomerates driving molecular weight engineering advances. Clinic networks in Tokyo and dermatology chains in Frankfurt concentrate procurement for professional-grade formulations. Regulatory divergence across FDA, REACH, and PMDA frameworks fragments compliance pathways.
South Korea
Seoul-based beauty conglomerates dominate both ingredient innovation and finished-product exports through advanced fermentation-derived hyaluronic acid technologies. MFDS quasi-drug classifications for whitening and anti-aging claims enforce rigorous stability documentation requirements. The Seoul Capital Area concentrates R&D facilities where multi-molecular-weight complexing drives serum formulation differentiation.
Japan
PMDA review processes for quasi-drug whitening and anti-aging claims extend product launch cycles by 18-24 months, filtering smaller entrants. METI supports biotechnology scale-up through targeted industrial policy. The Kansai region around Osaka hosts specialized fermentation facilities supplying clinical-grade polymers to dermatology clinic chains.
United States
Medical spa network expansion drives fastest-growing professional channel demand for clinical-grade topical applications. FDA maintains active oversight of hyaluronic acid marketed with drug-like claims, creating compliance thresholds. Greater Boston anchors dermatological research pipelines supplying both consumer retail and clinic-exclusive product lines.
Germany
Pharmacy distribution channels require CE marking compliance and ingredient disclosure validation for mass-market moisturizers. ECHA biodegradability mandates under REACH impose testing costs that filter smaller formulators from rinse-off product segments. North Rhine-Westphalia concentrates formulation laboratories serving EU Green Deal reformulation requirements.
France
ANSM enforces strict pharmacist involvement requirements in prestige retail channels, supporting premium price realization. The EU Green Deal's microplastic restrictions accelerate investment in enzymatically cleavable polymer backbones for cleanser reformulation. Île-de-France hosts headquarters operations for integrated beauty conglomerates managing multi-regulatory certification portfolios.
Hyaluronic Acid Personal Care Products Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures intensify as dermatology clinic chains demand volume pricing for clinical-grade formulations. Three archetypes dominate: integrated beauty conglomerates with dermatological research pipelines, fermentation biotechnology specialists with proprietary polymer engineering capabilities, and professional channel brands bridging injectable and topical applications. Competitive moves concentrate on direct procurement relationships with medical spa networks and multi-regulatory certification investments.
Among Asia-Pacific-based innovators, Shiseido Company, Limited and LG Household & Health Care Ltd. exemplify the fermentation-technology archetype, while L'Oréal S.A. represents diversified conglomerate positioning across consumer and professional channels. Allergan Aesthetics occupies a distinctive position spanning aesthetic medicine and home care convergence. These companies anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Shiseido Company, Limited |
| Allergan Aesthetics |
| L'Oréal S.A. |
| LG Household & Health Care Ltd. |
| SkinCeuticals |
| Procter & Gamble Company |
| Beiersdorf AG |
| Rohto Pharmaceutical |
| The Estée Lauder Companies |
| Others |
Cost & Logistics Intelligence
Clinic network procurement consolidation in South Korea and the United States is forcing suppliers to absorb volume pricing concessions while maintaining GMP certification standards, compressing margin pools and accelerating backward integration into fermentation biotechnology.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for clinical-grade hyaluronic acid polymers. Three-tier pricing structure across premium clinic-exclusive, standard professional, and economy mass-retail levels stratifies by molecular weight complexity and certification grade. Pricing pressure stems from dermatology chain volume negotiations, with cost compression running through standard-tier formulations. Mass-market consumers exhibit highest price sensitivity; clinic networks accept premium positioning for validated stability documentation.
Supply Chain Analysis
Direct-to-clinic channels handle hyperscale procurement from dermatology network headquarters in Seoul, Tokyo, and Frankfurt. Fermentation-derived production concentrates in South Korea, Japan, and Germany, drawing from glucose feedstocks, specialized bioreactor equipment, and purified water systems. Single-source vulnerability in rooster comb extraction for legacy grades exposes cost volatility to avian disease outbreaks. Distribution runs through manufacturer-direct contracts with volume guarantees, bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyaluronic acid personal care operates as a late-cycle quality story where clinic-grade specifications now command decisive procurement preference over commodity-grade alternatives.
For Market Incumbents: Deploy multi-regulatory certification investments to defend clinic-direct relationships against emerging fermentation specialists. Deepen backward integration into microbial production capacity in the Seoul Capital Area to secure supply against animal-derived volatility. Prioritize PMDA quasi-drug pathway navigation to extend exclusivity periods in Japan's premium channel. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms targeting male hydration routines in metropolitan China offer the most penetrable white space. Bypass saturated prestige retail through algorithmic personalization engines. Anchor initial positioning on lightweight texture formats with simplified regimens distinct from legacy unisex positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation biotechnology specialists possessing proprietary multi-molecular-weight engineering capabilities. Five-to-ten year viability hinges on biodegradability validation infrastructure for EU Green Deal compliance. Monitor ECHA enforcement intensity as the critical inflection signal for rinse-off formulation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Transition | REACH microplastic mandates force enzymatically cleavable backbone R&D investment in North Rhine-Westphalia laboratories. |
| Clinic-Direct Procurement Consolidation | Dermatology chain headquarters in Seoul and Frankfurt negotiate exclusive SKU development with volume guarantee structures. |
| Men's Hydration Line Extension | Gender-specific marketing breaks from unisex positioning in urban China and metropolitan United States discovery channels. |
| Fermentation Scale-Up Partnership | Joint ventures with Kansai-region bioreactor operators secure GMP-compliant clinical-grade polymer supply security. |
| Multi-Regulatory Certification Portfolio | Parallel FDA, REACH, and PMDA track development filters smaller competitors from professional channel access. |
Research Approach
Multiple input streams — primary interviews with dermatology procurement directors, fermentation R&D leads, and regulatory affairs specialists; secondary validation through MFDS quasi-drug filings, ECHA biodegradability registrations, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct market estimates.
Historical volume trajectories were cross-referenced against expert panel assessments across the projection horizon. Segmentation dimensions modeled include product format, molecular weight tier, application claim, distribution channel, and regional regulatory cluster. CAGRs derive from weighted average growth assumptions incorporating clinic network expansion rates, fermentation yield improvements, and substitution elasticity from peptide complexes.
The model assumes a particular technology adoption path; alternative pathways for enzymatic polymer engineering would alter the outlook. Forecasts reflect base-case assumptions regarding REACH enforcement timelines and PMDA review process durations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Preoperative Skin Preparation Market
Skincare
Facial Mask Market
Skincare
Tinted Sunscreen Market
Skincare
Facial Cleansing Balm Market
Skincare
Algae Skincare Products Market
Skincare
After Sun Care Products Market
Skincare
Biological Skin Substitutes Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
Self-Tanning Care Market
Skincare
Skin Toner Market
Skincare
Facial Mist Market
Skincare
Personalized Skin Care Products Market
Skincare
Global Scar Removal Treatment Market
Skincare
Retinol Skincare Product Market
Skincare
Skincare Serums Market
Skincare
Anti-Acne Dermal Patch Market