
 Ultrasound Skin Cleaners Market | 2026-2036
Ultrasound Skin Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Skin Cleaners Market Analytics
CE marking under the EU Medical Device Regulation is unwinding the competitive field, forcing smaller manufacturers to absorb notified body audit costs that larger rivals already amortize. Foreo leverages its vertically integrated manufacturing in Sweden to sustain margin structures that import-dependent competitors cannot match. Ya-Man anchors its position in Japan through JIS-standard compliance and domestic PMDA registration depth that foreign entrants struggle to replicate.
Ultrasound skin cleaners employ piezoelectric transducers generating frequencies between 20 kHz and 40 kHz to cavitate cleansing solutions against the epidermis, dislodging sebum and particulate matter without mechanical abrasion. Portable devices occupy the highest volume tier as home users prioritize convenience, yet professional equipment captures disproportionate margin pools due to clinic-grade output calibration and durable transducer arrays. AI-powered models represent the fastest-expanding segment, with embedded skin-type sensors adjusting frequency modulation in real time during deep cleansing protocols.
FDA 510(k) clearance requirements for ultrasonic aesthetic devices shape product development roadmaps, while REACH compliance in Europe constrains piezoelectric ceramic formulations containing lead zirconate titanate. China's NMPA now mandates domestic clinical trials for imported Class II aesthetic equipment, extending market access timelines for brands without local regulatory partnerships. Stakeholders must weigh certification investment sequencing against regional revenue timing, as regulatory divergence between the US, EU, and China fragments go-to-market economics.
Market Dynamics
Ultrasonic cavitation technology is decomposing manual extraction protocols across aesthetic dermatology, forcing equipment manufacturers to reconfigure transducer arrays around real-time skin-type sensing rather than fixed-frequency output.
Growth Catalysts
- AI-embedded frequency modulation:Deep-learning algorithms embedded in handheld units now adjust cavitation intensity based on epidermal impedance readings, expanding addressable user profiles beyond trained clinicians.
- FDA 510(k) pathway maturation:Accumulated predicate device databases for Class II ultrasonic aesthetic equipment are compressing review timelines for subsequent filers, accelerating commercialization cadence.
- South Korea clinic chain standardization:Seoul-based dermatology networks are mandating multi-modal platforms that bundle ultrasonic cleansing with thermal pulse delivery, creating volume anchors for OEMs.
Market Restraints
- Lead zirconate titanate supply concentration:REACH compliance constraints on piezoelectric ceramic formulations have thinned qualified European suppliers, concentrating input sourcing among three East Asian refiners.
- Clinical documentation burden:FDA clearance requirements for novel frequency ranges demand biocompatibility studies that extend development cycles by 18-24 months for non-predicate innovations.
- Manual extraction substitution:Low-cost esthetician-performed comedone extraction retains preference in price-sensitive Latin American and Southeast Asian markets, capping ultrasonic penetration.
Strategic Opportunities
- China NMPA domestic trial partnerships:Brands that establish joint-venture clinical research organizations can bypass the 24-month imported device approval queue and access Class II aesthetic equipment reimbursement pathways.
- Subscription hardware models:Device-as-a-service platforms targeting med-spa chains bundle consumable gel cartridges with quarterly transducer calibration, converting capex to recurring revenue.
- Atopic dermatitis adjacency:Ultrasonic cleansing protocols for barrier-compromised skin represent an unaddressed indication segment requiring only protocol labeling expansion, not hardware redesign.
Industry Challenges
- Biomedical engineer scarcity:Firms struggle to recruit transducer physicists capable of integrating MEMS pressure sensors with piezoelectric drive circuits, slowing AI-enabled product roadmaps.
- Notified body audit queuing:EU MDR CE marking backlogs at designated conformity assessment organizations are extending time-to-market for European launches by 8-14 months relative to pre-2021 timelines.
- Legacy CRM integration:Clinic-grade equipment vendors face customer resistance when ultrasonic platforms cannot synchronize with established practice management software ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Skin Cleaners Market |
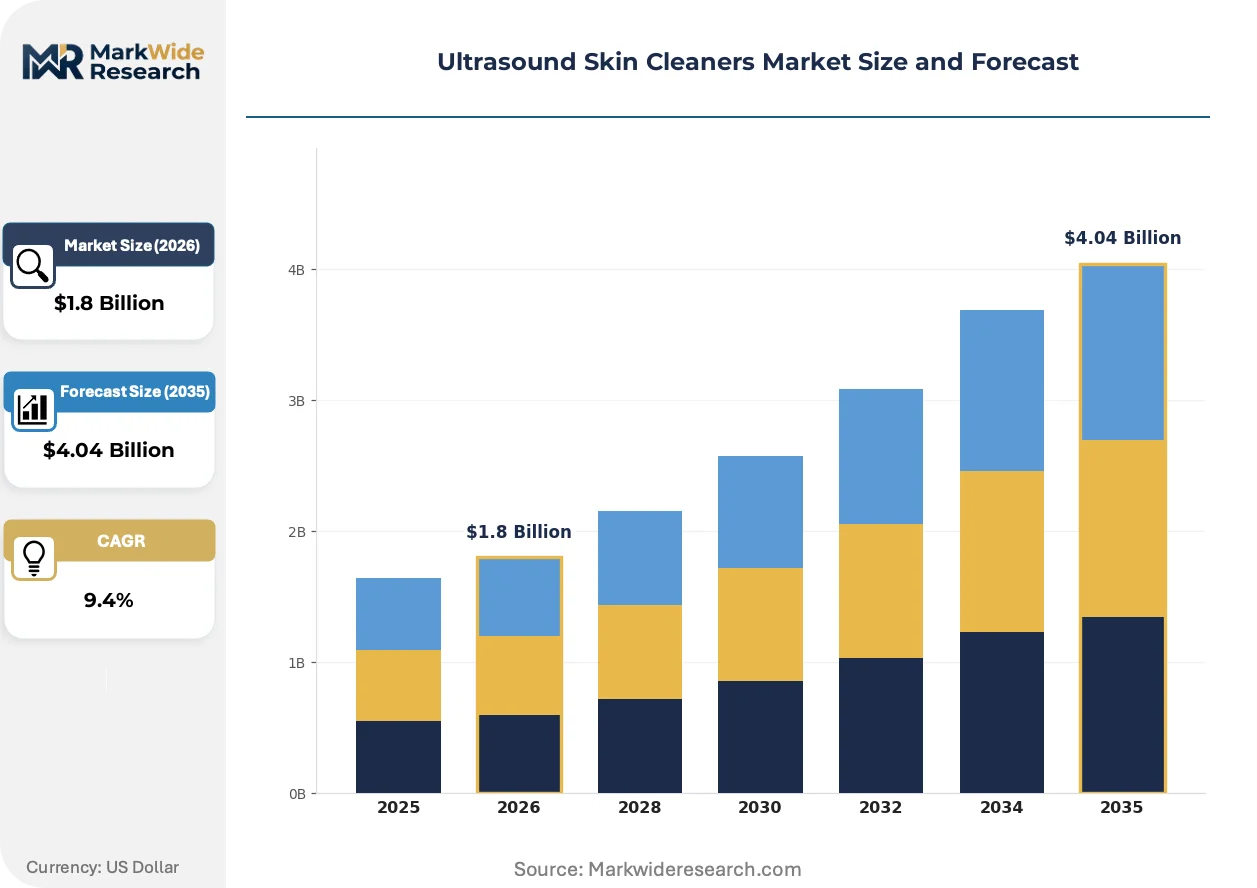
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Professional Equipment, AI-Powered Models, Manual Systems End User: Beauty Salons, Dermatology Clinics, Spa Centers, Home Users Technology: Ultrasonic Waves, High-Frequency Vibrations, Thermal Pulses, Microdermabrasion Application: Deep Cleansing, Exfoliation, Anti-Aging, Acne Treatment |
| Companies Covered | Bio-Therapeutic, Dermaflash, Skin Gym, Project E Beauty, Foreo, Ya-Man, Trophy Skin, Zemits, Lifetrons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Skin Cleaners Market Evolving Landscape
Real-time epidermal sensing capabilities are compressing the performance gap between professional and home-use ultrasonic devices, while regulatory divergence across major markets is fragmenting product architecture roadmaps.
Multi-frequency transducer arrays spanning 20 kHz to 40 kHz are decomposing the traditional single-frequency hardware paradigm. Premium dermatology chains in Germany and Japan are adopting these platforms to address mixed skin-type patient panels within single treatment sessions. The technology is decomposing aftermarket service revenue models, as self-calibrating transducers reduce scheduled maintenance dependencies.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to maintain post-market surveillance registries that track adverse event rates across 500+ patient exposures. This obligation has redirected R&D budgets toward prospective study design rather than iterative hardware refinement. Professional equipment segments bear disproportionate compliance costs, prompting some OEMs to bifurcate EU and non-EU product lines.
Home users now prioritize sensor-guided treatment protocols over raw power specifications, reversing the historical emphasis on wattage marketing. Direct-to-consumer channels are displacing aesthetician recommendations as the primary purchase influence among millennial and Gen Z demographics. South Korea and China exhibit the most pronounced channel migration, where live-stream commerce platforms bundle ultrasonic devices with personalized skincare regimens.
Ultrasound Skin Cleaners Market Segmentation
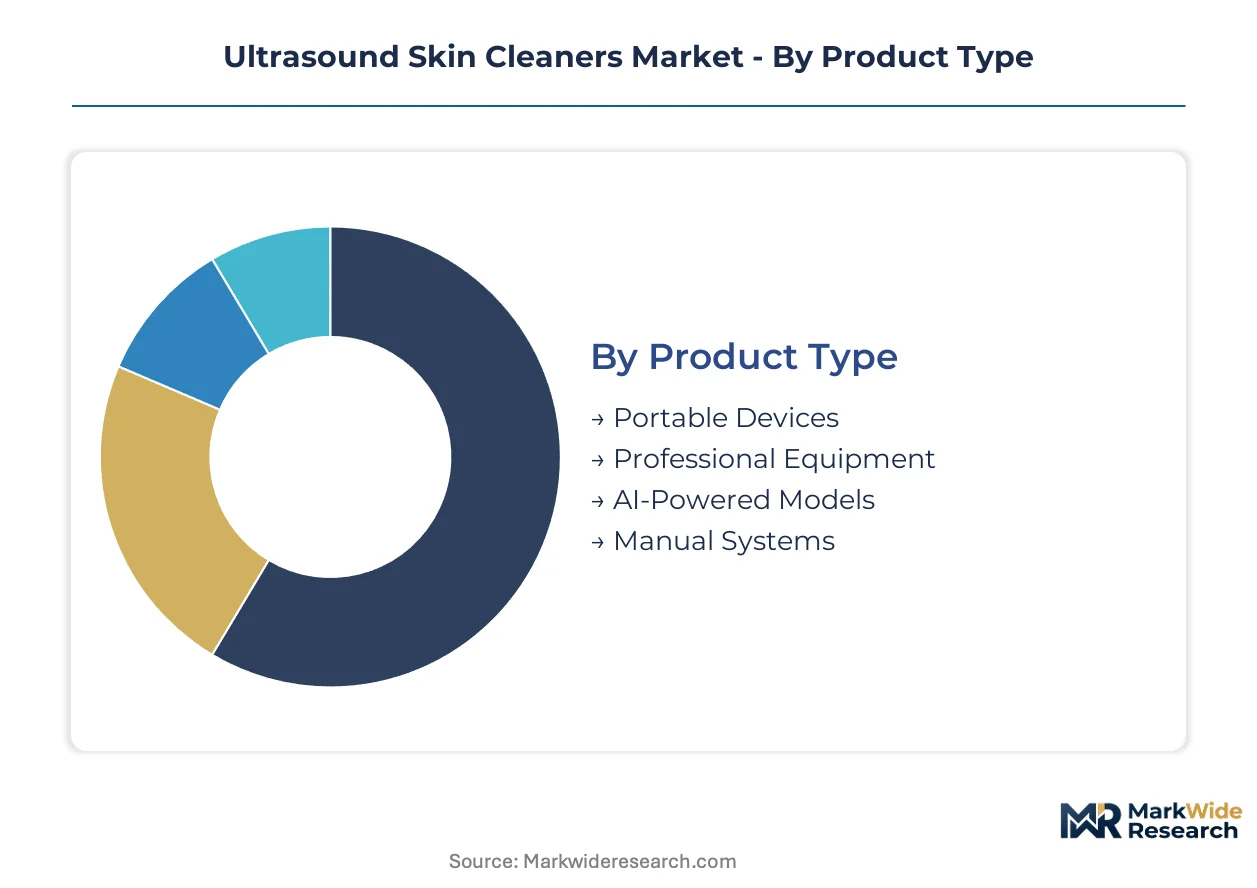
Ultrasound skin cleaners fragment across four intersecting dimensions that determine pricing power and regulatory burden. Product architecture choices lock manufacturers into specific channel strategies, while end-user concentration in Seoul clinic chains and Chinese live-stream commerce reshapes volume allocation.
Product Type:
Manual extraction kits and low-frequency alternatives exert substitution pressure most acutely on entry-level ultrasonic hardware, forcing mid-tier OEMs to defend positioning through feature bundling.
- Portable Devices:Handheld units operating between 20 kHz and 40 kHz dominate unit shipments as Chinese direct-to-consumer platforms absorb inventory. South Korean millennial buyers prioritize sensor-guided protocols over wattage specifications, compressing brand loyalty cycles.
- Professional Equipment:Clinic-grade platforms with calibrated transducer arrays and durable ceramic stacks command service-contract revenue streams. German dermatology chains specify multi-frequency arrays spanning mixed patient panels within single sessions.
- AI-Powered Models:Embedded impedance sensors adjust cavitation intensity in real time, expanding addressable profiles beyond trained clinicians.
- Manual Systems:Comedone extractors and pore vacuums retain preference in Latin American esthetician channels, capping ultrasonic penetration in price-sensitive tiers.
Portable Devices retain volume leadership; AI-Powered Models hold the steepest expansion curve.
End User:
Procurement authority concentrates with clinic procurement officers and platform algorithmic recommendations, bifurcating demand between institutional specification and impulse-driven home acquisition.
- Dermatology Clinics:Institutional buyers mandate FDA 510(k) clearance and EU MDR CE marking as baseline qualification. Seoul-based chains standardize on multi-modal platforms bundling ultrasonic cleansing with thermal pulse delivery.
- Home Users:Sensor-guided treatment protocols displace aesthetician recommendations as primary purchase influence. Chinese live-stream commerce bundles devices with personalized skincare regimens, accelerating channel migration.
- Beauty Salons:Mid-tier service providers balance equipment cost against per-treatment revenue capture, favoring lease arrangements over capital purchase.
- Spa Centers:Wellness-focused operators integrate ultrasonic cleansing into broader facial protocol menus, prioritizing guest experience consistency over clinical-grade output calibration.
Dermatology Clinics anchor premium pricing; Home Users drive volume scaling fastest.
Technology:
Regulatory divergence across FDA, EU MDR, and NMPA pathways fragments architecture roadmaps, as each jurisdiction imposes distinct biocompatibility and electromagnetic compatibility testing regimes.
- Ultrasonic Waves:Piezoelectric transducers generating cavitation effects against the epidermis without mechanical abrasion constitute the core modality. REACH compliance constraints on lead zirconate titanate formulations have thinned qualified European suppliers.
- High-Frequency Vibrations:Sonic oscillation alternatives operating above audible range compete on lower unit economics but lack cavitation efficacy for sebum dislodgement.
- Thermal Pulses:Adjunct heating elements enhance pore dilation and serum penetration, increasingly bundled as standard in South Korean multi-modal platforms.
- Microdermabrasion:Mechanical exfoliation alternatives retain installed base in legacy clinic equipment, though ultrasonic displacement accelerates in new procurement cycles.
Ultrasonic Waves dominate installed value; Thermal Pulses climb fastest through bundling penetration.
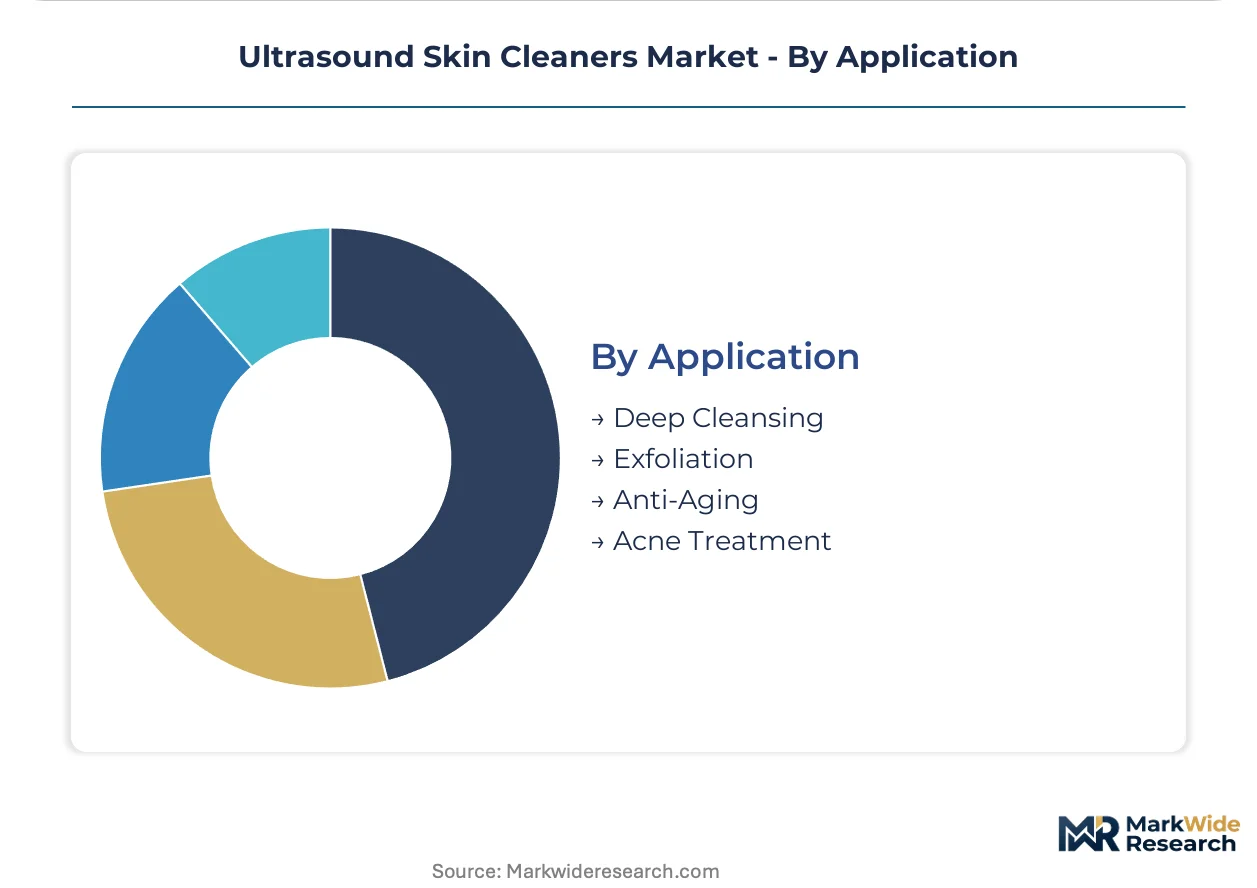
Application:
Clinical documentation requirements vary sharply by indication, with acne treatment protocols facing stricter adverse event tracking than cosmetic cleansing claims.
- Deep Cleansing:Foundational sebum and particulate removal protocols drive baseline device utilization across all channels. FDA 510(k) predicate databases for cleansing indications compress review timelines for subsequent filers.
- Anti-Aging:Collagen stimulation claims require more extensive clinical substantiation, elevating compliance investment for manufacturers targeting this positioning.
- Acne Treatment:Medical device classification in key jurisdictions triggers prescription-channel restrictions and physician oversight requirements.
- Exfoliation:Surface cell turnover protocols compete directly with chemical peel alternatives, placing pricing pressure on hardware-only value propositions.
Deep Cleansing captures volume leadership; Anti-Aging exhibits the steepest expansion trajectory as demographic aging concentrates demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatology clinic chains concentrate procurement authority in Seoul, while direct-to-consumer platforms in China absorb portable device inventory at unmatched velocity. Home users in Germany and the United States prioritize sensor-guided protocols over wattage specifications, fragmenting demand patterns across institutional and impulse-driven channels.
United States
FDA 510(k) clearance timelines shape product launch cadences for Class II ultrasonic aesthetic devices. The agency's predicate device database for cleansing indications compresses review periods for subsequent filers. Greater Boston hosts dermatology equipment distributors who specify multi-frequency arrays for mixed patient panels.
South Korea
Seoul-based clinic chains mandate multi-modal platforms bundling ultrasonic cleansing with thermal pulse delivery, creating volume anchors for OEMs. MFDS registration depth anchors domestic compliance frameworks that foreign entrants struggle to replicate. Busan-Ulsan corridor manufacturers supply piezoelectric transducer arrays to regional device assemblers.
Germany
EU MDR Article 10 clinical evaluation requirements redirect R&D budgets toward prospective study design. REACH compliance constraints on lead zirconate titanate formulations thin qualified European suppliers. Bavaria hosts dermatology chains specifying self-calibrating transducers that reduce scheduled maintenance dependencies.
China
NMPA now mandates domestic clinical trials for imported Class II aesthetic equipment, extending market access timelines for brands without local regulatory partnerships. Live-stream commerce platforms bundle ultrasonic devices with personalized skincare regimens, accelerating channel migration. Yangtze River Delta manufacturers dominate portable device assembly for direct-to-consumer export.
Japan
PMDA registration depth and JIS-standard compliance anchor domestic market positioning against foreign entrants. METI guidelines on electromagnetic compatibility testing shape product architecture roadmaps. Tokyo clinic networks prioritize AI-embedded frequency modulation for real-time epidermal impedance adjustment.
Ultrasound Skin Cleaners Market Competitive Landscape
Player mix skews toward vertically integrated specialists and import-dependent assemblers competing on divergent margin structures. Tier concentration is moderate, with premium positioning held by firms controlling captive manufacturing and regulatory registration depth. Two strategic archetypes dominate: vertically integrated manufacturers sustaining margin structures through in-house production, and regulatory-anchored specialists leveraging domestic compliance frameworks. Competitive moves center on geographic registration sequencing and subscription hardware models converting capex to recurring revenue.
Among Nordic vertically integrated manufacturers, Foreo exemplifies the captive-production archetype through Swedish-based manufacturing control. Ya-Man occupies a position within the regulatory-anchored tier, leveraging domestic Japanese compliance depth. Bio-Therapeutic and Dermaflash represent North American positioning, sitting within markets where FDA pathway maturation accelerates commercialization cadence for predicate-backed filers.
| Leading Market Players |
|---|
| Bio-Therapeutic |
| Dermaflash |
| Skin Gym |
| Project E Beauty |
| Foreo |
| Ya-Man |
| Trophy Skin |
| Zemits |
| Lifetrons |
| Others |
Value Network & Pricing Analysis
Capacity reservation agreements with East Asian piezoelectric ceramic refiners lock in transducer supply visibility while fixing lead zirconate titanate input costs against REACH compliance volatility. These contracts shield Swedish and Japanese OEMs from spot market exposure that squeezes import-dependent assemblers in North America and Europe.
Pricing Analysis
Cost-plus contracts with Japanese and South Korean indexation anchor professional equipment pricing against raw material volatility. Three-tier pricing structure across premium clinic-grade, standard salon-tier, and economy portable levels separates FDA 510(k) cleared platforms from unregistered alternatives. Cost compression in the portable tier intensifies as Chinese direct-to-consumer platforms absorb inventory at volume-scaled rates. Home users exhibit highest price sensitivity, while Seoul clinic chains prioritize multi-modal feature bundling over unit economics.
Supply Chain Analysis
China and South Korea anchor piezoelectric transducer fabrication and portable device assembly respectively. Lead zirconate titanate ceramic formulations draw from concentrated East Asian refiners, while MEMS pressure sensors feed from Taiwan semiconductor foundries. Single-source vulnerability in REACH-compliant ceramic supply threatens European OEM margins. Distribution runs through Yangtze River Delta contract manufacturers for direct-to-consumer export, with German and Japanese distributors handling clinic-grade equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in at-home sensor-guided protocols, as millennial and Gen Z buyers displace aesthetician recommendations with algorithmic purchase triggers on live-stream commerce platforms.
For Market Incumbents: Fortify regulatory registration depth in China through NMPA domestic trial partnerships, insulating against the 24-month imported device approval queue. Deepen backward integration into piezoelectric ceramic supply to offset REACH compliance cost concentration among three East Asian refiners. Prioritize AI-embedded frequency modulation R&D to defend margin structures against feature-commoditization in portable tiers. For New Entrants and Emerging Players: FDA 510(k) predicate pathway fast-tracks clearance timelines for ultrasonic cleansing indications, compressing commercialization cadence relative to novel frequency range submissions. White-space concentrates in atopic dermatitis adjacency protocols requiring only labeling expansion, not hardware redesign. Target Chinese live-stream commerce bundling partnerships as the most penetrable channel, pairing devices with personalized skincare regimens. For Investors and Strategic Acquirers: The market sits at a technology-maturation phase that favors vertically integrated manufacturers with captive production and regulatory registration depth. Long-term viability across the five-to-ten year window hinges on subscription hardware models converting clinic capex to recurring revenue. Monitor NMPA joint-venture clinical research organization formation as the inflection signal for accelerated China market access.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Domestic Trial Partnership | Bypasses 24-month imported device queue and unlocks Class II reimbursement pathways. |
| AI-Embedded Frequency Modulation | Expands addressable user profiles beyond trained clinicians through real-time epidermal sensing. |
| Subscription Hardware Model | Converts med-spa capex to recurring revenue through bundled consumable gel cartridges. |
| REACH-Compliant Ceramic Sourcing | Mitigates supply concentration risk among three East Asian lead zirconate titanate refiners. |
| Multi-Modal Platform Bundling | Aligns with Seoul clinic chain standardization on thermal pulse adjunct delivery. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, dermatology clinic procurement officers, regulatory affairs specialists at aesthetic device manufacturers, and live-stream commerce platform category managers, then refined against FDA 510(k) filing databases, EU MDR CE marking registries, NMPA approval records, and South Korean MFDS registration filings. Bottom-up shipment estimates from Yangtze River Delta contract manufacturers triangulated against top-down demand modeling from Seoul clinic chain procurement data.
Variance decomposition across product type, end user, technology modality, and application indication shaped volume and value outputs over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic dermatology service expenditure trends. Industry-specific forecast inputs incorporated piezoelectric transducer cost curves and regulatory pathway timeline maturation.
Underlying assumptions cover REACH compliance stability, FDA predicate database expansion, and NMPA joint-venture partnership viability, with deviation risk concentrated in lead zirconate titanate supply disruptions and EU MDR notified body audit queuing. Recalibration cycles align with material shifts in regulatory clearance timelines and clinic chain procurement standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Non-Surgical Skin Tightening Market
Skincare
Marine Retinol Market
Skincare
Skincare Serums Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Moisturizing Cream Market
Skincare
United Kingdom Skincare Market
Skincare
Global Scar Removal Treatment Market
Skincare
Skin Toner Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Vitamin C Serum Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Global Anti-Aging Market
Skincare
Biocellulose Mask Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Skin Grafting System Market
Skincare
Anti-Acne Dermal Patch Market