
 Anti-Acne Dermal Patch Market | 2026-2036
Anti-Acne Dermal Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Acne Dermal Patch Market Intelligence
Dermatological formulation chemists is reorganizing how patch manufacturers scale production, with specialized talent shortages in Korea and California constraining new entrant capacity. COSRX leverages its Seoul-based R&D campus to control hydrocolloid formulation pipelines from raw polymer to finished patch. Mighty Patch anchors North American shelf presence through Target and Ulta Beauty channel control, while 3M competes on medical-grade adhesive heritage transferred from wound-care divisions.
Anti-acne dermal patches are discrete occlusive dressings, typically 12-24 mm in diameter, composed of hydrocolloid gel layers on polyurethane backings that absorb exudate and maintain moist wound-healing environments for inflamed follicles. The primary commercial purpose is to deliver localized acne intervention without systemic drug exposure, reducing post-inflammatory hyperpigmentation risk. Hydrocolloid patches dominate volume due to mature manufacturing economics, though microdart variants containing salicylic acid or niacinamide command premium positioning in specialty and e-commerce channels. E-commerce platforms represent the fastest-growing end-user access point, bypassing traditional pharmacy gatekeepers through direct-to-consumer subscription models.
FDA medical device classification for hydrocolloid patches mandates biocompatibility testing under ISO 10993 standards, while REACH compliance in Europe restricts certain adhesive polymer chemistries. The EU MDR transition is forcing patch exporters to resubmit technical documentation, raising compliance costs for smaller brands. Stakeholders must monitor how FDA distinguishes between cosmetic and medical device claims, as this boundary determines labeling requirements and clinical data obligations.
Market Dynamics
Hydrocolloid raw material supply is consolidating around three Korean polymer suppliers, creating procurement bottlenecks that constrain patch manufacturers' ability to scale production lines without captive formulation chemistry expertise.
Growth Catalysts
- ISO 10993 biocompatibility standardization:FDA alignment with international testing protocols reduces duplicate certification costs for patch exporters entering US dermatology clinics.
- Moist wound-healing science:Clinical validation of occlusive microenvironments for acne lesions accelerates physician recommendation rates in ambulatory care settings.
- Seoul-Gyeonggi manufacturing corridor:Concentrated polymer synthesis and converting capabilities enable same-day raw material-to-finished-goods turnaround for export orders.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane backing films depend on propylene oxide pricing that fluctuates with refinery utilization rates.
- Single-region adhesive supply:Medical-grade pressure-sensitive adhesive production concentrates in Osaka and Busan, exposing brands to port congestion risk.
- EU MDR technical documentation:Resubmission requirements for hydrocolloid device classifications delay market access for smaller patch brands by 12-18 months.
Strategic Opportunities
- Brazilian dermatology channel expansion:ANVISA's streamlined medical device registration pathway opens shelf access in São Paulo and Rio de Janeiro pharmacy chains.
- Salicylic acid microdart convergence:Combination of hydrocolloid absorption with active ingredient delivery creates premium positioning in direct-to-consumer subscription models.
- Ulta Beauty and Sephora digital shelf integration:Retail media networks enable targeted placement ahead of competitor SKUs based on skin-type search behavior.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in hydrocolloid gel rheology and skin adhesion mechanics commands premium compensation in Seoul and Orange County labor markets.
- Cleanroom capex intensity:Medical device-grade patch production requires ISO Class 7 environments that cost $2,500-4,000 per square meter to construct and validate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Acne Dermal Patch Market |
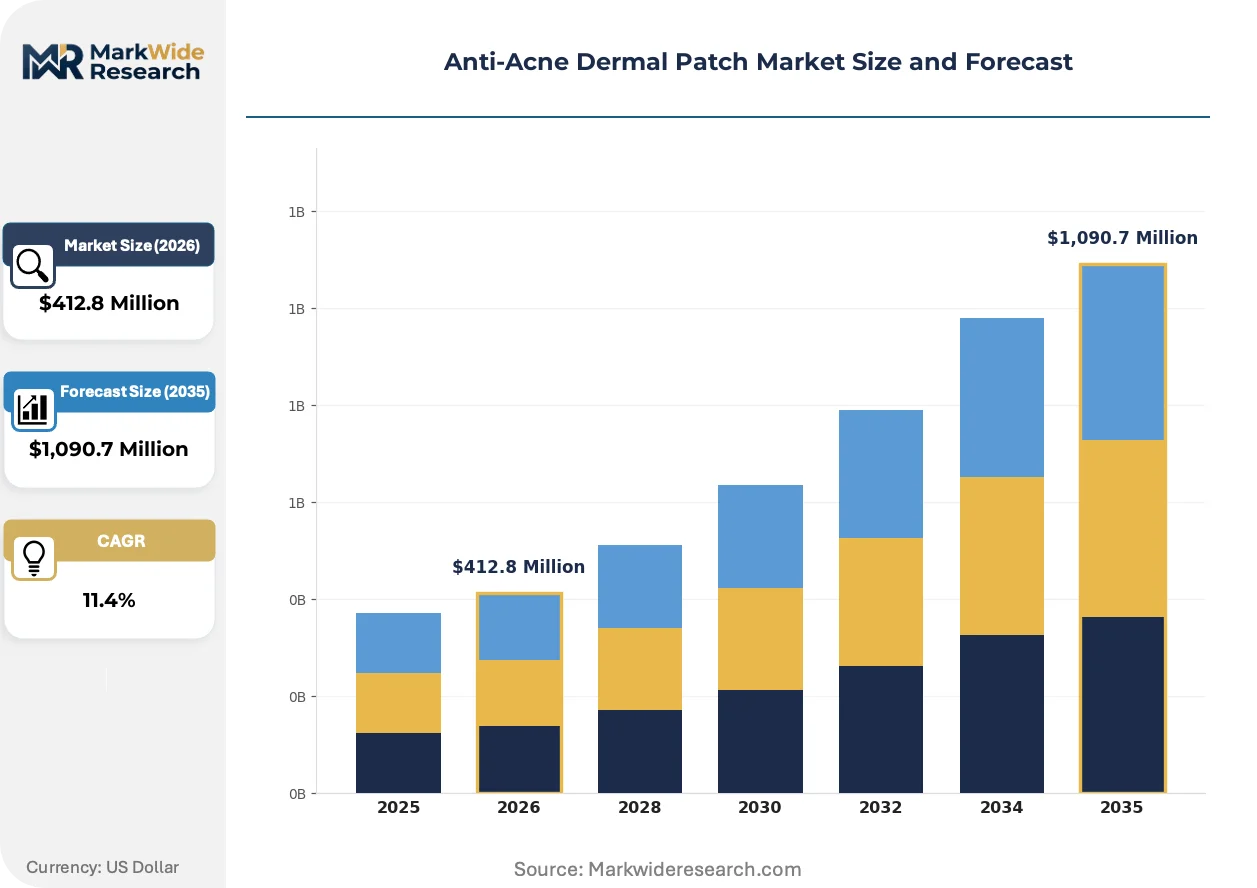
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $1,090.7 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid, Microdart, Biodegradable, Adhesive Application: Acne Treatment, Post-Acne Care, Prevention, Skin Protection End User: Individuals, Dermatology Clinics, Pharmacies, E-Commerce Platforms Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Hero Cosmetics, Rael, COSRX, Peace Out Skincare, ZitSticka, Mighty Patch, Peter Thomas Roth Labs LLC, 3M, Starface, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Acne Dermal Patch Market Strategic Shifts & Innovations
Active ingredient delivery mechanisms are fragmenting the traditional hydrocolloid patch category, with manufacturers racing to integrate pharmaceutical-grade compounds without triggering drug-device combination regulatory thresholds.
Microdart array technology is decomposing the barrier between cosmetic occlusion and pharmaceutical intervention. Dermatology clinics in Gangnam and Beverly Hills are adopting dissolvable hyaluronic acid spikes containing niacinamide at three times the rate of standard hydrocolloid SKUs. This convergence is decomposing the historical price ceiling for patch-based acne treatment by justifying clinical-grade positioning.
EU MDR transition timelines are compressing technical file preparation windows for hydrocolloid patch exporters. The regulation mandates updated clinical evaluation reports and post-market surveillance systems that smaller brands lack resources to assemble. German notified bodies are experiencing 14-month backlogs, forcing manufacturers to prioritize CE marking for core SKUs while delaying variant launches.
Subscription-based replenishment is displacing pharmacy impulse purchases among 18-34 year-old consumers. Direct-to-consumer platforms capture recurring revenue through algorithmic skin-assessment quizzes that recommend patch schedules. This behavioral shift concentrates brand loyalty in Seoul and Los Angeles metro areas where digital-native purchasing patterns dominate acne care procurement.
Anti-Acne Dermal Patch Market Segmentation
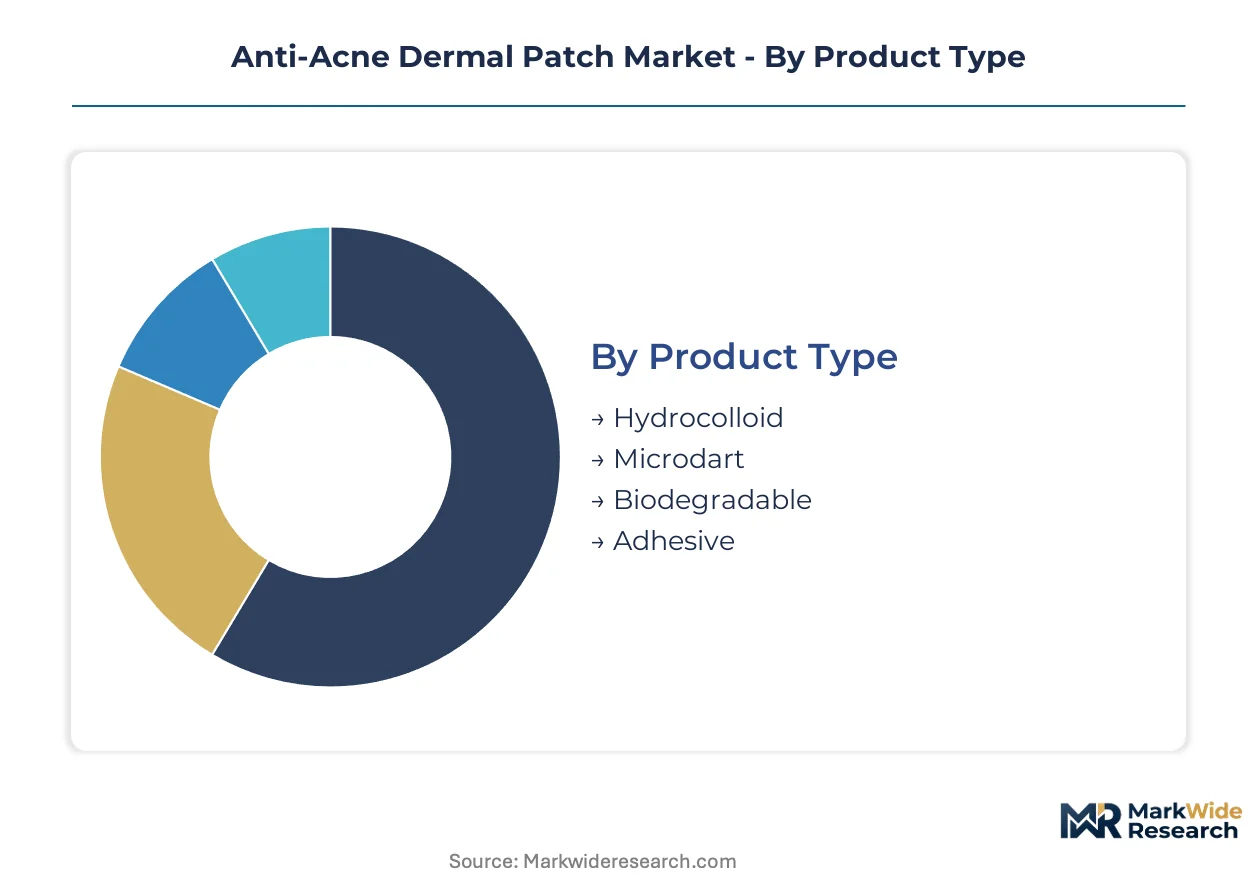
Patch manufacturers align production capacity against distinct demand profiles, with product type and distribution channel configurations determining export feasibility versus domestic market capture. Segmentation clarity exposes where formulation complexity intersects with regulatory pathway selection.
Product Type:
Domestic manufacturing clusters in South Korea and Japan anchor hydrocolloid supply, while microdart production concentrates in California and Seoul for FDA and MFDS dual-track submissions. Biodegradable variants remain export-constrained by compostability certification fragmentation across target markets.
- Hydrocolloid:Gel matrix of carboxymethylcellulose and pectin bonded to polyurethane film absorbs exudate while maintaining moist wound environment. Demand concentrates in US dermatology clinics where ISO 10993 biocompatibility documentation accelerates institutional procurement. Korean polymer suppliers control raw material pricing through three-firm oligopoly structure.
- Microdart:Dissolvable hyaluronic acid spikes measuring 300-500 micrometers deliver niacinamide or salicylic acid directly into follicular openings. Beverly Hills and Gangnam aesthetic clinics adopt these at triple the rate of standard patches, justifying premium positioning through clinical-grade outcome claims. FDA scrutiny on drug-device boundary determinations constrains active ingredient loading.
- Biodegradable:Polylactic acid backings with alginate gels decompose in marine environments within 180 days. European demand leads adoption under EU Green Deal procurement guidelines.
- Adhesive:Silicone-based pressure-sensitive variants minimize trauma upon removal for sensitive skin populations. Japanese cosmetic buyers prioritize these for overnight wear compliance.
Hydrocolloid commands the established base. The steepest expansion runs through microdart arrays.
Application:
Cost tier stratification separates pharmaceutical-grade intervention from cosmetic maintenance, with post-acne recovery commanding formulation premiums due to pigmentation risk sensitivity.
- Acne Treatment:Active lesion management for inflammatory papules and pustules. Dermatology clinics in São Paulo and Mexico City drive volume through protocol standardization.
- Post-Acne Care:Hyperpigmentation mitigation and barrier repair for healing lesions. Korean consumers sustain premium pricing through aesthetic outcome prioritization.
- Prevention:Proactive occlusion for comedone-prone zones during hormonal fluctuations. Direct-to-consumer subscription models capture recurring revenue in Los Angeles and New York metro areas.
- Skin Protection:Environmental barrier function against pollution and friction. Chinese urban consumers adopt these for PM2.5 exposure mitigation.
Acne treatment maintains volume leadership. Prevention applications are climbing the fastest through algorithmic skin-assessment platforms.
End User:
Customer type determines packaging unit economics, with institutional buyers demanding bulk sterile formats while individual consumers prioritize portable sachet configurations.
- Individuals:Direct purchasers through retail and digital channels. E-commerce penetration in Seoul and California concentrates loyalty program investment.
- Dermatology Clinics:Protocol-integrated dispensing for in-office and take-home regimens. ANVISA registration pathways in Brazil open ambulatory care access.
- Pharmacies:Over-the-counter placement alongside topical retinoid and benzoyl peroxide adjacencies. German apothekens sustain margin through consultation bundling.
- E-Commerce Platforms:Algorithmic recommendation engines and subscription replenishment. Ulta Beauty and Sephora retail media networks enable targeted placement by skin-type search behavior.
Individuals represent the volume foundation. E-commerce platforms gain share fastest through subscription lock-in mechanics.
Distribution Channel:
Supply chain configuration stratifies by margin preservation versus volume scale, with specialty stores demanding exclusive SKUs that online retail cannot undercut.
- Online Retail:Direct-to-consumer and marketplace fulfillment. Amazon and Coupang logistics networks enable same-day delivery in Seoul and Los Angeles.
- Supermarkets:Mass-market placement in health and beauty aisles. Target's shelf-reset velocity in North America determines challenger brand access.
- Specialty Stores:Sephora and Ulta Beauty curated assortments with tester availability. Beauty advisor commission structures favor premium microdart SKUs.
- Direct Sales:Dermatologist office dispensing and brand-owned flagship channels. Korean medical aesthetic chains bundle patches with laser treatment packages.
Supermarkets anchor the mass base. Online retail shows the steepest expansion trajectory through subscription algorithm deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA medical device classification for hydrocolloid patches anchors the United States as the regulatory benchmark geography, with Seoul-Gyeonggi manufacturing clusters supplying export markets across three continents.
United States
Dermatology clinics in Los Angeles and New York Metro are expanding patch-based protocols as FDA oversight tightens ingredient disclosure standards under ISO 10993 biocompatibility requirements. Orange County formulation chemists command premium compensation, constraining new entrant capacity. Mighty Patch anchors North American shelf presence through Target and Ulta Beauty channel control.
South Korea
COSRX and Rael anchor domestic manufacturing clusters serving export markets, with same-day raw material-to-finished-goods turnaround enabled by concentrated polymer synthesis capabilities. MFDS dual-track submissions for microdart variants accelerate regulatory pathways for active ingredient delivery systems. Seoul-based R&D campuses control hydrocolloid formulation pipelines from raw polymer to finished patch.
Germany
EU MDR transition timelines compress technical file preparation windows, with notified bodies experiencing 14-month backlogs that delay market access for smaller patch brands. German apothekens sustain margin through consultation bundling alongside topical retinoid adjacencies. REACH compliance restricts certain adhesive polymer chemistries, raising compliance costs for hydrocolloid device classifications.
Brazil
ANVISA's streamlined medical device registration pathway opens shelf access in São Paulo and Rio de Janeiro pharmacy chains, with dermatology clinics driving volume through protocol standardization. Ambulatory care settings in São Paulo Metro adopt patch-based regimens at accelerating rates. Brazilian demand concentrates in post-acne hyperpigmentation mitigation due to phototype-specific outcome prioritization.
Japan
METI standards for pressure-sensitive adhesive biocompatibility intersect with cosmetic claims boundaries, creating dual-track compliance requirements for patch exporters. Osaka medical-grade adhesive production concentrates supply risk for brands dependent on port access. Japanese cosmetic buyers prioritize silicone-based variants for overnight wear compliance, sustaining premium positioning for trauma-minimizing removal properties.
Anti-Acne Dermal Patch Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with hydrocolloid formulation expertise separating premium-positioned specialists from mass-market scale operators. The vendor base stratifies across three tiers: Seoul-anchored integrated manufacturers controlling raw polymer supply, North American brand marketers leveraging retail media networks for digital shelf dominance, and medical-grade adhesive heritage players transferring wound-care division capabilities. M&A activity concentrates on formulation chemistry talent acquisition, while capacity expansion focuses on ISO Class 7 cleanroom validation for medical device-grade production lines.
Among Seoul-anchored integrated manufacturers, COSRX exemplifies captive supply chain control from raw polymer synthesis through finished patch converting. Rael occupies a position within the same manufacturing corridor, representing domestic cluster advantages for export order fulfillment. At the medical-grade adhesive heritage end, 3M anchors competitive positioning through wound-care division technology transfer, sitting within a distinct archetype of industrial conglomerate diversification into consumer dermatology applications.
| Leading Market Players |
|---|
| Hero Cosmetics |
| Rael |
| COSRX |
| Peace Out Skincare |
| ZitSticka |
| Mighty Patch |
| Peter Thomas Roth Labs LLC |
| 3M |
| Starface |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Korean polymer suppliers and patch manufacturers lock in both hydrocolloid raw material access and eighteen-month price visibility, insulating integrated producers from propylene oxide feedstock swings that buffet spot-market buyers in California and Germany.
Pricing Analysis
Seoul-Gyeonggi manufacturers command fifteen to twenty percent premiums over California contract converters for equivalent hydrocolloid specifications. Three-tier pricing structure across premium microdart, standard hydrocolloid, and economy adhesive variants reflects ISO 10993 certification tier and active ingredient loading. Price erosion runs through mass-market supermarket tiers as Mighty Patch and Hero Cosmetics compress shelf-space economics. Direct-to-consumer subscription buyers exhibit lowest price sensitivity, while pharmacy chain procurement committees drive hardest unit-cost negotiations.
Supply Chain Analysis
Busan port congestion periodically severs medical-grade pressure-sensitive adhesive flows to North American converting lines, exposing brands to four-to-six week production delays. Raw material supply concentrates in South Korea, Japan, and Germany for hydrocolloid gels, polyurethane backings, and silicone adhesives respectively. Manufacturing rests on carboxymethylcellulose pectin blends, propylene oxide derivatives, and hyaluronic acid microspheres. Single-region adhesive production in Osaka and Busan creates tariff-exposure vulnerability for exporters. Distribution runs through Seoul-Gyeonggi manufacturing corridors for Asian markets and Orange County cleanroom facilities for FDA-regulated US supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patch-based acne intervention is reconfiguring as a service-attach business, with algorithmic skin-assessment subscription layers expanding faster than standalone hardware sales through recurring replenishment algorithms.
For Market Incumbents: Secure captive hydrocolloid formulation chemistry expertise through targeted hiring in Seoul and Orange County labor markets. Lock in multi-year offtake contracts with the three-firm Korean polymer oligopoly before feedstock volatility accelerates. Defend against microdart entrants by accelerating MFDS dual-track submissions for active ingredient delivery systems.
For New Entrants and Emerging Players: Lead with biodegradable patch variants targeting EU Green Deal procurement guidelines where compostability certification fragments incumbent advantage. Brazilian dermatology channels through ANVISA's streamlined registration pathway offer most penetrable white-space access. Deploy direct-to-consumer subscription models with algorithmic skin-type matching to bypass Target and Ulta Beauty gatekeeper control.
For Investors and Strategic Acquirers: Seoul-anchored integrated manufacturers with raw polymer-to-finished-patch control represent the highest-conviction acquisition archetype for long-term viability across the next decade. Formulation chemist scarcity in both Korean and California markets signals durable margin protection for vertically integrated assets. Watch FDA drug-device boundary determinations on microdart active ingredient loading as the critical inflection indicator for category expansion versus regulatory compression.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO Class 7 Cleanroom Validation | Medical device-grade production lines require $2,500-4,000 per square meter construction costs under FDA oversight. |
| MFDS Dual-Track Submission | Accelerated regulatory pathways for microdart variants containing niacinamide or salicylic acid active ingredients. |
| Direct-to-Consumer Subscription Launch | Algorithmic skin-assessment quizzes capture recurring revenue and displace pharmacy impulse purchases among digital-native consumers. |
| Backward Integration into Polymer Synthesis | COSRX-style captive supply chains insulate against Korean three-firm oligopoly pricing power and feedstock volatility. |
| EU MDR Technical File Resubmission | CE marking compliance for hydrocolloid device classifications navigates fourteen-month German notified body backlogs. |
Research Approach
Desk research of FDA 510(k) filings, MFDS medical device registrations, and Korean customs export data preceded structured interviews with dermatology clinic procurement directors, hydrocolloid formulation chemists, and e-commerce platform category managers. Primary fieldwork with patch manufacturers in Seoul-Gyeonggi and Orange County validated secondary estimates of cleanroom capacity expansion timelines. Bottom-up SKU-level volume builds triangulated against top-down market sizing from polymer supplier shipment disclosures.
Variance decomposition across product type, application, end user, and distribution channel segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by base-year revenue contribution. Modeled inputs included ISO 10993 biocompatibility certification adoption curves, subscription penetration rates in Seoul and Los Angeles metro areas, and ANVISA registration velocity for Brazilian market access.
The analysis sits within stated boundaries; outcomes outside sustained FDA medical device classification stability or Korean polymer supply continuity would require recalibration. Forecasts reflect documented assumptions on cleanroom capex intensity and formulation chemist labor market tightness. Practitioners should keep alternative scenarios live as EU MDR transition timelines and propylene oxide feedstock volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Facial Skincare Market
Skincare
Mineral Sunscreen Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Pseudo Collagen Market
Skincare
Herbal Skincare Products Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Facial Mist Market
Skincare
Incontinence Skin Care Products Market
Skincare
Global Scar Removal Treatment Market
Skincare
CBD Skincare Products Market
Skincare
Europe Functional Cosmetics Market
Skincare
Preoperative Skin Preparation Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Facial Massage Cream Market
Skincare
Anti-Aging Services Market