
 Facial Mist Market | 2026-2036
Facial Mist Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Mist Market Foresight
Biome-friendly fermentation technology is tilting formulation pipelines toward postbiotic-infused mists that strengthen skin barrier function rather than delivering surface-level hydration. Amorepacific leverages decades of fermented ingredient research to anchor its premium positioning across Asian and North American channels. L'Oréal Group competes through mass-market scale, while Tatcha differentiates via Japanese superfood-inspired compositions targeting wellness-oriented consumers.
A facial mist is a liquid aerosolized or pump-dispensed skincare product typically comprising water, humectants, and active botanical or mineral compounds, designed for topical application to deliver hydration, soothe irritation, or prepare skin for subsequent product layers. Hydrating mists and treatment mists occupy the deepest margin pools, as consumers pay premiums for hyaluronic acid and peptide complexes over basic thermal water sprays. Online retail channels are capturing the fastest volume growth, though specialty stores sustain higher average transaction values through assisted selling and sampling programs.
FDA cosmetic labeling requirements and EU REACH compliance frameworks govern ingredient safety disclosures, while the EU Green Deal pushes brands toward biodegradable packaging and reduced volatile organic compound propellants. South Korea's MFDS maintains stringent functional cosmetic approval pathways that elevate entry barriers for treatment claims. Stakeholders must monitor evolving regulatory divergence between Asian and Western markets when configuring global product portfolios.
Market Dynamics
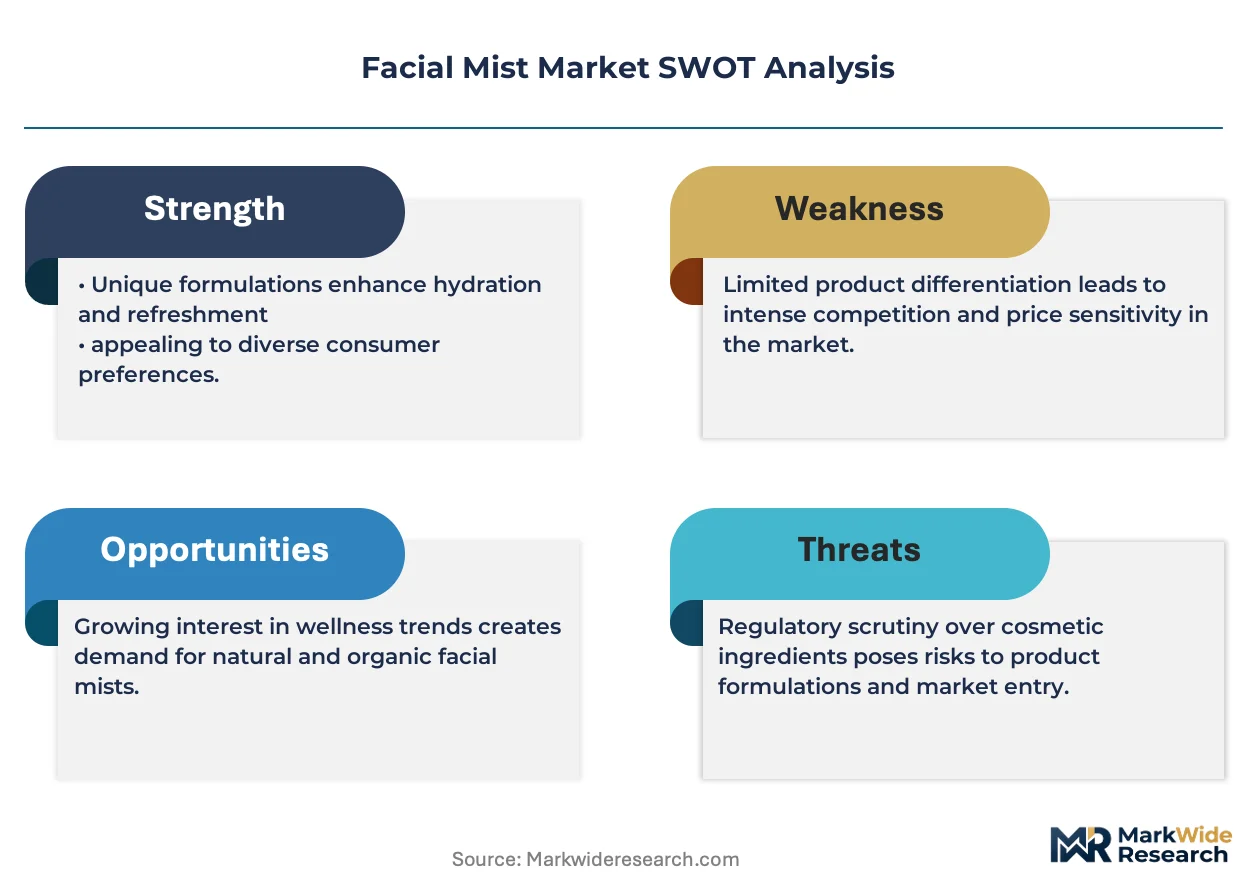
Fermentation-derived postbiotics are compressing formulation cycles as brands race to claim barrier-repair positioning ahead of competitors, while EU ingredient disclosure mandates force simultaneous packaging and labeling overhauls.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable aerosol alternatives and reduced volatile organic compound propellants create first-mover advantages for compliant suppliers.
- K-beauty export infrastructure:South Korea's domestic innovation hubs channel formulation expertise into North American and Southeast Asian retail networks.
- Hyaluronic acid complex demand:Treatment mists with peptide-infused formulations command sustained premium pricing in specialty retail channels.
Market Restraints
- Glass and aluminum input volatility:Sustainable packaging materials face price instability that compresses margin structures for mid-tier brands.
- MFDS functional cosmetic pathways:South Korea's stringent approval timelines for treatment claims delay product launches by 18-24 months.
- Thermal water spray substitution:Basic hydration products face displacement from multi-functional essences and lightweight serums.
Strategic Opportunities
- Indian clean beauty underpenetration:BIS certification frameworks and FSSAI cosmetic regulations create whitespace for compliant international entrants.
- Livestream commerce integration:China's digital retail ecosystem enables real-time formulation demonstrations that accelerate purchase conversion.
- Postbiotic-microneedle convergence:Delivery technology hybrids open professional clinic and medical spa distribution channels.
Industry Challenges
- Fermentation scientist scarcity:Biome-friendly formulation expertise concentrates in South Korean and Japanese research clusters.
- REACH compliance documentation:ECHA ingredient safety dossiers require specialized regulatory affairs capacity that smaller brands lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Mist Market |
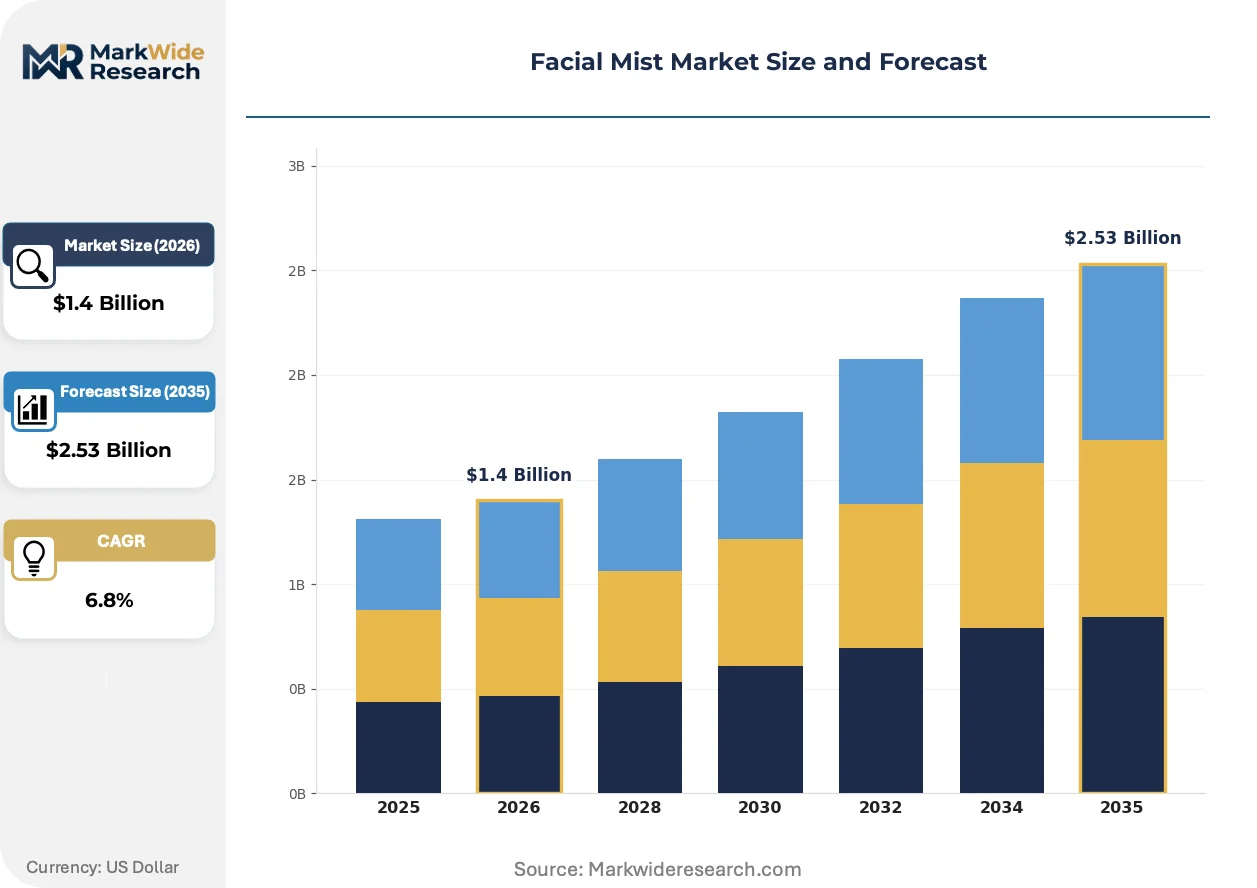
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating Mists, Refreshing Mists, Setting Mists, Treatment Mists Ingredient Type: Botanical Extracts, Mineral Water, Hyaluronic Acid, Essential Oils Target Demographic: Teenagers, Young Adults, Professionals, Seniors Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Amorepacific, La Roche-Posay, L'Oréal Group, Laneige, Tatcha, The Estée Lauder Companies, Avène, Kiehl's, Shiseido, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Mist Market Shifts & Advancements
Active ingredient delivery systems are fragmenting as brands pursue distinct technological moats, while regulatory divergence between Asian and Western markets forces parallel product development tracks.
Postbiotic fermentation technology is hybridizing barrier-strengthening and microbiome-balancing functions within single formulations. Skincare-conscious young adults in urban centers adopt these hybrid products faster than traditional thermal water segments. The convergence is compressing standalone probiotic and prebiotic categories into unified mist positioning.
EU REACH compliance frameworks are tightening safety assessment requirements for aerosolized botanical extracts. Manufacturers must submit expanded toxicological data that extends development timelines. Treatment mist segments with functional claims face the heaviest documentation burdens, pushing some brands toward simpler hydrating formulations.
Assisted selling in specialty stores is losing volume share to algorithm-driven online discovery. Direct-to-consumer channels capture younger demographics through subscription models and personalized skin diagnostic tools. South Korea's digital-native retailers demonstrate the most advanced integration of virtual try-on with postbiotic ingredient education.
Facial Mist Market Segmentation
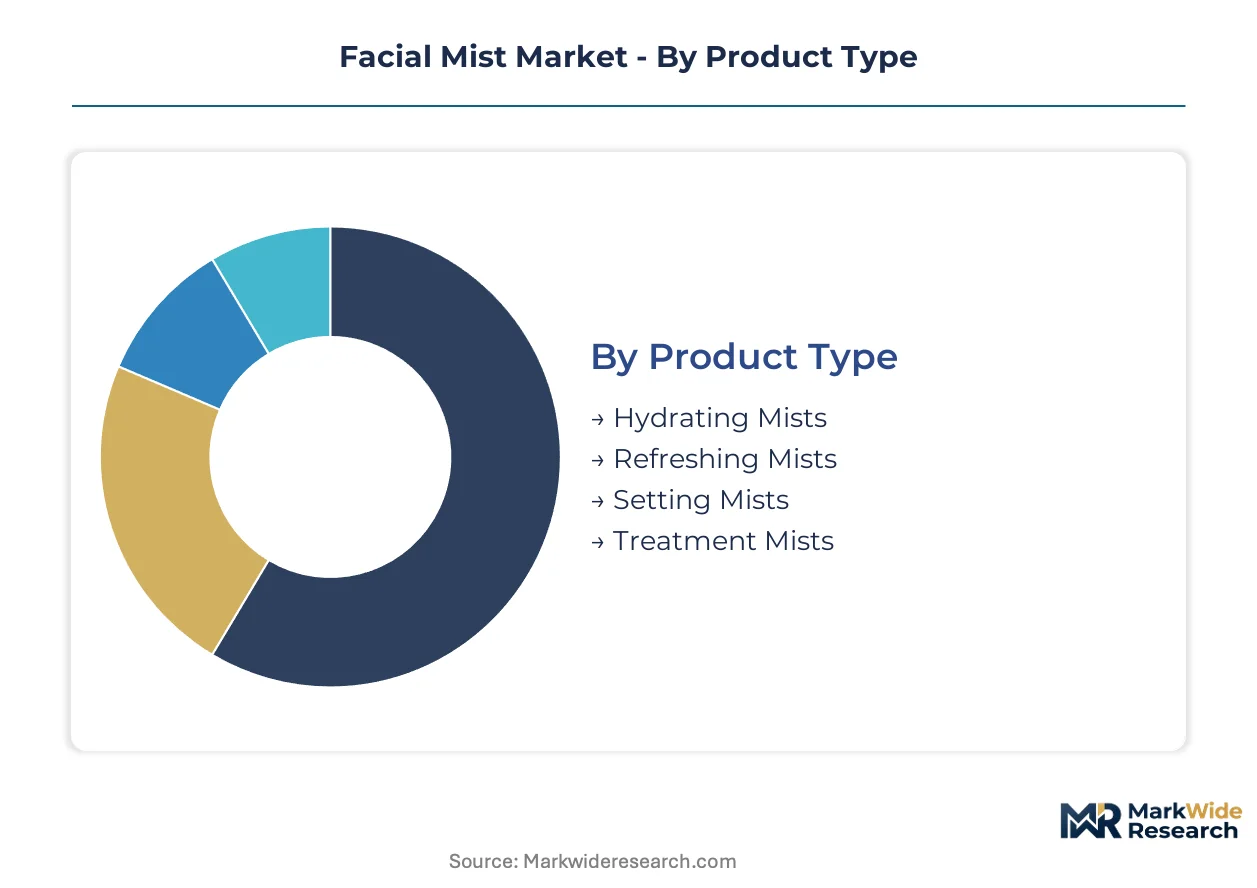
Facial mist segmentation reveals how formulation sophistication and channel strategy determine margin capture. Product architecture and ingredient sourcing separate premium positioning from commodity competition.
Product Type:
The use-case spectrum spans surface hydration through clinical-grade barrier repair, with functional complexity driving price architecture.
- Hydrating Mists:Water-based formulations with humectant complexes deliver immediate moisture replenishment for daily maintenance routines. Demand concentrates among young adults in South Korea seeking lightweight layering products under sunscreen and makeup. K-beauty export channels sustain volume leadership through accessible price points.
- Treatment Mists:Peptide-infused and postbiotic-fermented compositions target barrier dysfunction and microbiome imbalance with functional claims. Specialty stores in Japan and North American medical spas capture the steepest premium pricing for these clinically-positioned products. MFDS approval pathways in South Korea create 18-24 month launch delays that protect first-mover positioning.
- Refreshing Mists:Thermal water and mineral-rich sprays provide sensory cooling without active treatment claims.
- Setting Mists:Film-forming polymers lock makeup placement while delivering secondary hydration benefits.
The dominant share belongs to Hydrating Mists, while Treatment Mists is closing the gap fastest.
Ingredient Type:
Cost tier stratification separates commodity water-based formulations from biotechnology-derived actives commanding laboratory premiums.
- Hyaluronic Acid:Multi-molecular weight hyaluronan complexes enable deep dermal penetration alongside surface film formation. Young adult consumers in urban China and Southeast Asia demonstrate the strongest willingness-to-pay for proven humectant science. Supply concentration among fermentation specialists in South Korea creates procurement bottlenecks for Western formulators.
- Botanical Extracts:Centella asiatica, green tea polyphenols, and adaptogenic plant complexes anchor clean beauty positioning. EU REACH compliance documentation requirements for aerosolized botanicals extend development timelines by 8-12 months. Brands with established ECHA dossier capabilities extract competitive distance from smaller entrants.
- Mineral Water:Geothermally sourced thermal waters from specific French and Japanese springs support heritage marketing claims.
- Essential Oils:Aromatic plant distillates face declining inclusion rates due to EU fragrance allergen labeling mandates.
Hyaluronic Acid formulations capture the deepest margin pools, though Botanical Extracts is expanding most quickly through clean beauty certification pipelines.
Target Demographic:
Application intensity and skin concern sophistication vary dramatically across life stages and professional contexts.
- Young Adults:Skincare-conscious consumers aged 18-34 demonstrate the highest category engagement and trial velocity. South Korean and Chinese urban centers concentrate the most advanced adoption of multi-step routines incorporating barrier-repair mists. Social commerce discovery and influencer education accelerate purchase conversion in this cohort.
- Professionals:Time-constrained office workers in metropolitan India and Brazil seek portable hydration solutions for climate-controlled environments. Travel-size formats and desk-friendly packaging drive repeat purchase frequency among this segment.
- Teenagers:Entry-level price sensitivity and acne-prone skin concerns shape introductory product selection.
- Seniors:Barrier-weakened skin and medication-induced dryness create demand for ceramide-enriched treatment formulations.
Young Adults command the largest volume share, while Professionals is gaining share fastest through workplace wellness positioning.
Distribution Channel:
Customer acquisition economics and average transaction values diverge sharply between assisted and algorithm-driven purchase journeys.
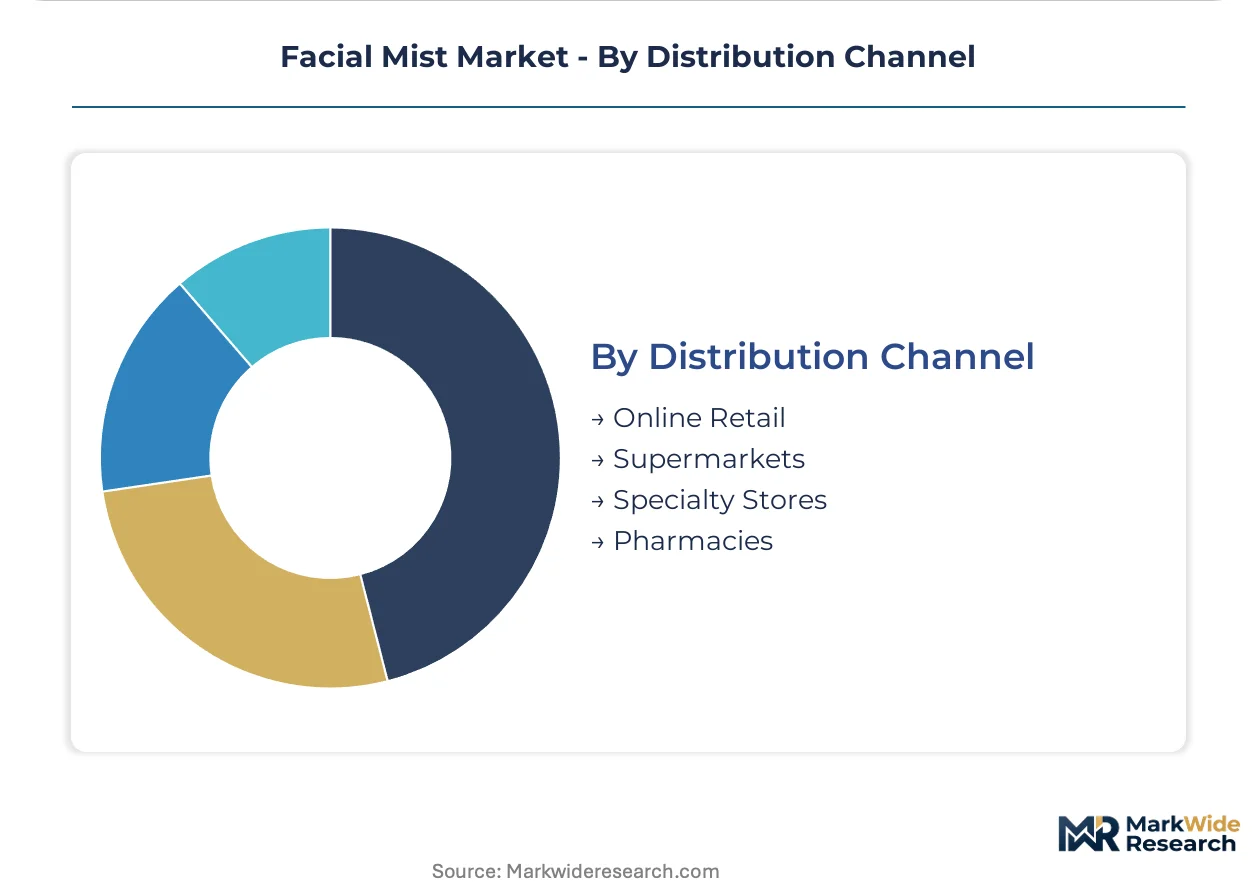
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture the steepest volume growth through subscription models and personalized skin diagnostics. China's livestream commerce ecosystem enables real-time formulation demonstrations that compress consideration-to-purchase cycles. Algorithmic recommendation engines expose niche postbiotic brands to previously unreachable audiences.
- Specialty Stores:Sephora, Ulta, and department store beauty halls sustain the highest average transaction values through sampling programs and consultant-assisted selling. South Korean multi-brand retailers demonstrate the most sophisticated integration of virtual try-on with ingredient education.
- Supermarkets:Mass-market thermal water sprays and basic hydrating formats compete on shelf visibility and promotional pricing.
- Pharmacies:Treatment mists with functional claims leverage healthcare credibility and insurance-adjacent purchase contexts.
Online Retail leads absolute volume, though Specialty Stores is climbing the fastest through experiential retail investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skincare-conscious young adults concentrate in urban innovation hubs across South Korea, China, and the United States, driving formulation sophistication and premium pricing acceptance. Their demand patterns pull supply chain investment toward postbiotic fermentation capacity and clean beauty certification infrastructure.
South Korea
Seoul's Gangnam and Hongdae districts generate the highest per-capita facial mist consumption globally, with multi-step routines now standard among consumers under 35. MFDS functional cosmetic approval pathways create 18-24 month barriers for treatment claim entrants, protecting domestic first-movers. The Songdo International Business District hosts concentrated R&D facilities where Amorepacific and Laneige anchor fermentation technology clusters.
United States
Coastal metropolitan areas from Los Angeles to New York sustain specialty retail channel dominance through Sephora and Ulta assisted-selling programs. FDA cosmetic labeling requirements govern ingredient safety disclosures, while California's Proposition 65 adds supplemental warning mandates for botanical extracts. The New Jersey corridor houses formulation laboratories serving direct-to-consumer brands targeting microbiome-conscious millennials.
China
Shanghai and Hangzhou livestream commerce ecosystems compress consideration-to-purchase cycles through real-time ingredient demonstrations. SAMR cosmetic registration requirements and GB standards for aerosol safety create compliance complexity for imported treatment mists. The Yangtze River Delta manufacturing belt supplies pump-dispensing and biodegradable packaging components to both domestic and export-oriented brands.
France
Parisian pharmacy channels leverage heritage thermal water sourcing from specific geothermally active springs in the Massif Central. EU REACH compliance frameworks and ECHA safety dossier requirements extend development timelines for aerosolized botanical formulations. The Lyon biotech corridor hosts fermentation research partnerships between cosmetic houses and agricultural science institutes.
Japan
Tokyo's Shibuya and Ginza districts demonstrate the most sophisticated integration of virtual try-on technology with postbiotic ingredient education. METI standards for sustainable packaging and PMDA oversight of quasi-drug claims shape product architecture decisions. The Kansai region around Osaka maintains traditional superfood-inspired formulation expertise that Tatcha and Shiseido leverage for wellness-positioned exports.
Facial Mist Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where mass-market scale and premium positioning operate on divergent capability requirements. The vendor base separates into three tiers: multinational conglomerates with cross-category leverage, fermentation-anchored Asian houses with ingredient science depth, and digitally native specialists with direct consumer relationships. Dominant competitive moves include backward integration into captive fermentation capacity and geographic licensing partnerships that bypass regulatory approval delays.
Within the fermentation-science tier, Amorepacific occupies a position exemplifying decades of postbiotic research translated into premium Asian and North American channel presence. L'Oréal Group sits within the scale-driven conglomerate archetype, competing through mass-market distribution density and portfolio breadth across thermal water and treatment mist segments. Tatcha represents the wellness-positioned specialist model, anchoring Japanese superfood-inspired compositions for algorithm-discovered audiences in direct-to-consumer and specialty retail channels.
| Leading Market Players |
|---|
| Amorepacific |
| La Roche-Posay |
| L'Oréal Group |
| Laneige |
| Tatcha |
| The Estée Lauder Companies |
| Avène |
| Kiehl's |
| Shiseido |
| Others |
Supply & Pricing Matrix
Songdo International Business District fermentation capacity anchors downstream pricing power for postbiotic-infused treatment mists, where captive R&D clusters compress formulation cycle costs and elevate margin capture for barrier-repair positioning.
Pricing Analysis
Cost-plus contracts with aluminum and glass indexation dominate packaging procurement, exposing mid-tier brands to input volatility that compresses margin structures. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-certified treatment mists from basic thermal water sprays, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from sustainable packaging material cost inflation. Young adults in South Korea demonstrate lowest price sensitivity for peptide-infused formulations, while mass-market thermal water buyers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for pump-dispensing and biodegradable packaging components. Manufacturing concentrates in South Korea, China, and Japan, with raw material dependencies spanning fermentation-derived hyaluronic acid, geothermally sourced thermal water, and aluminum aerosol canisters. Distribution runs through direct-to-consumer platforms and specialty retail channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Livestream commerce ecosystems in China and South Korea function as platform-economics inflection points, where real-time formulation demonstrations and algorithmic discovery reshape customer acquisition economics and brand entry pathways.
For Market Incumbents: Build captive fermentation capacity moats through backward integration into postbiotic research clusters in Seoul and Osaka. Secure MFDS approval pipeline advantages to delay competitor treatment claim launches by 18-24 months. Expand virtual try-on integration with ingredient education to defend specialty retail channel share against algorithm-driven discovery platforms.
For New Entrants and Emerging Players: Indian clean beauty underpenetration offers whitespace acquisition potential through BIS certification compliance and FSSAI cosmetic regulatory navigation. Target professional workplace wellness segments in metropolitan Brazil and India with travel-size portable formats. Leverage subscription model direct-to-consumer launch to bypass established retail gatekeepers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with personalized skin diagnostic tools and subscription replenishment programs. Long-term viability over the projection horizon favors fermentation-science specialists with captive postbiotic supply and ECHA dossier capabilities. Monitor livestream commerce conversion rate inflections as early signals of platform shift acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive postbiotic supply secures formulation differentiation against commodity competitors in Seoul clusters. |
| MFDS Functional Cosmetic Approval Investment | Treatment claim pathways create 18-24 month launch barriers protecting first-mover positioning in South Korea. |
| Livestream Commerce Platform Integration | Real-time ingredient demonstrations in Hangzhou and Shanghai compress consideration-to-purchase cycles measurably. |
| Biodegradable Packaging Transition | EU Green Deal compliance generates first-mover advantages in REACH-regulated European distribution channels. |
| Direct-to-Consumer Subscription Launch | Personalized skin diagnostics drive recurring revenue conversion among young adult urban demographics. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fermentation R&D directors, brand managers at K-beauty houses, specialty retail category buyers, and regulatory affairs specialists; and secondary validation through MFDS functional cosmetic filings, ECHA REACH dossier databases, SAMR cosmetic registration records, and customs trade flow data. Bottom-up volume triangulation across product type, ingredient tier, and channel segments converged with top-down macro anchoring.
Forecast inputs span hydrating versus treatment mist adoption curves, postbiotic ingredient penetration rates, livestream commerce channel share trajectories, and clean beauty certification pipeline expansion across the analysis window. Segmentation modeling incorporates product architecture, active ingredient biotechnology tier, demographic cohort application intensity, and distribution channel economics. CAGRs derive from regression-adjusted growth rate calibration against historical volume inflections.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices, aluminum commodity price bands, or cross-border e-commerce tariff regimes would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Algae Skincare Products Market
Skincare
Global Scar Removal Treatment Market
Skincare
Africa Cosmeceutical Market
Skincare
Moisturizing Cream Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Ampoule Cream Market
Skincare
Vitamin C Serum Market
Skincare
Encapsulated Retinol Market
Skincare
Global Anti-Aging Market
Skincare
Marine Retinol Market
Skincare
Global Skin Tears Treatment Market
Skincare
Biological Skin Substitutes Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Skin Replacement Market
Skincare
Hyaluronic Acid Personal Care Products Market
Skincare
Cosmeceuticals Market