
 Self-Tanning Care Market | 2026-2036
Self-Tanning Care Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Tanning Care Market Analytics
France is fragmenting as contract manufacturers and indie brands erode legacy control over European self-tanning supply. L'Oréal S.A. leverages its dermatological heritage to command premium shelf positioning across pharmacies and Sephora doors. Bondi Sands Pty Ltd. anchors its competitiveness through aggressive social-native marketing and beach-culture brand identity. St. Tropez specializes in salon-grade formulations that sustain professional channel loyalty despite retail commoditization.
Self-tanning care encompasses topical cosmetic preparations formulated with dihydroxyacetone (DHA) concentrations typically ranging from three to fifteen percent, designed to induce temporary melanoidin formation in the stratum corneum without ultraviolet exposure. These products serve consumers seeking cosmetic bronzing for aesthetic, confidence, or skin-health motivations while avoiding solar or artificial UV damage. Lotions retain the largest volume share due to their familiar application ritual and moisturizing dual function, though sprays are capturing growth among time-constrained users seeking even coverage. DHA-Based formulations dominate ingredient-type segmentation because of their predictable color development and decades of consumer familiarity, while Natural and Organic sub-categories attract premium pricing from clean-beauty adherents willing to accept shorter wear duration.
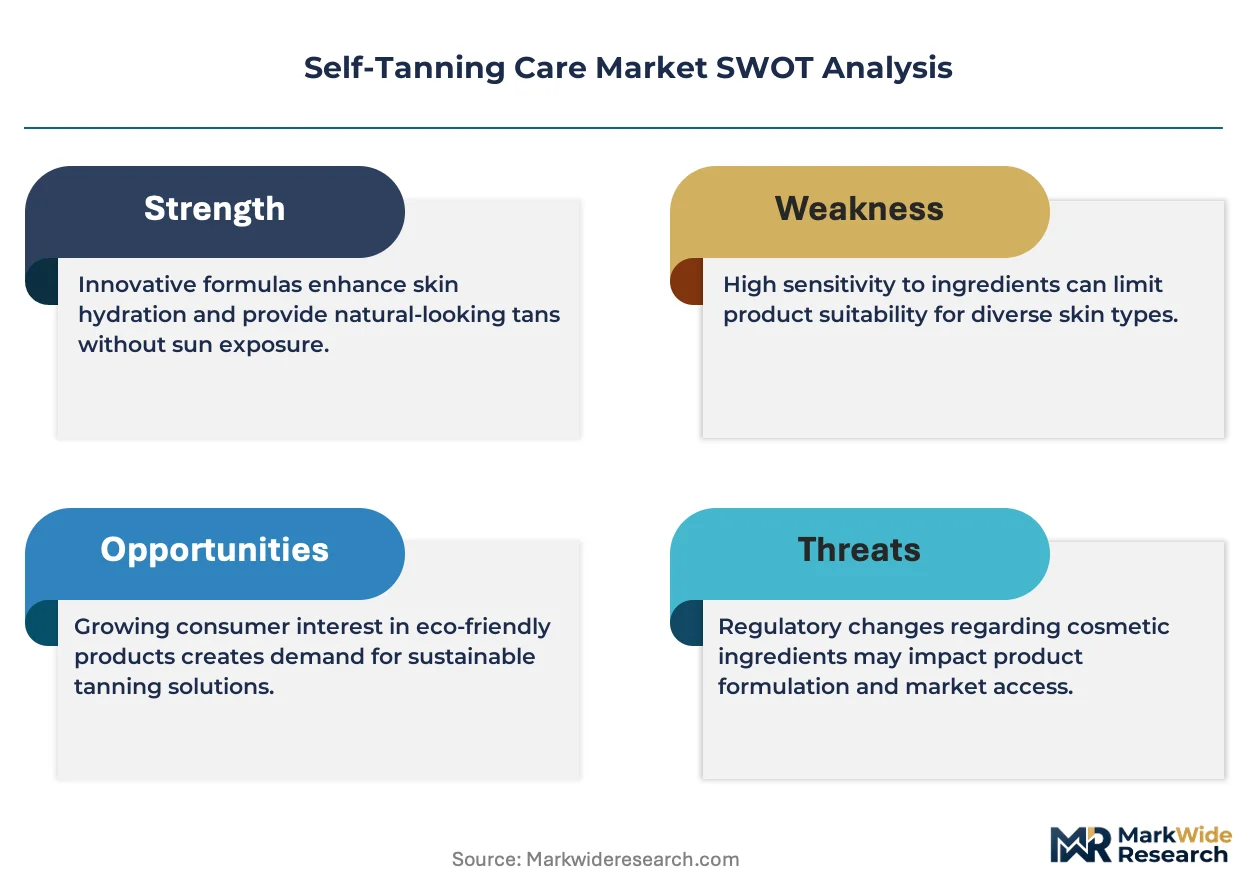
FDA oversight of cosmetic color additives and EU REACH chemical safety assessments constrain permissible DHA sources and co-formulant choices, pushing manufacturers toward exhaustive toxicological documentation. The EU's MDR and ongoing ECHA evaluations of inhalation exposure from spray applications are tightening occupational-use guidelines and consumer labeling requirements. Formulators and brand owners must monitor evolving aerosol restrictions and biotechnological alternatives to petrochemical-derived DHA as regulatory thresholds tighten across North America and Europe.
Market Dynamics
EU REACH chemical safety assessments are forcing reformulation timelines across the self-tanning care sector, compressing product development cycles and elevating toxicological documentation costs for manufacturers serving European and North American markets.
Growth Catalysts
- Clean-beauty certification mandates:Sephora and Ulta Beauty have implemented ingredient transparency requirements that push formulators toward plant-derived DHA alternatives, expanding the natural and organic sub-category.
- Social-native marketing infrastructure:TikTok and Instagram shopping integrations enable direct-to-consumer brands to bypass traditional retail slotting fees, lowering customer acquisition costs for emerging players.
- France:Indie brands and contract manufacturers are fragmenting legacy control, creating shelf space for innovative entrants at pharmacies and selective distribution channels.
Market Restraints
- Petrochemical-derived DHA supply concentration:Three specialty chemical suppliers control the majority of cosmetic-grade DHA feedstock, exposing formulators to input cost volatility and allocation risk.
- Inhalation exposure limitations:ECHA evaluations of spray application safety are tightening occupational-use guidelines and constraining aerosol product development pipelines.
- Wear duration trade-offs:Natural and organic formulations deliver shorter color persistence than synthetic DHA alternatives, limiting premium pricing power and repeat purchase frequency.
Strategic Opportunities
- Biotechnology convergence:Fermentation-derived DHA and enzymatic browning agents offer pathways to bypass petrochemical dependency while meeting clean-label demands.
- Professional channel expansion:Salon-grade formulations command loyalty through trained application expertise, insulating premium players from retail commoditization.
- India:Rising disposable incomes and limited UV tanning infrastructure create underpenetrated demand for sunless bronzing solutions among urban millennials.
Industry Challenges
- Toxicological documentation timelines:REACH compliance requires 12-18 month safety dossier preparation, delaying product launches and freezing working capital.
- Formulation chemist scarcity:Specialized expertise in DHA stability, pH buffering, and odor-masking technologies concentrates among aging talent pools with limited knowledge transfer mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Tanning Care Market |
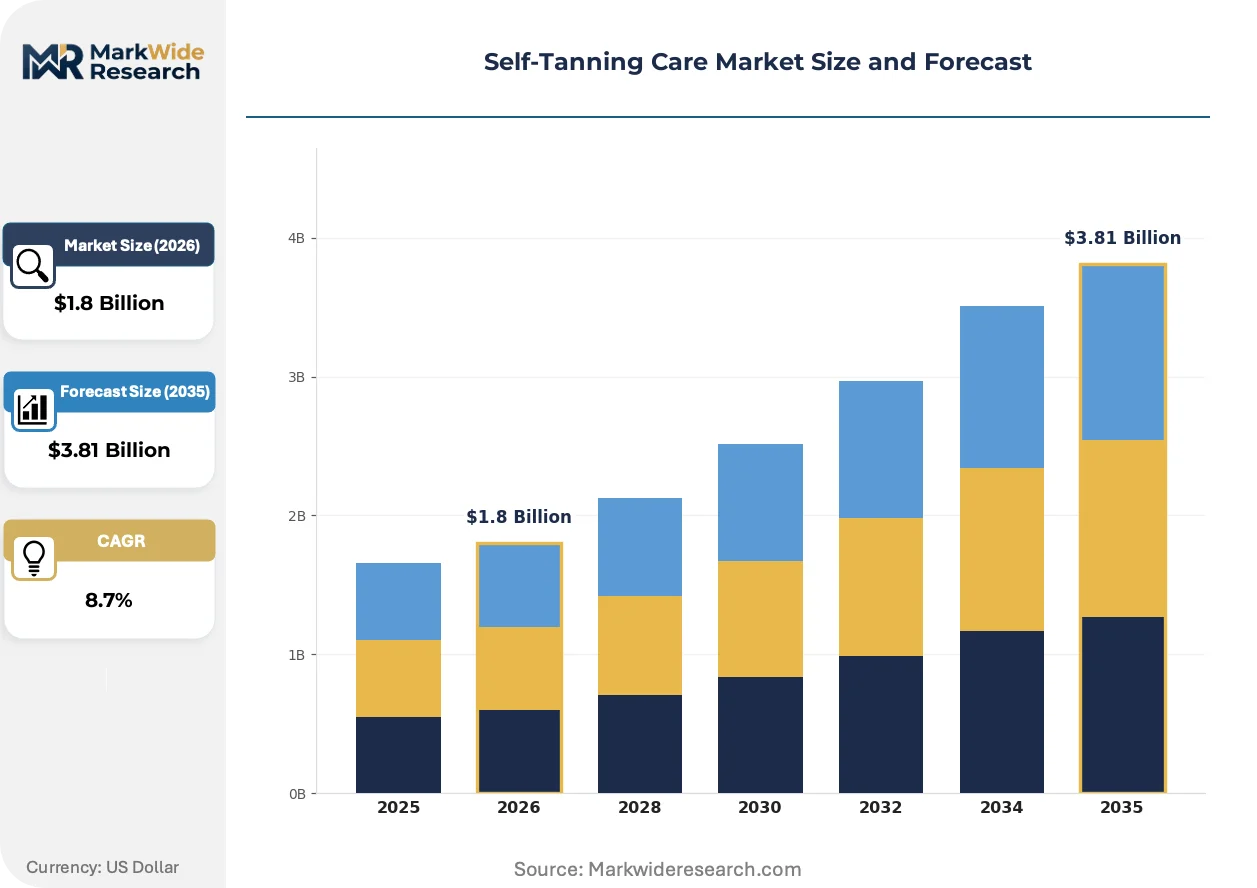
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Sprays, Gels, Towelettes Application Method: Airbrush, Hand Application, Applicator Mitt, Mist Skin Type: Normal, Oily, Dry, Combination Ingredient Type: Natural, Organic, DHA-Based, Synthetic |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies, Procter & Gamble Co., Unilever PLC, Johnson & Johnson Services Inc., Kao Corp., Shiseido Co. Ltd., Bondi Sands Pty Ltd., St. Tropez, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Tanning Care Market Evolving Landscape
Active ingredient sourcing and application modalities are undergoing parallel transformation, driven by regulatory pressure on chemical safety and consumer demand for seamless user experiences.
Biotechnological DHA production is migrating from laboratory-scale fermentation toward commercial manufacturing partnerships with specialty chemical firms. Clean-beauty adherents in Germany and the Netherlands are adopting these alternatives despite 15-20% cost premiums. This shift is compressing reliance on petrochemical supply chains while extending formulation stability challenges.
REACH authorization requirements for cosmetic color additives are tightening permissible co-formulant choices across the European Economic Area. Manufacturers must now submit exhaustive inhalation exposure data for aerosol formats, elevating compliance costs. Spray product lines face reformulation or channel restriction toward professional-only distribution.
Millennial and Gen Z buyers are consolidating skincare routines into multi-functional products that combine bronzing with barrier repair or antioxidant protection. Specialty retailers are responding by reconfiguring shelf sets around "skin health" rather than "sun care" merchandising. This behavioral pivot is most visible in United States Sephora doors, where self-tanning SKUs now sit adjacent to serums rather than seasonal sunscreen displays.
Self-Tanning Care Market Segmentation
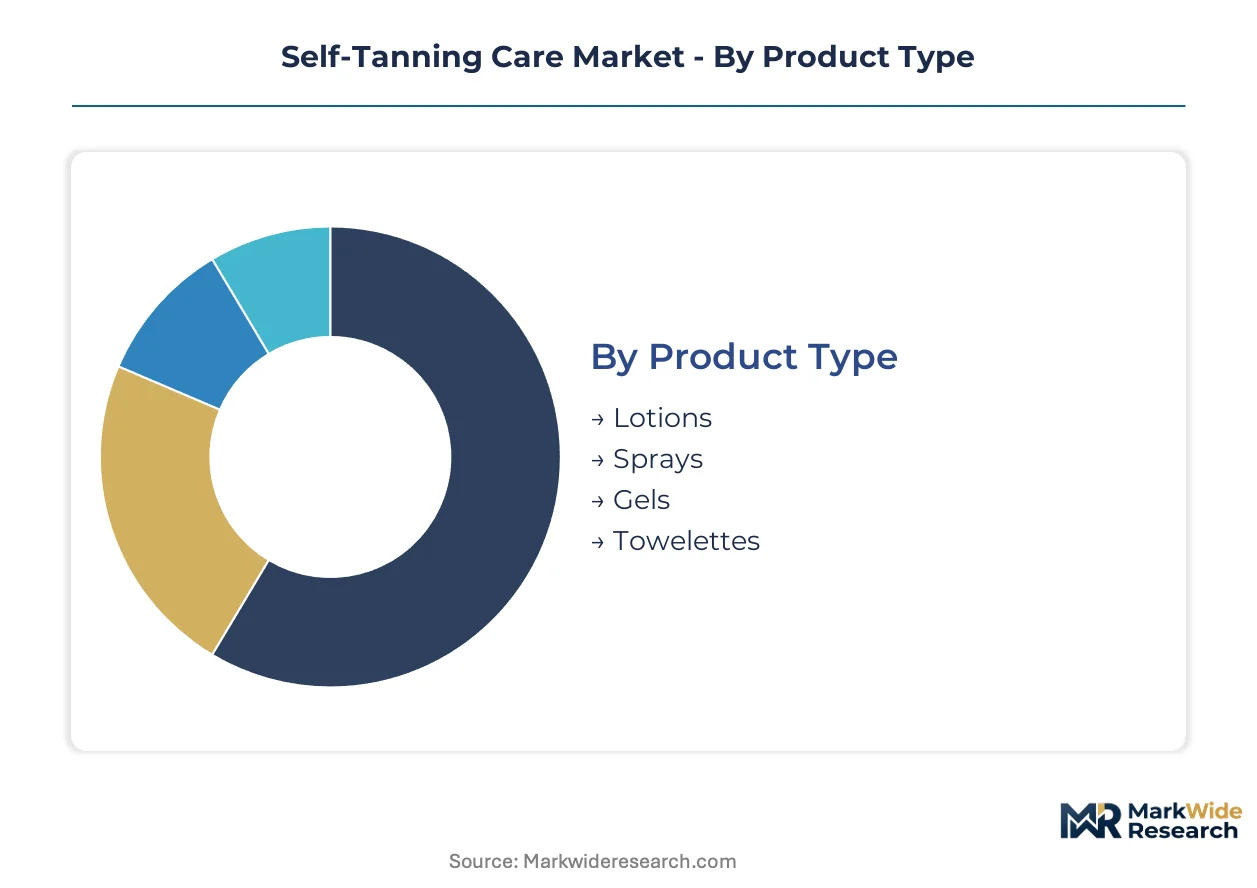
Segmentation in self-tanning care reveals distinct consumption patterns tied to application rituals, skin physiology, and ingredient transparency preferences. Manufacturers calibrate formulation chemistry and packaging formats against these divides to capture repeat purchase loyalty and premium pricing power.
Product Type:
Lotions turn inventory slowest due to established consumer habits, while sprays and towelettes cycle faster among trial-oriented buyers seeking convenience or travel portability.
- Lotions:Emulsion-based vehicles with DHA concentrations calibrated for gradual color build-up, typically incorporating humectants for dual moisturization. Mass-market and prestige channels in the United States favor this format for its familiar tactile ritual and extended wear duration. Lotions anchor the volume base while sprays gain share at the steepest rate.
- Sprays:Aerosol or pump-dispensed formulations enabling rapid, even coverage across large surface areas. Time-constrained professionals and fitness enthusiasts in urban markets drive demand, though ECHA inhalation exposure assessments constrain aerosol pipeline development.
- Gels:Lightweight, fast-absorbing vehicles preferred by oily-skinned consumers seeking non-comedogenic bronzing solutions. Sephora and Ulta Beauty have expanded gel SKU counts to capture male and Gen Z demographics.
- Towelettes:Single-use impregnated wipes delivering pre-measured DHA doses for travel and touch-up applications. Disposable format appeals to festival-goers and business travelers prioritizing portability over cost efficiency.
Sprays and towelettes compress the replenishment cycle through convenience positioning, whereas lotions sustain higher per-unit margins via bulk sizing and subscription bundling.
Application Method:
Cost tiers stratify sharply here: airbrush commands salon-grade pricing, hand application dominates mass retail, and mitts occupy the mid-market bridge.
- Airbrush:Professional-grade equipment delivering micronized DHA particles for streak-free, customizable depth. Licensed aestheticians and spray tan studios in Los Angeles and Miami anchor demand, insulating providers from retail commoditization.
- Hand Application:Direct palm spreading of lotion or gel formats without intermediary tools. Lowest barrier to entry drives volume in drugstore and grocery channels, though uneven results elevate product return rates.
- Applicator Mitt:Reusable microfiber gloves preventing palm staining while ensuring even product distribution. Bondi Sands and St. Tropez bundle branded mitts with core SKUs to lock in ecosystem loyalty.
- Mist:Continuous-spray pump bottles offering aerosol-like coverage without propellant chemistry. Clean-beauty retailers favor this format for its inhalation risk reduction and travel-friendliness.
Hand application generates the highest absolute unit volume, yet airbrush services deliver the steepest revenue-per-transaction expansion.
Skin Type:
Formulation complexity concentrates where physiological variability demands customized pH buffering and emollient loading.
- Normal:Baseline skin condition accommodating standard DHA concentrations without compensatory ingredients. Broadest addressable market supports economy-to-premium tiering across all retail channels.
- Oily:Mattifying, non-comedogenic vehicles with reduced occlusive agent content. Gel and mist formats predominate here, with demand clustering among younger demographics and humid-climate consumers.
- Dry:Richer emulsion bases incorporating ceramides, hyaluronic acid, or plant butters to prevent DHA-induced desquamation. Pharmacy and dermatologist-recommended channels favor these formulations.
- Combination:Zone-specific treatment requirements driving multi-product routines or hybrid formulations. This segment commands premium pricing for perceived customization despite formulation overlap with single-condition SKUs.
Normal skin targeting saturates shelf space, while combination skin formulations expand most quickly through personalized skincare algorithm recommendations.
Ingredient Type:
Supply concentration in petrochemical-derived DHA elevates cost volatility for synthetic and DHA-Based segments, while natural and organic alternatives face stability and duration trade-offs.
- DHA-Based:Synthetic dihydroxyacetone produced via glycerol fermentation or chemical oxidation, delivering predictable melanoidin formation and 5-7 day wear. Decades of consumer familiarity and regulatory documentation support dominance in United States and European mass markets.
- Natural:Plant-derived alternatives utilizing erythrulose, caramel, or walnut extract for temporary bronzing. German and Dutch clean-beauty adherents absorb 15-20% cost premiums despite shorter color persistence.
- Organic:Certified inputs meeting USDA or ECOCERT standards with restricted synthetic co-formulant palettes. Supply scarcity and batch variability constrain scale, limiting presence to specialty retailers and direct-to-consumer channels.
- Synthetic:Petrochemical-derived DHA and conventional cosmetic chemistry without natural positioning claims. Cost efficiency sustains volume in private-label and value-tier retail, though REACH documentation requirements compress margin structures.
DHA-Based formulations anchor manufacturer revenue, while natural alternatives climb fastest through Sephora's Clean at Sephora certification gatekeeping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of cosmetic color additives anchors United States market dynamics, while EU REACH chemical safety assessments reshape European formulation standards. Demand concentrates in developed markets with established clean-beauty retail infrastructure.
United States
Direct-to-consumer brands and specialty retailers command significant shelf space across Sephora and Ulta Beauty doors. FDA regulations on DHA concentration limits and labeling requirements constrain permissible formulations. Los Angeles and Miami anchor professional spray tan studio networks that sustain salon-grade service demand.
France
Indie brands and contract manufacturers fragment legacy control over European self-tanning supply. ANSM and EU REACH compliance requirements elevate toxicological documentation burdens for market entrants. Paris-based selective distribution channels and pharmacy networks create premium positioning opportunities for dermatologically-positioned products.
Germany
Clean-beauty adherents absorb cost premiums for plant-derived DHA alternatives despite shorter wear duration. BIS and EU Green Deal alignment pressures drive biotechnology adoption in ingredient sourcing. Berlin and Hamburg specialty retailers reconfigure shelf sets around skin health merchandising rather than seasonal displays.
United Kingdom
Social-native marketing infrastructure enables emerging brands to bypass traditional retail slotting fees. UK REACH transition from EU regulatory frameworks creates temporary compliance uncertainty for imported formulations. London anchors influencer-driven demand generation through TikTok and Instagram shopping integrations.
India
Rising disposable incomes among urban millennials create underpenetrated demand for sunless bronzing solutions. CDSCO cosmetic registration requirements and limited domestic DHA manufacturing capacity constrain supply expansion. Mumbai and Delhi-NCR concentrate early adopter demand among fitness enthusiasts and wedding-season consumers.
Self-Tanning Care Market Competitive Landscape
Prestige conglomerates and indie specialists split the market into distinct competitive spheres. L'Oréal S.A., Estée Lauder Companies, and Procter & Gamble Co. anchor mass and prestige retail through portfolio breadth and dermatological heritage claims. Unilever PLC and Johnson & Johnson Services Inc. leverage distribution density in pharmacy and grocery channels. Strategic archetypes include multinational beauty conglomerates with R&D scale, social-native direct-to-consumer disruptors, and professional-salon equipment specialists. Competitive moves concentrate on clean-beauty certification acquisition and biotechnology partnerships for fermentation-derived DHA sourcing.
Within the multinational tier, L'Oréal S.A. and Estée Lauder Companies exemplify dermatological heritage positioning across pharmacy and prestige retail doors. Bondi Sands Pty Ltd. and St. Tropez occupy positions within the indie-specialist and professional-salon archetypes respectively, representing beach-culture brand identity and salon-grade formulation expertise. Kao Corp. and Shiseido Co. Ltd. anchor Asia-Pacific origin diversification within the competitive set.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies |
| Procter & Gamble Co. |
| Unilever PLC |
| Johnson & Johnson Services Inc. |
| Kao Corp. |
| Shiseido Co. Ltd. |
| Bondi Sands Pty Ltd. |
| St. Tropez |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Rotterdam container freight corridors impose volatile landed costs on European formulators sourcing cosmetic-grade DHA, compressing margin structures and forcing three-tier pricing stratification across premium pharmacy, standard mass retail, and economy private-label tiers.
Pricing Analysis
Geographic price spreads between United States prestige retail and European pharmacy channels reach 40-60% for equivalent DHA concentrations, driven by FDA documentation burdens versus REACH compliance cost allocation. Three-tier pricing structure across premium, standard, and economy levels separates dermatologist-recommended SKUs from Sephora-positioned brands and grocery private labels. Cost compression in the natural and organic tier intensifies because fermentation-derived DHA carries 15-20% input premiums. Mass-market hand-application buyers exhibit highest price sensitivity, while professional airbrush service clients demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk profiles for cosmetic-grade DHA feedstock. Manufacturing concentrates in China, Germany, and the United States, with three specialty chemical suppliers controlling majority petrochemical-derived output. Formulators draw from glycerol fermentation streams, enzymatic browning agents, and plant-derived erythrulose as alternative inputs. Single-source vulnerability in biotechnology partnerships threatens clean-beauty brand pipelines. Distribution runs through direct-to-consumer platforms, Sephora and Ulta Beauty doors, and pharmacy selective distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional spray tan services and subscription replenishment programs expand faster than hardware SKU sales, creating service-attach revenue layers that insulate margins from retail commoditization.
For Market Incumbents: Insulate salon-grade formulation expertise through captive training academy networks, preventing indie competitors from replicating airbrush service quality. Backward integration into fermentation-derived DHA partnerships secures clean-beauty certification pipelines against petrochemical supply volatility. L'Oréal S.A. and Estée Lauder Companies should prioritize REACH pre-registration dossier completion to freeze working capital advantages over smaller rivals facing 12-18 month documentation timelines.
For New Entrants and Emerging Players: Urban millennial consumers in Mumbai and Delhi-NCR represent the most penetrable entry point for sunless bronzing solutions, given limited UV tanning infrastructure and rising disposable incomes. Social-native marketing through TikTok shopping integrations bypasses traditional retail slotting fees that burden legacy brand economics. Target festival-goers and wedding-season consumers with towelette format trials, converting to lotion subscriptions via performance data capture.
For Investors and Strategic Acquirers: Biotech-enabled ingredient suppliers with commercial-scale fermentation capabilities offer the strongest acquisition target archetype for long-term viability across the 5-10 year window. Clean-beauty certification infrastructure and REACH compliance expertise concentrate in aging talent pools with limited knowledge transfer mechanisms. Watch ECHA aerosol restriction rulings as the inflection indicator for professional-channel valuation premiums versus retail-exposed assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Partnership | Fermentation-derived DHA sourcing bypasses petrochemical dependency while meeting Sephora Clean certification. |
| Professional Channel Expansion | Salon-grade formulations command loyalty through trained application expertise in Los Angeles and Miami studios. |
| Direct-to-Consumer Launch | TikTok shopping integrations lower customer acquisition costs for emerging players against legacy retail economics. |
| Clean-Beauty Certification | ECOCERT and USDA Organic positioning unlocks 15-20% pricing premiums in German and Dutch markets. |
| Regulatory Pre-Registration | REACH dossier completion freezes competitive advantage through 12-18 month documentation barriers. |
Research Methodology
The analysis maps DHA-based, natural, organic, and synthetic formulation sub-sectors, each validated through formulation chemists, brand marketing executives, pharmacy category buyers, and contract manufacturing procurement leads. Primary interviews with specialty chemical suppliers and clean-beauty retail merchandisers combined with secondary validation from FDA color additive filings, ECHA REACH registration databases, and Sephora SKU velocity data. Bottom-up demand modeling across application methods and skin types triangulated against top-down market sizing from customs trade records and Nielsen retail audit data.
Assumptions held fixed include REACH authorization timelines and DHA concentration regulatory ceilings, while variables tested encompass biotechnology adoption rates and social-native marketing efficiency. Segmentation dimensions modeled span product type, application method, skin type, and ingredient transparency tier across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and channel shift elasticities. Forecast inputs incorporated Sephora Clean at Sephora certification gatekeeping intensity and ECHA aerosol exposure assessment progression.
Macroeconomic conditions sit as an overlay; deviation in disposable income trajectories among urban millennials or freight cost volatility on Asia-Europe corridors would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and biotechnology scale-up timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Skin Care Emulsion Market
Skincare
Organic Skincare Products Market
Skincare
Skin Antiseptic Market
Skincare
Global Skin Tears Treatment Market
Skincare
Anti-Aging Services Market
Skincare
Biological Skin Substitutes Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Algae Skincare Products Market
Skincare
Skin Care Body Products Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
Preoperative Skin Preparation Market
Skincare
Vitamin C Serum Market
Skincare
Europe Functional Cosmetics Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Skincare Cdmo and Cmo Market