
 Facial Mask Market | 2026-2036
Facial Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Mask Market Intelligence
The EU Green Deal is rebalancing raw material sourcing across the facial mask supply chain as European buyers enforce biodegradability mandates. L'Oréal leverages its integrated R&D network to reformulate sheet substrates around cellulose alternatives. Amorepacific Corporation anchors premium positioning through fermentation-derived actives sourced from its Seoul facilities. Estee Lauder Companies Inc. competes on clinical credibility by aligning mask claims with dermatological testing protocols.
A facial mask is a topical skincare delivery system comprising a substrate or semi-solid base saturated with active ingredients such as hyaluronic acid, niacinamide, or botanical extracts, designed for timed dermal contact to enhance hydration, absorption, or exfoliation. Manufacturing employs either nonwoven fiber lamination for sheet formats or emulsion compounding for cream and gel variants, with primary commercial purpose centered on at-home treatment extension between professional skincare visits. Sheet masks dominate volume due to single-use convenience and travel retail penetration, while clay masks capture margin pools through premium mineral sourcing and detoxification positioning. Hydration-focused SKUs sustain baseline demand across age demographics, whereas anti-aging formulations command higher per-unit economics in professional channels.
FDA cosmetic labeling requirements, REACH substance restrictions, and China's GB standards for cosmetics safety collectively govern ingredient transparency, microbiological limits, and import clearance protocols across major production and consumption zones. South Korea's MFDS maintains stringent functional claim verification that shapes export eligibility for K-beauty brands targeting regulated markets. Stakeholders must monitor evolving packaging waste directives in Europe and North America, as extended producer responsibility rules will increasingly determine substrate material selection and supply chain compliance costs.
Market Dynamics
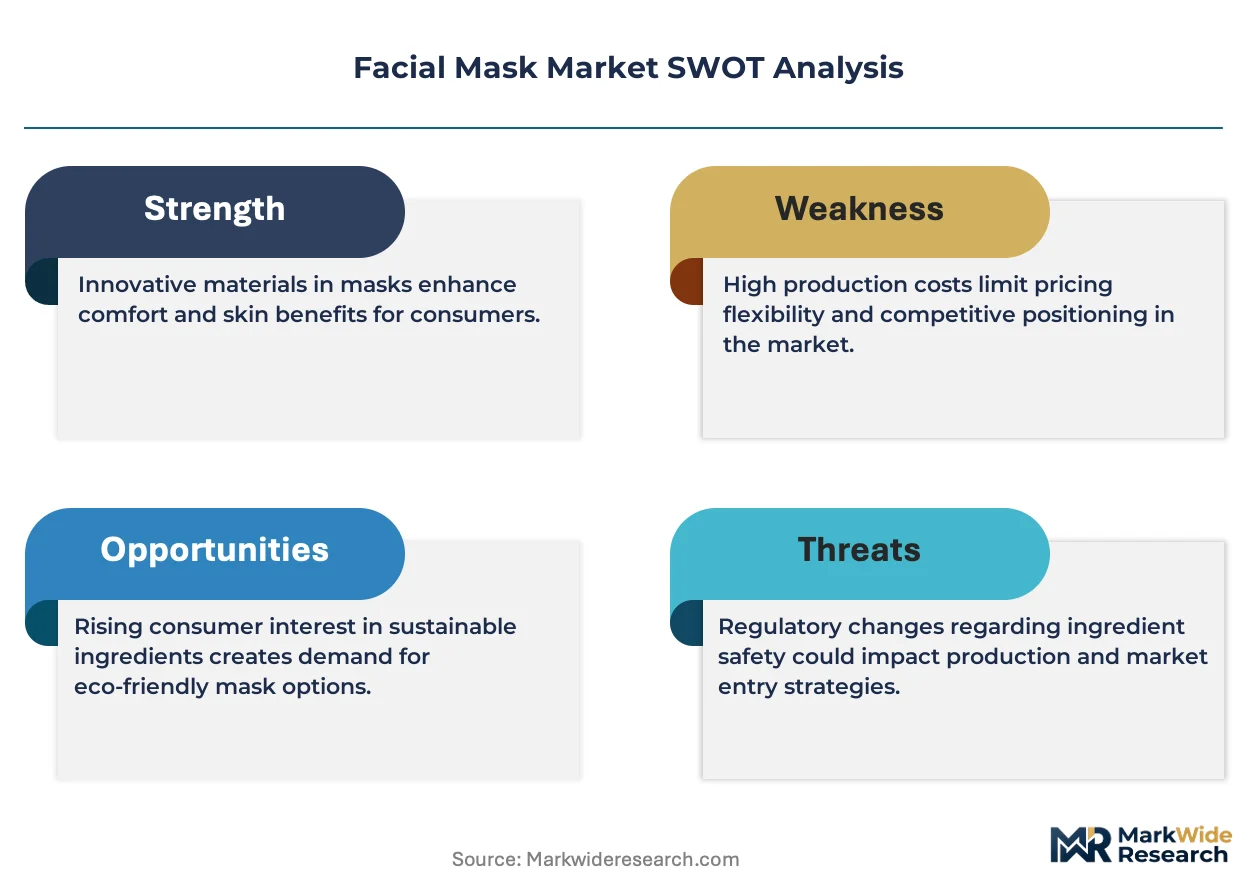
Biodegradability mandates from the EU Green Deal are forcing substrate material substitution across facial mask supply chains, compressing margins for nonwoven petroleum-based fiber producers while opening formulation advantages for cellulose and fermentation-derived alternatives.
Growth Catalysts
- Post-procedure recovery protocols:Professional spa chains and dermatology clinics in Seoul, Tokyo, and New York are expanding mask-based skin recovery services after laser and peel treatments, embedding single-use sheet formats into clinical workflows.
- REACH substance disclosure:European ingredient transparency rules are accelerating clean-label competition, rewarding manufacturers who preemptively publish full component lists and biodegradability certifications.
- K-beauty export infrastructure:South Korea's formulation clusters and cross-border e-commerce pipelines are concentrating demand origination, with Seoul-based R&D facilities feeding private-label production for global retail brands.
Market Restraints
- Petroleum-based fiber cost volatility:Polypropylene and polyester feedstock price swings squeeze nonwoven sheet manufacturers who lack backward integration into polymer supply.
- Single-use plastic directives:Extended producer responsibility rules in France and Germany are imposing per-unit waste fees on conventional sheet mask packaging, eroding the format's cost advantage.
- Functional claim verification:South Korea's MFDS maintains stringent documentation requirements for whitening, anti-wrinkle, and UV-blocking claims, delaying export eligibility for smaller brands.
Strategic Opportunities
- Men's grooming channel expansion:Underpenetrated male demographics in Japan and South Korea present white space for charcoal and pore-care positioning through convenience store and subscription box channels.
- Fermentation-derived actives:Convergence of biotech processing with traditional botanical extraction enables novel ingredient positioning, with Seoul facilities already scaling galactomyces and bifida lysate production.
- Professional channel credentialing:Dermatological testing protocols and clinic-exclusive SKUs create margin pools separate from mass retail, with New York and Los Angeles aesthetic practices driving adoption.
Industry Challenges
- Microbiologist staffing shortages:Clean-room manufacturing and preservative-free formulation trends require specialized quality control personnel that contract manufacturers struggle to recruit.
- Biodegradable substrate scale-up:Cellulose and seaweed-based nonwoven production lacks the throughput capacity of spunbond petroleum lines, creating supply bottlenecks for brands switching materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Mask Market |
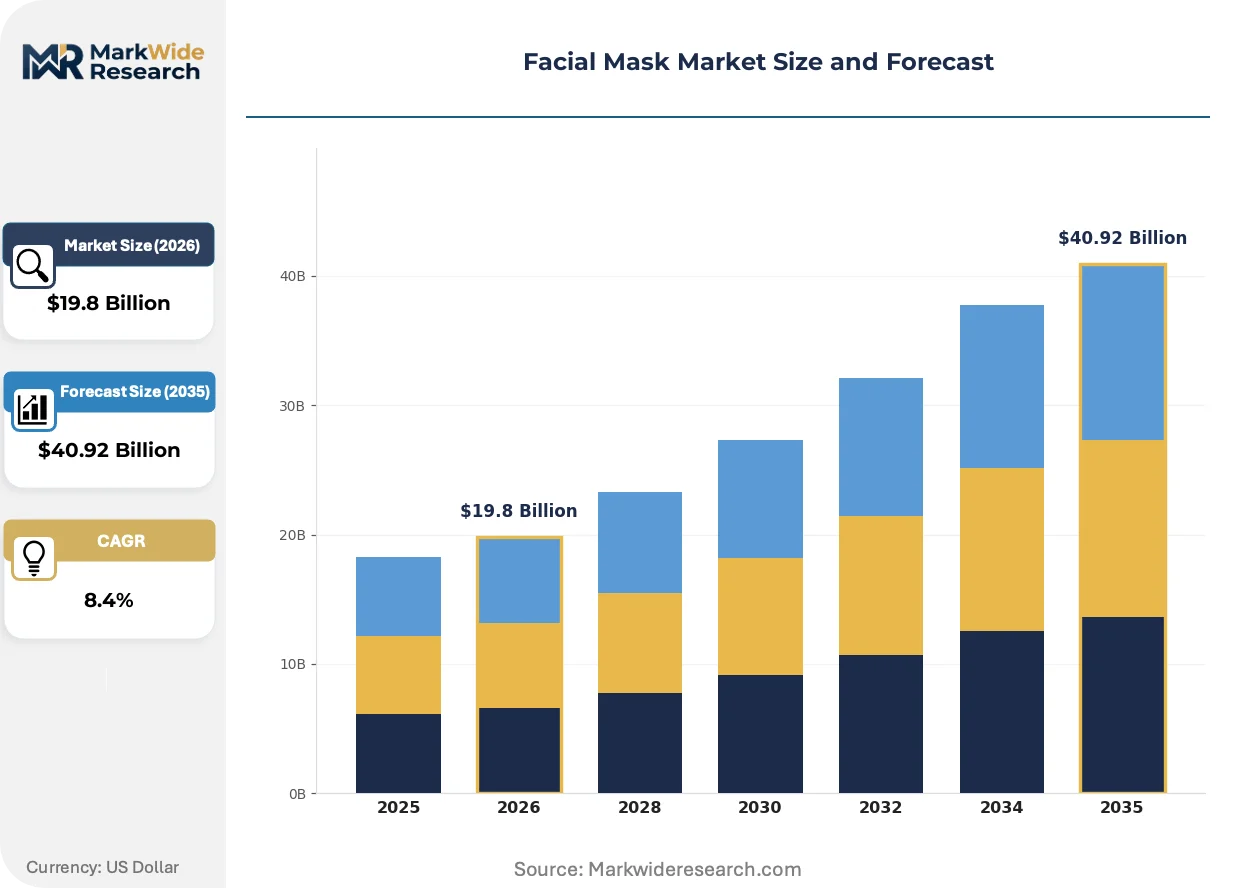
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Masks, Clay Masks, Peel-Off Masks, Cream Masks, Gel Masks Skin Concern: Hydration, Anti-Aging, Brightening, Acne Treatment, Pore Minimizing Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Beauty Salons, Department Stores End User: Individual Consumers, Beauty Clinics, Spas, Dermatology Centers, Wellness Retreats |
| Companies Covered | Amorepacific Corporation, Innisfree Corporation, L'Oréal, Tonymoly Co., SK-II, Estee Lauder Companies Inc., The Face Shop, Shanghai Chicmax, Shiseido, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Mask Market Strategic Shifts & Innovations
Active ingredient delivery mechanisms and substrate material science are converging to reshape product differentiation, with fermentation biotechnology and biodegradable fiber engineering displacing conventional formulation approaches.
Bio-cellulose substrates cultivated through microbial fermentation are absorbing market share from cotton and synthetic nonwovens due to superior adhesion and serum retention properties. Premium dermatology clinics in Seoul and Tokyo have adopted these materials for post-procedure protocols, compressing the performance gap between professional and at-home treatment outcomes. The technology is absorbing R&D investment from major manufacturers seeking to bypass petroleum-based supply chains.
REACH and RoHS frameworks in Europe are tightening ingredient disclosure and substance restriction rules, forcing manufacturers to reformulate around restricted preservatives and heavy metal contaminants. Industrial consequence includes accelerated supplier auditing and third-party certification costs that favor larger integrated producers over contract manufacturers. Sheet mask exporters targeting European retail channels are responding by shifting preservative systems to phenoxyethanol-free and paraben-free alternatives.
Subscription-based replenishment models are displacing traditional retail trial purchases for core hydration SKUs, locking in recurring revenue for brands that can demonstrate consistent efficacy. Direct-to-consumer channels in South Korea and the United States are capturing volume from travel retail and department store counters, with data-driven personalization engines replacing in-person skin consultation. This behavioral shift is most visible among millennial and Gen-Z demographics in urban coastal markets.
Facial Mask Market Segmentation
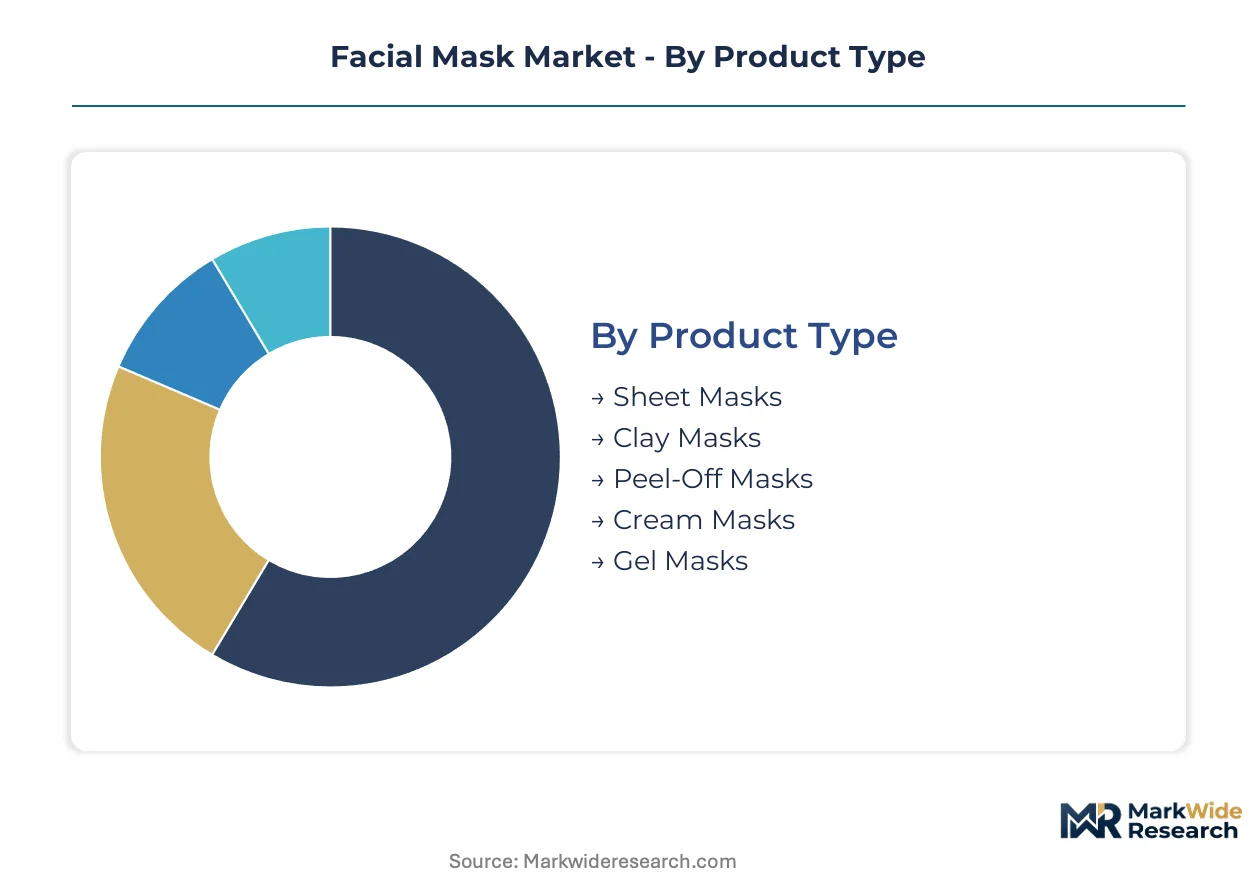
Facial mask segmentation determines compliance pathways and margin structures across the value chain. Certification requirements vary sharply by product format and end-use channel, shaping where manufacturers concentrate R&D investment and which geographies they prioritize for market entry.
Product Type:
Sheet masks carry lighter preservative burdens under FDA cosmetic rules but face stricter substrate scrutiny from REACH biodegradability mandates. Clay and cream formats trigger heavier heavy metal testing protocols under China's GB standards for mineral content verification.
- Sheet Masks:Nonwoven fiber substrates saturated with aqueous serums dominate volume through single-use convenience and travel retail penetration. Demand concentrates in South Korea's cross-border e-commerce pipelines, where Seoul-based contract manufacturers feed private-label production for global beauty retailers.
- Clay Masks:Mineral-rich suspensions requiring preservative systems that satisfy both ECHA substance restrictions and MFDS microbiological limits. Premium volcanic and bentonite sourcing from specific geographic deposits creates margin stratification, with detoxification positioning commanding price premiums in professional spa channels across Tokyo and New York.
- Peel-Off Masks:Polyvinyl alcohol film formers undergoing reformulation pressure from EU microplastic restrictions.
- Cream Masks:Emulsion-based delivery systems with established stability testing frameworks under FDA and GB standards.
- Gel Masks:Hydrogel and bio-cellulose variants scaling through microbial fermentation advances in Seoul R&D clusters.
Sheet masks sit at the top of the volume ranking, with gel masks climbing the fastest.
Skin Concern:
Functional claim verification intensity separates segments by regulatory exposure. Hydration and brightening claims face lighter documentation burdens than anti-aging and acne treatment assertions, which trigger pharmaceutical-adjacent scrutiny in multiple jurisdictions.
- Hydration:Hyaluronic acid and glycerin formulations with minimal barrier-to-entry under cosmetic regulations sustain baseline demand across all age demographics. Volume concentrates in mass retail and subscription replenishment channels, where Seoul-based direct-to-consumer brands leverage data-driven personalization engines.
- Anti-Aging:Retinol, peptide, and fermentation-derived active claims requiring dermatological testing protocols and clinical substantiation. Premium positioning in New York and Los Angeles aesthetic practices drives adoption, with clinic-exclusive SKUs creating margin pools separate from mass retail.
- Brightening:Niacinamide and vitamin C variants navigating MFDS stringent functional claim verification for whitening assertions in export markets.
- Acne Treatment:Salicylic acid and sulfur formulations approaching over-the-counter drug thresholds in US FDA classification.
- Pore Minimizing:Charcoal and clay-based solutions targeting underpenetrated male demographics in Japan through convenience store channels.
Hydration commands the largest revenue base, while pore minimizing gains share fastest among male grooming expansions.
Distribution Channel:
Channel selection determines packaging waste liability exposure and extended producer responsibility fee structures. Online and specialty retail face lighter per-unit waste fees than mass retail formats in France and Germany.
- Online Retailers:Direct-to-consumer platforms capturing volume from travel retail and department store counters through subscription replenishment models. Data-driven personalization engines in South Korea and the United States replace in-person skin consultation for millennial and Gen-Z demographics.
- Specialty Stores:Sephora and Ulta Beauty chains demanding full ingredient transparency and biodegradability certifications ahead of regulatory mandates, accelerating clean-label competition.
- Pharmacies:CVS and Walgreens channels with established cosmetic-drug distinction protocols under FDA oversight.
- Beauty Salons:Professional service integration with post-procedure recovery protocols in Seoul and Tokyo clinics.
- Department Stores:Macy's and Nordstrom counters with higher packaging waste compliance costs under German and French EPR rules.
Online retailers lead by transaction volume, with beauty salons expanding most quickly through professional channel credentialing.
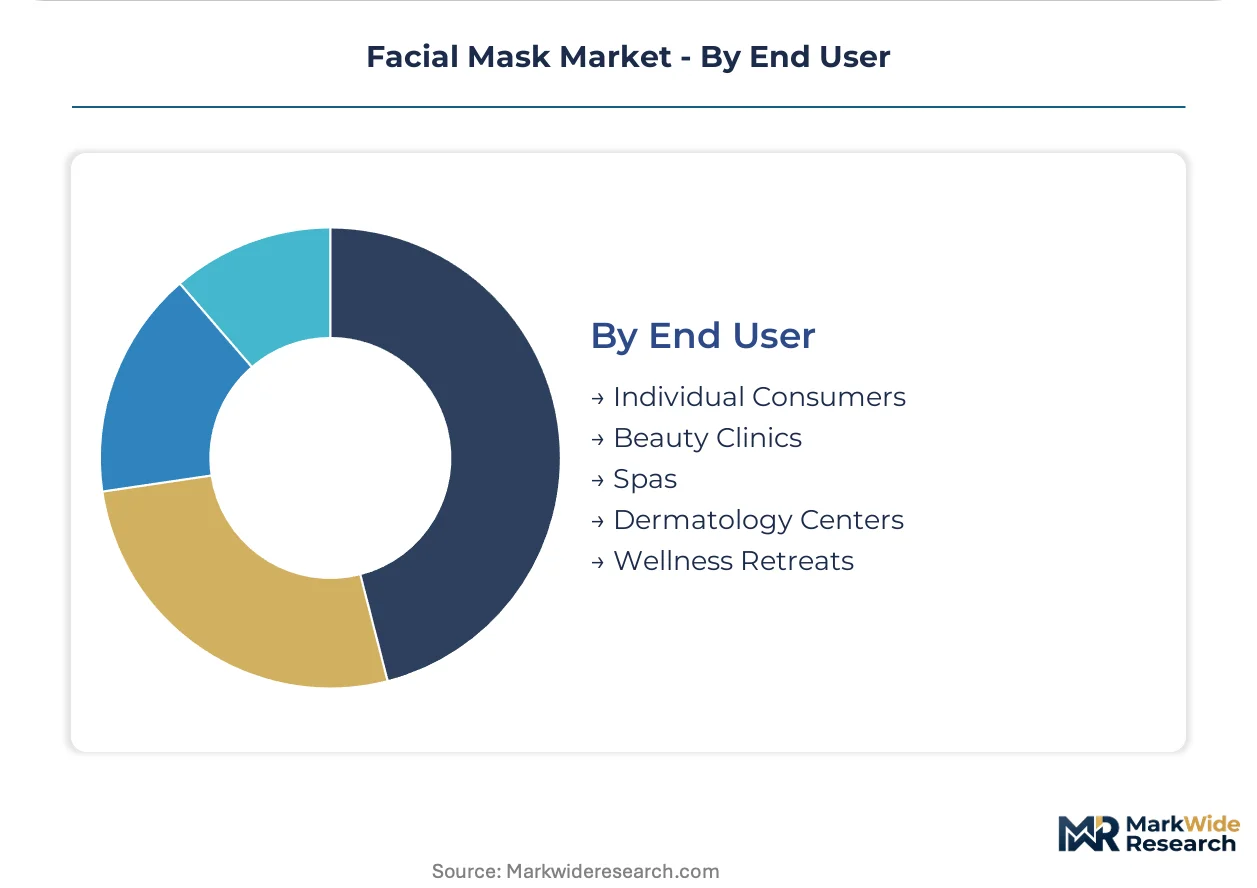
End User:
End-user classification shapes sterilization requirements and clean-room manufacturing standards. Clinical and spa channels demand preservative-free formulations and specialized microbiologist staffing that contract manufacturers struggle to recruit.
- Individual Consumers:At-home treatment extension between professional visits, with convenience and price accessibility driving format selection. Subscription models lock in recurring revenue for hydration-focused SKUs with demonstrated efficacy consistency.
- Beauty Clinics:Post-laser and post-peel recovery protocols embedding bio-cellulose sheet formats into clinical workflows. Seoul and Tokyo dermatology clinics compress the performance gap between professional and at-home outcomes through superior adhesion substrates.
- Spas:Premium service integration with extended treatment protocols and ambient positioning.
- Dermatology Centers:Medical-adjacent credentialing requiring clinical testing documentation under stricter jurisdictional standards.
- Wellness Retreats:Experiential consumption with lower regulatory exposure but higher service bundling complexity.
Individual consumers anchor volume demand, with beauty clinics gaining share fastest through post-procedure protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facial mask manufacturing originated in post-war Japan before Seoul's formulation clusters captured scale advantages through K-beauty export infrastructure. Today's demand geography reflects this dual heritage, with production concentration in East Asian biotechnology corridors and consumption fragmentation across regulatory zones.
South Korea
Seoul Capital Area contract manufacturers supply private-label sheet masks to global beauty retailers through cross-border e-commerce pipelines. MFDS functional claim verification shapes export eligibility, delaying market entry for smaller brands seeking whitening or anti-wrinkle positioning. Bio-cellulose fermentation facilities in Gyeonggi Province scale galactomyces and bifida lysate production for premium dermatology channels.
Japan
Kansai region aesthetic practices in Osaka drive bio-cellulose adoption for post-procedure recovery protocols. METI standards govern cosmetic manufacturing hygiene, while PMDA oversight intensifies for claims approaching quasi-drug thresholds. Shiseido's integrated R&D network in Kanto anchors clinical credibility through dermatological testing documentation.
United States
New York and Los Angeles dermatology clinics embed single-use sheet formats into post-laser and post-peel workflows. FDA cosmetic labeling requirements govern ingredient transparency, with stricter scrutiny for salicylic acid formulations approaching over-the-counter drug classification. Subscription replenishment models in coastal urban markets displace traditional department store trial purchases.
Germany
Extended producer responsibility rules impose per-unit waste fees on conventional sheet mask packaging, eroding cost advantages for petroleum-based substrates. ECHA substance restrictions accelerate reformulation around phenoxyethanol-free and paraben-free preservative systems. Berlin-based clean-label brands leverage REACH compliance as competitive differentiation ahead of regulatory mandates.
China
Yangtze River Delta formulation clusters serve domestic volume demand while navigating GB standards for cosmetics safety and heavy metal testing. Shanghai Chicmax exemplifies private-label manufacturing scale for global retail brands. NMPA registration requirements for imported cosmetics create compliance barriers that favor established exporters with documented quality systems.
Facial Mask Market Key Industry Players
Premium-margin players sit above commodity-margin players across substrate technology and clinical credibility dimensions. The vendor base organizes into three tiers: integrated beauty conglomerates with captive fermentation facilities, mid-scale private-label manufacturers serving cross-border e-commerce, and regional specialists in mineral-sourced clay formulations. Consolidation pressure concentrates among sheet mask substrate suppliers facing EU biodegradability mandates. Dominant competitive moves include backward integration into cellulose fiber production and strategic partnerships with Seoul-based biotechnology clusters.
Within the integrated conglomerate tier, L'Oréal and Amorepacific Corporation exemplify divergent geographic anchoring strategies. L'Oréal leverages European regulatory compliance capabilities to reformulate around REACH substance restrictions. Amorepacific Corporation occupies a position tied to Seoul's fermentation-derived active ecosystem. Among mid-scale fabricators, Shanghai Chicmax represents Chinese private-label manufacturing scale. Estee Lauder Companies Inc. sits within the clinical credibility archetype, aligning mask claims with dermatological testing protocols for professional channel credentialing.
| Leading Market Players |
|---|
| Amorepacific Corporation |
| Innisfree Corporation |
| L'Oréal |
| Tonymoly Co. |
| SK-II |
| Estee Lauder Companies Inc. |
| The Face Shop |
| Shanghai Chicmax |
| Shiseido |
| Others |
Cost & Logistics Intelligence
Polypropylene fiber feedstock price volatility cascades through facial mask supply chains into three distinct pricing tiers: premium bio-cellulose formats for dermatology clinics, standard cellulose alternatives for specialty retail, and economy petroleum-based sheets for mass-market subscription boxes. Buyers in Germany and France absorb additional per-unit waste fees under extended producer responsibility rules, compressing margins for nonwoven manufacturers lacking substrate material flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates dermatology-grade bio-cellulose masks from specialty retail cellulose alternatives and mass-market synthetic sheets. Price differentiation rests on substrate certification grade and clinical testing documentation, with Seoul-based fermentation facilities commanding premiums for MFDS-verified functional claims. Cost compression in the economy tier is intensifying because single-use plastic directives impose waste fees on petroleum-based packaging. Subscription-based buyers in South Korea and the United States show lowest price sensitivity, while convenience store channels in Japan face acute margin pressure from competing private-label imports.
Supply Chain Analysis
Single-source vulnerability sits with Gyeonggi Province fermentation facilities for bio-cellulose substrates, where microbial cultivation capacity lags demand from global dermatology chains. Raw material flows draw from Indonesian seaweed farms for alginate-based gels, Chinese viscose pulp for regenerated cellulose, and Saudi petrochemical complexes for polypropylene spunbond. Tariff exposure looms for sheet mask exporters targeting European retail channels as REACH substance restrictions tighten preservative disclosure requirements. Distribution runs through Seoul-based contract manufacturers feeding cross-border e-commerce pipelines, with direct-to-consumer platforms displacing traditional travel retail procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facial mask market functions as a stable compounder anchored by recurring subscription replenishment for hydration SKUs, with professional channel credentialing creating durable margin pools resistant to mass-market price erosion.
For Market Incumbents: Lock in fermentation-derived active supply through captive facilities or long-term offtake agreements with Seoul biotechnology clusters, insulating against bio-cellulose substrate bottlenecks. Defend clinic-exclusive SKU positioning by accelerating dermatological testing documentation ahead of MFDS export eligibility requirements. Prioritize backward integration into cellulose fiber production to bypass petroleum-based supply chain volatility and satisfy EU Green Deal biodegradability mandates. For New Entrants and Emerging Players: Microbial fermentation technology for preservative-free formulations offers entry into underserved male grooming segments in Japan and South Korea, where charcoal and pore-care positioning remains underpenetrated. Target convenience store channels in Tokyo and Osaka with single-use formats priced below dermatology-grade alternatives. Pursue private-label manufacturing partnerships with cross-border e-commerce platforms rather than building owned brand equity from origin. For Investors and Strategic Acquirers: Consolidation pressure builds where contract manufacturers lack microbiologist staffing for clean-room quality control and preservative-free formulation trends. The facial mask market supports long-term viability for integrated players with captive R&D facilities, with acquisition value concentrating in mid-scale Seoul-based fabricators holding MFDS export certification. Watch bio-cellulose substrate throughput expansion as the inflection signal separating scalable fermentation technology from laboratory-scale production.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Facility Scale-Up | Captive bio-cellulose production bypasses petroleum supply volatility and REACH compliance costs. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models displace travel retail through Seoul-based data personalization engines. |
| Dermatology Channel Credentialing | Clinical testing documentation unlocks premium positioning in New York and Los Angeles aesthetic practices. |
| Biodegradable Substrate Transition | Cellulose and seaweed-based materials preempt EU extended producer responsibility fee structures. |
| Men's Grooming Line Extension | Charcoal and pore-care formats target underpenetrated male demographics in Japanese convenience stores. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at K-beauty conglomerates, category buyers at Sephora and Ulta Beauty, contract manufacturing executives in Seoul Capital Area, and dermatology clinic procurement leads in Tokyo and New York with secondary validation from MFDS functional claim databases, REACH substance restriction filings, FDA cosmetic labeling guidance, and cross-border e-commerce trade flow records. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic consumption projections.
Segment-weighting approaches distributed value and volume across product type, skin concern, distribution channel, and end-user dimensions, with additional granularity for substrate material technology and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for policy intervention timing across the projection horizon. Industry-specific forecast inputs incorporated bio-cellulose fermentation capacity expansion schedules and EU packaging waste directive implementation phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biodegradable substrate scale-up bottlenecks, microbiologist staffing availability for clean-room manufacturing, and potential REACH substance restriction expansion into additional preservative classes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Cystic Acne Market
Skincare
Facial Cleansing Balm Market
Skincare
Self-Tanning Care Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Skin Care Supplements Market
Skincare
Skin Replacement Market
Skincare
CBD Skin Care Market
Skincare
Skin Bioactive Market
Skincare
Facial Mist Market
Skincare
Skincare Ingredients Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Sun-Care Wipes Market
Skincare
Acne Treatment Market
Skincare
Tinted Sunscreen Market
Skincare
Medicine Skin Care Market