
 Global Scar Removal Treatment Market | 2026-2036
Global Scar Removal Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scar Removal Treatment Market Foresight
Combination protocol bundling is repositioning buyer choice in scar removal, with clinics packaging fractional laser sessions with silicone sheets and topical creams into fixed-price treatment courses. Mölnlycke Health Care leverages its wound-care heritage to anchor silicone sheet supply across European hospital networks. Smith & Nephew sustains R&D intensity in advanced wound management, while Cynosure competes through specialized laser platforms for hypertrophic and keloid indications.
Scar removal treatment encompasses medical and aesthetic interventions designed to flatten, fade, or resurface fibrous tissue resulting from dermal injury, surgical incision, or inflammatory conditions. These modalities operate through collagen remodeling, melanin modulation, or controlled thermal injury at depths ranging from epidermal to deep dermal layers. Topical creams and silicone sheets occupy mature, high-volume positions with established reimbursement in post-surgical protocols, while laser devices capture expanding margin pools as fractional technology penetrates dermatology clinics. Injectable fillers represent the fastest-growing product category as hyaluronic acid formulations gain traction for atrophic acne scar correction.
FDA 510(k) clearance requirements govern laser device commercialization in the United States, while the EU MDR framework imposes clinical evidence standards for scar treatment devices marketed across Europe. The EPA regulates chemical peel formulations containing phenol or trichloroacetic acid concentrations above threshold levels, constraining home-use product availability. Stakeholders must monitor evolving MDR technical documentation requirements and FDA software-as-medical-device guidance for AI-powered treatment planning tools.
Market Dynamics
Fractional laser technology is compressing treatment timelines from months to weeks, forcing dermatology clinics to restructure service menus around combination protocols that bundle thermal devices with topical adjuncts.
Growth Catalysts
- EU MDR framework:The 2021 Medical Device Regulation imposes stricter clinical evidence standards for scar treatment devices, accelerating consolidation among manufacturers with robust documentation capabilities.
- Medspa chains:These retail healthcare operators are standardizing fractional laser protocols across multi-site networks, creating predictable demand for device OEMs and consumable suppliers.
- Hyaluronic acid fillers:This material is penetrating atrophic acne scar correction with minimally invasive injection techniques that bypass surgical downtime entirely.
Market Restraints
- Device cost structure:Fractional CO2 and erbium laser systems require capital outlays exceeding $100,000 per unit, constraining independent dermatology practice adoption.
- Supply concentration:High-purity silicone for medical-grade sheets concentrates among a limited set of chemical manufacturers, creating input vulnerability for sheet producers.
- Substitution threat:Microneedling devices and radiofrequency platforms are capturing price-sensitive patients who decline premium laser procedures.
Strategic Opportunities
- Brazil:ANVISA's streamlined medical device registration pathway for Class II laser systems is opening access to Latin America's largest aesthetic medicine market.
- Telemedicine integration:Remote consultation platforms are enabling pre-screening for scar severity and treatment candidacy, reducing no-show rates at brick-and-mortar clinics.
- AI-powered treatment planning:Software-as-medical-device guidance from FDA is creating regulatory clarity for machine learning tools that optimize laser parameters based on scar morphology.
Industry Challenges
- Laser operator certification:State-level medical board requirements for physician supervision vary dramatically, complicating staffing models for multi-state clinic operators.
- Integration complexity:Electronic health record systems lack standardized scar assessment coding, forcing manual documentation workflows that slow reimbursement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scar Removal Treatment Market |
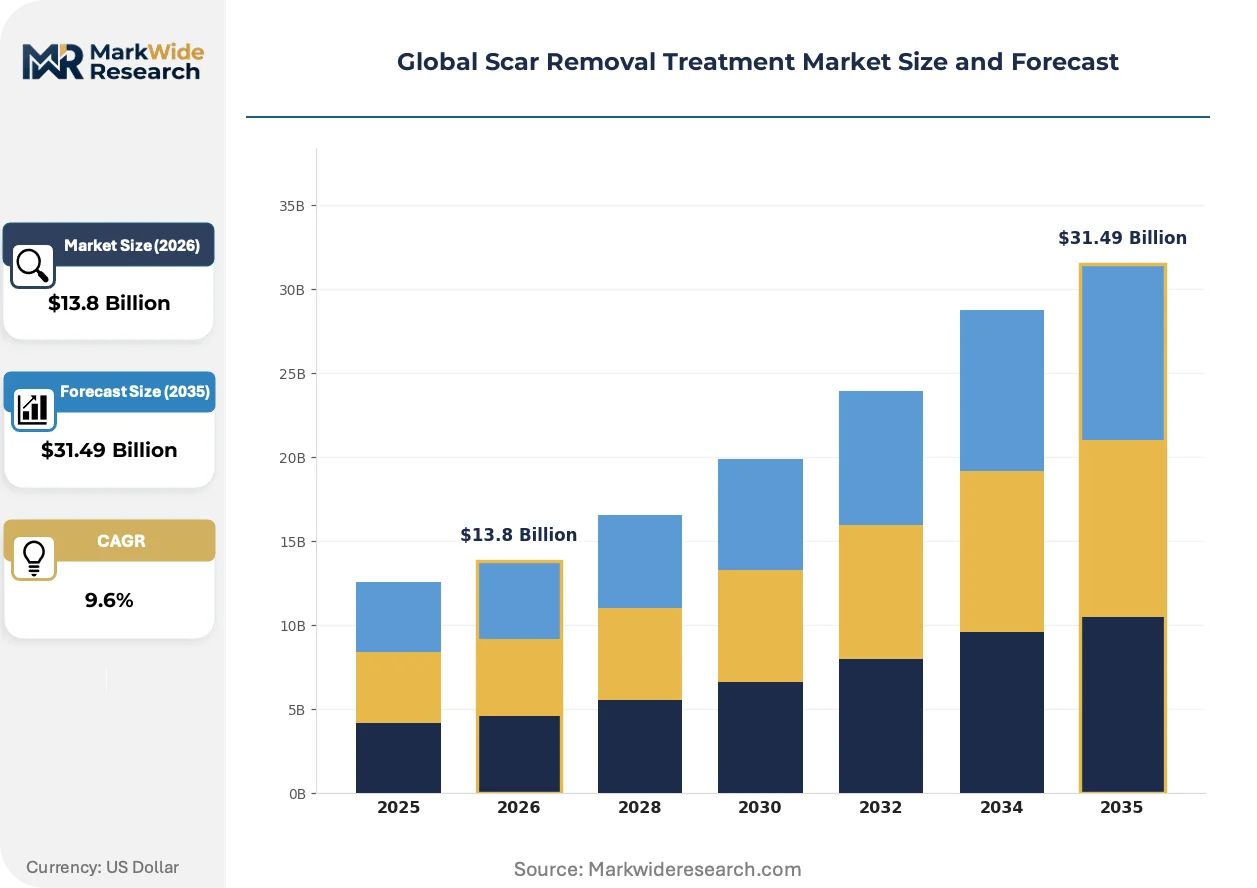
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $31.49 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Silicone Sheets, Laser Devices, Injectable Fillers, Chemical Peels Application: Post-Surgical, Acne Scars, Burn Scars, Injury Scars, Stretch Marks End User: Dermatology Clinics, Cosmetic Surgery Centers, Beauty Spas, Home Users, Pharmacies Treatment Technology: Fractional Laser, Microneedling, Cryotherapy, Radiofrequency, Ultrasound Therapy |
| Companies Covered | Sonoma Pharmaceuticals, Mölnlycke Health Care, Smith & Nephew, Suneva Medical, CCA Industries, Merz Pharma, Cynosure, Newmedical Technology, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scar Removal Treatment Market Shifts & Advancements
Device manufacturers are embedding predictive algorithms into treatment platforms while clinicians experiment with sequential multi-modality protocols. These shifts are compressing the gap between medical-grade outcomes and consumer-accessible procedures.
Picosecond laser technology is converging with fractional delivery systems to address post-inflammatory hyperpigmentation alongside textural irregularities. Dermatology clinics in South Korea and the United States are adopting these dual-wavelength platforms at accelerated replacement cycles. This convergence is collapsing the traditional separation between pigment-specific and resurfacing device categories.
FDA's evolving software-as-medical-device guidance is forcing laser OEMs to submit algorithmic treatment planning tools through 510(k) pathways previously reserved for hardware. The industrial consequence is extended product development timelines and elevated regulatory compliance costs. Fractional laser systems with embedded AI are experiencing the most pronounced approval delays.
Patients are demanding fixed-price treatment courses rather than per-session billing, pressuring clinics to absorb outcome variability risk. Medspa chains are responding with subscription models that bundle silicone sheets and topical retinoids into prepaid packages. This behavioral shift is most visible in the United States, where cosmetic procedure financing platforms enable multi-thousand-dollar commitment at point of consultation.
Global Scar Removal Treatment Market Segmentation
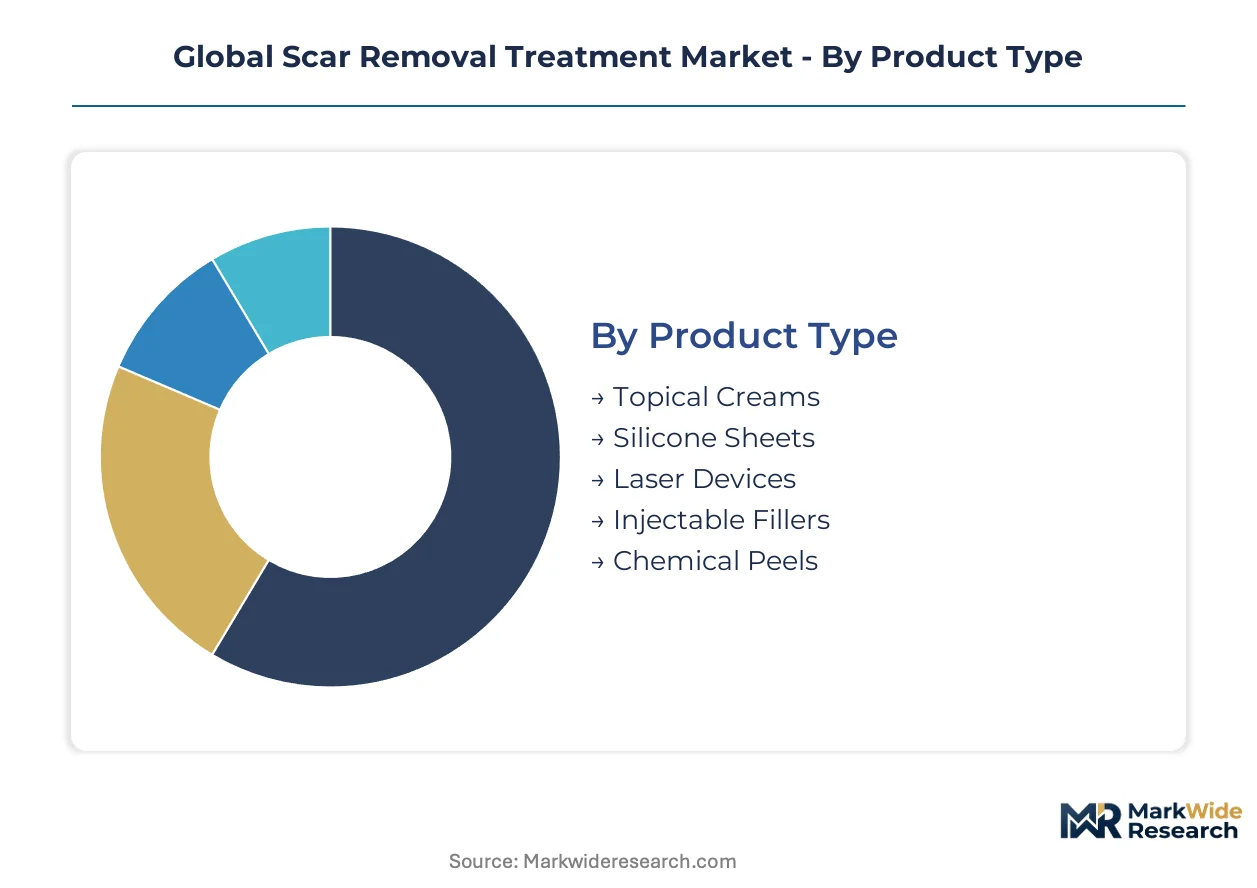
Scar removal treatment markets fragment across capital intensity, clinical setting, and technology maturity. Understanding segment boundaries reveals where margin pools concentrate versus where volume commoditization pressures pricing.
Product Type:
Laser devices demand the steepest upfront capital deployment, with fractional CO2 platforms exceeding six-figure acquisition costs and requiring dedicated procedure rooms.
- Laser Devices:Fractional and ablative systems deliver controlled thermal injury for collagen remodeling. Dermatology clinics in the United States and South Korea are replacing legacy platforms at accelerated cycles as dual-wavelength capabilities converge pigment and texture correction.
- Injectable Fillers:Hyaluronic acid formulations address atrophic acne scars through minimally invasive subcision and volumization. Cosmetic surgery centers in Brazil and the United States are expanding injection service menus to capture patients bypassing surgical downtime.
- Topical Creams:Retinoid and silicone-based formulations occupy mature, pharmacy-distributed channels with established post-surgical reimbursement protocols.
- Silicone Sheets:Medical-grade polymer sheets apply sustained pressure and hydration for hypertrophic scar management, dominating hospital procurement in Europe.
- Chemical Peels:Phenol and trichloroacetic acid solutions target superficial textural irregularities, constrained by EPA concentration thresholds for home-use availability.
Laser devices absorb the bulk of installed capacity; injectable fillers are expanding most quickly.
Application:
Acne scar correction commands premium pricing per square centimeter treated, while post-surgical protocols drive recurring volume through standardized hospital discharge bundles.
- Post-Surgical:Sternotomy, cesarean, and orthopedic incision scars trigger immediate silicone sheet and topical cream deployment. Hospital networks in Germany and Japan specify scar management in bundled payment protocols.
- Acne Scars:Atrophic and hypertrophic facial scarring drives demand for combination laser-injection protocols. Medspa chains across the United States are packaging fractional sessions with hyaluronic acid into prepaid courses.
- Burn Scars:Contracture and hypertrophic formations require specialized pressure garment and laser intervention, concentrated in tertiary burn centers.
- Injury Scars:Traumatic laceration outcomes vary by depth and anatomical location, fragmenting treatment selection across topical, laser, and surgical revision.
- Stretch Marks:Striae distensae respond variably to fractional laser and microneedling, with demand clustering in cosmetic surgery centers serving postpartum populations.
Post-surgical applications anchor volume throughput; acne scar correction delivers the steepest expansion trajectory.
End User:
Dermatology clinics capture the highest procedure margins through device ownership and physician-administered protocols, while home-use channels face regulatory compression on active ingredient concentrations.
- Dermatology Clinics:Physician-supervised settings deploy full-spectrum laser, injection, and combination protocols. FDA 510(k) clearance requirements for fractional systems shape equipment procurement timelines in the United States.
- Cosmetic Surgery Centers:Plastic surgery practices integrate scar revision into comprehensive aesthetic service menus, leveraging operating room infrastructure for complex cases.
- Beauty Spas:Non-medical operators are limited to superficial peels and microneedling in most jurisdictions, with state medical board supervision rules constraining service scope.
- Home Users:Direct-to-consumer silicone sheets and retinoid creams dominate this channel, though EPA and FDA restrictions on phenol and acid concentrations limit efficacy claims.
- Pharmacies:Retail and hospital pharmacy networks distribute post-surgical scar management kits, with reimbursement driving volume in European and Japanese markets.
Dermatology clinics command the deepest procedure mix; cosmetic surgery centers are gaining share fastest through bundled aesthetic packages.
Treatment Technology:
Fractional laser platforms require the most substantial facility investment and regulatory documentation, while microneedling and cryotherapy offer lower barriers to entry for independent practices.
- Fractional Laser:Ablative and non-ablative systems create microscopic thermal zones for collagen induction. EU MDR technical documentation requirements are extending development timelines for OEMs seeking European market access.
- Microneedling:Percutaneous collagen induction devices penetrate at controlled depths, capturing price-sensitive patients who decline premium laser procedures in the United States and Brazil.
- Cryotherapy:Liquid nitrogen application flattens keloid and hypertrophic scars through controlled tissue necrosis, concentrated in dermatology practices with existing lesion removal capabilities.
- Radiofrequency:Thermal energy delivery through microneedle or surface applicators targets dermal remodeling without epidermal disruption, expanding in Asian aesthetic medicine markets.
- Ultrasound Therapy:Microfocused and high-intensity platforms stimulate neocollagenesis, with adoption constrained by limited scar-specific clinical evidence relative to facial lifting applications.
Fractional laser dominates installed base value; microneedling is climbing the fastest on capital accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters in Germany and the United States supply fractional laser systems worldwide, while consumption concentrates in cosmetic surgery centers across South Korea, Brazil, and the United Arab Emirates. Regulatory divergence between FDA 510(k) pathways and EU MDR technical documentation requirements fragments product launch timelines.
United States
Cosmetic surgery centers in Los Angeles and Miami drive premium procedure volumes for acne scar correction. FDA 510(k) clearance requirements for fractional laser systems shape equipment procurement cycles at dermatology clinics. Medspa chains across Texas and Florida standardize combination protocols bundling thermal devices with silicone sheets.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia specify scar management in bundled payment protocols for post-surgical patients. EU MDR clinical evidence standards extend development timelines for device manufacturers seeking European market access. Mölnlycke Health Care anchors silicone sheet supply across German hospital procurement systems.
Brazil
Cosmetic surgery centers in São Paulo and Rio de Janeiro expand injection service menus for atrophic acne scar correction. ANVISA's streamlined Class II laser registration pathway accelerates device market entry for international OEMs. Hyaluronic acid filler demand concentrates in clinics serving price-sensitive patients bypassing surgical downtime.
South Korea
Dermatology clinics in Seoul and Busan adopt dual-wavelength fractional platforms at accelerated replacement cycles. MFDS regulates medical device software embedded in AI-powered treatment planning tools. Picosecond laser convergence with fractional delivery addresses post-inflammatory hyperpigmentation alongside textural irregularities.
United Arab Emirates
Medical tourism flows into Dubai and Abu Dhabi cosmetic surgery centers drive demand for premium scar revision procedures. MOHAP registration requirements for laser devices align with international standards while permitting faster commercialization than European timelines. Medspa chains target Gulf nationals with fixed-price treatment courses bundling multiple modalities.
Global Scar Removal Treatment Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with wound-care heritage. Market concentration remains moderate, with no single participant commanding dominant share across all product categories. Three archetypes define positioning: wound-management specialists with silicone sheet manufacturing depth, laser platform OEMs with dermatology clinic relationships, and pharmaceutical firms with topical formulation pipelines. Consolidation activity centers on vertical integration of consumable supply chains and technology licensing agreements for AI-powered treatment planning.
Among wound-care specialists, Mölnlycke Health Care and Smith & Nephew occupy positions anchored by hospital procurement relationships and post-surgical protocol integration. Cynosure exemplifies the laser platform archetype, competing through specialized hardware for hypertrophic and keloid indications. These three entities represent distinct strategic postures: consumable supply chain control, capital equipment innovation, and clinical outcome bundling.
| Leading Market Players |
|---|
| Sonoma Pharmaceuticals |
| Mölnlycke Health Care |
| Smith & Nephew |
| Suneva Medical |
| CCA Industries |
| Merz Pharma |
| Cynosure |
| Newmedical Technology |
| Lumenis |
| Others |
Supply & Pricing Matrix
Fixed-price treatment course preferences from United States medspa chains and Brazilian cosmetic surgery centers are forcing device OEMs to absorb outcome variability risk through prepaid bundling structures, compressing per-session revenue realization and shifting margin capture toward consumable supply chains.
Pricing Analysis
Margin tightening in fractional laser systems reflects capital intensity exceeding six figures per unit plus consumable attachment requirements. Three-tier pricing structure across premium dual-wavelength platforms, standard single-modality systems, and economy refurbished equipment segments the installed base. Cost-down pressure on silicone sheets accelerates because hospital procurement in Germany and Japan demands volume discounts for bundled post-surgical protocols. Home-use topical channels exhibit highest price sensitivity; dermatology clinic direct purchases show lowest.
Supply Chain Analysis
Direct-to-clinic channels handle capital equipment demand from United States and South Korean dermatology networks. High-purity silicone feedstock concentrates in Germany, Japan, and United States chemical manufacturing bases. Laser device assembly draws from precision optics clusters in Germany and semiconductor component suppliers in South Korea. Single-source vulnerability sits with medical-grade polymer resin suppliers serving European sheet manufacturers. Distribution runs through hospital procurement systems, GPO contracts, and medspa chain central purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractional laser technology with embedded AI treatment planning is displacing legacy ablative platforms, compressing replacement cycles and reshaping competitive positioning around software-hardware integration rather than pure hardware specifications.
For Market Incumbents: Extend consumable attachment strategies to lock in recurring revenue streams as capital equipment sales plateau. Secure backward integration into high-purity silicone supply to defend against raw material concentration risk. Invest in FDA 510(k) documentation capabilities ahead of evolving software-as-medical-device guidance. Counter microneedling substitution threat through combination protocol bundling with topical adjuncts. For New Entrants and Emerging Players: Medspa chain central purchasing departments represent the most penetrable channel for fractional laser OEMs lacking established dermatology relationships. Target Brazil's ANVISA-streamlined Class II registration pathway for faster market entry than EU MDR timelines permit. Focus initial commercialization on atrophic acne scar correction applications where hyaluronic acid filler demand outstrips established supply. Pursue white-label manufacturing partnerships with wound-care specialists seeking laser platform complements. For Investors and Strategic Acquirers: Re-rating potential sits with AI-embedded treatment planning software developers given FDA regulatory clarity creation and dermatology clinic workflow integration demand. Long-term viability centers on participants controlling both hardware installed base and consumable attachment revenue across the analysis window. Target acquisition archetype: mid-cap laser OEMs with established 510(k) portfolios but underdeveloped software capabilities. Signal to watch: accelerated replacement cycles in South Korean clinics indicating technology convergence acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Treatment Planning Development | FDA software-as-medical-device guidance creates regulatory pathway clarity for algorithmic laser parameter optimization. |
| Combination Protocol Bundling | Medspa chains in Texas and Florida standardize fractional laser plus silicone sheet prepaid courses. |
| ANVISA Registration Acceleration | Brazil's streamlined Class II laser pathway opens Latin America's largest aesthetic medicine market faster than EU MDR. |
| Silicone Sheet Supply Integration | Mölnlycke Health Care and Smith & Nephew anchor European hospital procurement through post-surgical protocol integration. |
| Telemedicine Pre-Screening Platforms | Remote consultation tools reduce no-show rates at brick-and-mortar dermatology clinics across United States networks. |
Research Methodology
Trade publications, FDA 510(k) clearance databases, and EU MDR technical documentation registries formed the secondary backbone, cross-referenced against primary interviews with dermatology clinic operators, biomedical equipment procurement managers, GPO contracts specialists, and laser device OEM product directors. Bottom-up and top-down triangulation validated installed base estimates and procedure volume assumptions across geographic clusters.
Bottom-up modeling segmented demand across product type, application, end user, and treatment technology dimensions, with value outputs reflecting equipment pricing, consumable attachment rates, and procedure reimbursement levels throughout the forecast period. CAGRs derived from regression analysis against historical replacement cycles and technology penetration curves. Forecast inputs incorporated ANVISA registration timelines, EU MDR documentation requirements, and medspa chain expansion trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, raw material supply disruptions, and macroeconomic impacts on elective procedure demand. Forecasts reflect documented assumptions regarding technology adoption rates and pricing stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Global Anti-Aging Products and Services Market
Skincare
Algae Skincare Products Market
Skincare
Dermal Regeneration Market
Skincare
Skincare Ingredients Market
Skincare
Incontinence Skin Care Products Market
Skincare
United Kingdom Skincare Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Skin Replacement Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Retinol Skincare Product Market
Skincare
Mineral Sunscreen Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Cystic Acne Market
Skincare
Retinoids Market
Skincare
ASEAN Sensitive Skin Care Market