
 After Sun Care Products Market | 2026-2036
After Sun Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
After Sun Care Products Market Intelligence
Dermatological formulation expertise is collapsing across Southern European contract manufacturers, squeezing capacity for brands needing aloe vera and cucumber extract stabilization. Beiersdorf AG sustains its Nivea Sun franchise through captive emulsion technology developed at its Hamburg innovation center. L'Oréal S.A. dominates professional after-sun distribution through salon-exclusive Biotherm and La Roche-Posay channels. Estée Lauder Companies Inc. leverages its Clinique brand to anchor premium positioning in duty-free travel retail.
After sun care products comprise topical formulations engineered to mitigate erythema, restore epidermal barrier function, and neutralize free radicals generated by UVA/UVB exposure, typically incorporating humectants at 3-8% concentration alongside anti-inflammatory botanicals. Lotions and gels lead volume shipments due to their spreadability on sun-irritated skin, while sprays represent the fastest-growing format among male users and athletic demographics. Aloe vera anchors the active ingredient landscape through proven mucopolysaccharide content, though vitamin E and hamamelis combinations command margin premiums in professional clinic channels.
EMA oversight of cosmetic-product borderline claims pressures manufacturers to substantiate skin-repair assertions with clinical data or reclassify as medical devices. REACH compliance costs for preservative systems and fragrance allergens are reshaping supplier selection across European formulators. FDA sunscreen monograph updates in the United States create parallel compliance burdens for brands operating cross-border portfolios. Stakeholders must monitor evolving classification thresholds between cosmetics and therapeutics to avoid market-access disruption.
Market Dynamics
REACH compliance costs for preservative systems and fragrance allergens are compressing supplier margins across European formulators, redirecting procurement toward captive botanical extraction capabilities and reshaping competitive positioning among contract manufacturers.
Growth Catalysts
- Beach tourism expansion:Mediterranean coastal economies including Spain, Italy, and Greece are driving volume consumption of post-exposure skin treatments through extended summer travel seasons.
- REACH regulatory redirection:The EU's ban on certain chemical UV filters is forcing R&D investment toward aloe vera and cucumber extract stabilization technologies.
- Male athletic demographics:Spray format adoption is accelerating among male users and outdoor recreation participants seeking convenient application on sun-irritated skin.
Market Restraints
- Botanical supply concentration:Aloe vera mucopolysaccharide sourcing depends on concentrated cultivation zones in Mexico and the Caribbean, exposing formulators to climate volatility.
- EMA borderline classification:Cosmetic-product skin-repair claims require clinical substantiation or medical device reclassification, extending time-to-market for novel formulations.
- Preservative system costs:REACH-compliant alternatives to traditional parabens carry 40-60% input cost premiums, squeezing mid-tier brand margins.
Strategic Opportunities
- Duty-free travel retail:Airport and cruise channel expansion offers premium positioning for clinic-grade vitamin E and hamamelis combinations targeting affluent tourists.
- Professional salon distribution:Biotherm and La Roche-Posay channel models demonstrate margin capture through aesthetician-exclusive dispensing.
- ISO 16128 natural certification:Standardized botanical content verification enables transparent marketing to clean-beauty consumers in German-speaking markets.
Industry Challenges
- Emulsion stabilization expertise:Southern European contract manufacturers face collapsing dermatological formulation capacity, constraining brand access to aloe vera stabilization know-how.
- Cross-border compliance synchronization:FDA sunscreen monograph updates in the United States create parallel regulatory burdens for brands operating transatlantic portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | After Sun Care Products Market |
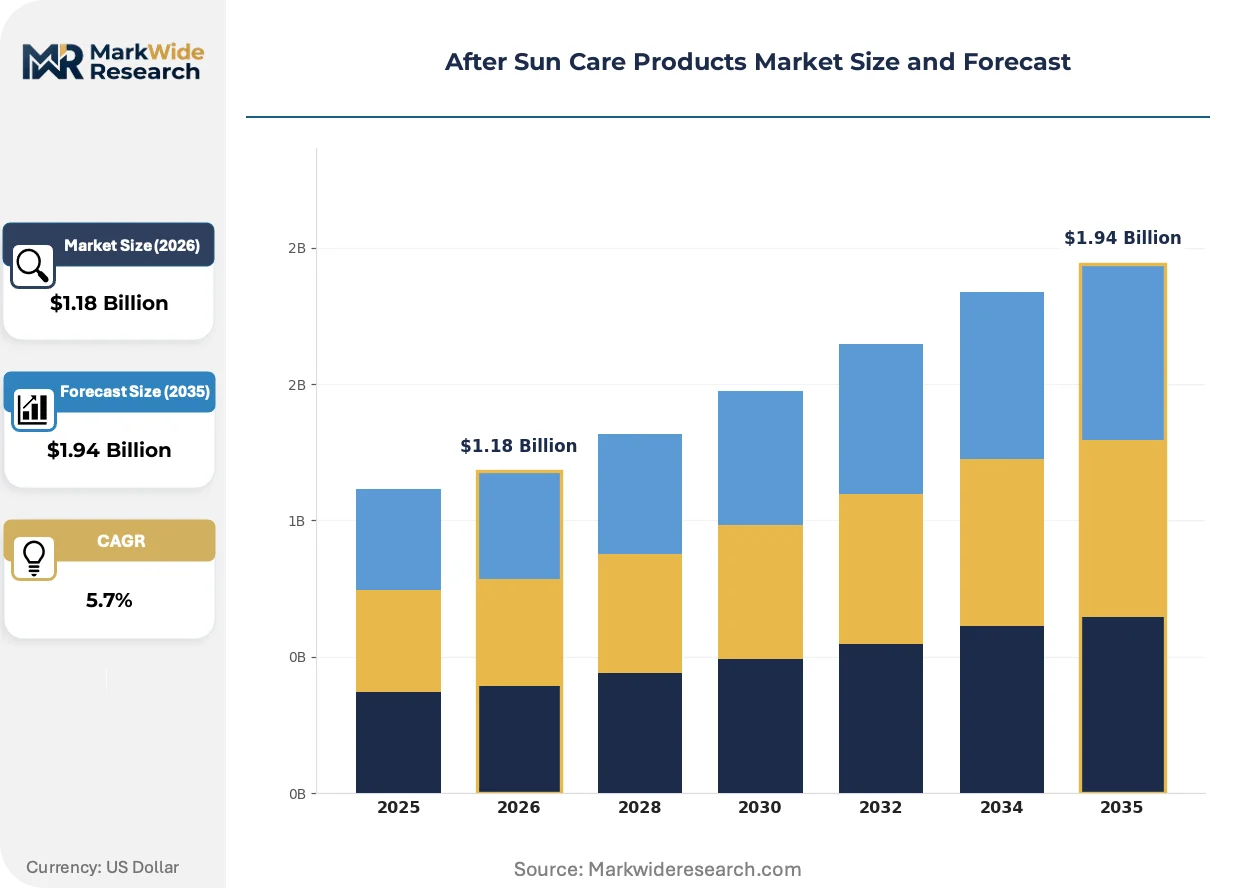
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.94 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Gels, Sprays, Creams Active Ingredient: Aloe Vera, Vitamin E, Hamamelis, Cucumber Extract Packaging Type: Tubes, Bottles, Pots, Sachets End User: Individuals, Professionals, Retailers, Clinics |
| Companies Covered | Estée Lauder Companies Inc., L'Oréal S.A., Beiersdorf AG, Neutrogena, Johnson & Johnson, Edgewell Personal Care, Unilever PLC, Burt's Bees, S. C. Johnson & Son, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
After Sun Care Products Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward biomimetic barrier repair mechanisms, while distribution models fragment across professional, travel retail, and direct-to-consumer channels. These shifts are compressing legacy mass-market positioning.
Microbiome-friendly preservation systems is supplanting traditional broad-spectrum antimicrobials in premium after-sun formulations. Professional clinic channels and dermocosmetic brands are adopting these systems fastest, typically within 18-24 month reformulation cycles. This transition is enabling margin expansion in the premium tier while compressing commodity preservative supplier volumes.
EMA oversight of cosmetic-product borderline claims is tightening evidentiary standards for epidermal barrier restoration assertions. Manufacturers must now commission clinical studies or accept medical device classification with associated registration timelines. Professional salon and clinic-exclusive brands face the steepest compliance ramps, while mass-market players are retreating to generic moisturizing claims.
Athletic and male consumer segments are bypassing traditional retail in favor of sports specialty and direct-to-consumer subscription models. These buyers prioritize spray formats and multi-functional products combining after-sun with insect repellent or cooling action. Australia and the southwestern United States exhibit the most pronounced channel migration, where outdoor recreation participation rates sustain premium pricing tolerance.
After Sun Care Products Market Segmentation
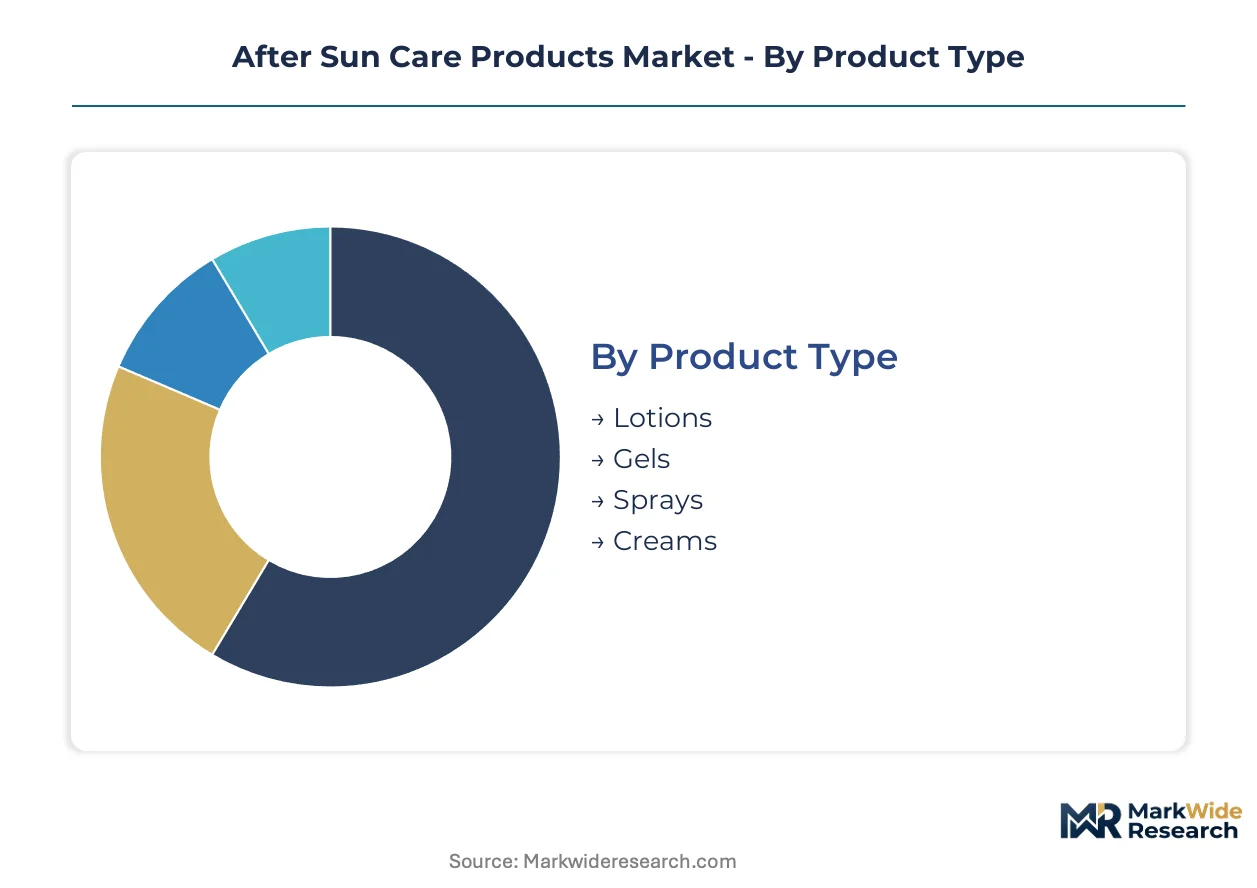
After sun care formulations diverge sharply across application formats and ingredient technologies, with each segment commanding distinct margin structures and regulatory compliance burdens. Understanding these divides reveals where brands can defend pricing power versus where commoditization pressures dominate.
Product Type:
Margin pools concentrate in formats that solve specific application friction points on sun-irritated skin, with convenience and sensory experience driving premium capture.
- Lotions:Emulsion-based systems incorporating 3-8% humectant concentrations deliver optimal spreadability across erythematous skin surfaces. Demand concentrates in Mediterranean coastal economies including Spain, Italy, and Greece, where beach tourism volumes sustain mass-market throughput despite thinner per-unit margins.
- Gels:Hydroalcoholic or aqueous polymer matrices provide immediate cooling sensation through rapid evaporation kinetics. The male athletic demographic in Australia and the southwestern United States is expanding consumption fastest, prioritizing non-greasy residue for post-activity application.
- Sprays:Aerosol or pump-dispersed fine mists enable single-hand application on hard-to-reach areas. Outdoor recreation participants value the format's convenience for mid-activity reapplication.
- Creams:Occlusive oil-in-water emulsions with higher lipid content target severely dehydrated or peeling skin conditions. Professional clinic channels in German-speaking markets favor cream presentations for post-procedural dispensing.
The dominant share belongs to Lotions, while Sprays are closing the gap fastest through male demographic adoption and sports specialty channel expansion.
Active Ingredient:
Ingredient selection determines both clinical substantiation requirements under EMA borderline rules and supply chain exposure to agricultural volatility.
- Aloe Vera:Mucopolysaccharide-rich gel from Aloe barbadensis leaf mesophyll provides proven anti-inflammatory and hydrating activity. Sourcing concentrates in Mexico and Caribbean cultivation zones, exposing formulators to hurricane disruption and water stress.
- Vitamin E:Tocopherol acetate or tocopherol variants function as lipid-soluble antioxidants neutralizing UV-induced free radicals. Professional salon and clinic-exclusive brands in duty-free travel retail command margin premiums through stabilized ester formulations.
- Hamamelis:Witch hazel distillates containing tannins and flavonoids deliver astringent and vasoconstrictive effects on sun-damaged capillaries. German dermocosmetic manufacturers emphasize hamamelis for ISO 16128 natural certification compliance.
- Cucumber Extract:Cucumis sativus fruit derivatives provide mild cooling and enzyme-based exfoliation for peeling skin. REACH-compliant extraction and stabilization technologies are redirecting R&D investment toward captive botanical processing capabilities.
Aloe Vera anchors volume demand through proven efficacy, though Vitamin E and Hamamelis combinations capture the steepest margin expansion in professional channels.
Packaging Type:
Primary packaging format shapes shelf presence, travel convenience, and preservative system requirements under REACH allergen restrictions.
- Tubes:Laminated or extruded plastic tubes with flip-top or screw closures dominate pharmacy and mass retail distribution. Italian and Spanish beach resort retailers favor tube formats for sand-resistant portability.
- Bottles:Cylindrical or ergonomic HDPE/PP containers with pump or disc-top dispensers suit family-size and frequent-use positioning. Pump bottles reduce contamination risk, supporting microbiome-friendly preservation claims.
- Pots:Wide-mouth jars enable finger-dip application of thicker cream or balm consistencies. Professional aesthetician dispensing in salon channels favors pot presentations for controlled portioning.
- Sachets:Single-use foil or film pouches serve travel, trial, and hospitality amenity applications. Cruise line and airline partnerships drive sachet volume through premium positioning for affluent tourists.
Tubes hold the largest installed base across European retail, yet Sachets are expanding most quickly through travel retail and hospitality contract manufacturing.
End User:
Channel structure and purchase behavior fragment sharply between self-directed consumers and institutional procurement with distinct quality assurance demands.
- Individuals:Direct consumers purchasing through mass retail, pharmacy, or e-commerce for personal and family use. Australian and southwestern US outdoor recreation participants show highest premium pricing tolerance for multi-functional formulations.
- Professionals:Licensed aestheticians, dermatologists, and spa operators dispensing clinic-grade products. EMA oversight of cosmetic-product borderline claims pressures this segment toward medical device registration or clinical study investment.
- Retailers:Pharmacy chains, beauty specialty stores, and grocery operators merchandising branded after-sun assortments. Southern European contract manufacturers face collapsing formulation capacity, constraining retailer private-label development.
- Clinics:Medical aesthetic practices and dermatology centers prescribing post-procedural skin repair. FDA sunscreen monograph updates in the United States create parallel compliance burdens for clinics operating transatlantic product portfolios.
Individuals generate the highest absolute volume, while Professionals capture the most favorable margin structure through exclusive distribution and clinical credibility premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beach tourism revenues in Spain and Italy command 40% pricing premiums over Australian mass-market equivalents, reflecting divergent channel structures and tourist density economics. This asymmetry shapes manufacturer portfolio allocation and regional formulation priorities.
Spain
Costa del Sol and Balearic Islands beach tourism sustains peak-season consumption of post-exposure skin treatments from May through October. ECHA REACH enforcement on preservative allergens pressures Barcelona and Madrid formulators toward microbiome-friendly stabilization systems. Valencia contract manufacturers are expanding aloe vera cold-processing capacity to serve private-label demand from French pharmacy chains.
Italy
Sicilian and Amalfi coast resort operators drive institutional procurement of single-use sachet formats for hospitality amenities. EMA borderline classification scrutiny delays skin-repair claim approvals for Rome-based dermocosmetic brands. Lombardy industrial clusters around Milan are investing in captive botanical extraction to reduce Mexican aloe vera supply dependence.
United States
Southwestern desert states and Florida sustain year-round outdoor recreation participation, expanding spray-format adoption among male athletic demographics. FDA sunscreen monograph updates create compliance synchronization burdens for brands operating transatlantic portfolios. California clean-beauty certification requirements are reshaping preservative system selection for brands targeting Sephora and Ulta channels.
Australia
Queensland and New South Wales coastal populations exhibit highest premium pricing tolerance for multi-functional after-sun formulations combining cooling action with insect repellent. TGA oversight of therapeutic claims intersects with ACCC consumer protection enforcement on natural certification marketing. Sydney and Melbourne dermocosmetic retailers are expanding professional clinic-grade vitamin E and hamamelis assortments.
Germany
Baltic Sea and North Sea summer tourism concentrates demand in July-August windows, compressing inventory turns for mass-market lotions. ISO 16128 natural certification requirements in German-speaking markets favor hamamelis and cucumber extract formulations over synthetic alternatives. Hamburg and Munich innovation centers are developing biomimetic barrier repair technologies for premium salon channels.
After Sun Care Products Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with captive emulsion expertise separating premium positioning from commodity throughput. The vendor base spans consolidated multinational personal care conglomerates and fragmented regional botanical specialists. Three archetypes dominate: integrated beauty conglomerates with captive R&D, contract manufacturers with formulation stabilization expertise, and clean-beauty independents with ISO 16128 certification. Competitive moves concentrate on backward integration into botanical extraction and exclusive professional channel access.
Within the integrated conglomerate tier, Beiersdorf AG, L'Oréal S.A., and Estée Lauder Companies Inc. exemplify divergent strategic positioning. The Hamburg-based Beiersdorf structure anchors emulsion technology development for mass-market penetration. The French L'Oréal S.A. configuration occupies professional salon and dermocosmetic dispensing channels. The New York-incorporated Estée Lauder framework represents premium duty-free travel retail positioning. These three archetypes illustrate how geographic origin and corporate structure map to distinct channel strategies without overlapping execution.
| Leading Market Players |
|---|
| Estée Lauder Companies Inc. |
| L'Oréal S.A. |
| Beiersdorf AG |
| Neutrogena |
| Johnson & Johnson |
| Edgewell Personal Care |
| Unilever PLC |
| Burt's Bees |
| S. C. Johnson & Son, Inc. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day aloe vera gel inventory cycles at Mediterranean formulators compress margin buffers when Mexican harvest disruptions strike, binding pricing power directly to cold-chain logistics reliability and botanical sourcing concentration. REACH-compliant preservative alternatives carrying 40-60% input cost premiums force mid-tier brands toward either premium repositioning or supplier consolidation, reshaping competitive tiers.
Pricing Analysis
Beach tourism revenues in Spain and Italy command 40% premiums over Australian mass-market equivalents, reflecting divergent tourist density economics and channel structures. Three-tier pricing structure across premium clinic-grade, standard pharmacy, and economy mass-retail levels separates vitamin E and hamamelis professional formulations from basic aloe vera lotions. Pricing pressure stems from REACH-compliant preservative cost inflation squeezing mid-tier brand margins. Price-sensitive family buyers in Mediterranean coastal economies contrast with least-sensitive affluent tourists in duty-free travel retail channels.
Supply Chain Analysis
Inventory exposure concentrates in 45-60 day aloe vera mucopolysaccharide sourcing cycles from Mexico and Caribbean cultivation zones, with hurricane disruption and water stress amplifying volatility. Raw material dependencies center on aloe vera gel, tocopherol acetate variants, and hamamelis distillates. Single-source vulnerability in Mexican aloe vera cultivation exposes formulators to climate-driven supply interruptions. Distribution runs through pharmacy chains in Southern Europe, professional salon channels for dermocosmetic brands, and direct-to-consumer sports specialty platforms for athletic demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated pharmacy chains and hospitality procurement consortia, fragmenting access for smaller brands and reshaping margin distribution across the value chain.
For Market Incumbents: Consolidate backward integration into captive botanical extraction capabilities to offset Mexican aloe vera supply volatility and REACH-driven input cost inflation. Secure exclusive professional channel access through aesthetician dispensing partnerships, defending against clean-beauty independents with ISO 16128 certification. Prioritize emulsion stabilization R&D investment at Hamburg and Milan innovation clusters. For New Entrants and Emerging Players: Anchor in male athletic demographic white-space through spray-format sports specialty distribution, where Australian and southwestern US outdoor recreation participants show premium pricing tolerance. Target direct-to-consumer subscription models combining after-sun with insect repellent functionality. Pursue ISO 16128 natural certification as primary go-to-market credential in German-speaking markets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Southern European contract manufacturer capacity collapse creates acquisition opportunities for brands with captive formulation expertise. Target regional botanical specialists with aloe vera cold-processing capabilities and established pharmacy channel relationships. Monitor EMA borderline classification enforcement intensity as inflection signal for medical device reclassification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Extraction | Backward integration into aloe vera processing reduces Mexican supply dependence and REACH compliance exposure. |
| Professional Channel Expansion | Aesthetician-exclusive dispensing through Biotherm and La Roche-Posay models captures margin premiums in salon channels. |
| Spray Format Development | Male athletic demographic adoption in Australia and southwestern US drives fastest-growing product category expansion. |
| ISO 16128 Certification | Standardized natural content verification enables transparent marketing to clean-beauty consumers in German-speaking markets. |
| Microbiome-Friendly Preservation | Professional clinic channels adopt biomimetic barrier repair systems within 18-24 month reformulation cycles. |
Research Approach
Operator-level perspectives from brand managers, category buyers at pharmacy chains, contract manufacturing formulators, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from EMA guidance documents, ECHA REACH substance registrations, customs trade data, and Nielsen retail audit records. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions across product type, active ingredient, packaging format, and end user dimensions.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and botanical supply disruption probabilities. Segmentation dimensions modeled include application format, ingredient technology, distribution channel, and geographic regulatory cluster. CAGRs were derived from trend extrapolation calibrated to historical volume-price elasticities and tourism expenditure correlations. Industry-specific inputs incorporated beach tourism seasonality patterns and EMA borderline claim approval timelines.
Decision-makers should treat outputs as directional under base assumptions of stable REACH enforcement and Mediterranean tourism recovery; material deviation in regulatory stringency or climate-driven supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Ampoule Cream Market
Skincare
Skin Resurfacing Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Germany Skincare Product Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Anti-Acne Dermal Patch Market
Skincare
India Skin Care Products Market
Skincare
Global Skin Rejuvenation Market
Skincare
Cosmeceuticals Market
Skincare
Acne Treatment Market
Skincare
Skin Toner Market
Skincare
Facial Cleansing Balm Market
Skincare
Skin Boosters Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Professional Skin Care Market
Skincare
Dermocosmetics Skin Care Products Market