
 Facial Cleansing Balm Market | 2026-2036
Facial Cleansing Balm Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Cleansing Balm Market Analysis
Plant-derived squalane is broadening the raw-material base for mid-tier facial cleansing balms, displacing petrochemical esters in cost-sensitive formulations. Shiseido Company, Limited leverages its integrated squalane supply chain from Japanese sugarcane fermentation to secure margin stability. Charlotte Tilbury anchors its positioning through fragrance-forward formulations that command specialty-store placement. Unilever competes across mass-market retail with scaled manufacturing in Southeast Asian hubs.
A facial cleansing balm is an anhydrous or limited-water emulsion comprising oils, waxes, and surfactants that liquefy upon skin contact to dissolve sebum, sunscreen, and cosmetic pigments through the like-dissolves-like mechanism, typically requiring a warm-water emulsification step for complete removal. Oil-based formulations dominate volume due to their efficacy against long-wear cosmetics, while hypoallergenic variants capture expanding margin pools as dermatologist referrals rise among reactive-skin consumers. Specialty stores and beauty salons together represent the highest-margin distribution channel, though online platforms are displacing conventional retail for first-time purchases.
The US FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while the EU's REACH and MDR frameworks constrain ingredient portfolios and mandate clinical substantiation for dermal-contact claims. Japan's Ministry of Health, Labour and Welfare enforces quasi-drug standards for balms making acne-prevention or whitening assertions, elevating compliance costs for foreign entrants. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as these compounds appear in some water-resistant balm variants.
Market Dynamics
EU REACH microplastic restrictions are forcing wholesale reformulation of rinse-off cosmetics, redirecting R&D expenditure toward biodegradable emulsifiers and plant-derived alternatives across the facial cleansing balm supply base.
Growth Catalysts
- Biodegradable emulsifier mandates:EU REACH restrictions on microplastic-containing rinse-off products accelerate ingredient substitution toward sugarcane-derived surfactants and fermentation-based alternatives.
- Dermatology clinic protocols:Professional skincare facilities in Seoul and Tokyo are standardizing balm-based pre-treatment routines, creating institutional demand pull for medical-grade formulations.
- K-beauty export channel expansion:South Korean premium beauty distributors are securing dedicated shelf space in North American and European specialty retail, amplifying category visibility.
Market Restraints
- Squalane feedstock volatility:Brazilian sugarcane harvest fluctuations and competing industrial demand from bioplastics producers create raw material price instability for plant-derived formulations.
- Quasi-drug compliance burden:Japan's Ministry of Health, Labour and Welfare standards for acne-prevention or whitening claims impose 18-24 month approval timelines and elevated testing costs for foreign entrants.
- Solid bar substitution threat:Waterless shampoo and cleansing bar formats are capturing sustainability-conscious consumers seeking plastic-free packaging alternatives.
Strategic Opportunities
- Reactive-skin dermatology referrals:Hypoallergenic balm variants can capture expanding margin pools as clinicians recommend oil-based cleansing for barrier-compromised patients.
- Online-first purchase migration:Direct-to-consumer platforms and subscription models are displacing conventional retail for initial trials, reducing slotting fee burdens.
- State-level PFAS restrictions:Emerging US state bans on per- and polyfluoroalkyl substances create first-mover advantage for brands with verified fluorine-free formulations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in anhydrous emulsion stability and sensory engineering remains concentrated among legacy Japanese and European suppliers.
- Cold-chain packaging capex:Temperature-sensitive natural waxes and butter formulations require refrigerated logistics infrastructure that mid-tier brands lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Cleansing Balm Market |
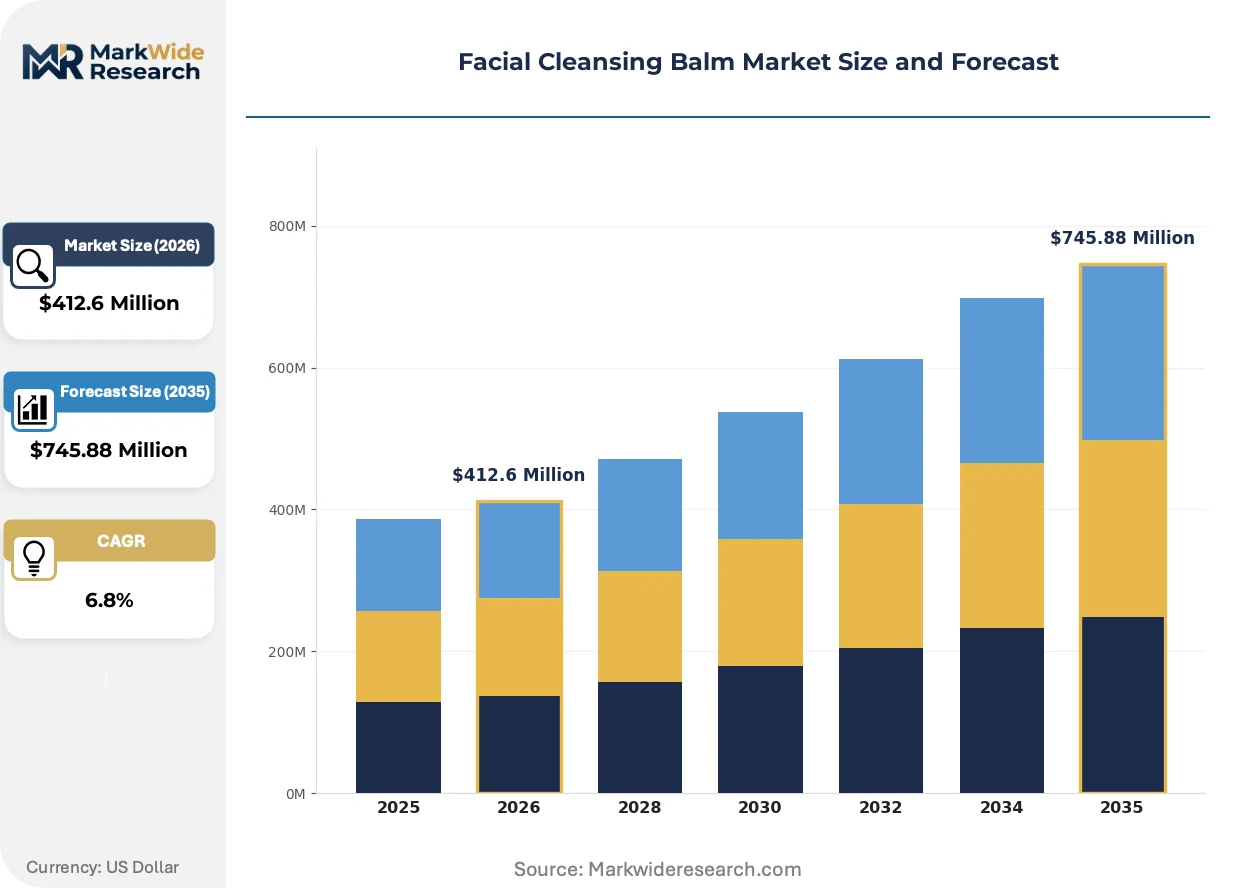
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-based, Water-based, Cream, Stick Formulation Type: Organic, Vegan, Paraben-free, Hypoallergenic End User: Women, Men, Teens, Sensitive Skin Distribution Channel: Online, Supermarkets, Specialty Stores, Beauty Salons |
| Companies Covered | Shiseido Company, Limited, Charlotte Tilbury, Unilever, Procter & Gamble, L'Occitane Groupe S.A., L'Oréal Group, Amorepacific, Kao Corporation, Estee Lauder Companies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Cleansing Balm Market Emerging Trajectories
Formulation science is advancing through biotechnology integration and regulatory compliance automation, while distribution channels fragment between clinical endorsement and algorithm-driven discovery.
Biotechnology-derived squalane is converging with precision fermentation platforms to deliver consistent molecular profiles independent of agricultural harvest cycles. Premium and medical-grade balm producers in Japan and South Korea are adopting these inputs fastest. This convergence is compressing the historical quality gap between mass-market and professional-grade formulations.
EU MDR clinical substantiation requirements now mandate dermal-contact safety documentation for cosmetic claims, elevating testing protocols for brands operating across European markets. Manufacturers must maintain ISO 10993 biocompatibility data packages. Small and mid-sized brands lacking in-house regulatory affairs capacity are outsourcing compliance to specialized CROs.
Algorithm-curated subscription boxes are displacing traditional beauty counter discovery for first-time balm purchasers. Korean and US-based platforms use skin-type quizzes and purchase-history matching to recommend specific balm textures. This shift concentrates marketing spend toward digital sampling and influencer seeding rather than retail slotting fees.
Facial Cleansing Balm Market Segmentation
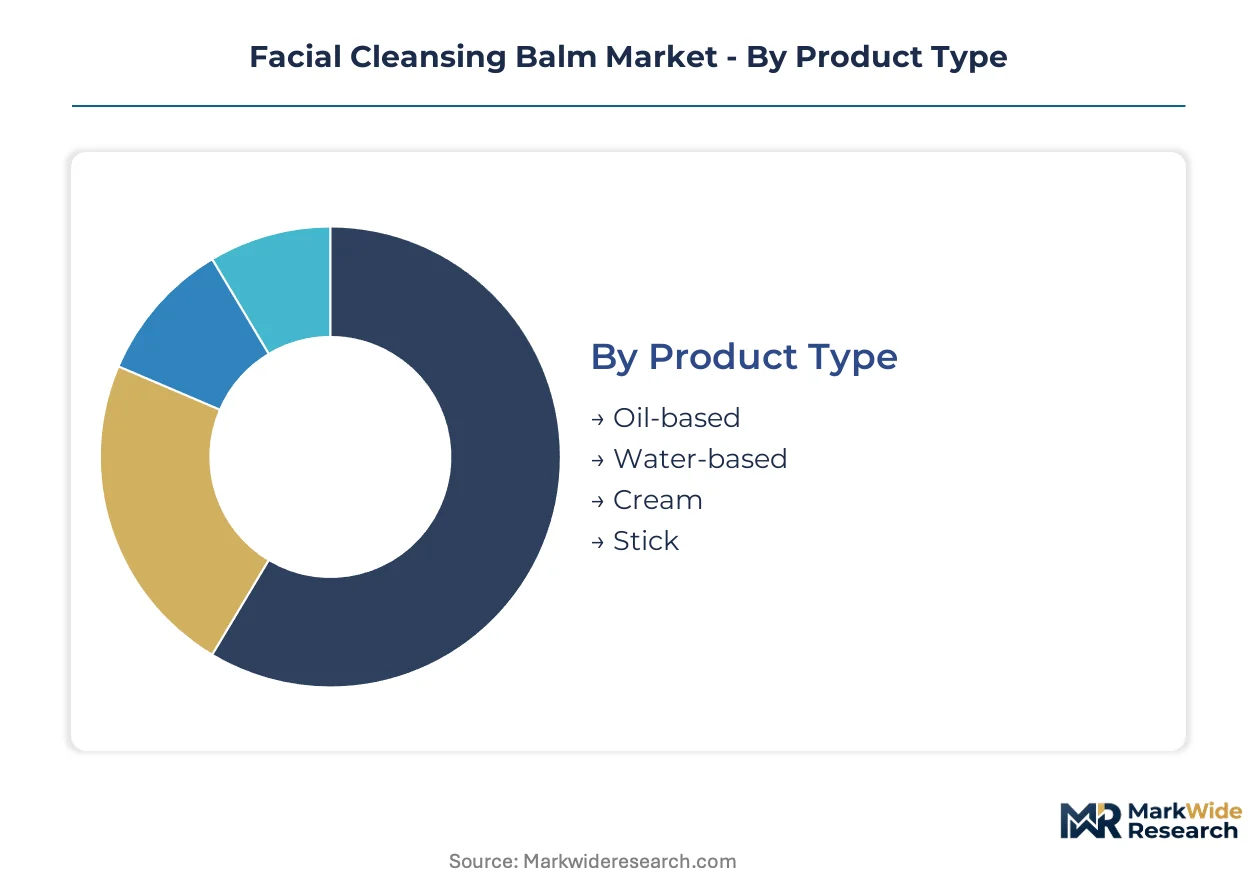
Facial cleansing balm segmentation reveals distinct performance tiers across formulation chemistry and channel access. Product architecture and end-user sensitivity profiles determine margin capture and regulatory exposure for manufacturers.
Product Type:
Cost tier separates mass-market accessibility from premium efficacy claims in this category.
- Oil-based:Anhydrous emulsions of plant-derived triglycerides and esters dissolve long-wear cosmetics through lipophilic attraction. Demand concentrates in Seoul and Tokyo dermatology clinics where pre-treatment protocols standardize balm-based sebum removal.
- Water-based:Limited-water microemulsions incorporate humectants for residue-free rinsing without emulsification steps. South Korean K-beauty export channels favor these formats for humid-climate consumers seeking lightweight textures.
- Cream:Higher aqueous phase content delivers moisturizing benefits for dry-skin segments.
- Stick:Solid anhydrous formats target travel and sustainability-conscious buyers with plastic-free packaging.
Oil-based leads volumes today; water-based is gaining share fastest.
Formulation Type:
Margin stratification follows certification burden and raw-material provenance in this dimension.
- Organic:Certified botanical inputs from regulated agriculture command shelf-space premiums in EU specialty retail. ECHA REACH compliance on biodegradable emulsifiers redirects R&D spend toward sugarcane-derived surfactants.
- Vegan:Exclusion of animal-derived squalane and beeswax requires fermentation-based alternatives. Japanese sugarcane fermentation platforms supply consistent molecular profiles independent of Brazilian harvest volatility.
- Paraben-free:Phenoxyethanol and sodium benzoate substitution responds to EU consumer preference shifts.
- Hypoallergenic:Minimal ingredient lists capture dermatologist referrals for barrier-compromised patients in clinical channels.
Hypoallergenic captures the steepest expansion trajectory as reactive-skin diagnoses multiply.
End User:
Application context drives frequency of use and average transaction value across demographic splits.
- Women:Multi-step skincare routines incorporate balm as first cleanse in double-cleansing protocols. North American specialty stores report highest basket attachment for fragrance-forward formulations.
- Men:Simplified regimens favor low-residue formats with neutral scent profiles. Online subscription platforms accelerate trial through algorithm-matched recommendations.
- Teens:Acne-prevention claims trigger Japan's quasi-drug approval requirements.
- Sensitive Skin:Reactive-type consumers pay premium multiples for fragrance-free, barrier-supporting variants.
Women anchor current revenue; sensitive-skin positioning expands most quickly.
Distribution Channel:
Customer acquisition cost and retention economics vary sharply by touchpoint in this dimension.
- Online:Direct-to-consumer platforms displace conventional retail for first-time purchases through skin-type quizzes and sampling programs. Korean and US-based algorithmic curation reduces slotting fee burdens for emerging brands.
- Supermarkets:Mass-market velocity depends on scaled Southeast Asian manufacturing and promotional depth.
- Specialty Stores:Beauty advisors drive conversion through texture demonstration and regimen bundling.
- Beauty Salons:Professional protocols in Seoul and Tokyo clinics institutionalize medical-grade balm demand.
Specialty stores and beauty salons together represent the highest-margin channel; online is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's dermatology clinic cluster anchors professional-grade balm demand through standardized pre-treatment protocols. Regulatory divergence across major markets forces parallel compliance tracks. Manufacturing concentrates in fermentation-capable regions with established surfactant chemistry infrastructure.
United States
Algorithm-curated subscription platforms and direct-to-consumer sampling drive first-time trial migration away from conventional retail. The FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act. California's emerging state-level PFAS restrictions create compliance complexity for water-resistant formulation variants.
South Korea
Premium K-beauty export channels secure dedicated shelf space in North American and European specialty retail, amplifying category visibility. The Ministry of Food and Drug Safety (MFDS) enforces stringent cosmetic safety standards. Seoul's Gangnam district hosts the densest concentration of dermatology clinics standardizing balm-based pre-treatment routines.
Japan
Quasi-drug approval requirements for acne-prevention or whitening claims impose 18-24 month timelines that filter foreign entrants. The Ministry of Health, Labour and Welfare maintains these elevated standards. Tokyo's Shibuya and Ginza districts concentrate flagship specialty retail where fragrance-forward formulations command premium positioning.
Germany
EU REACH restrictions on microplastic-containing rinse-off cosmetics accelerate reformulation toward biodegradable emulsifiers. ECHA mandates clinical substantiation for dermal-contact claims under MDR frameworks. Hamburg and Düsseldorf serve as distribution hubs for certified organic formulations targeting EU specialty retail.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance obligations alongside retained EU REACH alignment. The Office for Product Safety and Standards oversees cosmetic safety enforcement. London's West End specialty stores drive conversion through texture demonstration and regimen bundling for premium-tier variants.
Facial Cleansing Balm Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation-based squalane platforms scale to displace agricultural feedstock dependency. The vendor base stratifies across three tiers: integrated beauty conglomerates with captive biotechnology assets, mid-tier specialists leveraging contract manufacturing, and emerging direct-to-consumer brands. Two strategic archetypes predominate: those securing upstream control over plant-derived emulsifier supply chains, and those anchoring positioning through sensory differentiation and fragrance engineering. M&A activity concentrates on biotechnology capabilities, while geographic expansion targets Southeast Asian manufacturing hubs for cost-sensitive mass-market lines.
Within the integrated conglomerate tier, Shiseido Company, Limited and Unilever occupy positions reflecting divergent supply chain strategies. Shiseido exemplifies backward integration into Japanese sugarcane fermentation platforms for margin-stable squalane sourcing. Unilever represents scale-driven manufacturing concentration across Southeast Asian hubs. Charlotte Tilbury sits within the premium specialist archetype, anchoring market presence through sensory-forward formulation positioning that commands specialty-store placement economics.
| Leading Market Players |
|---|
| Shiseido Company, Limited |
| Charlotte Tilbury |
| Unilever |
| Procter & Gamble |
| L'Occitane Groupe S.A. |
| L'Oréal Group |
| Amorepacific |
| Kao Corporation |
| Estee Lauder Companies, Inc. |
| Others |
Supply Flow & Price Mechanics
EU REACH microplastic restrictions gate qualified supply access and premium-tier pricing power by mandating biodegradable emulsifier substitution. Manufacturers lacking fermentation-based surfactant partnerships face margin compression or market exit.
Pricing Analysis
Input-cost pass-through from Brazilian sugarcane harvest volatility and bioplastics sector competition feeds directly into plant-derived squalane pricing. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade dermatology formulations from mass-market retail variants. Pricing pressure stems from solid cleansing bar substitution threatening volume-based economies. Mass-market supermarket buyers exhibit highest price sensitivity; Seoul clinic procurement committees demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Hamburg and Düsseldorf anchor EU hub-and-spoke patterns for certified organic formulations. Manufacturing concentrates in Japan, South Korea, and Southeast Asian contract hubs. Raw material dependencies center on sugarcane-derived squalane, fermentation-based surfactants, and temperature-sensitive natural waxes. Single-source vulnerability from Brazilian agricultural feedstock creates supply risk. Distribution runs through specialty retail and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facial cleansing balm market functions as a stable compounder, with dermatology clinic protocol standardization in Seoul and Tokyo driving institutional demand recurrence.
For Market Incumbents: Anticipate solid bar substitution by securing captive fermentation capacity for margin-stable squalane sourcing. Shiseido's integrated Japanese sugarcane platform exemplifies defensive positioning. Backward integration into biotechnology assets protects against feedstock volatility while clinical channel control preserves premium pricing. For New Entrants and Emerging Players: Begin with algorithm-curated subscription platforms targeting North American sensitive-skin consumers seeking fragrance-free trials. The reactive-skin dermatology referral channel offers lowest competitive density. Direct-to-consumer sampling reduces slotting fee barriers versus specialty retail entry. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier vegan-certified specialists because EU REACH compliance costs filter sub-scale competitors. Five-to-ten year viability rests on biotechnology capability consolidation. Acquisition targets should demonstrate fermentation partnerships or clinical endorsement traction. Watch Japanese quasi-drug approval timelines as inflection signal for medical-grade positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | Captive squalane supply from Japanese sugarcane platforms insulates margin from Brazilian harvest volatility. |
| Clinical Channel Partnership | Seoul dermatology clinic protocols institutionalize medical-grade balm demand through standardized pre-treatment routines. |
| Direct-to-Consumer Platform Launch | Algorithm-curated subscription boxes reduce slotting fees while capturing sensitive-skin trial migration from conventional retail. |
| EU REACH Compliance Certification | Biodegradable emulsifier documentation unlocks specialty retail placement in Hamburg and Düsseldorf distribution hubs. |
| Fragrance-Free Line Extension | Hypoallergenic variants capture dermatologist referral flows for barrier-compromised patients in clinical channels. |
Methodological Framework
Bottom-up dermatology clinic and specialty retail modeling reconciled against top-down fermentation capacity and export channel tracking forms the analytical core. Primary interviews with formulation chemists, brand regulatory affairs leads, Korean beauty distributor category managers, and Seoul clinic procurement officers combined with secondary validation from ECHA REACH documentation, MFDS cosmetic safety filings, Japanese Ministry of Health quasi-drug registers, and customs export data. Triangulation between demand-side protocol adoption and supply-side biotechnology investment patterns anchors volume estimates.
Input-output matrices connect segmentation dimensions including formulation chemistry, certification tier, distribution channel, and regional regulatory cluster to derive value trajectories across the projection horizon. CAGRs emerge from fitted growth curves calibrated against historical K-beauty export velocity and clinical protocol diffusion rates. Modeled inputs incorporate squalane feedstock cost indices, EU emulsifier substitution timelines, and algorithmic platform customer acquisition metrics.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration on PFAS compounds, abrupt Brazilian sugarcane crop failure, and pandemic-scale disruption to clinical channel operations. Forecasts reflect documented assumptions on biotechnology scale-up curves and clinic protocol standardization rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Sensitive Skin Care Products Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
Retinol Skincare Product Market
Skincare
Ampoule Cream Market
Skincare
India Skin Care Products Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Cystic Acne Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Mineral Sunscreen Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
Acne Treatment Market
Skincare
CBD Skin Care Market
Skincare
Germany Skincare Product Market
Skincare
Global Skin Rejuvenation Market
Skincare
Ultrasound Skin Cleaners Market