
 Skincare Serums Market | 2026-2036
Skincare Serums Market Size, Share, and Industry Trends Forecast 2026-2036
Skincare Serums Market Outlook
Prestige retail margin pools is fragmenting as direct-to-consumer subscriptions and professional channel sales capture higher lifetime value per user. L'Oréal S.A. leverages its dermatological science heritage to anchor clinical credibility across pharmacy and med-spa channels. Estée Lauder Companies Inc. sustains premium positioning through controlled distribution and limited wholesale exposure. DECIEM Beauty Group Inc. differentiates via radical price transparency and ingredient-first communication that undercuts traditional marketing overhead.
Skincare serums are concentrated aqueous or emulsion-based formulations containing active ingredients at therapeutic concentrations, typically delivered through dropper or pump systems designed for targeted epidermal penetration. These products function as treatment layers within multi-step regimens, delivering actives such as vitamin C, hyaluronic acid, or retinol before occlusion with moisturizers. Anti-aging serums command the deepest margin pools due to consumer willingness to pay for visible wrinkle reduction and skin texture improvement. Hydrating serums built around hyaluronic acid are gaining velocity among younger demographics prioritizing barrier repair over corrective treatment. Brightening formulations face regulatory headwinds in multiple jurisdictions where pigment-modifying claims trigger pharmaceutical classification thresholds.
The U.S. FDA oversees cosmetic safety through the Federal Food, Drug, and Cosmetic Act, while the EPA regulates certain preservative chemistries under antimicrobial pesticide frameworks; the EU Cosmetics Regulation and REACH constrain ingredient palettes and mandate safety dossiers that shape formulation possibilities. China's NMPA and GB standards impose additional testing requirements for imported products, creating divergent compliance pathways that favor localized production. Stakeholders must monitor evolving classification boundaries between cosmetics and drugs, as retinol concentration thresholds and peptide-based claims face heightened scrutiny across FDA, EMA, and NMPA jurisdictions simultaneously.
Market Dynamics
Prestige retail margin pools are fragmenting as direct-to-consumer subscriptions and professional channel sales capture higher lifetime value per user, while EU Cosmetics Regulation disclosure mandates force simultaneous reformulation investments across multiple product lines.
Growth Catalysts
- Professional channel expansion:Dermatology clinics and medical spas across North America and Europe are developing proprietary serum protocols that lock in recurring patient visits and professional-grade product purchases.
- REACH compliance investments:The EU's tightening ingredient safety dossier requirements are accelerating clean-formulation R&D that opens premium positioning for brands with verified safety credentials.
- Hyaluronic acid innovation:Barrier-repair formulations built around multi-molecular-weight hyaluronic acid are displacing basic moisturizers among younger demographics prioritizing prevention over correction.
Market Restraints
- Retinol concentration thresholds:FDA, EMA, and NMPA jurisdictions are simultaneously scrutinizing retinol potency levels, forcing brands to maintain parallel formulation inventories or dilute efficacy claims.
- Preservative chemistry constraints:EPA antimicrobial pesticide frameworks and EU biocide regulations are narrowing acceptable preservative palettes, increasing formulation instability risks and shelf-life limitations.
- Import testing requirements:China's NMPA and GB standards impose animal testing mandates and extended registration timelines that favor localized production over cross-border supply.
Strategic Opportunities
- Subscription platform penetration:Direct-to-consumer replenishment models in the United States are capturing recurring revenue streams that bypass traditional wholesale margin stacking and inventory risk.
- Peptide-based claims development:Signal peptide and growth factor formulations occupy regulatory gray zones between cosmetics and drugs, offering first-mover advantages for brands that navigate classification boundaries successfully.
- Men's grooming expansion:Underpenetrated male demographics in prestige retail channels represent whitespace for simplified regimen positioning and gender-neutral packaging architectures.
Industry Challenges
- Clinical validation timelines:Substantiating visible wrinkle reduction claims requires extended instrumental measurement studies and dermatologist oversight that compresses launch windows and inflates R&D burn rates.
- Cross-jurisdictional dossier management:Maintaining parallel safety documentation for FDA, EMA, and NMPA submissions demands specialized regulatory affairs talent that commands premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skincare Serums Market |
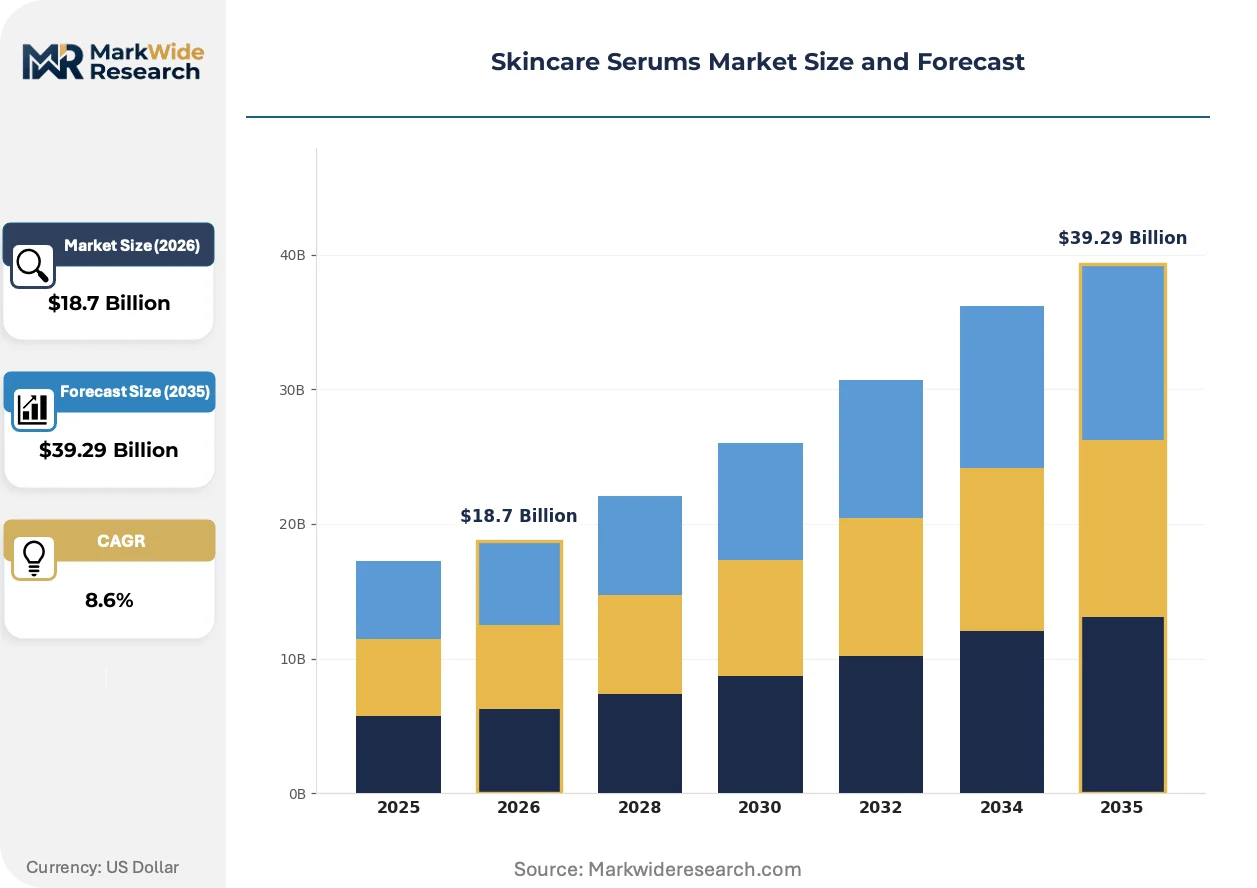
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidant, Hydrating, Brightening, Anti-Aging Ingredient Type: Vitamin C, Hyaluronic Acid, Retinol, Peptides Formulation: Gel, Liquide, Cream, Oil End User: Women, Men, Teens, Professionals |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies Inc., Shiseido Company Limited, Procter & Gamble, DECIEM Beauty Group Inc., Unilever plc, Amorepacific Group Inc., Beiersdorf AG, Galderma S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skincare Serums Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel compression as biotechnology-enabled actives meet algorithmic personalization platforms, collapsing traditional development and go-to-market timelines simultaneously.
Liposomal and nanostructured lipid carrier delivery systems are collapsing the efficacy gap between cosmetic and pharmaceutical penetration depths. Prestige brands and dermatology channel suppliers are adopting these encapsulation technologies to justify price premiums through measurable bioavailability improvements. The structural consequence is compressing competitive differentiation around raw ingredient sourcing alone.
The EU Cosmetics Regulation's 2023 fragrance allergen expansion mandates are forcing reformulation of legacy serum bases that relied on masking scents. Manufacturers serving European markets are stripping fragrance entirely or investing in hypoallergenic alternative scent technologies. Brightening and anti-aging serums with complex botanical portfolios face the steepest compliance costs and timeline disruptions.
Algorithmic skin analysis tools embedded in mobile applications are redirecting purchase decisions from in-store consultation toward data-driven subscription matching. Younger demographics in the United States are bypassing department store beauty counters for diagnostic-led direct purchasing that reduces trial-and-error expenditure. This behavior concentrates demand among platforms with proprietary skin imaging datasets and recommendation engines.
Skincare Serums Market Segmentation
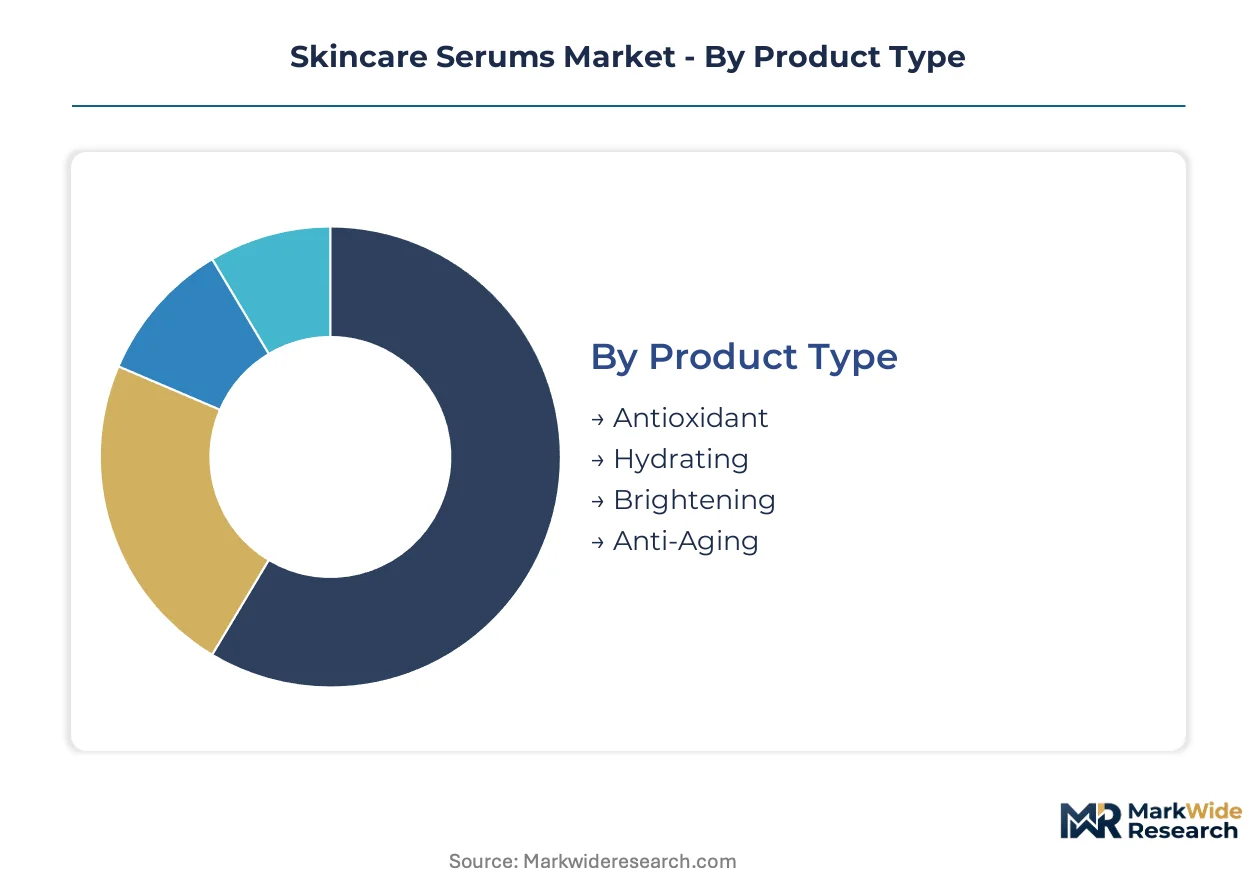
Segmentation in skincare serums determines formulation investment priorities, channel strategy, and regulatory compliance pathways. Each dimension reveals distinct margin structures and customer lifetime value profiles that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across serum categories, with professional-channel brands investing in dermatologist consultation networks while mass-market players rely on digital self-service education.
- Anti-Aging:Concentrated retinol, peptide, and growth factor formulations targeting visible wrinkle reduction and collagen synthesis. Demand concentrates in the United States through prestige retail and medical spa channels, driven by consumer willingness to pay premium prices for clinically validated efficacy claims.
- Hydrating:Multi-molecular-weight hyaluronic acid matrices designed for barrier repair and transepidermal water loss prevention. Younger demographics in direct-to-consumer subscription platforms are displacing basic moisturizers with these prevention-focused treatments.
- Antioxidant:Vitamin C, niacinamide, and polyphenol-based formulations neutralizing free radical damage. Stability challenges in aqueous bases drive refrigerated delivery models and shorter shelf-life positioning.
- Brightening:Pigment-modifying actives including arbutin, kojic acid, and tranexamic acid. Regulatory scrutiny across FDA and NMPA jurisdictions constrains claim language and triggers pharmaceutical classification thresholds in several markets.
Anti-Aging holds the largest share; momentum sits with Hydrating.
Ingredient Type:
Cost tier stratification in raw material sourcing directly determines retail price positioning and gross margin sustainability across pharmacy, prestige, and professional channels.
- Hyaluronic Acid:Biotechnologically produced glycosaminoglycan with water-binding capacity up to 1000x molecular weight. Fermentation-grade supply from South Korean and Chinese manufacturers has collapsed per-gram costs, enabling mass-market penetration.
- Retinol:Vitamin A derivative requiring encapsulation or stabilization systems to prevent degradation. FDA and NMPA concentration thresholds are forcing parallel inventory maintenance or efficacy dilution.
- Vitamin C:L-ascorbic acid and derivative forms including ascorbyl glucoside and tetrahexyldecyl ascorbate. Oxidation susceptibility drives airless packaging requirements and pH optimization R&D.
- Peptides:Signal sequences and carrier molecules occupying regulatory gray zones between cosmetic and drug classifications. First-mover brands navigating EMA and FDA boundary enforcement capture premium positioning.
Hyaluronic Acid commands volume leadership; Peptides are climbing the fastest.
Formulation:
Application-driven texture preferences vary by climate, skin type distribution, and regimen complexity expectations across consumer segments.
- Liquide:Low-viscosity aqueous bases enabling rapid absorption and layerability within multi-step routines. Dominates in humid climates and among younger consumers prioritizing lightweight textures.
- Gel:Hydrocolloid-thickened systems providing cooling sensory cues and oil-free positioning. Oily and combination skin demographics in Asia-Pacific markets show strongest preference.
- Cream:Emulsion-based vehicles combining treatment actives with occlusive moisturizing benefits. Mature skin segments and colder climate markets favor this simplified regimen approach.
- Oil:Lipid-dissolved retinoids and antioxidant actives leveraging enhanced penetration through sebum-mimetic vehicles. Dry and sensitive skin positioning commands price premiums through ingredient quality signaling.
Liquide formulations hold the largest share; Gel is gaining share fastest.
End User:
Customer type segmentation determines marketing architecture, retail channel selection, and product education investment intensity.
- Women:Core demographic with established multi-step regimen behavior and highest category spending per capita. Prestige retail and subscription platforms concentrate acquisition investment.
- Professionals:Medical spa clients and dermatology patients purchasing professional-grade protocols. Recurring visit structures lock in higher lifetime value than retail-only relationships.
- Men:Underpenetrated segment responding to simplified positioning and gender-neutral packaging architectures. Barber channel and direct-to-consumer digital acquisition show traction.
- Teens:Prevention-focused early adopters prioritizing barrier repair and antioxidant protection over corrective treatments. Social media discovery and peer recommendation drive purchase decisions.
Women hold the largest share; Men represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with United States consumers absorbing premium pricing for clinical-grade formulations while price-sensitive buyers in emerging markets trade down to basic hydrators or defer purchases entirely.
United States
Prestige retail and subscription platforms concentrate the highest per-capita spending on anti-aging and peptide-based serums. The FDA's scrutiny of retinol concentration thresholds under the Federal Food, Drug, and Cosmetic Act is forcing brands to maintain dual-formulation inventories. New York and Los Angeles anchor the professional channel expansion, with dermatology clinics and medical spas developing proprietary protocols that lock in recurring patient visits.
Germany
Pharmacy-channel distribution dominates consumer trust, with consumers prioritizing ECHA-verified safety dossiers over marketing claims. The EU Cosmetics Regulation's fragrance allergen mandates are accelerating fragrance-free reformulation across legacy serum lines. The Rhine-Ruhr and Bavarian industrial clusters host specialized contract manufacturers serving both domestic brands and private-label exporters.
China
Domestic biotech fermentation of hyaluronic acid has collapsed raw material costs, enabling mass-market penetration at price points below imported equivalents. The NMPA's animal testing requirements and extended registration timelines favor localized production over cross-border supply. Shanghai and Guangzhou concentrate R&D investment in liposomal delivery systems and algorithmic skin analysis platforms.
South Korea
Fermentation-grade hyaluronic acid supply from domestic biotech manufacturers underpins cost competitiveness in hydrating serum exports. The MFDS maintains alignment with EU safety standards while streamlining approval timelines for novel encapsulation technologies. Seoul anchors both the ingredient innovation cluster and the direct-to-consumer platform ecosystem targeting younger demographics across Asia-Pacific markets.
France
Luxury heritage positioning sustains premium pricing for botanical and marine-derived active formulations. The EU Green Deal's sustainability reporting requirements under CSRD are pressuring supply chain transparency from raw material sourcing through retail. The Île-de-France region concentrates headquarters operations for multinational groups, while Provence-Alpes-Côte d'Azur hosts specialized extraction facilities for regional botanical actives.
Skincare Serums Market Competitive Environment
Science-backed dermatological heritage and algorithmic direct-to-consumer platforms split the market between credibility-driven pharmacy channels and data-optimized subscription models. The vendor base concentrates among multinational conglomerates with vertical control over raw material supply and specialized mid-cap innovators with single-brand focus. Three archetypes dominate: conglomerate science brands leveraging R&D scale, transparency-first challengers stripping marketing overhead, and professional-channel specialists embedding in clinic protocols. Competitive intensity centers on M&A absorption of peptide-biotech startups and strategic partnerships with dermatology clinic networks.
Within the conglomerate tier, L'Oréal S.A. and Estée Lauder Companies Inc. exemplify divergent channel strategies—one anchoring clinical credibility across pharmacy and med-spa networks, the other sustaining scarcity through controlled distribution. DECIEM Beauty Group Inc. occupies a distinct challenger position, representing the transparency archetype that undercuts traditional marketing investment through ingredient-first communication. These three entities collectively illustrate the structural tension between heritage credibility, distribution control, and radical price positioning that defines current competitive dynamics.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies Inc. |
| Shiseido Company Limited |
| Procter & Gamble |
| DECIEM Beauty Group Inc. |
| Unilever plc |
| Amorepacific Group Inc. |
| Beiersdorf AG |
| Galderma S.A. |
| Others |
Value Chain & Pricing Dynamics
South Korean and Chinese fermentation-grade hyaluronic acid supply has collapsed per-gram costs, concentrating upstream margin capture among biotech manufacturers while downstream brands compete on formulation sophistication and channel access. This raw material cost compression enables mass-market penetration but simultaneously erodes differentiation for brands lacking proprietary delivery technology or clinical validation infrastructure.
Pricing Analysis
Professional consultation and replenishment subscription tiers drive lifetime value far above transactional retail purchases. Three-tier pricing structure across prestige retail, professional-channel protocols, and direct-to-consumer subscriptions separates clinical credibility from accessibility. Pricing pressure stems from hyaluronic acid commoditization and private-label proliferation in pharmacy channels. Price-sensitive younger demographics in mass-market subscriptions trade efficacy claims for affordability, while medical spa clients absorb premium positioning for dermatologist-supervised protocols.
Supply Chain Analysis
Extended payment terms from prestige retailers and supply-chain finance facilities strain working capital for mid-tier formulation houses. Raw material sourcing draws from South Korea, China, and Germany for hyaluronic acid, retinol precursors, and peptide synthesis respectively. Single-source vulnerability concentrates in liposomal encapsulation technology licensed from specialized European suppliers. Distribution runs through pharmacy networks in Germany, department store beauty halls in France, and algorithmic subscription platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel fragmentation and regulatory divergence are creating defendable niches for specialists with jurisdiction-specific compliance capabilities or proprietary professional relationships. Algorithmic personalization platforms and medical spa protocol integration represent the most significant demand-side shifts opening whitespace.
For Market Incumbents: Entrench clinical credibility through exclusive dermatology clinic partnerships that lock in recurring professional-grade purchases. Deepen backward integration into fermentation-grade hyaluronic acid production to defend margin position against Chinese and South Korean supply cost compression. Prioritize EMA and FDA parallel dossier capabilities as regulatory divergence intensifies compliance moats. For New Entrants and Emerging Players: Men's grooming segments in prestige retail channels represent the most penetrable entry point given underpenetrated demographics and simplified regimen positioning. Algorithmic skin analysis platforms with proprietary recommendation engines offer direct-to-consumer bypass of traditional wholesale margin stacking. Target barber channel distribution for male-focused hydrating serums with gender-neutral packaging architectures. For Investors and Strategic Acquirers: Capital is best deployed toward peptide-biotech startups navigating cosmetic-drug classification boundaries with first-mover EMA and FDA submission strategies. Long-term viability across the analysis window favors specialists with captive professional channel relationships over mass-market brands exposed to private-label substitution. Watch NMPA retinol concentration threshold enforcement as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Professional Channel Partnership | Exclusive dermatology clinic protocols lock in recurring patient visits and higher lifetime value than retail-only relationships. |
| Peptide-Based Claims Development | Signal peptide formulations occupying regulatory gray zones capture premium positioning before FDA and EMA boundary enforcement tightens. |
| Direct-to-Consumer Platform Launch | Algorithmic skin analysis tools with proprietary datasets bypass department store beauty counters and reduce customer acquisition costs. |
| Backward Integration into Fermentation | In-house hyaluronic acid production defends margin compression from South Korean and Chinese biotech supply dominance. |
| Fragrance-Free Reformulation | EU Cosmetics Regulation allergen mandates force legacy serum base redesigns that open premium positioning for hypoallergenic alternatives. |
Study Parameters
A spread of perspectives from dermatology clinic operators, regulatory affairs specialists at multinational conglomerates, pharmacy channel buyers, and direct-to-consumer platform engineers converged on the working assumptions underlying demand elasticity and channel shift trajectories. Secondary validation drew from FDA 510(k) filings, EMA cosmetic ingredient safety dossiers, NMPA registration databases, and customs trade data on hyaluronic acid imports. Bottom-up serum volume estimates by channel and formulation type triangulated against top-down market value reconstructions from prestige retail audit data.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, ingredient category, formulation texture, and end-user demographic. CAGRs were derived from trend extrapolation of professional channel expansion rates, subscription platform penetration curves, and regulatory reformulation cycle impacts. Industry-specific forecast inputs included REACH compliance investment timelines, NMPA animal testing requirement phase-out assumptions, and liposomal delivery technology adoption curves in prestige positioning.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on prestige beauty, cross-border e-commerce tariff regimes, or biotech fermentation input costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and channel migration velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Acne Treatment Market
Skincare
Professional Skin Care Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Skincare Ingredients Market
Skincare
Africa Cosmeceutical Market
Skincare
Skin Care Emulsion Market
Skincare
Skin Grafting System Market
Skincare
Organic Skincare Products Market
Skincare
Hand Care Market
Skincare
Dermocosmetics Market
Skincare
Global Skin Rejuvenation Market
Skincare
Skin Antiseptic Market
Skincare
Sun-Care Wipes Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
CBD Skin Care Market
Skincare
Skin Barrier Market