
 Biological Skin Substitutes Market | 2026-2036
Biological Skin Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Skin Substitutes Market Intelligence
Asset-light licensing and contract manufacturing arrangements is narrowing the capital barrier for mid-tier biologics firms seeking entry into advanced wound care. MIMEDX Group leverages placental tissue processing expertise to sustain premium positioning in chronic wound applications. Organogenesis Inc. anchors outpatient channels with living cell-based therapies, while Smith & Nephew plc competes across surgical and burn center segments through diversified biological and synthetic portfolios.
Biological skin substitutes comprise engineered or naturally derived matrices designed to replace or regenerate damaged integumentary tissue, typically incorporating collagen scaffolds seeded with autologous or allogeneic cells and maintaining moisture vapor transmission rates between 2,000 and 10,000 g/m²/day to promote re-epithelialization. These products serve primarily to accelerate closure of full-thickness wounds, reduce scar contracture, and restore barrier function in burns, diabetic ulcers, and surgical defects. Human dermal matrix products dominate current revenue pools given established reimbursement and broad surgical applicability, while composite grafts represent the fastest-expanding category as surgeons seek single-procedure solutions combining dermal scaffold and epidermal coverage. Delivery mode segmentation reveals surgical application as the mature volume base, though outpatient procedures are gaining share as ambulatory surgical centers expand their scope of complex wound management.
FDA oversight through its Center for Biologics Evaluation and Research and the Human Cells, Tissues, and Cellular and Tissue-Based Products framework demands rigorous donor screening, manufacturing controls, and clinical evidence for new biological skin substitute approvals, directly shaping product development costs and timelines. The European Medicines Agency's Advanced Therapy Medicinal Products regulation and the Medical Device Regulation create parallel but distinct conformity pathways that influence market access strategies for firms pursuing dual-territory commercialization. Stakeholders must monitor evolving health technology assessment criteria from national payers, as evidence thresholds for premium reimbursement increasingly determine which biological platforms achieve sustainable adoption beyond initial clinical enthusiasm.
Market Dynamics
The FDA's evolving Human Cells, Tissues, and Cellular and Tissue-Based Products framework is compressing product development timelines while elevating clinical evidence thresholds, forcing manufacturers to restructure trial designs and donor screening protocols to maintain market access.
Growth Catalysts
- Burn center expansion:Rising chronic wound prevalence among aging populations in the United States is accelerating facility investments and procedural volume.
- EMA Advanced Therapy Medicinal Products pathway:Streamlined conformity assessment in Europe is reducing time-to-market for novel cellular therapies.
- Placental tissue processing:Advanced decellularization techniques are expanding donor tissue yield and improving matrix consistency for chronic wound applications.
Market Restraints
- Donor tissue supply concentration:Limited qualified tissue recovery organizations in the United States create procurement bottlenecks and geographic access disparities.
- FDA clinical evidence requirements:Expanded randomized controlled trial mandates for new biological skin substitutes extend development cycles and inflate regulatory costs.
- Synthetic matrix substitution:Improved acellular dermal matrices from collagen engineering labs offer lower-cost alternatives for partial-thickness wound coverage.
Strategic Opportunities
- Ambulatory surgical center penetration:Outpatient wound management capabilities are expanding in Germany and France, creating new procedural volume outside hospital settings.
- Japan's regenerative medicine fast-track:PMDA's conditional approval framework for tissue-engineered products accelerates commercialization timelines for qualified sponsors.
- 3D bioprinting convergence:Integration of patient-derived cells with automated scaffold fabrication is enabling personalized graft geometries for complex defect reconstruction.
Industry Challenges
- Tissue processing technician scarcity:Specialized skills in aseptic decellularization and cryopreservation remain concentrated at a limited number of academic medical centers.
- Health technology assessment divergence:Inconsistent evidence requirements across England's NICE, Germany's IQWiG, and France's HAS complicate parallel reimbursement submissions.
- Cold chain integrity:Maintaining viable cell populations through distributed logistics networks requires capital-intensive temperature monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Skin Substitutes Market |
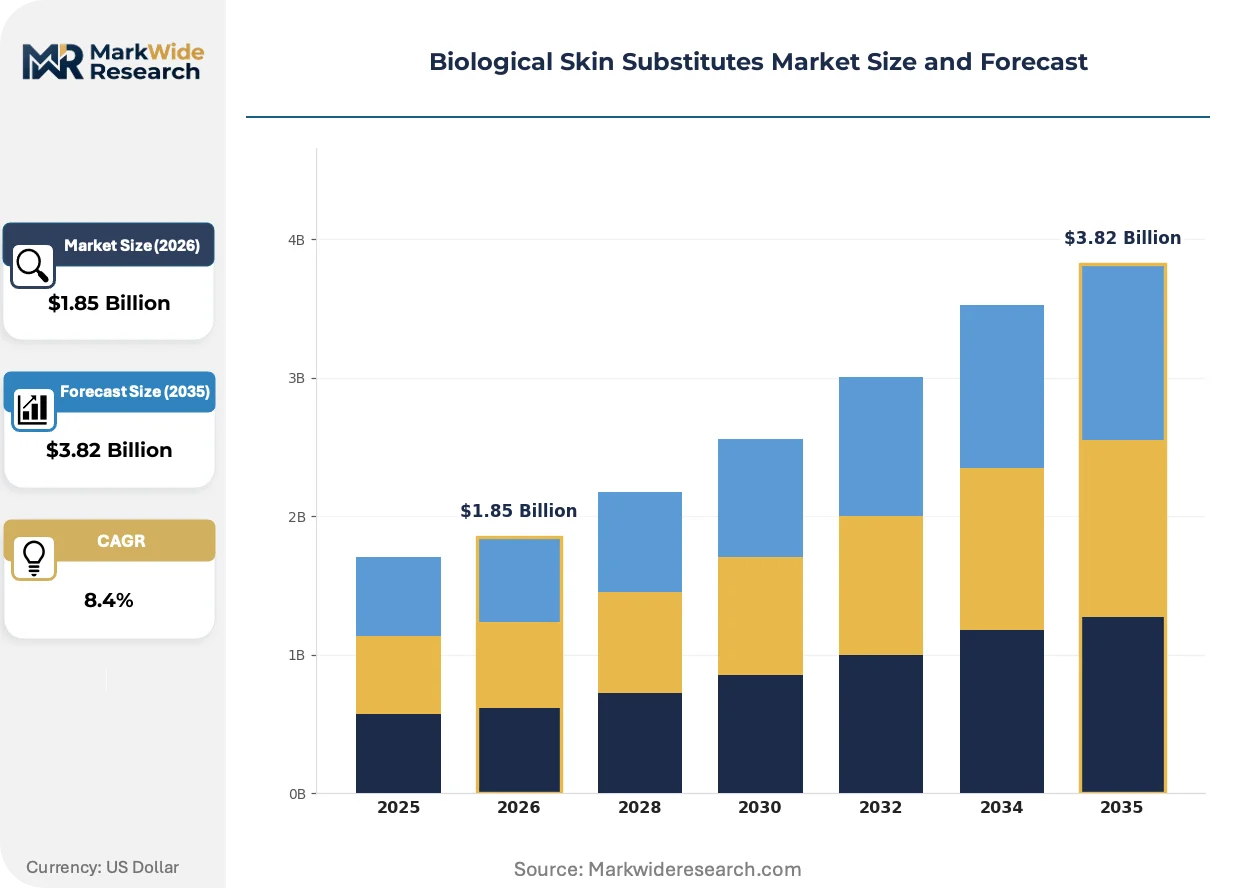
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Dermal Matrix, Epidermal Replacement, Composite Grafts, Biological Dressings Delivery Mode: Surgical Application, Outpatient Procedures, In-Hospital Treatments, Home Care Solutions End User: Hospitals, Clinics, Burn Centers, Research Institutions Material: Collagen, Chitosan, Hyaluronic Acid, Fibrin, Others |
| Companies Covered | Stryker Corporation, MIMEDX Group, Inc., Organogenesis Inc., Tissue Regenix, Vericel Corporation, Integra LifeSciences Corporation, 3M Company, Mölnlycke Health Care, Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Skin Substitutes Market Strategic Shifts & Innovations
Biological skin substitute development is pivoting toward integrated manufacturing approaches that collapse the traditional separation between scaffold production and cellular seeding. This convergence is reshaping competitive capabilities and procurement criteria across wound care settings.
Composite graft technology is hybridizing autologous keratinocyte harvesting with off-the-shelf dermal matrices to enable single-procedure full-thickness wound closure. Burn centers in the United States are adopting these systems fastest, driven by operative efficiency demands and reduced donor site morbidity. The technology is hybridizing previously distinct product categories into unified surgical workflows that compress total treatment costs.
The European Union's Medical Device Regulation recast classification rules for dermal substitutes containing viable cells, shifting oversight from notified bodies to EMA for certain product categories. Manufacturers face expanded quality management system requirements and clinical follow-up obligations. France and Germany are experiencing the steepest compliance cost increases as national competent authorities align inspection protocols with the new framework.
Hospital procurement committees are consolidating vendor relationships around suppliers offering both biological and synthetic portfolios, reducing administrative burden and standardizing clinician training. This concentration favors integrated wound care companies over single-product specialists. The United States exhibits the most pronounced procurement consolidation, with integrated delivery networks in Texas and Florida leading contract rationalization efforts.
Biological Skin Substitutes Market Segmentation
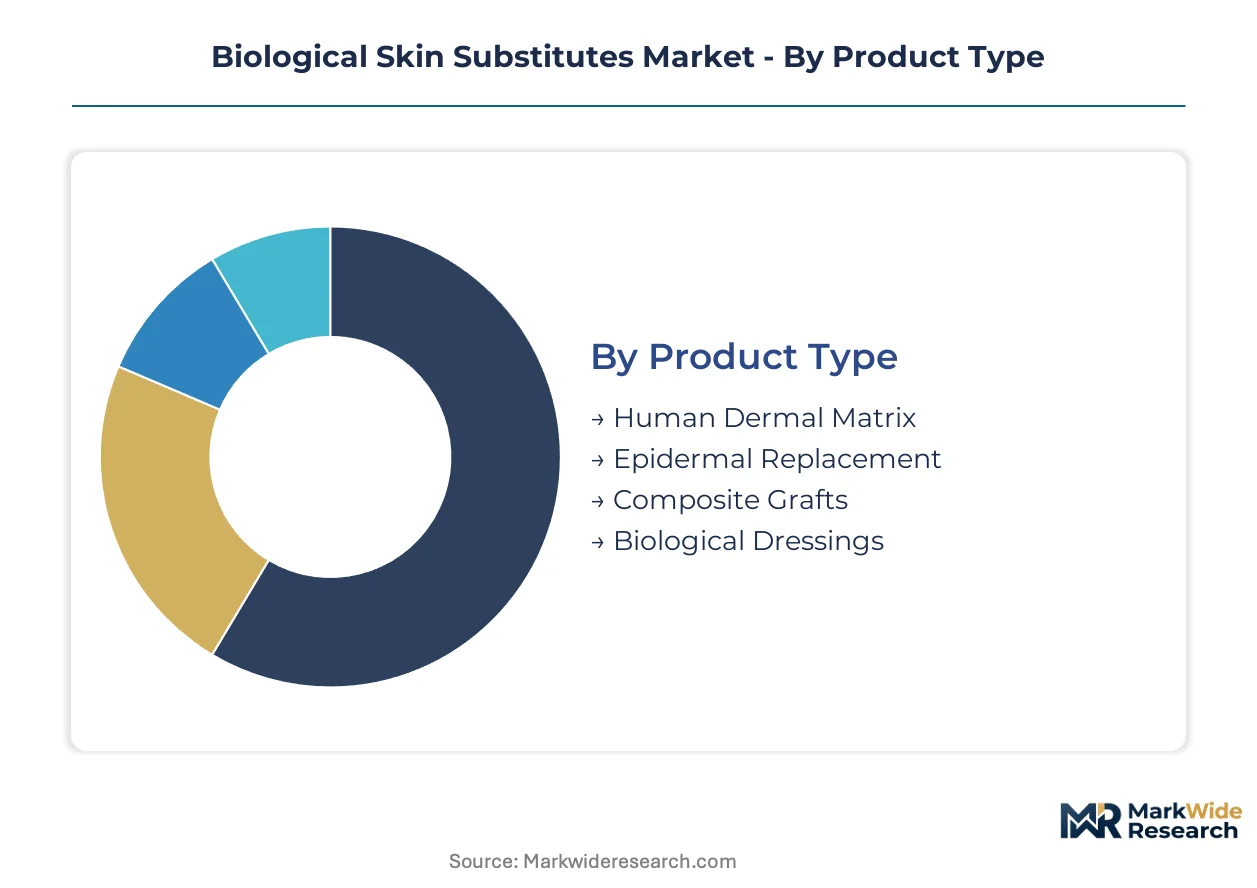
Segmentation in biological skin substitutes reveals distinct procurement cycles and clinical utility patterns across product architectures. Cycle-time variations between permanent implantables and temporary dressings directly influence inventory management and reimbursement negotiations for wound care providers.
Product Type:
Inventory velocity diverges sharply between acellular matrices with extended shelf stability and living cellular products requiring just-in-time logistics.
- Human Dermal Matrix:Acellular collagen scaffolds derived from cadaveric or engineered tissue provide structural support for dermal regeneration. Burn centers in Texas and Florida concentrate procurement around established suppliers with validated cold chain protocols. FDA donor screening requirements extend lead times but secure premium reimbursement through durable clinical outcomes.
- Composite Grafts:Integrated bilayer constructs combining dermal scaffold with epidermal cellular components enable single-procedure full-thickness wound closure. Ambulatory surgical centers in Germany are adopting these systems fastest as operative efficiency demands intensify. PMDA's conditional approval framework in Japan accelerates commercialization timelines for qualified sponsors.
- Epidermal Replacement:Cultured autologous keratinocyte sheets deliver functional barrier restoration for superficial defects.
- Biological Dressings:Temporary coverage materials derived from amniotic or placental tissue facilitate moist wound healing environments.
Human Dermal Matrix anchors the volume base while Composite Grafts gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates capital-intensive surgical implantation from lower-acuity outpatient administration pathways.
- Surgical Application:Operating room deployment of permanent biological substitutes demands specialized instrumentation and sterile field protocols. Academic medical centers in the United States maintain the highest procedural volumes for complex defect reconstruction. Reimbursement through surgical DRG codes sustains margin structures despite lengthy sterilization and preparation workflows.
- Outpatient Procedures:Ambulatory settings enable same-day biological dressing application for chronic wound management. France and Germany are expanding procedural authorization for cellular therapies outside hospital settings. EMA's Advanced Therapy Medicinal Products pathway reduces regulatory friction for novel outpatient platforms.
- In-Hospital Treatments:Wound care unit administration of biological substitutes occurs under continuous monitoring protocols.
- Home Care Solutions:Patient or caregiver application of biological dressings extends treatment continuity beyond clinical encounters.
Surgical Application dominates revenue concentration while Outpatient Procedures expand most quickly across European markets.
End User:
Customer type segmentation maps directly to case complexity and reimbursement tier access.
- Burn Centers:Specialized facilities manage the highest-acuity full-thickness wound cases with multimodal biological substitute protocols. The United States maintains the densest network of verified burn centers with consolidated procurement relationships. Aging population demographics are accelerating facility investments and procedural volume expansion.
- Hospitals:General acute care settings handle diverse wound etiologies through standardized formulary protocols. Integrated delivery networks in Texas and Florida are rationalizing vendor contracts around suppliers offering both biological and synthetic portfolios.
- Clinics:Outpatient wound care centers focus on chronic ulcer management with biological dressing applications.
- Research Institutions:Academic centers drive clinical trial execution and novel product validation.
Hospitals anchor the volume base while Burn Centers gain share at the steepest rate.
Material:
Supply concentration for raw biomaterials determines geographic manufacturing footprint and cost variability.
- Collagen:Bovine, porcine, and recombinant collagen sources constitute the foundational scaffold material for dermal substitutes. Tissue processing technician scarcity at qualified recovery organizations creates procurement bottlenecks in the United States. Advanced decellularization techniques are expanding donor tissue yield and improving matrix consistency.
- Hyaluronic Acid:Glycosaminoglycan components modulate inflammatory response and support cellular migration during wound healing. Cross-linked formulations extend residence time in proteolytic wound environments.
- Chitosan:Polysaccharide derived from crustacean shells offers antimicrobial properties and hemostatic functionality.
- Fibrin:Autologous or allogeneic blood-derived matrices provide adhesive and growth factor delivery capabilities.
- Others:Emerging biomaterials including silk fibroin and decellularized extracellular matrix expand formulation options.
Collagen anchors the volume base while Hyaluronic Acid formulations climb the fastest in chronic wound applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in the United States, where mature reimbursement pathways for advanced wound care sustain premium positioning, while European markets face compressed margins under divergent health technology assessment regimes.
United States
Burn centers in Texas and Florida drive procedural volume expansion as aging demographics elevate chronic wound prevalence. FDA's Human Cells, Tissues, and Cellular and Tissue-Based Products framework elevates clinical evidence thresholds for new biological skin substitute approvals. Hospital procurement committees in integrated delivery networks are consolidating vendor relationships around suppliers offering diversified biological and synthetic portfolios.
Germany
Ambulatory surgical centers are expanding procedural authorization for cellular therapies outside traditional hospital settings. EMA's Advanced Therapy Medicinal Products pathway reduces regulatory friction for novel outpatient platforms. The Eindhoven-to-Munich corridor hosts concentrated tissue processing capabilities serving central European wound care demand.
Japan
PMDA's conditional approval framework for tissue-engineered products accelerates commercialization timelines for qualified sponsors. METI coordinates regenerative medicine fast-track initiatives with national health insurance pricing negotiations. The Kanto region around Tokyo anchors domestic manufacturing of decellularized extracellular matrix scaffolds.
United Kingdom
NICE evidence requirements for premium reimbursement increasingly determine which biological platforms achieve sustainable adoption beyond initial clinical enthusiasm. MHRA post-Brexit regulatory autonomy enables tailored conformity assessment timelines for advanced therapy medicinal products. The Cambridge-Oxford-London triangle concentrates academic medical center trial execution for novel composite graft technologies.
France
HAS health technology assessment criteria create parallel evidence submission requirements distinct from Germany's IQWiG and England's NICE frameworks. ANSM inspection protocols align with EU Medical Device Regulation recast classification rules for dermal substitutes containing viable cells. The Paris-Saclay cluster hosts specialized aseptic decellularization facilities serving southern European markets.
Biological Skin Substitutes Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying scaffold materials and cellular components to finished product assemblers. Market structure exhibits moderate consolidation around integrated wound care companies with diversified biological and synthetic portfolios, while single-product specialists face procurement rationalization pressure. Three archetypes dominate: placental tissue processors, living cell-based therapy developers, and diversified surgical portfolio suppliers. Competitive dynamics center on M&A activity targeting tissue recovery organization access and strategic partnerships securing ambulatory surgical center distribution channels.
Among United States-based platform integrators, Stryker Corporation and Integra LifeSciences Corporation occupy positions spanning surgical and chronic wound segments through diversified portfolio breadth. MIMEDX Group exemplifies the placental tissue processing archetype with concentrated expertise in decellularized matrix production. Smith & Nephew plc represents the multinational diversified supplier model competing across burn center and outpatient channels with integrated biological and synthetic offerings.
| Leading Market Players |
|---|
| Stryker Corporation |
| MIMEDX Group, Inc. |
| Organogenesis Inc. |
| Tissue Regenix |
| Vericel Corporation |
| Integra LifeSciences Corporation |
| 3M Company |
| Mölnlycke Health Care |
| Smith & Nephew plc |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoint exposure through FDA's Human Cells, Tissues, and Cellular and Tissue-Based Products framework determines both pricing tier spreads and supply chain shape. The framework elevates clinical evidence requirements for new approvals while compressing development timelines, forcing manufacturers to absorb compliance costs into premium tier positioning or exit to lower-margin synthetic alternatives.
Pricing Analysis
Burn center procurement committees anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on cellular viability status and FDA donor screening tier compliance, with living cellular products commanding substantial premiums over acellular matrices. Pricing pressure stems from synthetic matrix substitution as collagen engineering labs deliver lower-cost alternatives for partial-thickness coverage. Ambulatory surgical centers exhibit highest price sensitivity due to constrained reimbursement codes, while academic medical centers with surgical DRG pathways show least sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and tissue recovery organization networks dominates supply chain risk assessment. Manufacturing concentrates in the United States, Germany, and Japan, with the Eindhoven-to-Munich corridor anchoring European processing capabilities. Raw material dependencies center on cadaveric tissue donations, placental tissue collections, and recombinant collagen feedstocks. Single-source vulnerability persists as qualified tissue recovery organizations remain limited in number. Distribution runs through cold chain logistics networks requiring continuous temperature monitoring infrastructure to maintain viable cell populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated delivery networks as hospital procurement committees consolidate vendor relationships around diversified suppliers. This consolidation fragments negotiating leverage for single-product specialists while concentrating volume commitments for platform integrators.
For Market Incumbents: Insulate market position through backward integration into tissue recovery organization partnerships and captive supply of decellularized matrix materials. Secure ambulatory surgical center distribution channels before outpatient procedural authorization expands further. Invest in FDA dual-pathway submissions to preempt regulatory chokepoint exposure from evolving clinical evidence requirements. For New Entrants and Emerging Players: Mid-tier biologics firms seeking entry into advanced wound care represent the most penetrable white-space opportunity through asset-light licensing arrangements. Japan's regenerative medicine fast-track pathway offers accelerated commercialization timelines for qualified sponsors with novel composite graft technologies. Target Germany's expanding ambulatory surgical center network with EMA Advanced Therapy Medicinal Products pathway alignment as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with diversified biological and synthetic portfolios over component specialists. Long-term viability across the projection horizon rests on securing tissue recovery organization access and validated cold chain capabilities. Monitor health technology assessment divergence across NICE, IQWiG, and HAS frameworks as the signal for reimbursement-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Tissue Recovery Organization Partnership | Secures qualified donor tissue supply chains against procurement bottlenecks in the United States. |
| FDA Dual-Pathway Submission | Navigates evolving Human Cells, Tissues, and Cellular and Tissue-Based Products framework requirements efficiently. |
| Ambulatory Surgical Center Distribution Agreement | Captures outpatient procedural volume expansion in Germany and France outside hospital settings. |
| EMA Advanced Therapy Medicinal Products Alignment | Reduces regulatory friction for novel cellular therapies seeking European market access. |
| 3D Bioprinting Platform Development | Enables personalized graft geometries for complex defect reconstruction in burn centers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, hospital procurement databases, and GPO contracts. Primary interviews engaged burn center directors, tissue processing technicians, hospital purchasing committee members, and regulatory affairs specialists across the United States, Germany, and Japan. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement data, and national health technology assessment publications. Bottom-up demand modeling triangulated against top-down market sizing across product type, delivery mode, and end user segmentation.
Forecast inputs incorporate procedural volume trajectories, reimbursement pathway maturation, and regulatory approval timelines across the analysis window. Segmentation dimensions modeled include product architecture, delivery setting, customer type, and regional regulatory cluster. CAGRs derive from slope analysis of historical procedural growth correlated with demographic wound prevalence projections and facility investment cycles. Industry-specific inputs encompass burn center expansion rates and health technology assessment evidence threshold evolution.
Practitioners should monitor FDA guidance revisions, EMA inspection protocol alignment, and national payer evidence requirement shifts for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
India Skin Care Products Market
Skincare
Europe Functional Cosmetics Market
Skincare
Revitalizing Skin Wands Market
Skincare
Africa Cosmeceutical Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Retinol Skincare Product Market
Skincare
Peel Off Face Mask Market
Skincare
Facial Erythema Treatment Market
Skincare
Global Hand Lotion and Hand Cream Market
Skincare
Facial Mist Market
Skincare
Facial Skincare Market
Skincare
Body Scrub Market
Skincare
Tinted Sunscreen Market
Skincare
Anti-Aging Services Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Global Eczema Skin-Care Products Market