
 Retinol Skincare Product Market | 2026-2036
Retinol Skincare Product Market Size, Share, and Industry Trends Forecast 2026-2036
Retinol Skincare Product Market Insights
REACH compliance is rebalancing the cost-of-entry calculus for retinol formulators entering European distribution channels. L'Oréal Group leverages captive dermatological research infrastructure to sustain clinical credibility across its retinol portfolio. Estée Lauder Companies anchors premium positioning through controlled-release retinol technologies. Shiseido Company, Limited competes via fermentation-derived retinol alternatives that navigate Japan's strict quasi-drug classification requirements.
Retinol skincare products incorporate vitamin A derivatives—primarily retinol, retinaldehyde, and retinyl esters—at concentrations ranging from 0.25% to 1.0% in cosmetic formulations, with higher strengths classified as drugs in several jurisdictions. These compounds accelerate cellular turnover and stimulate collagen synthesis for anti-aging and acne-management applications. Serums command the highest margin pools due to concentrated actives and premium positioning, while creams retain volume leadership through accessibility and tolerance profiles. Water-based gel formulations are gaining fastest among younger consumers prioritizing lightweight textures compatible with layering routines.
The FDA governs retinol concentration thresholds separating cosmetics from drugs in the United States, while the EU's Scientific Committee on Consumer Safety periodically revises maximum permitted levels. China's NMPA requires animal-free safety substantiation for imported retinol products, reshaping formulation validation protocols for brands seeking mainland market access. Stakeholders must monitor evolving photostability mandates and retinoid pregnancy-labeling requirements across their priority geographies.
Market Dynamics
Tele-dermatology platforms are collapsing the prescription barrier for clinical-grade retinol, funneling demand toward higher-concentration formulations previously gatekept by dermatologist visits.
Growth Catalysts
- Tele-dermatology expansion:Virtual consultation platforms in the United States are streamlining access to prescription-strength retinol, converting cosmetic users to clinical protocols.
- EU Cosmetics Regulation updates:Tighter stability-testing mandates for vitamin A derivatives are professionalizing formulation standards and advantaging R&D-capable manufacturers.
- Fermentation-derived alternatives:Biotechnology processes are producing retinol analogues that bypass traditional supply constraints from petrochemical feedstocks.
Market Restraints
- Photostability failures:Retinol degradation under light exposure necessitates expensive encapsulation technologies and opaque packaging, elevating unit economics.
- Raw material concentration:Three chemical suppliers control bulk retinol precursor production, creating vulnerability to input price volatility.
- Pregnancy labeling restrictions:FDA and EMA teratogenicity warnings limit addressable population and require costly segmentation of distribution channels.
Strategic Opportunities
- Men's grooming penetration:Male-identifying consumers remain underindexed in retinol adoption, presenting white space for gender-neutral positioning and simplified routines.
- Water-based gel formats:Lightweight textures compatible with Korean-inspired skincare layering are capturing younger demographics previously alienated by heavy cream vehicles.
- China NMPA pathway:Animal-free safety substantiation requirements, once satisfied, unlock access to the world's second-largest skincare market with limited incumbent competition.
Industry Challenges
- Formulation chemist scarcity:Expertise in retinoid stabilization and irritation mitigation is concentrated among a small cohort of cosmetic scientists, constraining R&D velocity.
- Cross-border compliance complexity:Divergent cosmetic-drug thresholds between FDA, EMA, and NMPA force SKU proliferation and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinol Skincare Product Market |
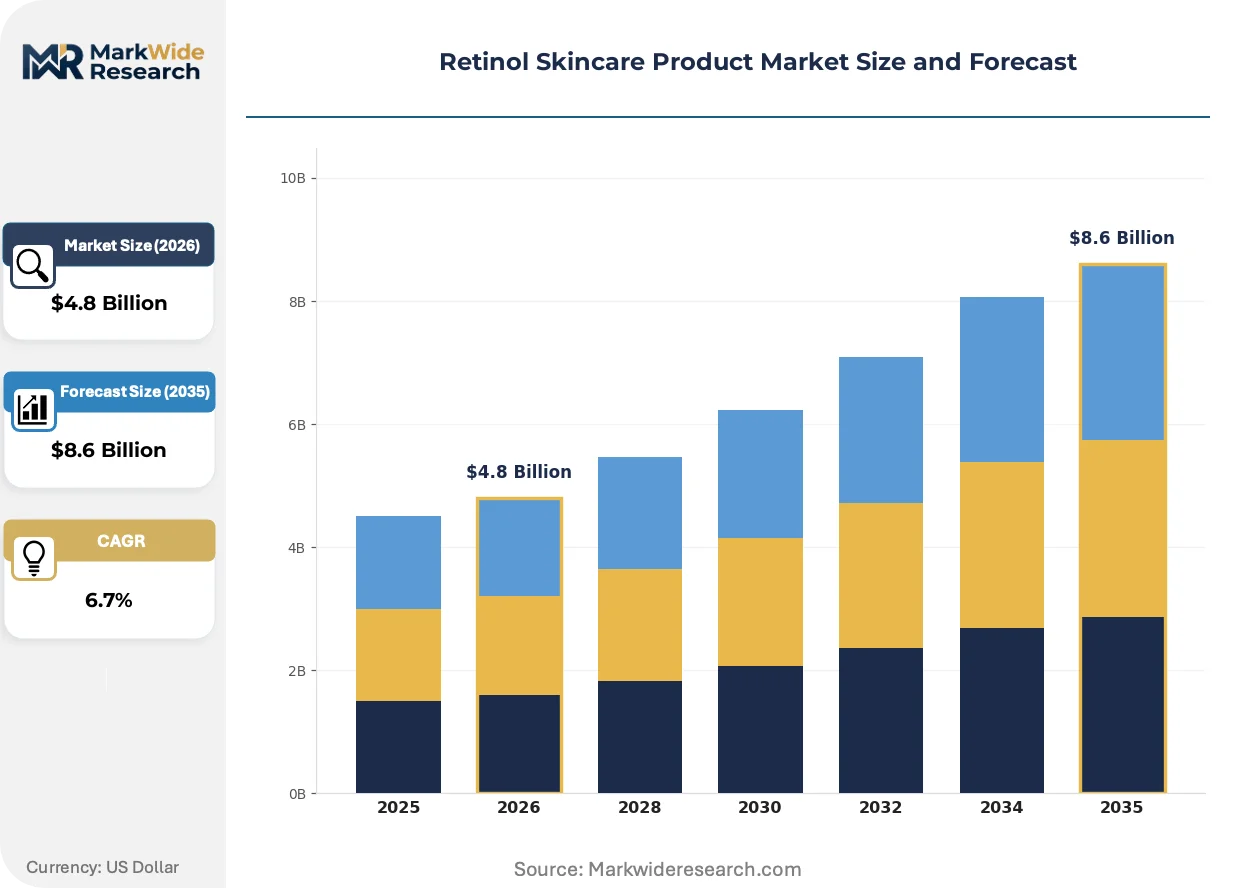
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Masks, Oils Formulation: Water-based, Oil-based, Gel-based, Emulsion Target Skin Type: Oily, Dry, Combination, Sensitive Application Method: Topical, Layering, Spot Treatment, Night Routine |
| Companies Covered | L'Oréal Group, Procter & Gamble, Unilever, Estée Lauder Companies, Johnson & Johnson, Beiersdorf AG, Shiseido Company, Limited, Amorepacific Corporation, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinol Skincare Product Market Trends and Innovations
Retinol delivery science is pivoting from concentration arms races toward tolerance engineering, with encapsulation and controlled-release architectures defining the next competitive frontier.
Microencapsulation technology is integrating retinol within lipid-shell matrices that degrade at skin temperature rather than upon light exposure. Premium serum manufacturers are adopting these systems to extend shelf stability without sacrificing bioavailability. This architecture is integrating clinical efficacy claims into mass-market price tiers, compressing the historical performance gap between professional and cosmetic channels.
REACH compliance deadlines are forcing European formulators to submit full safety dossiers for retinol concentrations above 0.3%. The regulatory burden is advantaging multinational groups with captive toxicology departments while marginalizing indie brands dependent on contract manufacturers. Germany and France are witnessing accelerated consolidation as smaller labels exit or sell to compliant parent entities.
Subscription-based replenishment models are displacing traditional retail discovery for retinol users seeking consistent routines without photodegradation risk from store lighting. Direct-to-consumer clinical brands are capturing loyalty through algorithmic skin assessment tools that personalize concentration ramp schedules. This behavioral shift is most pronounced among millennial consumers in urban United States markets where dermatologist wait times exceed three weeks.
Retinol Skincare Product Market Segmentation
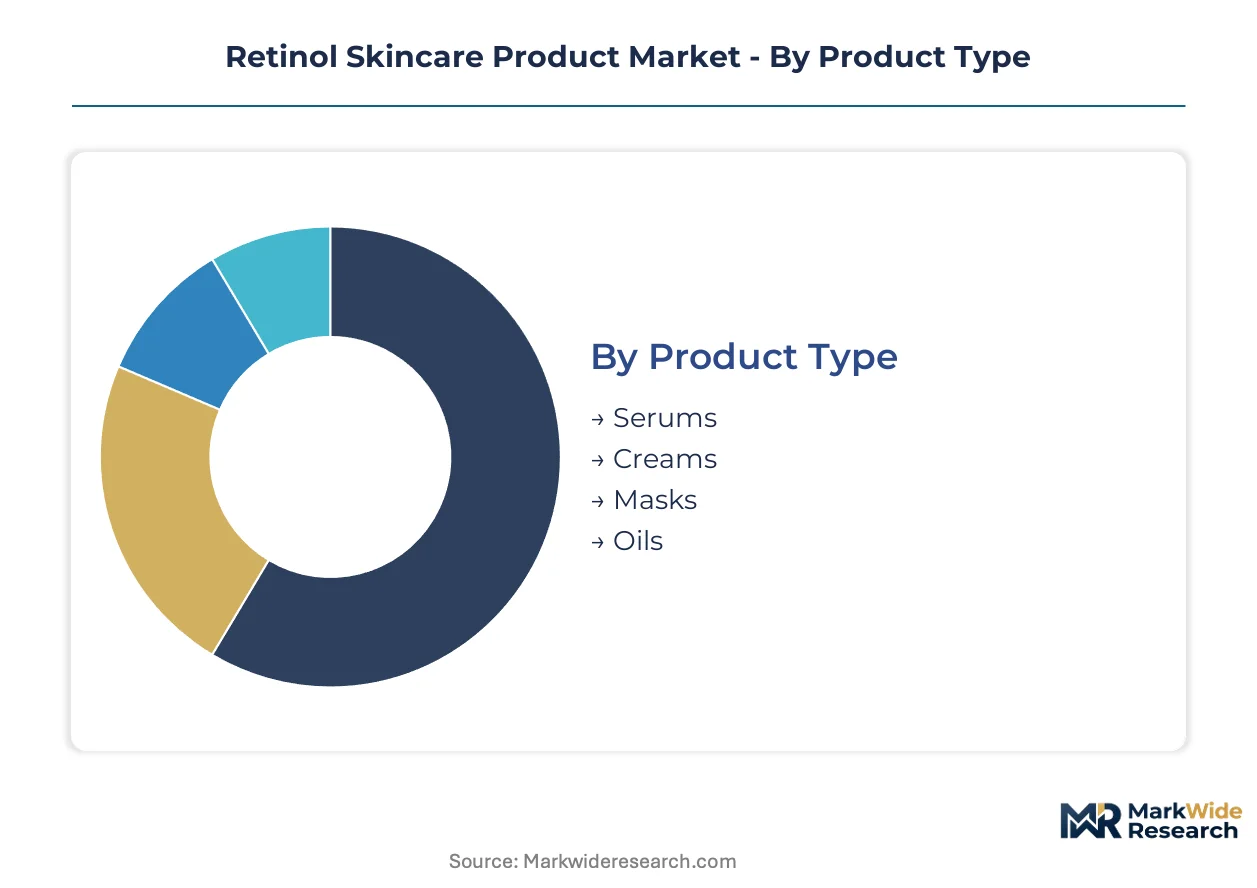
Retinol skincare segmentation reflects divergent capital requirements across formulation architectures and delivery systems. Product type and formulation choices dictate equipment investment, stability-testing expenditure, and regulatory compliance burden.
Product Type:
Capital intensity peaks in serum manufacturing due to cleanroom requirements and precision dosing infrastructure.
- Serums:Concentrated aqueous or anhydrous vehicles containing 0.3% to 1.0% retinol demand sophisticated encapsulation systems and cold-chain stabilization. United States direct-to-consumer brands are driving premium serum volume through subscription models that justify high per-unit production costs.
- Creams:Oil-in-water emulsions with 0.25% to 0.5% retinol leverage existing moisturizer manufacturing lines with lower barrier to entry. Mass-market retailers in Germany and France stock cream formats as entry-level clinical positioning vehicles.
- Masks:Rinse-off formats with brief retinol contact time require less photostability engineering than leave-on products.
- Oils:Anhydrous lipid vehicles simplify preservation challenges but limit compatibility with water-soluble active layering routines.
Serums absorb the bulk of installed capacity; water-based gel serums are expanding most quickly among millennial layering enthusiasts.
Formulation:
Water-based systems command the highest technical investment due to hydrolytic degradation risks and preservative complexity.
- Water-based:Lightweight gel and essence formats compatible with Korean-inspired multi-step routines. Younger consumers in urban United States markets prioritize these textures for morning-evening flexibility despite shorter shelf stability windows.
- Oil-based:Anhydrous carriers eliminate microbial contamination pathways and simplify preservation, suiting sensitive-skin positioning.
- Gel-based:Silicone or carbomer-thickened vehicles spread evenly with minimal residue, capturing male-identifying users new to retinol adoption.
- Emulsion:Dual-phase systems balance hydration with lipid delivery, dominating dermatology clinic professional protocols.
Emulsion formats retain the broadest manufacturing footprint; gel-based formulations are climbing the fastest as gender-neutral positioning expands.
Target Skin Type:
Formulation R&D spend concentrates on tolerance engineering for reactive skin profiles.
- Sensitive:Microencapsulated retinol and retinyl ester precursors require dedicated stability-testing protocols. European Union REACH compliance deadlines are forcing sensitive-skin specialists to submit full safety dossiers or exit the market.
- Oily:Non-comedogenic water-based gels address acne-management demand without exacerbating sebum production.
- Dry:Cream and oil vehicles with ceramide co-formulation target mature consumers seeking barrier repair alongside retinoid benefits.
- Combination:Zone-specific protocols and hybrid textures serve the largest addressable population with modular routine architecture.
Combination skin targeting captures the widest consumer base; sensitive-skin formulations are gaining share fastest as tolerance engineering differentiates premium positioning.
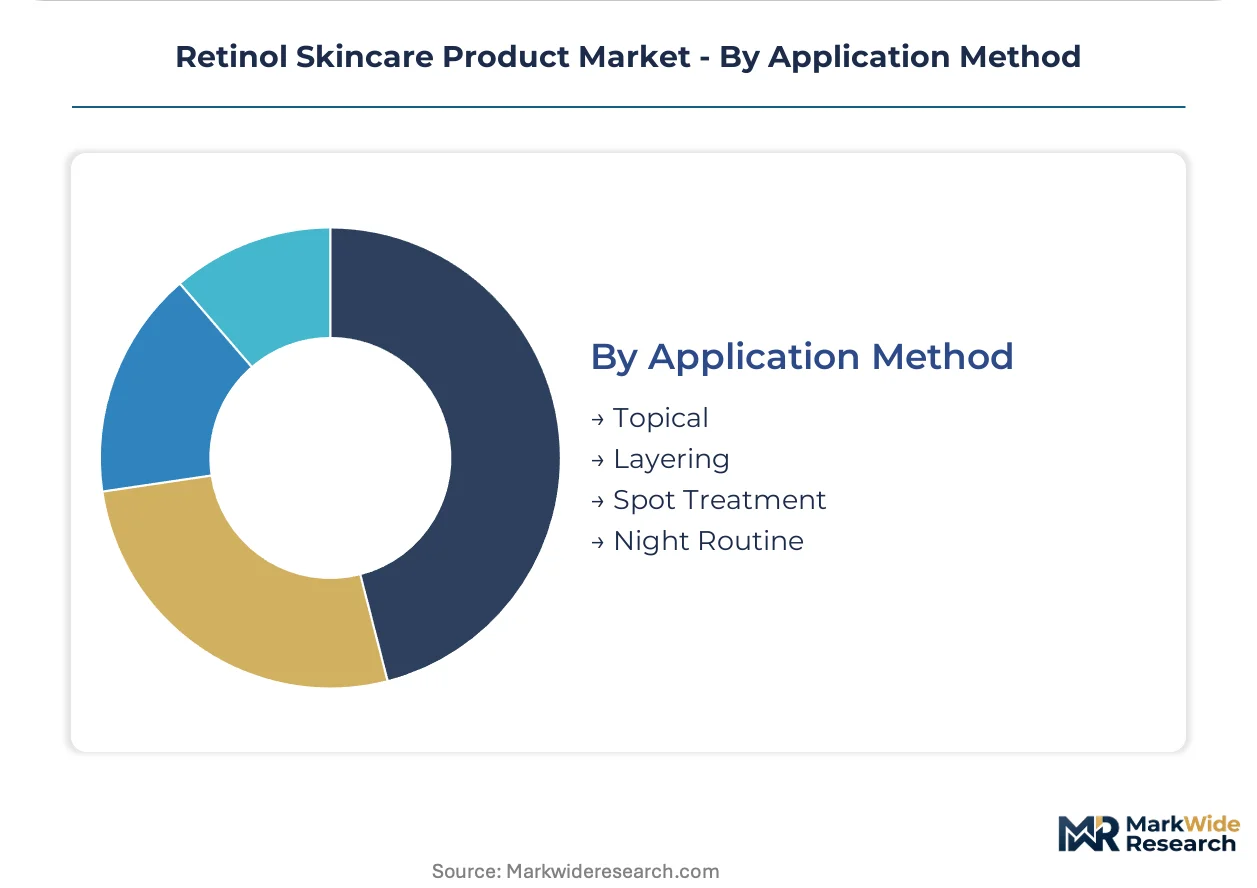
Application Method:
Packaging automation investment varies sharply by dosing precision and contamination control requirements.
- Night Routine:Photostability mandates relax for opaque, single-use sachets and airless pumps designed for evening-only application. United States tele-dermatology platforms prescribe night-concentrated protocols that simplify patient compliance.
- Layering:Fast-absorbing textures engineered for serum-stacking compatibility demand sophisticated rheology modification and pH buffering.
- Topical:Standard leave-on application dominates mass-market cream and serum formats with minimal behavior change required.
- Spot Treatment:High-concentration localized delivery systems require precision applicators and targeted stability testing for small-surface-area use.
Night Routine packaging commands the most specialized equipment; Layering-compatible formats are expanding most quickly among urban professional demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and Shanghai concentrate retinol formulation R&D investment for Asia-Pacific market access. These special-economic zones offer reduced tariff exposure for imported active ingredients and accelerated regulatory pre-approval pathways.
United States
Tele-dermatology platforms in California and New York are collapsing prescription barriers for clinical-grade retinol, converting cosmetic users to higher-concentration protocols. FDA concentration thresholds separating cosmetics from drugs shape formulation strategies for brands seeking over-the-counter distribution. Boston's biotech corridor hosts encapsulation technology specialists supplying microencapsulated retinol systems to direct-to-consumer brands.
Germany
REACH compliance deadlines are forcing retinol formulators to submit full safety dossiers for concentrations above 0.3%, professionalizing market entry standards. ECHA regulatory burden advantages multinational groups with captive toxicology departments over indie brands. Düsseldorf and Hamburg witness accelerated consolidation as smaller labels exit or sell to compliant parent entities.
China
NMPA animal-free safety substantiation requirements for imported retinol products are reshaping formulation validation protocols for brands seeking mainland market access. Shanghai's Pudong New Area hosts contract research organizations specializing in alternative toxicity testing for cosmetic actives. Domestic fermentation-derived retinol alternatives are gaining share as biotech startups bypass traditional petrochemical feedstock constraints.
Japan
Quasi-drug classification requirements for retinol concentrations above specified thresholds drive demand for fermentation-derived alternatives that navigate regulatory complexity. METI industrial policy supports biotechnology investment in novel vitamin A derivatives. Osaka-Kobe manufacturing corridor concentrates precision encapsulation capacity for sensitive-skin positioning products.
South Korea
K-beauty layering routines prioritize water-based gel retinol formats compatible with multi-step skincare architectures. MFDS regulates retinol as a functional cosmetic ingredient with specific concentration notification requirements. Seoul's Gangnam district anchors premium dermatology clinic chains prescribing professional-grade retinol protocols to affluent consumers.
Retinol Skincare Product Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across concentration tiers and distribution channels. The market exhibits moderate consolidation, with multinational beauty groups commanding premium positioning through captive dermatological research infrastructure while indie brands capture niche tolerance-engineering segments. Three strategic archetypes dominate: conglomerate beauty houses with clinical credibility platforms, biotechnology specialists in fermentation-derived alternatives, and direct-to-consumer disruptors leveraging subscription-based replenishment models. Competitive intensity centers on encapsulation technology licensing and geographic regulatory compliance capabilities.
Within the conglomerate tier, L'Oréal Group and Estée Lauder Companies exemplify scale-driven players leveraging dermatological research credibility across retinol portfolios. Shiseido Company, Limited occupies a distinct position among Asia-Pacific headquartered groups navigating Japan's quasi-drug classification through fermentation-derived alternative investments. Johnson & Johnson represents the healthcare-origin archetype bridging pharmaceutical and cosmetic channel expertise.
| Leading Market Players |
|---|
| L'Oréal Group |
| Procter & Gamble |
| Unilever |
| Estée Lauder Companies |
| Johnson & Johnson |
| Beiersdorf AG |
| Shiseido Company, Limited |
| Amorepacific Corporation |
| Kao Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH compliance deadlines for vitamin A derivatives above 0.3% concentration gate qualified supply access and premium-tier pricing power across European distribution channels. ECHA regulatory burden advantages R&D-capable manufacturers while marginalizing indie brands dependent on contract manufacturers, compressing mid-tier pricing flexibility.
Pricing Analysis
Short lead-time premiums for microencapsulated retinol systems command pricing separation from spot inventory of conventional unprotected actives. Three-tier pricing structure across premium, standard, and economy levels stratifies by encapsulation sophistication and stability-testing documentation depth. Cost compression in mass-market cream tiers intensifies as private-label entrants replicate basic retinyl ester formulations. Subscription-based direct-to-consumer brands exhibit lowest price sensitivity due to algorithmic personalization justifying sustained per-unit premiums.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for temperature-sensitive retinol shipments requiring cold-chain integrity. Bulk retinol precursor production concentrates in China, Switzerland, and Japan, drawing from petrochemical and fermentation-derived feedstocks. Single-source vulnerability pervades microencapsulation lipid-shell matrix supply, with three specialty chemical houses controlling proprietary degradation-temperature formulations. Distribution runs through dermatology clinic wholesalers in Germany, tele-dermatology fulfillment centers in California, and cross-border e-commerce platforms serving South Korean layering enthusiasts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retinol skincare represents a vertical-integration race where captive encapsulation technology and toxicology departments determine market access. Players are pursuing upstream control over fermentation-derived alternative production to bypass petrochemical feedstock constraints and regulatory concentration thresholds.
For Market Incumbents: Deepen captive dermatological research infrastructure to sustain clinical credibility against biotechnology specialist entrants. Secure backward integration into microencapsulation lipid-shell production to defend margin position from specialty chemical supplier price volatility. Prioritize REACH compliance certification for concentrations above 0.3% to consolidate European market share as smaller labels exit. For New Entrants and Emerging Players: Male-identifying consumers previously alienated by gendered skincare marketing represent the most penetrable buyer archetype for simplified gel-based routines. Water-based formats compatible with Korean-inspired layering capture fastest-expanding younger demographics in urban United States markets. Pursue direct-to-consumer algorithmic skin assessment tools to bypass traditional retail gatekeepers and establish subscription loyalty before incumbent platform replication. For Investors and Strategic Acquirers: Consolidation announcements from Düsseldorf and Hamburg indie brands selling to compliant parent entities is the leading indicator that REACH regulatory burden is concentrating market structure faster than organic growth permits. Five-to-ten year viability favors acquisition targets with captive toxicology departments and established NMPA animal-free safety substantiation pathways for China market access. Watch for fermentation-derived retinol alternative patent filings as signal of supply-chain-disruption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Microencapsulation partnerships with Boston biotech corridor specialists extend shelf stability without sacrificing bioavailability. |
| Direct-to-Consumer Platform Launch | Algorithmic skin assessment tools in California and New York collapse prescription barriers for clinical-grade protocols. |
| Fermentation-Derived Alternative Investment | Biotechnology processes in Osaka-Kobe corridor bypass petrochemical feedstock constraints and Japan quasi-drug complexity. |
| REACH Compliance Certification | Full safety dossier submission for concentrations above 0.3% professionalizes European market entry standards. |
| China NMPA Pathway Development | Animal-free safety substantiation through Shanghai Pudong contract research organizations unlocks world's second-largest skincare market. |
Research Methodology
Independent corroboration across formulation chemists, dermatology clinic procurement managers, tele-dermatology platform operators, and encapsulation technology specialists underwrites the qualitative findings. Primary interviews with R&D directors at multinational beauty houses and contract manufacturing executives supplemented secondary validation through FDA cosmetic-drug threshold guidance documents, ECHA REACH substance dossiers, NMPA import registration databases, and customs records for retinol precursor trade flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic absorption capacity estimates.
Rate-of-change decomposition across product type, formulation architecture, target skin type, and application method segments drove analytical framework construction over the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and substitution elasticity between retinol and retinaldehyde alternatives. Industry-specific forecast inputs incorporated photostability mandate evolution timelines and tele-dermatology platform penetration curves.
Revisions become necessary when REACH concentration thresholds shift, NMPA animal-testing requirements change, or fermentation-derived alternatives achieve cost parity with petrochemical retinol. Forecasts reflect documented assumptions regarding regulatory stability and consumer tolerance education effectiveness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Biocellulose Mask Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Skin Care Body Products Market
Skincare
Personalized Skin Care Products Market
Skincare
United Kingdom Skincare Market
Skincare
Encapsulated Retinol Market
Skincare
Revitalizing Skin Wands Market
Skincare
Dermal Regeneration Market
Skincare
Skin Care Supplements Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Cosmeceuticals Market
Skincare
Sheet Face Mask Market
Skincare
Incontinence Skin Care Products Market
Skincare
Moisturizing Cream Market
Skincare
Skin Replacement Market